
 Global MS Polymer Adhesives Market | 2026-2036
Global MS Polymer Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global MS Polymer Adhesives Market Foresight
A shortage of polymer chemists trained in silane-terminated formulations is unwinding capacity expansion plans at several manufacturers. Henkel AG leverages its European R&D footprint to sustain formulation leadership in hybrid polyurethane systems. Sika AG anchors its position through deep vertical integration into construction distribution channels. Arkema (Bostik) competes by specializing in acrylic modified grades for electronics bonding applications.
MS polymer adhesives are moisture-curing sealants based on silane-terminated polyether or polyurethane backbones, typically exhibiting tensile strengths of 2–6 MPa and Shore A hardness values between 25 and 55, designed primarily for elastic bonding and sealing in structural joints subject to dynamic movement. Silane terminated polymers dominate volume consumption in building and construction where elastic recovery requirements exceed 85%. Electronics bonding represents the fastest-expanding application segment driven by miniaturization and thermal management demands in handheld devices. Cartridge packaging controls the aftermarket channel while bulk drums occupy industrial OEM procurement.
REACH registration requirements in Europe, EPA VOC regulations in the United States, and GB standards administered by SAMR in China collectively elevate compliance costs for imported formulations. ECHA restrictions on isocyanate content are accelerating reformulation toward polyether-based systems with reduced hazard classifications. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized production or standardized global formulations offer superior risk-adjusted returns.
Market Dynamics
Construction sector procurement is pivoting from solvent-based bonding systems to silane-terminated formulations as builders face tightening VOC limits and elastic recovery mandates for structural joints.
Growth Catalysts
- EU Green Deal compliance deadlines:REACH registration requirements and ECHA restrictions on isocyanate content are accelerating reformulation toward polyether-based systems with reduced hazard classifications across European construction.
- Automotive lightweighting programs:OEMs in Germany, Japan, and the United States are specifying advanced bonding solutions for multi-material vehicle assemblies requiring dynamic movement tolerance.
- Electronics miniaturization:Thermal management demands in handheld devices are pulling acrylic-modified grades into high-density circuit bonding applications.
Market Restraints
- Specialized polymer chemist scarcity:Training pipelines for silane-terminated formulation expertise remain underdeveloped, unwinding capacity expansion timelines at multiple manufacturers.
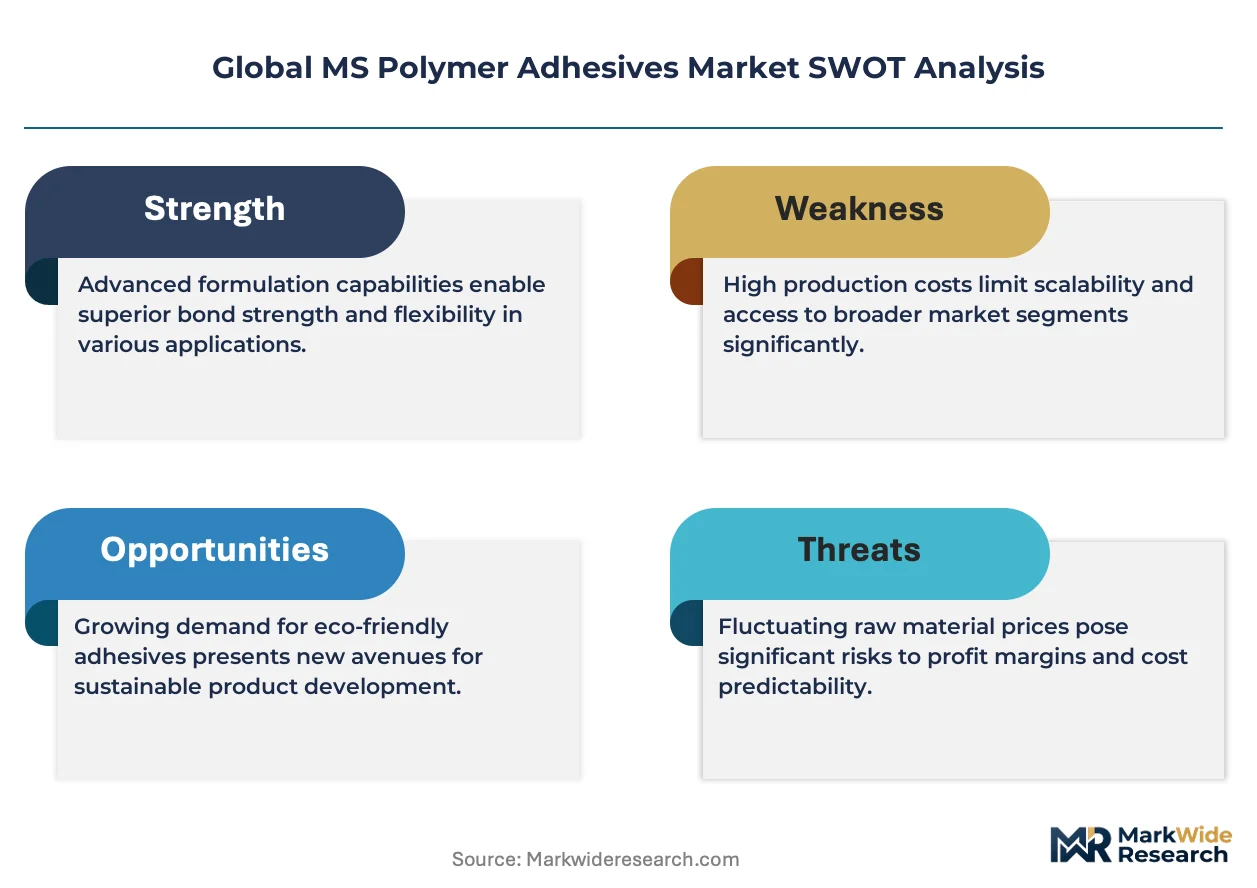
- Propylene oxide feedstock volatility:Polyether backbone production faces input cost swings that compress margin predictability for mid-tier formulators.
- Epoxy and polyurethane substitution:Lower-cost alternatives retain foothold in static-load applications where elastic recovery requirements fall below structural thresholds.
Strategic Opportunities
- India construction acceleration:BIS standards adoption for low-VOC sealants in commercial building creates first-mover positioning for compliant hybrid systems.
- Wind turbine blade bonding:Offshore wind installations require elastic joint sealants with 85%+ recovery under cyclic loading, opening specialized grade development.
- Bulk drum channel penetration:Industrial OEM procurement is consolidating around direct supply relationships that bypass cartridge aftermarket markups.
Industry Challenges
- Formulation talent pipeline gaps:University polymer programs emphasize commodity thermoplastics over silane-terminated chemistry, forcing manufacturers into captive training investments.
- Multi-jurisdiction compliance divergence:EPA VOC rules, REACH registrations, and SAMR-administered GB standards require parallel certification tracks that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MS Polymer Adhesives Market |
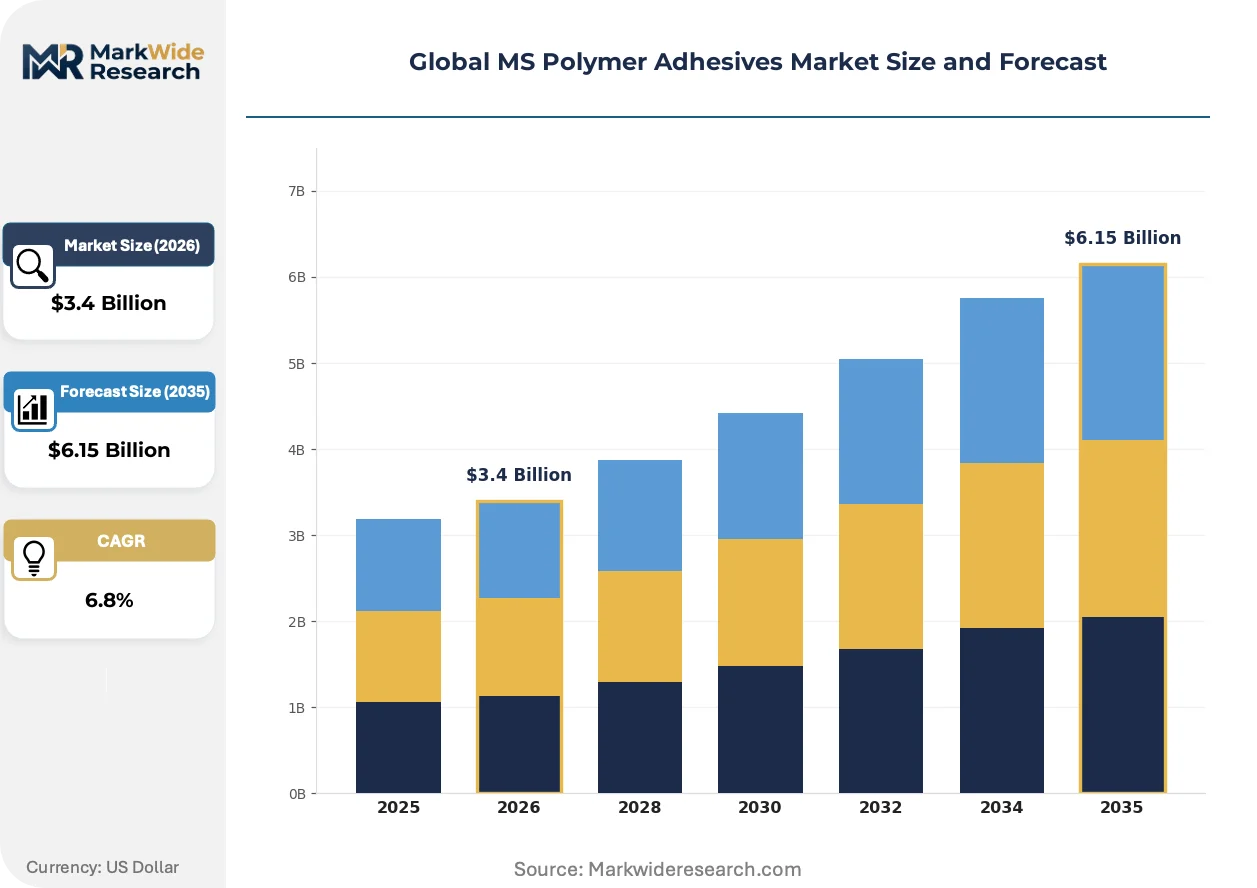
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silane Terminated Polymers, Hybrid Polyurethane, Silicone Modified, Polyether Based, Acrylic Modified Application: Building & Construction, Automotive Assembly, Electronics Bonding, Marine Sealants, Packaging Solutions End User Sector: Original Equipment Manufacturers, Aftermarket Suppliers, Electrical Assemblers, Ship Repair Yards, Consumer Goods Producers Packaging Format: Cartridge, Tube, Pail, Bulk Drum, Sachet |
| Companies Covered | Henkel AG, Sika AG, 3M Company, Arkema (Bostik), H.B. Fuller, Wacker Chemie AG, Tremco Illbruck GmbH & Co. KG, Mapei S.p.A, Soudal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MS Polymer Adhesives Market Shifts & Advancements
Silane-terminated chemistry is branching beyond construction into precision bonding applications where thermal cycling and miniaturization constraints dominate design specifications.
Thermally conductive MS polymer grades are miniaturizing into handheld electronics assembly where semiconductor packaging densities exceed traditional adhesive dissipation limits. Smartphone OEMs in South Korea and Taiwan are qualifying these formulations for 5G module attachment. The technology is miniaturizing bonding footprints while maintaining dielectric stability under repeated thermal shock.
REACH authorization procedures are tightening scrutiny of residual isocyanate content in polyurethane-based sealants, forcing reformulation toward pure polyether backbones. ECHA's 2023 restriction entry is compressing allowable hazard classifications for professional-grade products. German and French construction distributors are now prioritizing polyether-only inventory to preempt compliance discontinuities.
Specification authority is migrating from general contractors to facade engineering consultants who mandate certified elastic recovery data for structural glazing warranties. This shift is fragmenting procurement decisions across project phases rather than consolidating at bid award. The pattern is most pronounced in Japanese commercial tower construction where JIS standards enforcement has tightened post-2021 facade failures.
Global MS Polymer Adhesives Market Segmentation
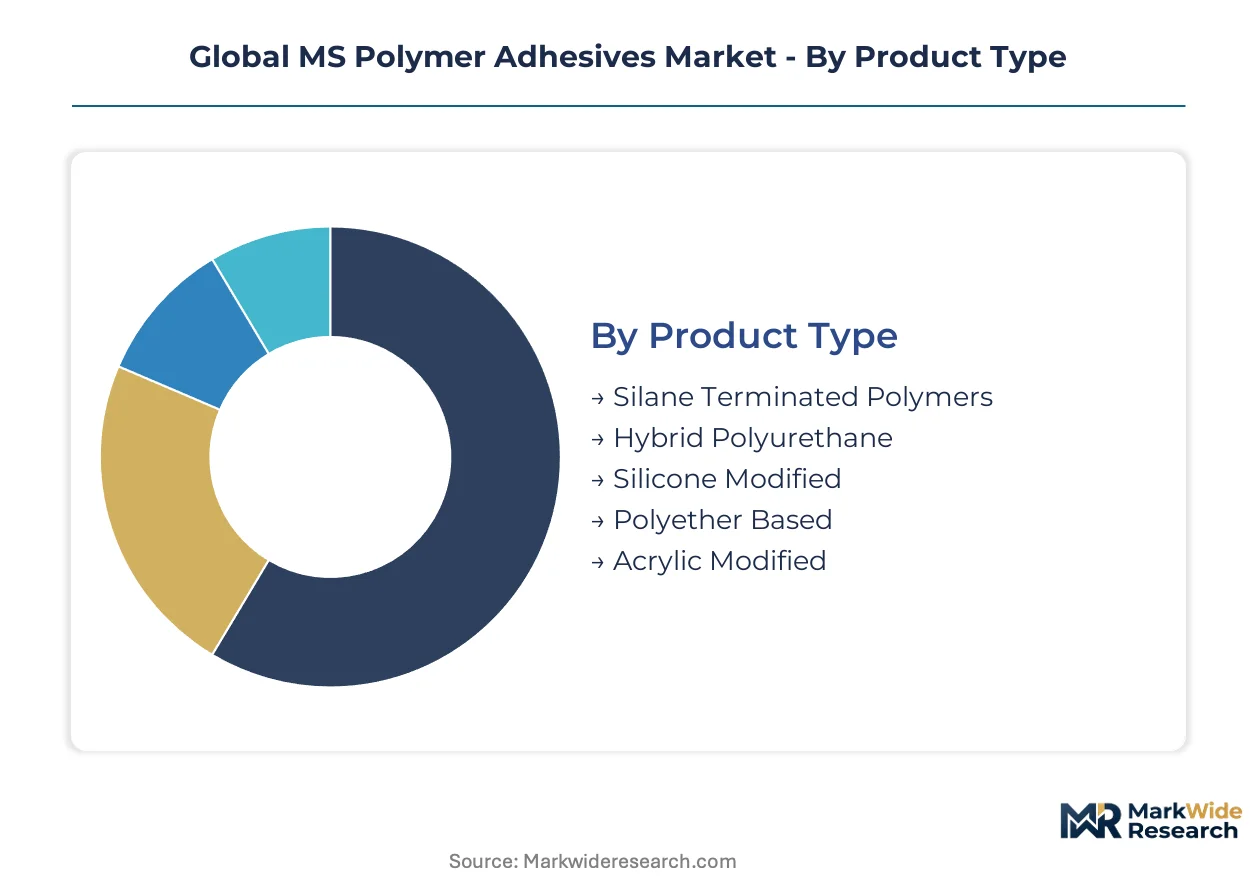
MS polymer adhesives fragment across formulation chemistry, application environment, procurement channel, and packaging scale. Each dimension carries distinct regulatory exposure and margin architecture that shapes supplier positioning.
Product Type:
REACH registration tiers and ECHA hazard classifications split formulation strategies between polyether-based systems and residual isocyanate-bearing alternatives.
- Silane Terminated Polymers:Pure polyether backbones with terminal silane crosslinking deliver elastic recovery above 85% for structural glazing joints. Demand concentrates in German and French commercial construction where facade engineering consultants now mandate certified recovery data for warranty coverage.
- Hybrid Polyurethane:Combines polyurethane backbone toughness with silane moisture-cure mechanisms, typically exhibiting tensile strengths of 4–6 MPa. Automotive OEMs in Japan specify these grades for multi-material vehicle assemblies requiring dynamic movement tolerance under lightweighting programs.
- Silicone Modified:Blends silicone segments for enhanced UV resistance in exterior exposure applications.
- Polyether Based:Reduced hazard classifications under ECHA restrictions are accelerating reformulation toward these systems across European professional-grade products.
- Acrylic Modified:Thermal conductivity variants are expanding into handheld electronics assembly where 5G module attachment requires dielectric stability under thermal shock.
Established volume favors Silane Terminated Polymers; emerging adoption favors Acrylic Modified grades.
Application:
End-use requirements for elastic recovery versus static load bearing determine specification authority and procurement channel.
- Building & Construction:Elastic bonding of structural joints subject to dynamic movement dominates volume consumption. JIS standards enforcement tightened in Japanese commercial tower construction following post-2021 facade failures, migrating specification authority from general contractors to facade engineering consultants.
- Electronics Bonding:Miniaturization and thermal management demands in semiconductor packaging are pulling specialized grades into high-density circuit applications. South Korean and Taiwanese smartphone OEMs are qualifying thermally conductive formulations for 5G module attachment.
- Automotive Assembly:Multi-material bonding for lightweighting programs requires movement tolerance across dissimilar substrates.
- Marine Sealants:Cyclic loading resistance under saltwater exposure drives offshore wind turbine blade bonding specifications.
- Packaging Solutions:Food-contact compliance requirements differentiate this segment from industrial sealing applications.
Construction maintains volume dominance; electronics climbing the fastest on miniaturization drivers.
End User Sector:
Procurement scale and technical specification authority fragment across OEM direct supply, aftermarket distribution, and specialized service channels.
- Original Equipment Manufacturers:Industrial OEM procurement is consolidating around bulk drum supply relationships that bypass cartridge aftermarket markups. Automotive and electronics manufacturers specify certified formulations for production line integration.
- Aftermarket Suppliers:Cartridge packaging controls this channel where distribution runs through construction supply houses and automotive parts retailers. Markup structures favor lower-volume, higher-margin specialty grades.
- Electrical Assemblers:Contract manufacturers serving consumer electronics brands require just-in-time delivery of thermally conductive grades.
- Ship Repair Yards:Offshore wind installations are opening specialized grade development for elastic joint sealants under cyclic loading.
- Consumer Goods Producers:Appliance and furniture assembly applications favor cost-optimized formulations with moderate elastic recovery requirements.
OEM direct procurement favors bulk formats; aftermarket channel stickiness sustains cartridge economics.
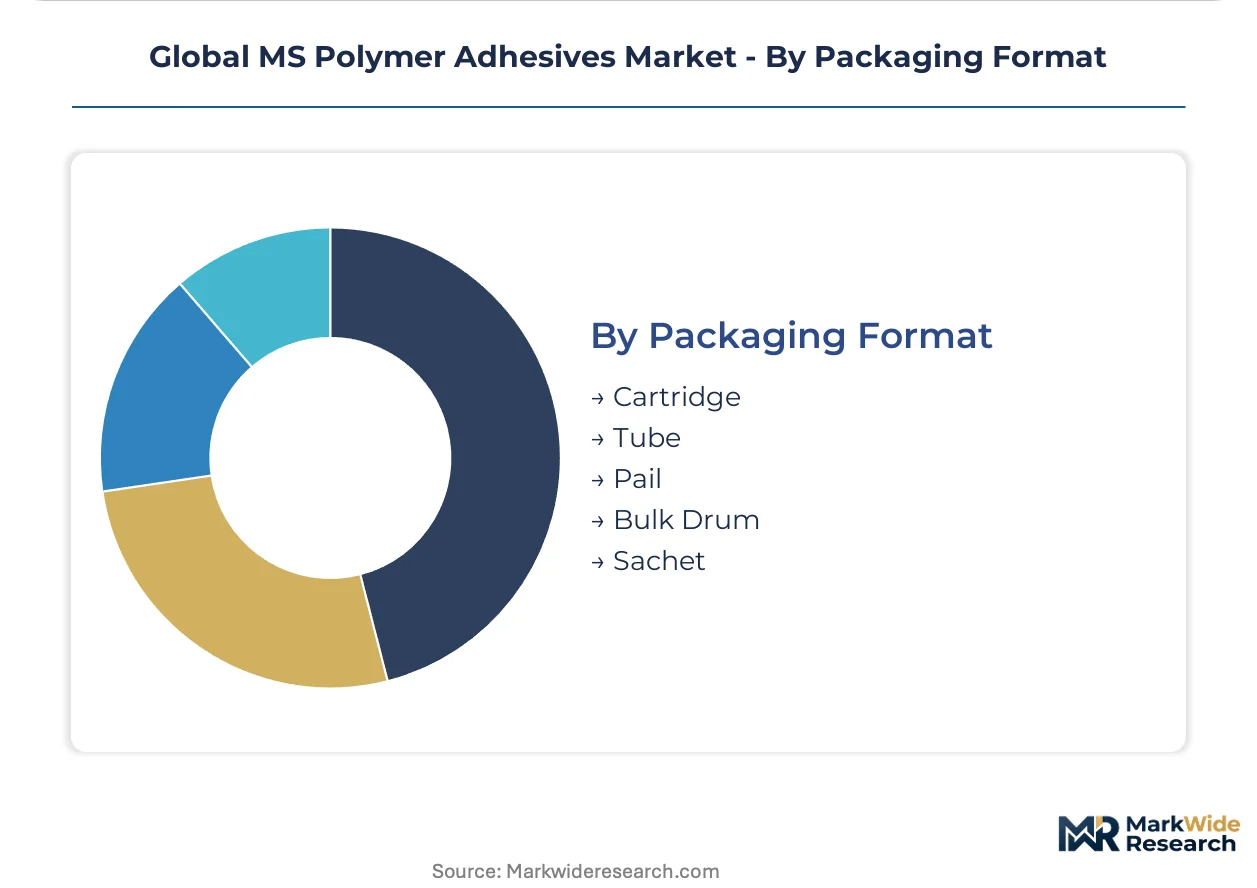
Packaging Format:
Volume scale and application method determine packaging selection, with regulatory labeling requirements varying by container size and professional versus consumer use designation.
- Bulk Drum:Industrial-scale supply for OEM production lines and construction projects with continuous consumption. EPA VOC regulations in the United States and REACH requirements in Europe impose parallel certification tracks that extend product launch timelines for imported formulations.
- Cartridge:Standard 300ml and 600ml formats dominate professional application in building and construction. SAMR-administered GB standards in China create compliance divergence from Western regulatory frameworks.
- Tube:Consumer retail formats for small-scale repair and DIY applications.
- Pail:Mid-volume supply for commercial contractors with recurring project demand.
- Sachet:Single-use pouches for field service applications and emergency repairs.
Bulk formats concentrate in OEM procurement; cartridges anchor professional construction distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA restrictions on isocyanate content anchor European compliance architecture, forcing reformulation timelines that ripple through construction supply chains in Germany, France, and adjacent markets. Regional demand concentrates where automotive lightweighting programs and facade engineering standards intersect with tightening chemical hazard classifications.
Germany
Automotive OEMs in Stuttgart and Munich specify hybrid polyurethane grades for multi-material vehicle assemblies under lightweighting mandates. REACH registration requirements and ECHA's 2023 isocyanate restrictions accelerate polyether-only inventory positioning by construction distributors. The Rhine-Ruhr industrial corridor concentrates formulation R&D investment for compliant sealant development.
United States
EPA VOC regulations compress allowable solvent content in structural glazing applications across commercial tower construction. Automotive assembly plants in Michigan and Tennessee procure bulk drum formats for production line integration of elastic bonding systems. The Southeast construction belt faces compliance divergence as state-level environmental rules supplement federal frameworks.
Japan
JIS standards enforcement tightened following post-2021 facade failures, migrating specification authority from general contractors to facade engineering consultants in Tokyo and Osaka commercial tower projects. Automotive manufacturers in Nagoya specify movement-tolerant grades for dissimilar substrate bonding. Kanto region electronics assemblers qualify thermally conductive formulations for 5G module attachment.
China
SAMR-administered GB standards for low-VOC sealants create compliance divergence from Western regulatory frameworks in commercial building procurement. Electronics contract manufacturers in Shenzhen and Dongguan drive qualification of acrylic-modified grades for high-density circuit applications. Yangtze River Delta construction acceleration pulls compliant hybrid systems into infrastructure expansion.
India
BIS standards adoption for low-VOC sealants in commercial building creates first-mover positioning opportunities for compliant hybrid systems. Wind turbine blade bonding specifications for offshore installations emerge from Gujarat and Tamil Nadu manufacturing clusters. Mumbai and Delhi-NCR facade engineering consultancies increasingly specify certified elastic recovery data for structural warranties.
Global MS Polymer Adhesives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with formulation specialists commanding premium positioning in regulated European markets while scale-driven manufacturers compete on bulk supply economics. The vendor base concentrates around three strategic archetypes: integrated chemical conglomerates with captive polymer supply, construction-focused specialists with distribution channel control, and electronics-oriented formulators with thermal management expertise. Competitive moves center on backward integration into polyether backbone production and geographic expansion through localized certification investments.
Among European-based integrated chemical conglomerates, Henkel AG and Sika AG exemplify archetype differentiation through distinct strategic positioning. Henkel AG occupies a position representing formulation leadership in hybrid systems, while Sika AG anchors the construction channel control archetype through distribution infrastructure. Arkema (Bostik) sits within the specialization tier for modified grades targeting electronics applications. These three entities collectively illustrate how regulatory compliance capabilities and application-specific expertise fragment competitive positioning across end-use segments.
| Leading Market Players |
|---|
| Henkel AG |
| Sika AG |
| 3M Company |
| Arkema (Bostik) |
| H.B. Fuller |
| Wacker Chemie AG |
| Tremco Illbruck GmbH & Co. KG |
| Mapei S.p.A |
| Soudal Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between polyether backbone producers and European formulators lock in both feedstock access and margin visibility against propylene oxide volatility. These arrangements concentrate pricing power with integrated chemical conglomerates while compressing margin predictability for mid-tier compounders dependent on spot market procurement.
Pricing Analysis
German construction distributors command 15-20% premiums over Southeast Asian spot markets for REACH-compliant polyether grades. Three-tier pricing structure across premium, standard, and economy levels separates certified elastic recovery formulations from uncertified alternatives and commodity hybrid systems. Price differentiation hinges on ECHA hazard classification tiers and volume scale commitments. Pricing pressure stems from epoxy substitution in static-load applications where elastic recovery requirements fall below structural thresholds. Aftermarket cartridge buyers exhibit highest price sensitivity; OEM bulk procurement shows lowest sensitivity due to certification lock-in effects.
Supply Chain Analysis
Inventory cycles for silane-terminated polyether extend 8-12 weeks due to moisture-sensitive packaging requirements and batch certification protocols. Manufacturing concentrates in Germany, China, and Japan where polyether backbone production anchors formulation economics. Raw material dependencies center on propylene oxide, specialty silane crosslinkers, and catalyst packages sourced from petrochemical complexes. Single-source vulnerability runs through German chemical conglomerates controlling silane crosslinker patents. Distribution runs through construction supply houses for cartridge formats and direct bulk drum relationships for automotive and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global MS Polymer Adhesives Market tracks construction investment cycles, with recovery momentum tied to European commercial building permits and Asian infrastructure stimulus deployment.
For Market Incumbents: Compound formulation leadership in hybrid polyurethane systems through captive R&D investments in silane-terminated chemistry expertise. Defend against epoxy substitution threats by certifying elastic recovery data for structural glazing warranties. Prioritize backward integration into polyether backbone production to secure margin control against propylene oxide volatility. For New Entrants and Emerging Players: Technical training services for silane-terminated application represent a service-layer gap where incumbents under-serve regional construction markets. Penetrate India's BIS standards transition for low-VOC sealants before compliance deadlines harden procurement requirements. Pursue wind turbine blade bonding specifications in Gujarat and Tamil Nadu manufacturing clusters through direct OEM qualification programs. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulators with established REACH registration portfolios and regional certification capabilities across multiple jurisdictions. Five-to-ten year viability favors players with demonstrated ECHA compliance navigation and polyether-only formulation pipelines. Monitor ECHA authorization timeline extensions as the inflection signal for competitive repositioning toward reduced hazard classification systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Production | Captive supply of backbone polymers insulates Henkel and Sika from propylene oxide volatility in German manufacturing. |
| REACH Registration Portfolio Expansion | ECHA compliance capabilities differentiate European incumbents from Asian competitors facing certification divergence. |
| Electronics Thermal Management Qualification | Acrylic-modified grade development opens 5G module attachment specifications with South Korean smartphone OEMs. |
| India BIS Standards Pre-Compliance Positioning | First-mover hybrid system certification captures commercial building procurement ahead of enforcement deadlines. |
| Wind Turbine Blade Bonding Grade Development | Offshore wind installations in Gujarat require elastic joint sealants with certified cyclic loading recovery above 85%. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical sector filings, ECHA registration databases, and national construction permit records. Primary interviews engaged formulation R&D directors at European chemical conglomerates, procurement leads at Japanese automotive OEMs, facade engineering consultants in German commercial tower projects, and distribution channel partners across Indian construction supply houses. Bottom-up volume estimates triangulate against top-down spending analysis across end-use segments.
Segmentation dimensions modeled span formulation chemistry, application environment, procurement channel, and packaging scale across the projection horizon. Grade tier splits separate pure polyether, hybrid polyurethane, and acrylic-modified systems. End-use industry segmentation captures building and construction, electronics bonding, automotive assembly, and emerging marine sealant applications. Regional production hub clustering reflects regulatory framework divergence between REACH, EPA, and SAMR jurisdictions. CAGRs derive from elasticity-adjusted demand curves incorporating substitution effects from epoxy and polyurethane alternatives.
Forecasts assume regulatory continuity in REACH authorization procedures, EPA VOC enforcement, and SAMR GB standards administration; material policy shifts would require re-modeling compliance cost assumptions. Specific risks include ECHA isocyanate restriction acceleration, propylene oxide supply disruptions, and construction sector demand contraction. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Wood Repair Epoxy Market