
 Global Bone Cement and Glue Market | 2026-2036
Global Bone Cement and Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Cement and Glue Market Foresight
Orthopedic polymer chemists is rotating toward antibiotic-loaded and dual-curing formulation expertise as hospitals demand infection-resistant fixation. Stryker Corporation leverages its vertically integrated biomaterials platform to control raw methyl methacrylate supply chains. Zimmer Biomet anchors its position through R&D intensity in patient-specific cement mixing systems. Smith & Nephew differentiates via bioactive glass cement portfolios targeting cranioplasty applications.
Bone cement and glue comprises polymer-based and ceramic-based biomaterials formulated for mechanical fixation and biological integration with skeletal tissue. Methyl methacrylate cement dominates volume due to its compressive strength exceeding 70 MPa and established track record in total joint arthroplasty. Calcium phosphate cement occupies the fastest-growing structural position as resorbable formulations gain traction in vertebroplasty and dental reconstruction. Antibiotic-loaded technology commands premium positioning where hospital-acquired infection protocols mandate prophylactic elution profiles.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access barriers for bone cement manufacturers. ISO 5833 standards for acrylic resin cements and ASTM F451 specifications define mechanical performance thresholds that differentiate commercial-grade from surgical-grade formulations. Stakeholders must monitor evolving antibiotic resistance patterns and corresponding regulatory guidance on prophylactic loading concentrations.
Market Dynamics
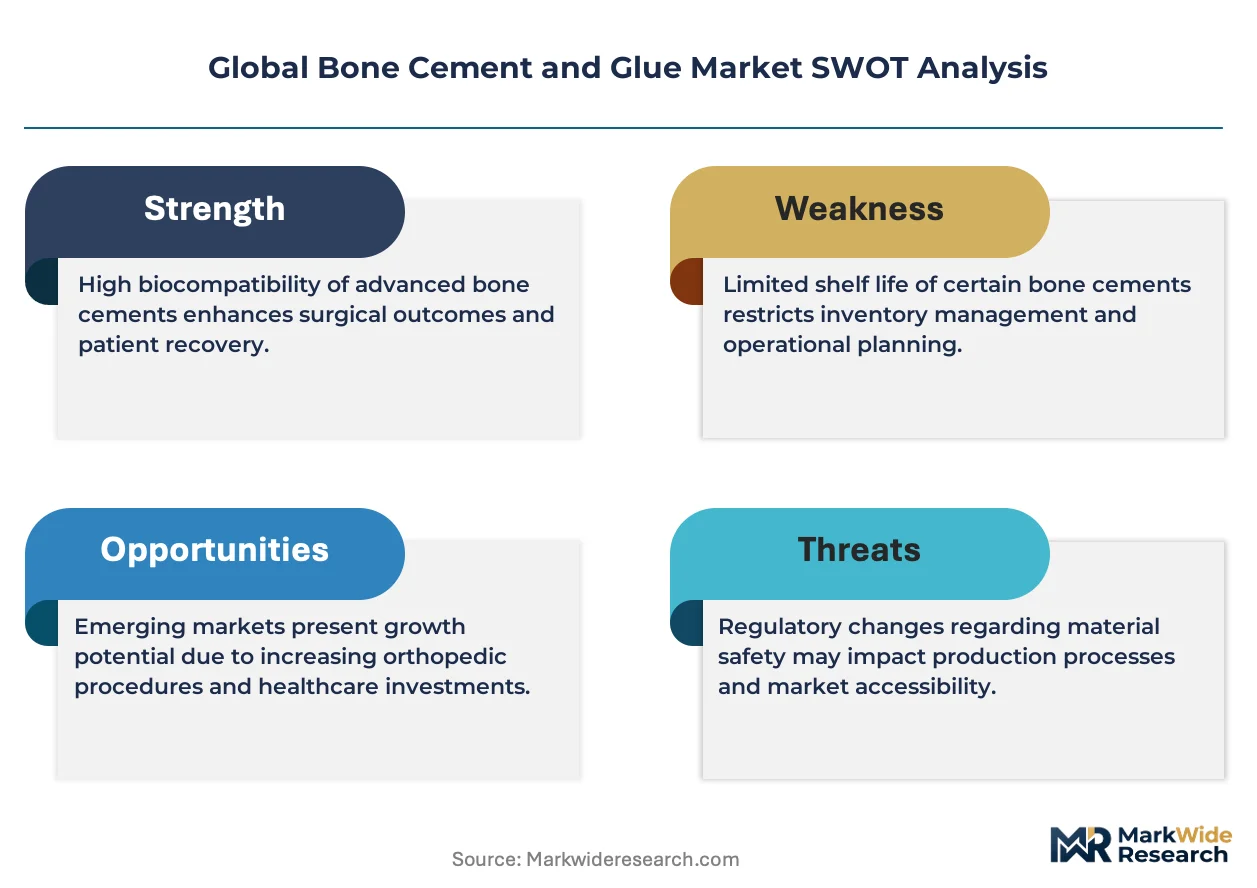
Antibiotic-loaded cement formulations are compressing product lifecycles as hospitals mandate infection-resistant fixation protocols. EU MDR biocompatibility testing requirements and FDA 510(k) clearance timelines now dictate R&D resource allocation across the supplier base.
Growth Catalysts
- EU MDR conformity pathways:Tighter biocompatibility standards are accelerating hospital procurement of certified antibiotic-eluting cements. German and French orthopedic centers now specify MDR-compliant formulations in tender documents.
- Vertebroplasty procedure volumes:Aging demographics in Japan and the United States are expanding calcium phosphate cement adoption for minimally invasive spinal stabilization. Resorbable formulations reduce revision surgery rates.
- Methyl methacrylate supply security:Captive production of surgical-grade monomer is insulating integrated manufacturers from petrochemical volatility. Raw material traceability now anchors procurement decisions.
Market Restraints
- Methyl methacrylate price volatility:Crude oil-linked feedstock costs create margin compression for non-integrated formulators. Acrylic resin cements face input cost instability.
- Antibiotic resistance surveillance:ECDC and CDC guidance on prophylactic loading concentrations is narrowing clinically acceptable elution profiles. Formulation flexibility is constrained.
- ISO 5833 certification timelines:Mechanical testing protocols for acrylic resin cements extend product development cycles. Small manufacturers lack capital for parallel regulatory submissions.
Strategic Opportunities
- Cranioplasty reconstruction:Bioactive glass cement portfolios are penetrating neurosurgical applications with osteoconductive properties. Smith & Nephew and specialized ceramic houses are targeting this white space.
- Patient-specific mixing systems:Automated cement preparation units are reducing operative variability in Japanese university hospitals. Zimmer Biomet's R&D intensity is compressing adoption timelines.
- India's CDSCO registration pathway:Streamlined medical device approvals are opening access to private hospital chains in Mumbai and Delhi. Domestic manufacturing partnerships reduce import duty exposure.
Industry Challenges
- Polymer chemist talent scarcity:Dual-curing and antibiotic-loaded formulation expertise concentrates in Basel, Warsaw, and Boston clusters. Compensation inflation is squeezing mid-tier R&D budgets.
- FDA 510(k) predicate device strategies:Substantial equivalence determinations for novel cement compositions require extensive mechanical testing data. Submission preparation consumes 18-24 month lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Cement and Glue Market |
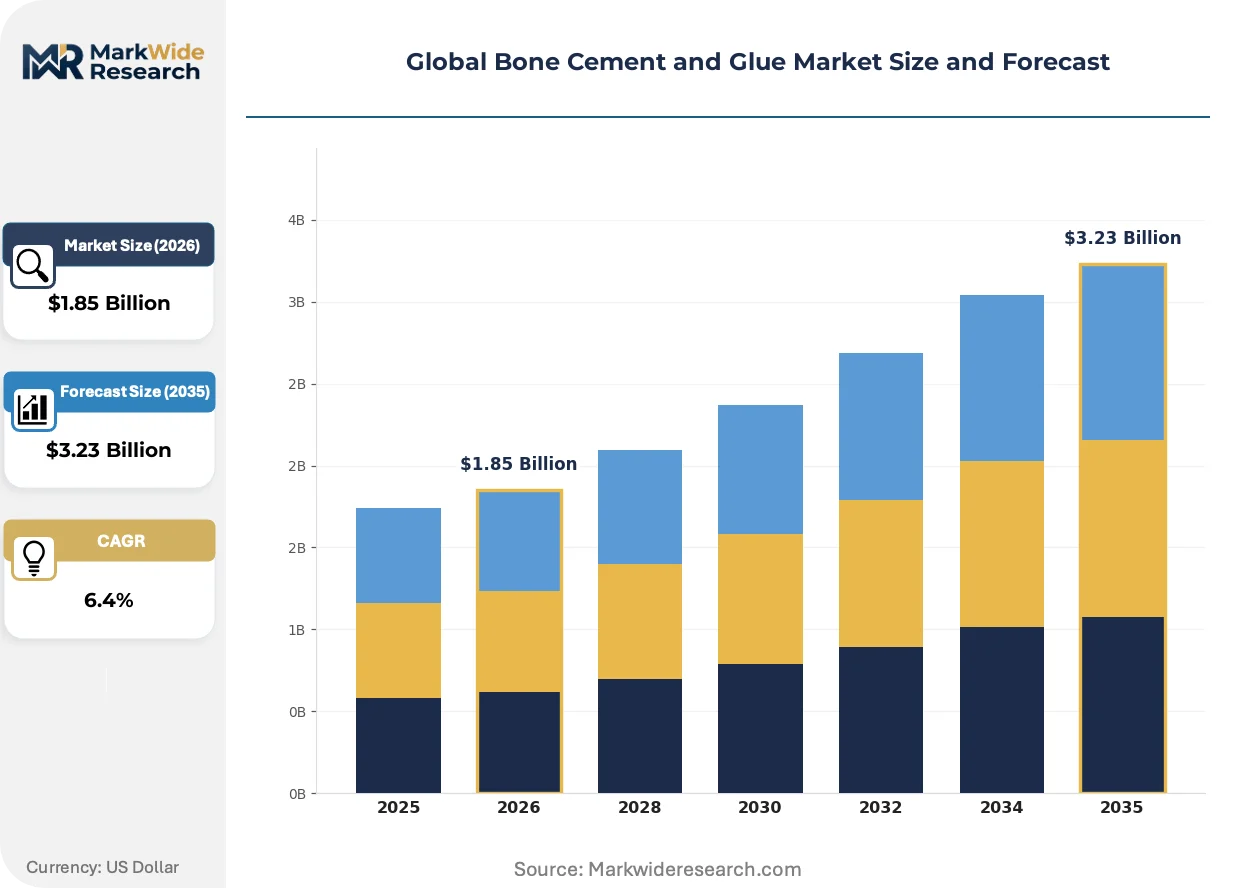
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Methacrylate Cement, Calcium Phosphate Cement, Bioactive Glass Cement, Epoxy Resin Adhesive, Polyurethane Adhesive Application: Orthopedic Surgery, Dental Reconstruction, Vertebroplasty, Cranioplasty, Arthroplasty End User: Hospitals, Orthopedic Clinics, Dental Clinics, Rehabilitation Centers, Surgical Centers Technology: Self-curing, Light-curing, Dual-curing, Radiopaque, Antibiotic-loaded |
| Companies Covered | Stryker Corporation, Zimmer Biomet, DePuy Synthes, Smith & Nephew, Arthrex, B. Braun Melsungen AG, Exactech, Globus Medical, Heraeus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Cement and Glue Market Shifts & Advancements
Digital surgical planning and automated mixing technologies are compressing operative variability while regulatory convergence around biocompatibility standards is homogenizing quality thresholds across major markets.
Smart cement delivery systems incorporating real-time viscosity sensing are miniaturizing operative workflow steps. Orthopedic surgery departments in German university hospitals are piloting these units to standardize cement preparation. The technology is miniaturizing the role of manual mixing technicians while reducing waste from discarded batches.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for acrylic resin cements. Notified bodies in Germany and the Netherlands are prioritizing antibiotic-loaded formulations with established clinical surveillance data. Manufacturers are responding by front-loading post-market clinical follow-up studies to accelerate renewal cycles.
Hospital procurement committees are consolidating supplier relationships around vertically integrated manufacturers with captive methyl methacrylate supply. Group purchasing organizations in the United States are awarding multi-year contracts to vendors with demonstrated raw material traceability. This concentration is most visible in the Midwest, where integrated delivery networks manage arthroplasty volumes exceeding ten thousand procedures annually.
Global Bone Cement and Glue Market Segmentation
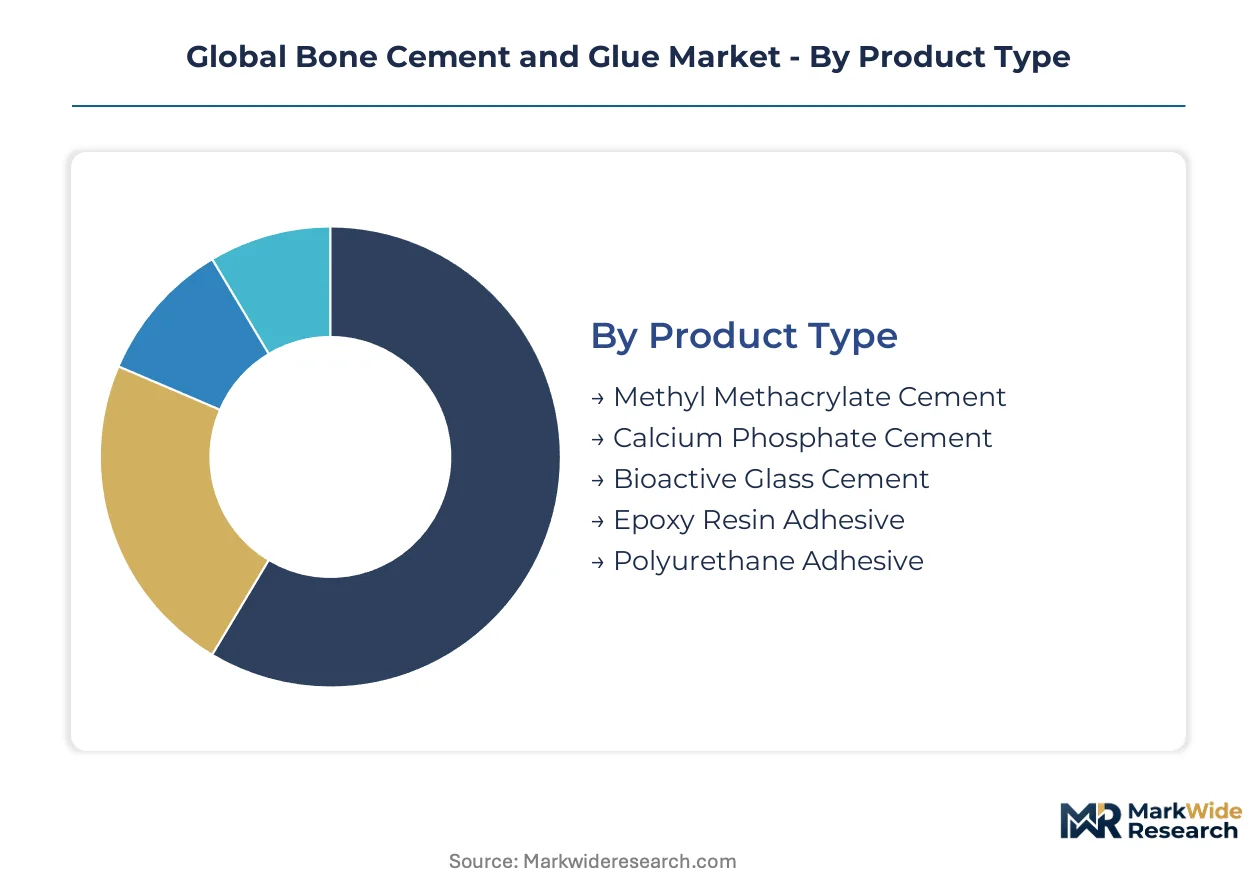
Segmentation in bone cement and glue markets reveals how formulation chemistry, procedural application, and procurement channel each create distinct margin architectures. Manufacturers configure R&D portfolios and regulatory submissions around these boundaries.
Product Type:
Methyl methacrylate formulations command the deepest margin pools due to raw material integration advantages and arthroplasty volume concentration.
- Methyl Methacrylate Cement:Acrylic resin formulation delivering compressive strength exceeding 70 MPa for load-bearing fixation. Demand concentrates in German and US orthopedic surgery departments where arthroplasty volumes exceed ten thousand procedures annually at integrated delivery networks.
- Calcium Phosphate Cement:Resorbable ceramic composition enabling biological integration without revision surgery. Japanese university hospitals and US spinal centers are adopting these formulations for vertebroplasty as aging demographics expand minimally invasive stabilization volumes.
- Bioactive Glass Cement:Silicate-based osteoconductive material targeting cranioplasty applications.
- Epoxy Resin Adhesive:High-bond-strength polymer system for structural skeletal fixation.
- Polyurethane Adhesive:Flexible elastomeric formulation for load-distributing applications.
Methyl methacrylate cement holds installed capacity. Calcium phosphate cement is rotating up the share rankings.
Application:
Procedure reimbursement intensity and revision risk profile determine where premium pricing sustains within this category.
- Orthopedic Surgery:Broad procedural category encompassing trauma fixation and reconstructive interventions. German and French orthopedic centers specify MDR-compliant antibiotic-eluting cements in tender documents, tightening supplier qualification requirements.
- Arthroplasty:Joint replacement procedures generating concentrated cement consumption per operation. US group purchasing organizations award multi-year contracts to vendors with demonstrated methyl methacrylate traceability, consolidating procurement relationships.
- Dental Reconstruction:Maxillofacial and implant fixation applications with distinct regulatory pathways.
- Vertebroplasty:Minimally invasive spinal stabilization driving resorbable formulation adoption.
- Cranioplasty:Neurosurgical reconstruction requiring osteoconductive properties and precise contouring.
Arthroplasty anchors volume concentration. Vertebroplasty is climbing the fastest as resorbable formulations reduce revision rates.
End User:
Capital equipment integration and sterilization protocol requirements create divergent procurement patterns across this category.
- Hospitals:Acute care institutions with centralized sterile processing and bulk purchasing leverage. Japanese university hospitals are piloting automated cement preparation units to standardize operative workflow and reduce batch waste.
- Orthopedic Clinics:Specialized ambulatory facilities with procedure-focused supply chains. These settings concentrate demand for patient-specific mixing systems as surgeons seek operative variability reduction.
- Dental Clinics:Outpatient oral surgery and implant practices with distinct material requirements.
- Rehabilitation Centers:Post-acute facilities with limited cement consumption profiles.
- Surgical Centers:Ambulatory settings prioritizing throughput and standardized protocols.
Hospitals hold procurement scale. Orthopedic clinics are gaining share fastest through specialized volume concentration.
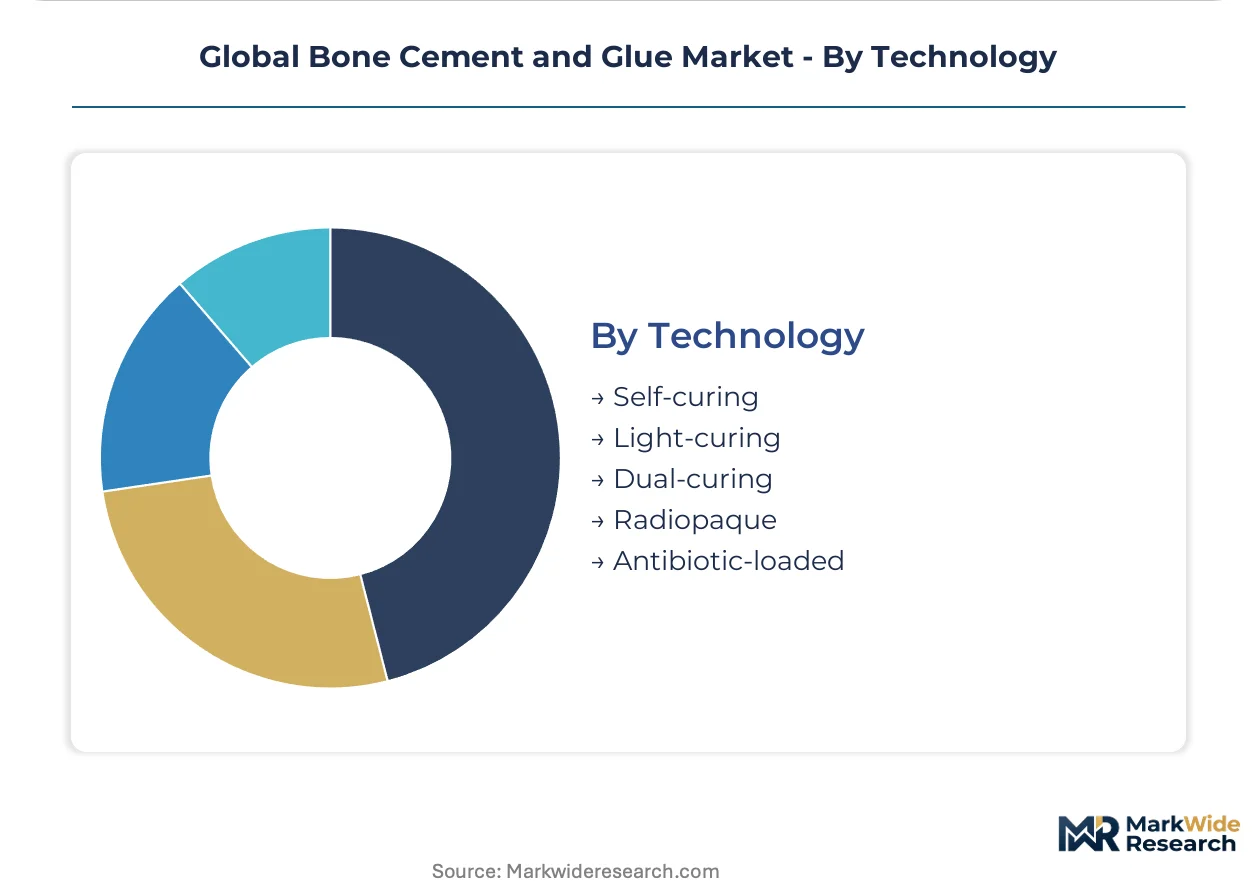
Technology:
Regulatory certification burden and formulation complexity stratify competitive positioning within this category.
- Antibiotic-loaded:Prophylactic elution formulations mandated by hospital-acquired infection protocols. ECDC and CDC guidance on loading concentrations is narrowing clinically acceptable profiles, constraining formulation flexibility for manufacturers.
- Dual-curing:Combined chemical and light-activated polymerization enabling controlled setting times. EU MDR biocompatibility testing requirements are extending conformity assessment timelines for these advanced compositions.
- Self-curing:Autonomous polymerization without external energy input.
- Light-curing:Photo-initiated setting for surface applications.
- Radiopaque:Contrast-enhanced visualization for post-operative imaging.
Antibiotic-loaded technology commands premium positioning. Dual-curing is expanding most quickly as hospitals demand infection-resistant fixation with operative control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance timelines and EU MDR conformity assessments anchor regulatory gravity in the United States and Germany, while Japan's PMDA and India's CDSCO shape procurement patterns across Asia-Pacific hospital networks.
United States
Group purchasing organizations in the Midwest consolidate arthroplasty procurement around vendors with methyl methacrylate traceability. FDA antibiotic resistance surveillance narrows clinically acceptable elution profiles for prophylactic formulations. The Greater Boston cluster concentrates dual-curing formulation expertise as orthopedic polymer chemists migrate toward infection-resistant fixation R&D.
Germany
Notified bodies in Berlin and Munich prioritize antibiotic-loaded cements with established post-market surveillance under EU MDR Article 10. German university hospitals specify MDR-compliant formulations in tender documents, tightening supplier qualification. The Basel-Warsaw-Boston corridor concentrates polymer chemist talent for advanced cement compositions.
Japan
Aging demographics expand vertebroplasty volumes at Tokyo and Osaka university hospitals, driving calcium phosphate cement adoption. METI guidelines on medical device quality management shape procurement standards for automated mixing systems. The Kansai region pilots smart cement delivery units with real-time viscosity sensing to standardize operative workflow.
India
CDSCO streamlined registration pathways open private hospital chains in Mumbai and Delhi to imported antibiotic-eluting formulations. Domestic manufacturing partnerships reduce import duty exposure for multinational cement suppliers. The Maharashtra-Gujarat corridor attracts toll manufacturing agreements for methyl methacrylate processing.
Switzerland
Swissmedic conformity assessments for orthopedic biomaterials emphasize mechanical testing data under ISO 5833 standards. The Basel cluster anchors European R&D intensity for bioactive glass cement targeting cranioplasty applications. Swiss university hospitals coordinate with German procurement networks for MDR-compliant antibiotic-loaded portfolios.
Global Bone Cement and Glue Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in bone cement supply. Vertically integrated manufacturers with captive methyl methacrylate production control raw material traceability and compress procurement cycles. Specialist ceramic houses and regional formulators occupy mid-tier positions with niche application focus. Competitive moves concentrate on backward integration into monomer supply and patient-specific mixing system development.
Among US-based orthopedic conglomerates, Stryker Corporation and Zimmer Biomet exemplify integrated archetypes with biomaterials platform control. Smith & Nephew represents the specialty-tier vector with bioactive glass cement positioning. German fabricator B. Braun Melsungen AG anchors European supply security through diversified medical device manufacturing scale.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| DePuy Synthes |
| Smith & Nephew |
| Arthrex |
| B. Braun Melsungen AG |
| Exactech |
| Globus Medical |
| Heraeus Medical |
| Others |
Supply & Pricing Matrix
Twenty-four month FDA 510(k) clearance timelines compress working capital cycles for non-integrated formulators, concentrating pricing power with manufacturers holding captive methyl methacrylate supply. This lead-time asymmetry stratifies procurement negotiations across German university hospitals and US group purchasing organizations.
Pricing Analysis
Transatlantic price spreads exceed thirty percent between US integrated delivery networks and Indian private hospital chains, reflecting tariff exposure and certification tier differentials. Three-tier pricing structure across premium antibiotic-loaded, standard acrylic resin, and economy unmodified formulations anchors contract negotiations. Pricing pressure stems from ECDC narrowing of clinically acceptable antibiotic elution profiles, forcing reformulation investments. Orthopedic clinics exhibit highest price sensitivity due to limited bulk purchasing leverage, while German university hospitals prioritize MDR compliance over unit cost.
Supply Chain Analysis
BASF Ludwigshafen monomer output and SABIC petrochemical feedstock streams constitute the primary chokepoint for surgical-grade methyl methacrylate availability. Manufacturing concentrates in Germany, the United States, and Japan, drawing from crude oil-linked acrylate precursors and pharmaceutical-grade stabilizer additives. Single-source vulnerability runs through European notified body certification capacity for EU MDR conformity assessments. Distribution runs through hospital group purchasing organizations in North America and centralized procurement consortia in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated cement mixing system service contracts and post-market clinical follow-up study management represent recurring revenue layers expanding faster than hardware sales. These attach opportunities transform transactional cement supply into multi-year hospital partnerships.
For Market Incumbents: Shield arthroplasty volume concentration through backward integration into pharmaceutical-grade monomer supply, insulating procurement cycles from petrochemical volatility. Fortify positions by acquiring dual-curing formulation talent in the Basel-Warsaw-Boston corridor before compensation inflation locks out mid-tier R&D budgets. Cement mixing system software subscriptions provide defensive moats against emerging automated preparation unit competitors. For New Entrants and Emerging Players: Automated viscosity sensing calibration services represent a service-layer gap where Stryker and Zimmer Biomet under-serve Japanese university hospital pilot programs. White-space targets include bioactive glass cement for cranioplasty applications in Swiss and German neurosurgical centers, plus CDSCO-registered antibiotic-eluting formulations for Mumbai and Delhi private hospital chains. Go-to-market leverage rests on domestic manufacturing partnerships that eliminate import duty exposure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with orthopedic biomaterials divisions lacking vertical integration into monomer supply. Five-to-ten year viability favors manufacturers with established EU MDR Article 10 technical documentation and FDA 510(k) predicate device libraries. Watch antibiotic resistance surveillance guidance from ECDC and CDC as the inflection signal for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive methyl methacrylate production insulates margins from crude oil volatility and secures raw material traceability for FDA submissions. |
| EU MDR Article 10 Technical Documentation | Front-loaded post-market clinical follow-up studies accelerate conformity assessment renewal cycles at German and Dutch notified bodies. |
| Automated Mixing System Development | Real-time viscosity sensing reduces operative variability and locks in multi-year service contracts with Japanese university hospitals. |
| Antibiotic-Loaded Formulation Expansion | Hospital-acquired infection protocols in German and French orthopedic centers mandate prophylactic elution profiles. |
| CDSCO Registration Pathway Execution | Streamlined approvals open Mumbai and Delhi private hospital chains while domestic partnerships reduce import duty exposure. |
Research Methodology
Cross-validation between orthopedic polymer chemist interviews and FDA 510(k) submission databases anchors the qualitative findings on formulation innovation trajectories. Primary fieldwork encompassed biomedical engineers at German university hospitals, GPO contracts managers at US integrated delivery networks, regulatory affairs leads at notified bodies in Berlin and Munich, and procurement directors at Japanese spinal centers. Secondary validation drew from EU MDR Article 10 technical documentation, ISO 5833 mechanical testing protocols, ECDC antibiotic resistance surveillance reports, and hospital tender databases. Bottom-up cement consumption modeling triangulated against top-down arthroplasty procedure volume projections.
Sensitivity analysis around methyl methacrylate price volatility and EU MDR conformity assessment timeline extensions stress-tested base case assumptions. The analytical framework segmented across product chemistry, procedural application, technology tier, and end-user procurement channel throughout the forecast period. CAGRs derived from procedure volume elasticity to aging demographic penetration and reimbursement intensity by geography. Industry-specific inputs included antibiotic elution profile regulatory guidance evolution and automated mixing system adoption curves at Japanese pilot sites.
Underlying assumptions cover stable FDA 510(k) predicate device strategies and sustained EU MDR notified body capacity, with deviation risk concentrated in antibiotic resistance surveillance guidance revisions and petrochemical feedstock disruptions. Forecasts reflect these conditions without claiming predictive certainty. Practitioners should keep alternative scenarios live as ECDC loading concentration guidance and methyl methacrylate supply security evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
Removable Adhesive Market