
 Connected Gym Equipment Market | 2026-2036
Connected Gym Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Gym Equipment Market Intelligence
Subscription-based software layers is rebalancing how connected gym equipment generates lifetime value, shifting revenue from one-time hardware sales toward recurring digital service streams. Technogym leverages its unified Mywellness cloud ecosystem to anchor premium positioning across commercial fitness chains. Peloton competes through vertically controlled content production and direct-to-consumer streaming membership models. Life Fitness sustains broad manufacturing scale and institutional channel relationships across North American and European gym operators.
Connected gym equipment encompasses electromechanical training machines integrated with sensors, embedded processors, and wireless communication modules that transmit performance metrics to cloud platforms and mobile applications. These systems typically incorporate Bluetooth Low Energy for peripheral pairing, Wi-Fi for cloud synchronization, and capacitive touch interfaces displaying real-time heart rate, power output, and cadence data to enable personalized workout programming and remote coaching. Exercise bikes and treadmills occupy the dominant hardware categories, with Bluetooth-enabled devices commanding premium positioning due to seamless integration with third-party fitness apps and wearable ecosystems. The rehabilitation clinic segment represents an emerging demand pocket where AI Coaching features are gaining traction for post-injury recovery protocols and clinician-supervised remote monitoring.
The FCC in the United States governs wireless transmission standards for IoT fitness devices, while the EU Cyber Resilience Act mandates baseline security certification for connected sports equipment sold across member states, effectively raising compliance barriers for entry-level manufacturers. These regulatory frameworks shape product development roadmaps by requiring encryption protocols, firmware update mechanisms, and vulnerability disclosure processes that add engineering cost but reduce liability exposure for commercial deployments. Stakeholders must weigh whether to absorb compliance investments internally or outsource certification to specialized testing laboratories as enforcement timelines solidify.
Market Dynamics
The EU Cyber Resilience Act is forcing a fundamental re-engineering of product development cycles across connected gym equipment manufacturers, as baseline security certification becomes mandatory for IoT-enabled sports devices sold in member states.
Growth Catalysts
- Boutique Studio Expansion:Specialized fitness chains in Germany are driving fleet modernization through municipal procurement programs that prioritize digitally integrated training systems over legacy hardware.
- REACH Compliance Differentiation:Manufacturers achieving full material safety certification under EU chemical regulations are capturing preferred vendor status with institutional buyers seeking liability reduction.
- Bluetooth Low Energy Integration:Seamless peripheral pairing protocols are expanding addressable market reach into wearable ecosystem users demanding unified health data streams.
Market Restraints
- Semiconductor Input Volatility:Embedded processor and sensor module costs fluctuate with foundry capacity constraints in Taiwan and South Korea, compressing hardware margins.
- Cloud Infrastructure Concentration:Reliance on AWS, Microsoft Azure, and Google Cloud for workout data synchronization creates single-point vulnerability for equipment operators.
- FCC Certification Friction:United States wireless transmission approval timelines extend go-to-market schedules by 4-8 months versus non-connected alternatives.
Strategic Opportunities
- Rehabilitation Clinic Penetration:Post-injury recovery facilities in the United States represent underdeveloped demand for AI Coaching-enabled remote monitoring protocols.
- GDPR-Compliant Data Monetization:European operators can leverage anonymized performance analytics as secondary revenue streams without triggering cross-border transfer restrictions.
- Hotel Wellness Channel Innovation:Direct procurement relationships with hospitality chains bypass traditional fitness distributor markups while enabling white-label software customization.
Industry Challenges
- Firmware Security Talent Scarcity:Embedded systems engineers with IoT vulnerability assessment capabilities command premium compensation, constraining R&D expansion.
- Legacy Equipment Integration Complexity:Retrofitting analog training machines with sensor arrays and wireless modules requires custom mechanical engineering per installation.
- CE Marking Timeline Compression:Accelerated EU enforcement schedules for cyber resilience certification are compressing product validation windows ahead of December 2024 deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Gym Equipment Market |
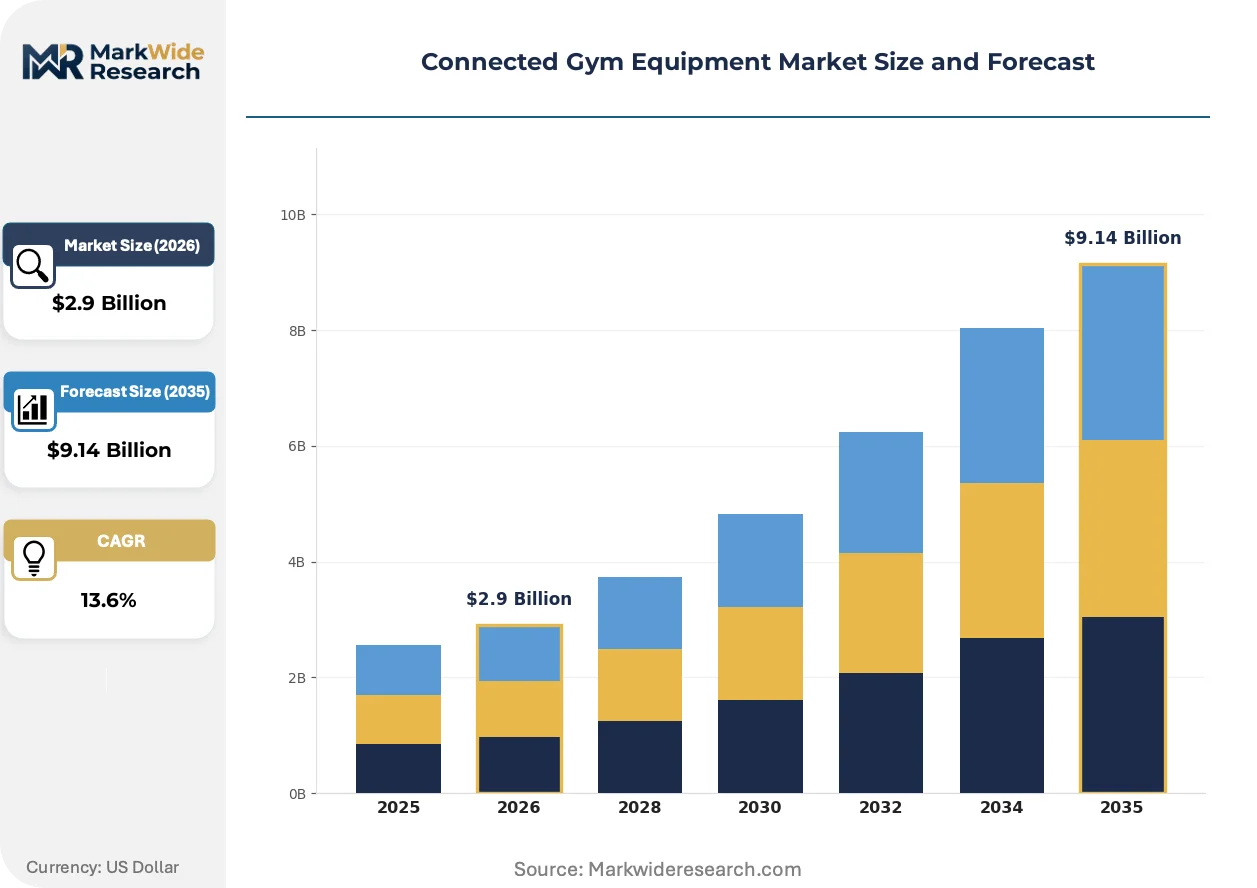
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $9.14 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Exercise Bikes, Ellipticals, Rowing Machines Technology: Bluetooth, Wi-Fi, NFC, Cloud Connectivity End User: Home Users, Fitness Centers, Corporate Gyms, Rehabilitation Clinics Feature: Real-Time Tracking, Virtual Workouts, Social Connectivity, AI Coaching |
| Companies Covered | EGYM, Echelon, Life Fitness, Precor, Matrix Fitness, Technogym, NordicTrack, Concept2, Peloton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Gym Equipment Market Strategic Shifts & Innovations
Software-defined hardware architectures are dissolving traditional boundaries between physical training equipment and digital service platforms, enabling rapid feature deployment without hardware replacement cycles.
Edge computing modules with localized AI inference capabilities are modularizing how connected gym equipment processes biometric data. Rehabilitation clinics and high-end boutique studios are adopting these systems fastest, reducing cloud dependency for real-time form correction. This architecture is modularizing vendor competitive advantage away from raw manufacturing scale toward software iteration velocity.
The EU Cyber Resilience Act mandates encryption protocols, automated firmware update mechanisms, and standardized vulnerability disclosure processes for all networked sports equipment. Manufacturers must now maintain dedicated security engineering functions or outsource to specialized testing laboratories. Commercial fitness chains with multi-country footprints face the steepest compliance burden as enforcement solidifies across member states.
Subscription unbundling from hardware purchases is restructuring buyer economics across institutional segments. North American university recreation centers and corporate wellness programs increasingly reject bundled financing in favor of separate equipment procurement and SaaS licensing negotiations. Germany's municipal gym operators exhibit the most advanced procurement sophistication, demanding granular service-level agreements for uptime and data portability.
Connected Gym Equipment Market Segmentation
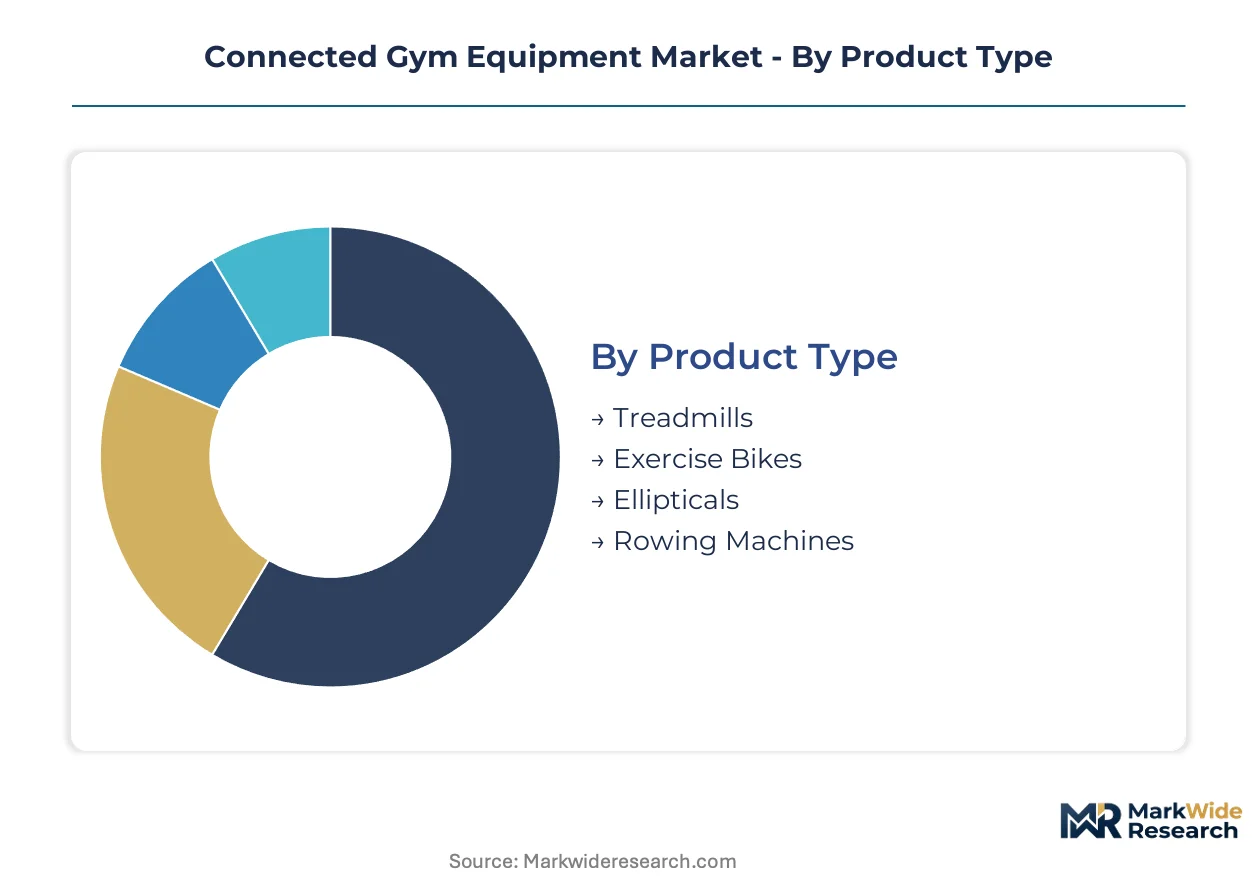
Equipment replacement cycles in commercial fitness chains accelerate when digital integration promises measurable member retention gains. Segmentation reveals where procurement budgets flow and which technical specifications command premium positioning across institutional buyers.
Product Type:
Upgrade decisions hinge on floor space efficiency and member utilization rates rather than hardware durability alone.
- Treadmills:Electromechanical running decks with integrated heart rate sensors and variable incline motors dominate commercial floor space allocation. Demand concentrates in German municipal gym modernization programs where fleet standardization reduces maintenance contract complexity.
- Exercise Bikes:Stationary cycles with magnetic resistance systems and crank-based power meters anchor boutique studio configurations. Volume clusters in North American corporate wellness centers seeking low-impact cardiovascular options for diverse employee demographics.
- Ellipticals:Cross-trainer machines with adjustable stride lengths and upper-body engagement arms serve rehabilitation-focused installations.
- Rowing Machines:Air or water resistance ergometers with performance monitors appeal to high-intensity interval training formats.
Volume placements concentrate in Treadmills; the faster expansion belongs to Exercise Bikes.
Technology:
Wireless protocol selection determines ecosystem lock-in and third-party app compatibility for end users.
- Bluetooth:Low-energy peripheral pairing enables seamless heart rate monitor and smartwatch integration without complex network configuration. Demand concentrates in home user segments prioritizing plug-and-play setup simplicity over advanced analytics depth.
- Wi-Fi:Continuous cloud synchronization supports real-time leaderboard updates and remote firmware management for commercial operators. Volume clusters in fitness center chains requiring centralized equipment monitoring across multiple locations.
- NFC:Tap-to-pair authentication streamlines user profile loading in high-traffic institutional settings.
- Cloud Connectivity:Direct platform integration enables subscription-based content streaming and workout history storage.
Bluetooth dominates current installation bases; Wi-Fi is climbing the fastest as cloud-dependent features become standard.
End User:
Procurement sophistication varies sharply across customer types, with contract structures and service-level expectations diverging significantly.
- Home Users:Direct-to-consumer purchasers prioritize compact footprints and subscription bundling over commercial-grade durability. Demand concentrates in suburban markets with dedicated exercise space and reliable broadband infrastructure.
- Fitness Centers:Multi-location chains negotiate fleet pricing with uptime guarantees and rapid replacement provisions. Volume clusters in Germany where municipal procurement frameworks favor digitally integrated equipment tenders.
- Corporate Gyms:Employer-sponsored wellness facilities prioritize low-maintenance operation and broad demographic accessibility over performance metrics depth.
- Rehabilitation Clinics:Medical-supervised recovery centers require HIPAA-compliant data handling and clinician dashboard integration.
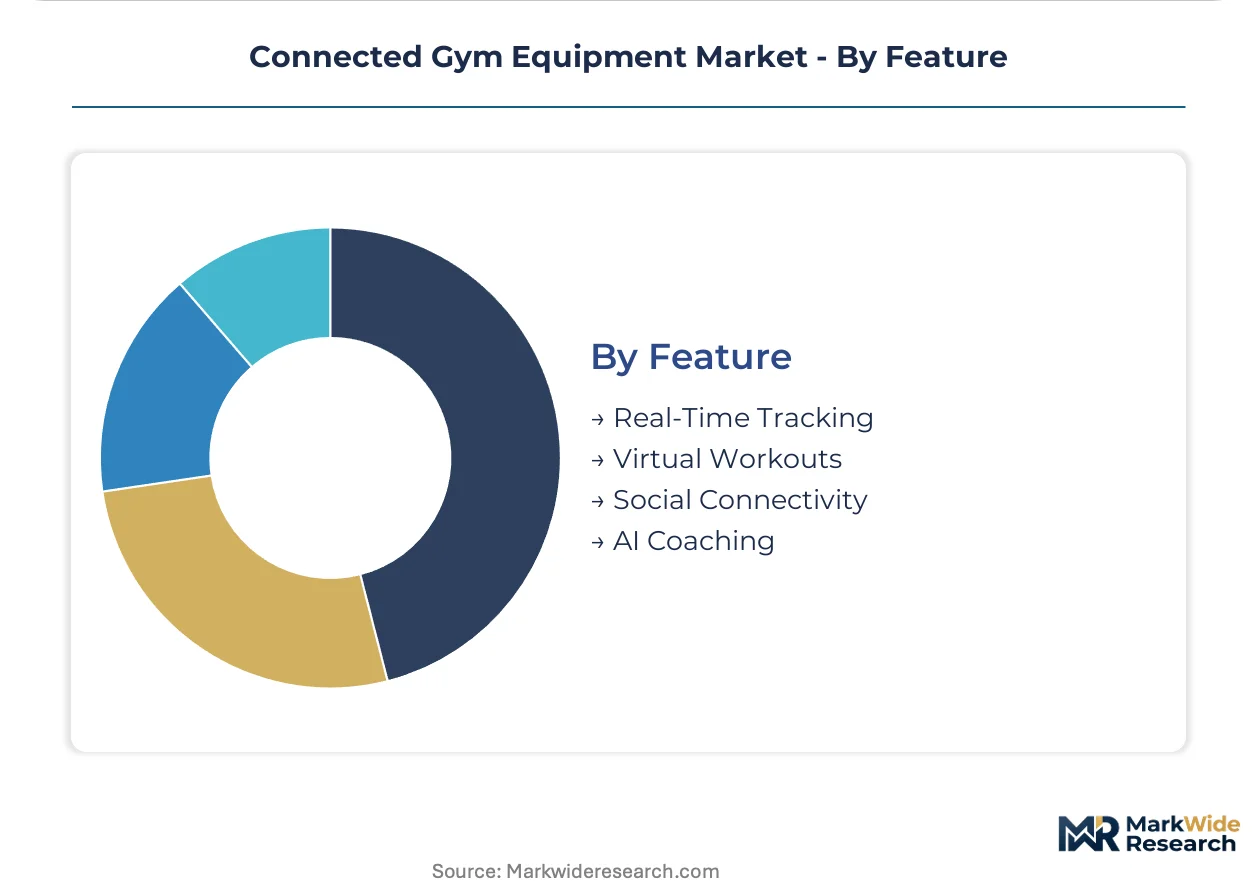
Fitness Centers absorb the highest absolute volume; Rehabilitation Clinics are gaining share fastest as remote monitoring protocols expand.
Feature:
Software capability differentiation increasingly determines hardware selection criteria across institutional segments.
- Real-Time Tracking:Instantaneous display of heart rate, power output, and cadence metrics enables self-paced workout adjustment. Demand concentrates in performance-oriented home users and boutique studios emphasizing measurable progress.
- Virtual Workouts:Streaming instructor-led classes and simulated terrain environments reduce perceived equipment monotony. Volume clusters in corporate gym settings where programming variety compensates for limited floor space diversity.
- Social Connectivity:Leaderboards and achievement sharing drive engagement in competitive user segments.
- AI Coaching:Algorithmic form correction and adaptive programming personalize training load without human trainer involvement.
Real-Time Tracking remains the baseline expectation; AI Coaching shows the steepest expansion trajectory as rehabilitation applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Taiwan and South Korea supplies semiconductor components, while consumption clusters in Western Europe and North America where municipal and corporate procurement budgets flow.
United States
Corporate wellness programs and university recreation centers drive fleet modernization. FCC certification requirements extend equipment launch timelines. Rehabilitation clinics in Florida and California adopt AI Coaching systems for post-injury recovery protocols.
Germany
Municipal gym operators prioritize digitally integrated equipment tenders through regional procurement frameworks. EU Cyber Resilience Act mandates baseline security certification for all IoT-enabled devices. Bavaria's fitness studio chains anchor demand for Bluetooth-enabled exercise bike fleets.
China
Domestic fitness chains expand connected equipment deployment in tier-one cities. MIIT governs wireless transmission standards for smart hardware. Shenzhen manufacturers supply sensor modules and embedded processors to global equipment brands.
United Kingdom
Boutique studio expansion in London accelerates networked training system adoption. GDPR compliance shapes data handling architectures for performance analytics. Manchester and Birmingham host distributor networks serving commercial fitness chains.
Japan
Corporate wellness facilities integrate compact connected equipment for aging workforce demographics. METI standards influence IoT device interoperability requirements. Tokyo's metropolitan gym operators demand granular service-level agreements for equipment uptime.
Connected Gym Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the connected gym equipment landscape. Vertically integrated manufacturers controlling cloud software development and content production face asset-light hardware specialists sourcing white-label digital platforms. Three archetypes dominate: integrated platform owners, manufacturing-scale suppliers, and direct-to-consumer streaming brands. M&A activity concentrates on software capability acquisition, while geographic expansion targets European municipal procurement channels.
Within the integrated platform tier, Technogym anchors premium positioning through unified cloud ecosystems, while Peloton exemplifies vertically controlled content production models. Life Fitness occupies the manufacturing-scale archetype with broad institutional channel relationships across North American and European gym operators.
| Leading Market Players |
|---|
| EGYM |
| Echelon |
| Life Fitness |
| Precor |
| Matrix Fitness |
| Technogym |
| NordicTrack |
| Concept2 |
| Peloton |
| Others |
Cost & Logistics Intelligence
Semiconductor foundry pricing indices in Taiwan cascade through connected gym equipment supply chains, compressing margins at the embedded processor tier while amplifying differentiation premiums for cyber-resilience-certified hardware tiers.
Pricing Analysis
Cost-down pressure on mid-tier equipment accelerates because municipal procurement programs in Germany prioritize digitally integrated fleets with mandatory EU Cyber Resilience Act certification. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native platform bundles from basic Bluetooth-enabled hardware and unconnected legacy alternatives. Price differentiation hinges on firmware security certification grade and after-sales service bundling. Boutique studios exhibit least price sensitivity; entry-level home users absorb greatest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for embedded processors and sensor modules, constraining foundry allocation flexibility during capacity crunches. Component sourcing draws from Shenzhen for capacitive touch interfaces, Germany for precision motor assemblies, and Japan for high-durability bearings. Tariff exposure on semiconductor imports from East Asia threatens hardware margin stability. Distribution runs through commercial fitness equipment distributors serving gym chains, direct procurement relationships with hospitality operators, and direct-to-consumer channels for home segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected gym equipment market functions as a cost-of-compliance story where the EU Cyber Resilience Act erects barrier-to-entry moats favoring manufacturers with dedicated security engineering functions.
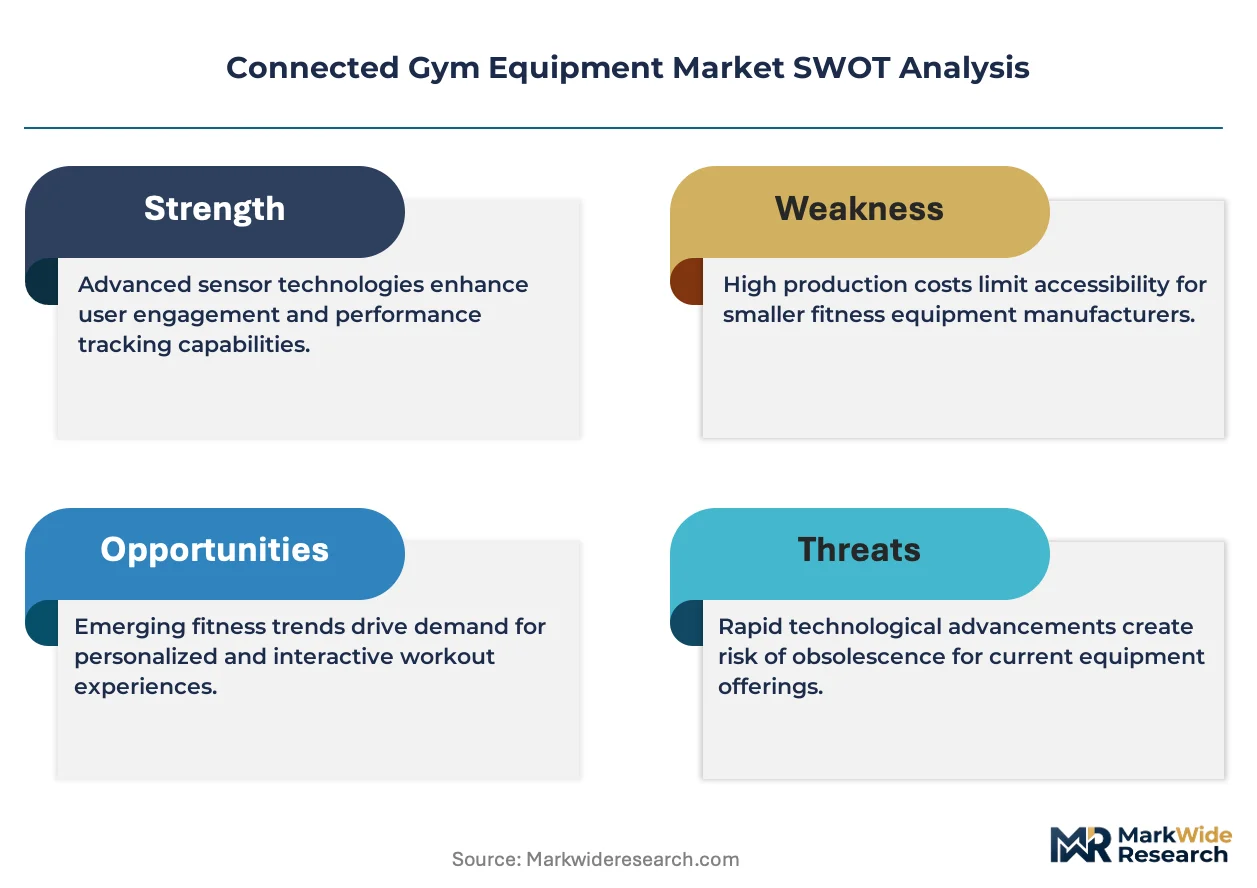
For Market Incumbents: Cement platform stickiness through backward integration into firmware security development, insulating against asset-light competitors outsourcing certification to testing laboratories. Expand captive cloud infrastructure capacity across European data centers to reduce AWS concentration risk. Prioritize municipal procurement framework pre-qualification in Germany where fleet standardization contracts lock out uncertified rivals. For New Entrants and Emerging Players: Direct-to-consumer streaming subscriptions offer the most penetrable entry vector, bypassing institutional sales cycles and FCC certification delays. Target rehabilitation clinic segments in the United States where HIPAA-compliant AI Coaching capabilities remain underdeveloped. Pursue white-label software partnerships with hotel wellness chains seeking customized member experience platforms without vertical hardware investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated platform owners with unified cloud ecosystems in European geographies where enforcement timelines compress validation windows. Five-to-ten year viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Monitor municipal tender award patterns in Bavaria and North Rhine-Westphalia as inflection indicators for procurement sophistication migration.| Strategic Initiative | Industry Significance |
|---|---|
| Cyber Resilience Certification Investment | EU Cyber Resilience Act mandates baseline security protocols, raising engineering barriers for commercial deployments. |
| Cloud Platform Integration | Unified ecosystems like Mywellness anchor premium positioning across German municipal gym chains. |
| Rehabilitation Clinic Partnership | HIPAA-compliant AI Coaching capabilities unlock post-injury recovery protocols in Florida and California facilities. |
| Direct Hospitality Procurement | Hotel wellness channel relationships bypass distributor markups while enabling white-label software customization. |
| Edge Computing Module Deployment | Localized AI inference reduces cloud dependency for real-time form correction in high-end boutique studios. |
Research Approach
Independent corroboration across equipment procurement officers at German municipal gym operators, firmware security engineers at IoT testing laboratories, and hospitality wellness directors underwrites the qualitative findings. Primary interviews with commercial fitness chain CTOs, rehabilitation clinic biomedical engineers, and semiconductor procurement leads at equipment manufacturers combined with secondary validation from FCC equipment authorization databases, EU Cyber Resilience Act draft regulatory texts, and municipal tender documentation from Bavaria and North Rhine-Westphalia. Bottom-up installation base modeling and top-down addressable market sizing triangulate volume estimates.
Rate-of-change decomposition across the analysis window segments expansion by equipment type, wireless protocol technology, end-user procurement sophistication, and software feature tier. CAGRs derive from equipment replacement cycle acceleration patterns, subscription attachment rate trajectories, and municipal procurement budget allocation shifts. Industry-specific forecast inputs include foundry capacity utilization projections for Taiwan semiconductor suppliers and enforcement timeline certainty for EU cyber resilience certification.
The model holds under stable regulatory enforcement schedules and foundry capacity normalization; deviation in tariff escalation or accelerated CE marking deadlines would shift replacement cycle assumptions. Forecasts reflect documented assumptions about municipal procurement migration patterns and cloud infrastructure concentration stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Smart Gym Equipment Market