
 Global Commercial Fitness Equipment Market | 2026-2036
Global Commercial Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Fitness Equipment Market Analysis
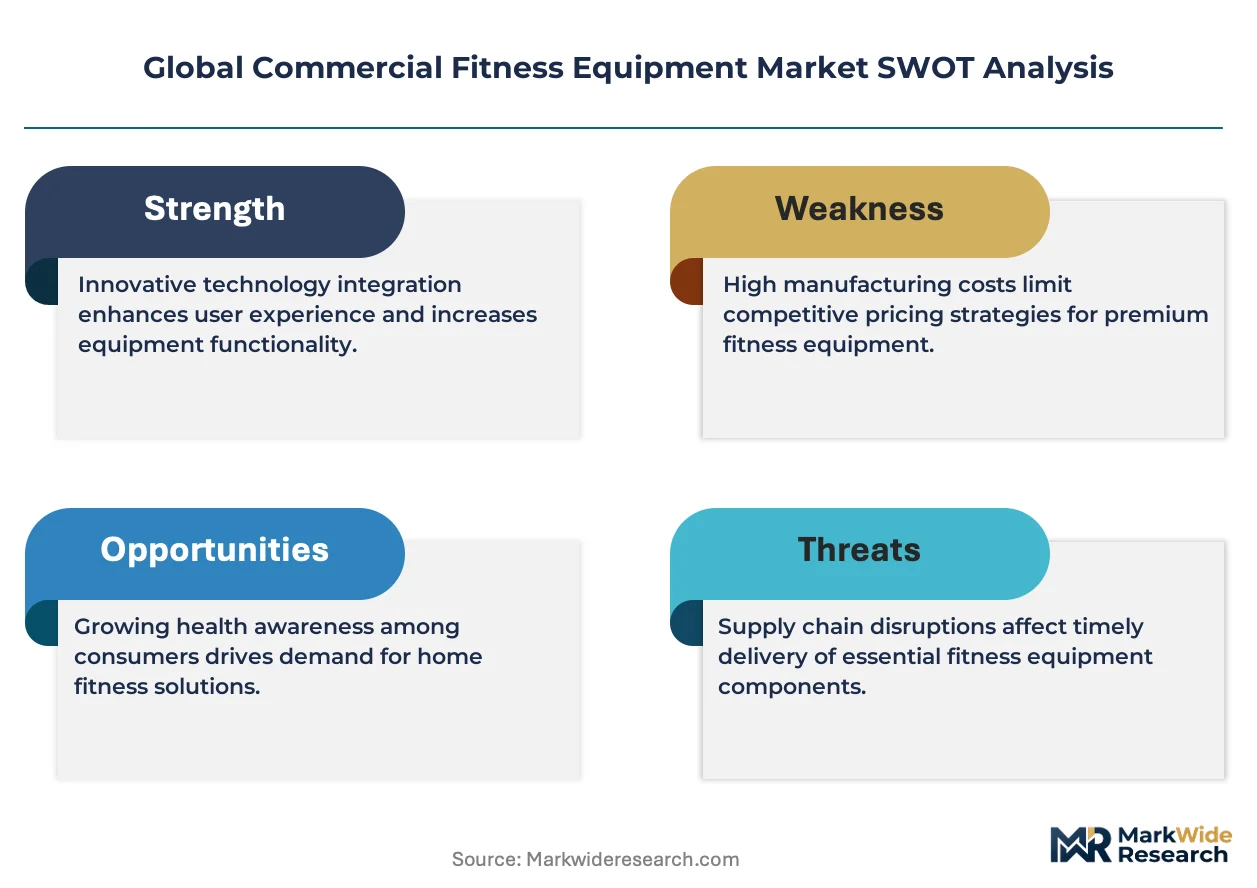
Aftermarket service revenue is reshaping margin capture across the Global Commercial Fitness Equipment Market as operators seek to extend asset lifecycles and reduce capital intensity. Technogym S.p.A. leverages its connected ecosystem to lock in recurring software subscriptions alongside hardware sales. Life Fitness sustains broad geographic coverage through extensive distributor partnerships. Johnson Health Tech anchors its position with manufacturing scale across Asian production bases.
Commercial fitness equipment comprises motorized and non-motorized apparatus designed for repeated public-use environments, typically constructed with steel alloy frames, commercial-grade motors rated for continuous duty cycles, and polyurethane cushioning systems engineered for durability exceeding 10,000 operating hours. Treadmills retain the largest product type revenue share due to their ubiquity across gyms and health clubs, while smart technology integration is expanding fastest as operators demand real-time usage analytics and member engagement tools. Strength machines occupy mature margin pools in corporate fitness centers where space constraints favor multi-station configurations.
ISO 20957 governs safety and performance testing protocols for stationary training equipment across major export markets, while the EU's CE marking and Machinery Directive establish conformity requirements for European market access. The US Consumer Product Safety Commission monitors injury reporting trends that influence design standards and liability exposure. Stakeholders must weigh connected-platform R&D commitments against the capital requirements of serving fragmented community center procurement channels.
Market Dynamics
Aftermarket service revenue streams are restructuring competitive economics across the Global Commercial Fitness Equipment Market as operators prioritize asset lifecycle extension over new capital deployment. Connected platform subscriptions now command recurring revenue multiples that hardware sales alone cannot replicate.
Growth Catalysts
- EU Green Deal compliance mandates:Manufacturers are retooling production lines to meet lower-emission thresholds, creating first-mover advantage for certified suppliers accessing European health club procurement channels.
- China domestic gym chain expansion:Provincial fitness operators are accelerating equipment refresh cycles as membership bases scale beyond 10 million active users nationally.
- Smart technology integration:Real-time usage analytics and member engagement tools are penetrating boutique studio segments previously served by basic mechanical equipment.
Market Restraints
- Steel alloy input volatility:Commercial-grade frame material costs fluctuate with energy-intensive smelting operations concentrated in specific Asian production basins.
- ISO 20957 certification timeline:Safety and performance testing protocols impose 6-12 month validation windows that delay product launches in major export markets.
- Used equipment resale channels:Secondary markets for refurbished treadmills and strength machines capture budget-conscious community center demand that would otherwise flow to new equipment orders.
Strategic Opportunities
- Corporate wellness mandate expansion:Employer-sponsored fitness benefits in Germany and France are creating dedicated procurement budgets for on-site multi-station configurations.
- Software-hardware convergence:Integration of biomechanical feedback sensors with cloud-based training programming opens subscription revenue in rehabilitation clinic verticals.
- India PLI scheme alignment:Domestic manufacturing incentives for fitness equipment assembly are attracting component suppliers to establish regional supply nodes.
Industry Challenges
- Connected platform cybersecurity certification:GDPR compliance for biometric data collection requires specialized engineering talent scarce in traditional mechanical equipment firms.
- Legacy equipment interoperability:Retrofitting analog strength machines with digital tracking modules demands firmware development capabilities outside core manufacturing competencies.
- Continuous-duty motor supply concentration:Commercial-grade treadmill drive systems rely on specialized winding suppliers with limited geographic diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Fitness Equipment Market |
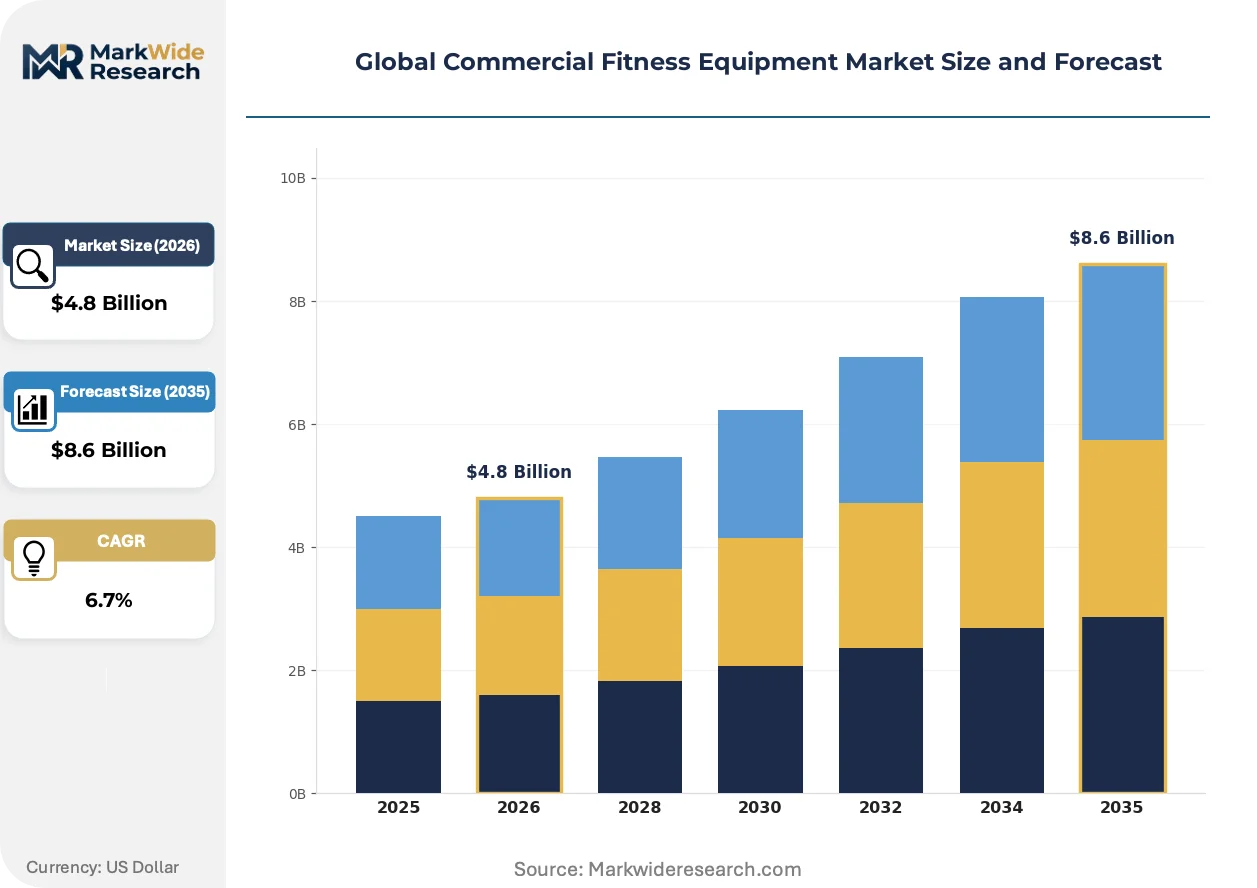
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Ellipticals, Stationary Bikes, Strength Machines End User: Gyms, Health Clubs, Corporate Fitness Centers, Community Centers Technology: Electronic, Mechanic, Digital, Smart Distribution Channel: Online Retail, Direct Sales, Distributors, Brick-and-Mortar |
| Companies Covered | Technogym S.p.A., Life Fitness, Precor Incorporated, Core Health & Fitness, Johnson Health Tech, Cybex International, Brunswick Corporation, TRUE Fitness, Torque Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Fitness Equipment Market Emerging Trajectories
Digital ecosystem integration is displacing standalone hardware value propositions across gym operator procurement evaluations. Equipment vendors now compete on platform stickiness rather than mechanical specifications alone.
Biomechanical sensor arrays embedded in strength training stations are migrating from premium health club installations to mid-market corporate fitness centers. Facility managers in the United Kingdom and Australia are piloting these systems to reduce injury liability exposure. The technology is migrating from high-end boutique studios toward volume-driven commercial chains seeking differentiation without floor space expansion.
REACH substance restrictions on polyurethane cushioning formulations are forcing reformulation of impact-absorption components used in treadmills and elliptical trainers. European manufacturers face 18-month material qualification cycles to maintain CE marking compliance. German and Italian production facilities are absorbing the highest compliance costs as they serve markets with the most stringent enforcement protocols.
Leasing structures with bundled maintenance and software access are displacing outright purchase models among US multi-location gym operators. Private equity-backed fitness chains favor operational expenditure treatment for tax optimization. This shift concentrates most visibly in Texas and Florida markets where capital-light expansion strategies dominate competitive positioning.
Global Commercial Fitness Equipment Market Segmentation
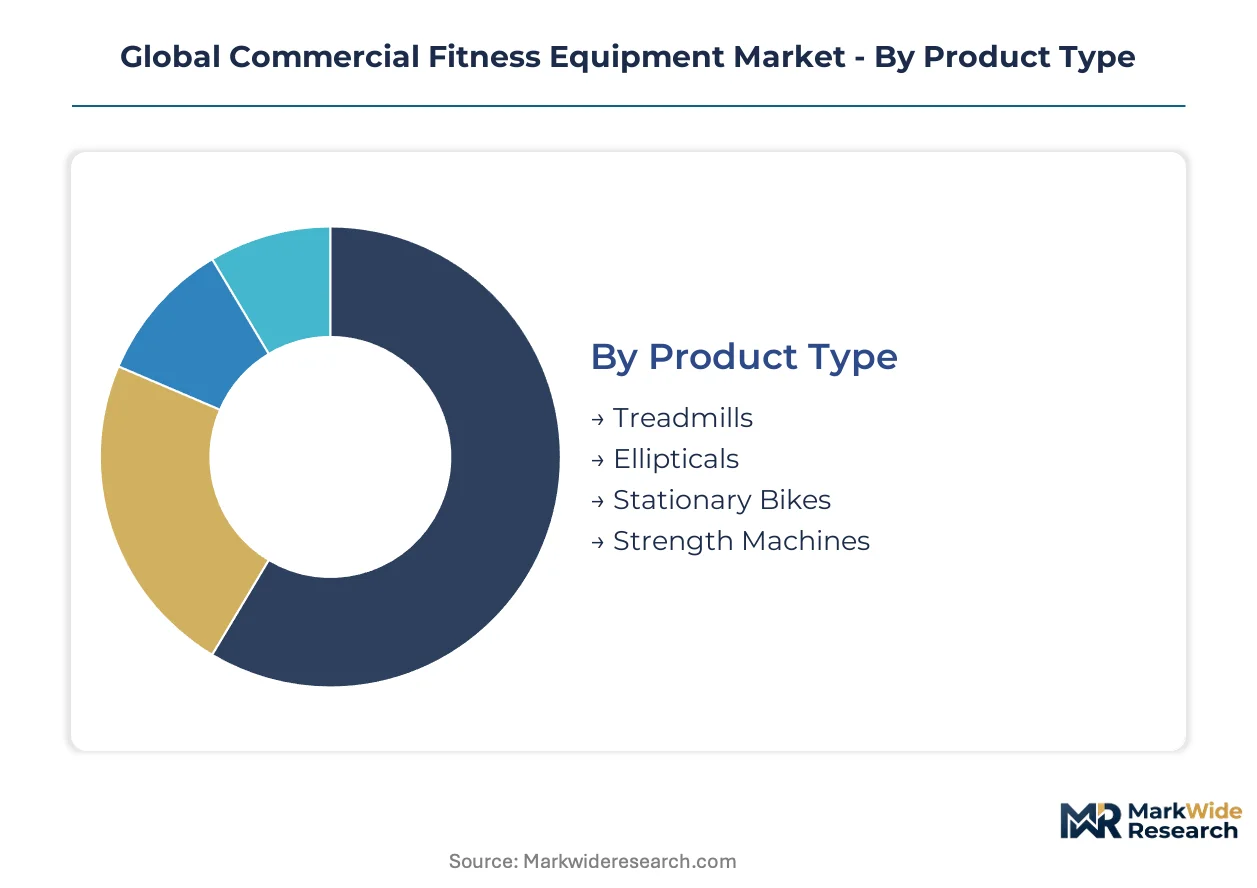
Equipment segmentation in the commercial fitness sector reveals divergent margin structures across mechanical versus connected product categories. Procurement patterns vary sharply between capital-intensive gym chains and budget-constrained municipal facilities.
Product Type:
Mature motorized equipment dominates installed base volumes while emerging smart-enabled categories capture premium pricing.
- Treadmills:Continuous-duty motor systems with steel alloy frames and polyurethane cushioning rated for 10,000+ operating hours. Demand concentrates in US multi-location gym chains refreshing cardio floors, constrained by steel input volatility from Asian smelting basins.
- Strength Machines:Multi-station configurations with selectorized weight stacks and cable transmission systems. Corporate fitness centers in Germany and France prioritize space-efficient designs as employer wellness mandates expand on-site facilities.
- Ellipticals:Low-impact cardio platforms with adjustable stride mechanisms and electromagnetic resistance.
- Stationary Bikes:Upright and recumbent configurations for high-cadence interval training programming.
Treadmills handle the majority of throughput; strength machines are gaining share fastest in corporate verticals.
End User:
Customer type segmentation tracks capital availability and procurement sophistication across facility ownership models.
- Gyms:High-volume membership operations with 24/7 access models and centralized equipment refresh cycles. China's domestic chains are accelerating procurement as active users exceed 10 million nationally, though used equipment resale channels capture budget-conscious demand.
- Health Clubs:Premium amenity-focused facilities with spa and recovery service integration. UK and Australian operators are piloting biomechanical sensor arrays to reduce injury liability exposure.
- Corporate Fitness Centers:Employer-sponsored on-site facilities with space constraints favoring multi-station configurations.
- Community Centers:Municipal and nonprofit facilities with fragmented procurement channels and extended asset lifecycles.
Gyms command the largest equipment volumes; health clubs are expanding fastest on software-hardware convergence.
Technology:
Technology tiers separate legacy mechanical installations from connected platforms generating recurring revenue streams.
- Smart:Cloud-integrated systems with real-time usage analytics, member engagement tools, and biomechanical feedback sensors. Boutique studios in the United States are expanding procurement budgets for these platforms as operators prioritize asset lifecycle extension over new capital deployment.
- Digital:Embedded displays with pre-programmed workout content and basic connectivity.
- Electronic:Motorized resistance and programmable incline without network integration.
- Mechanic:Gravity-based resistance systems with minimal component complexity serving budget procurement channels.
Smart technology is climbing the fastest on subscription revenue multiples; electronic equipment retains the broadest installed base.
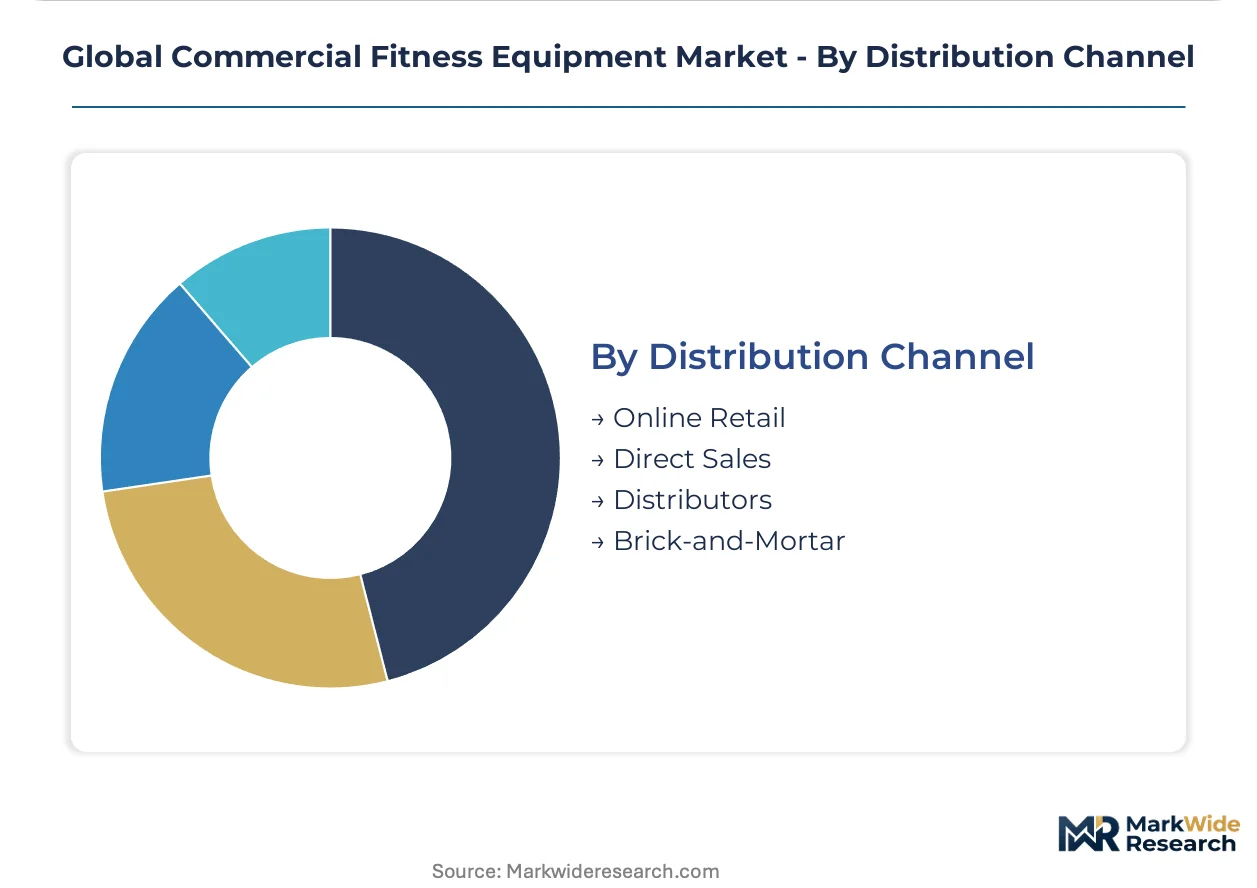
Distribution Channel:
Channel structure reflects capital treatment preferences and geographic coverage requirements across operator types.
- Direct Sales:Manufacturer-led account management for large-scale gym chain deployments with bundled maintenance and software access. Private equity-backed US operators in Texas and Florida favor leasing structures for operational expenditure treatment.
- Distributors:Extensive geographic coverage networks serving fragmented community center procurement with localized service capabilities.
- Online Retail:Digital procurement platforms with specification comparison tools for mid-market facility managers.
- Brick-and-Mortar:Physical showrooms with demonstration capabilities for equipment evaluation.
Direct sales capture the highest-value contracts; distributor networks are expanding most quickly into underserved municipal markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fitness equipment manufacturing clusters concentrate in northern Italy, southern Germany, and China's eastern seaboard, with final assembly facilities gravitating toward major consumer markets to reduce logistics exposure. Taiwan and South Korea supply specialized motor drive systems and electronic control modules. Raw steel inputs flow from integrated mills in Hebei Province and the Ruhr Valley.
United States
Multi-location gym chains in Texas and Florida are accelerating equipment refresh cycles as private equity-backed operators favor leasing structures for tax optimization. The Consumer Product Safety Commission monitors injury reporting trends that influence design standards and liability exposure. Life Fitness maintains headquarters and R&D operations in the Chicago metropolitan area.
Germany
Corporate wellness mandates in Bavaria and Baden-Württemberg are creating dedicated procurement budgets for on-site multi-station configurations. The EU Green Deal and REACH substance restrictions impose 18-month material qualification cycles on polyurethane cushioning reformulation. Technogym S.p.A. operates a major distribution hub serving central European health club networks from Cesena.
China
Domestic gym chains are scaling beyond 10 million active users nationally, accelerating provincial equipment procurement from Jiangsu and Zhejiang manufacturing bases. GB standards and dual carbon goals from the Ministry of Ecology and Environment are retooling production lines in the Yangtze River Delta. Johnson Health Tech anchors manufacturing scale across Taiwanese-invested facilities in Xiamen and Dongguan.
United Kingdom
Health club operators in Greater London are piloting biomechanical sensor arrays to reduce injury liability exposure and differentiate premium amenity offerings. GDPR compliance for biometric data collection requires specialized engineering talent that traditional mechanical equipment firms struggle to source. Core Health & Fitness maintains service infrastructure serving boutique studio expansions in Manchester and Birmingham.
Australia
Corporate fitness centers in Sydney and Melbourne are adopting smart-enabled strength training stations previously limited to premium health club installations. The Therapeutic Goods Administration and state-level consumer protection frameworks govern equipment safety claims in rehabilitation clinic verticals. Precor Incorporated distributes through established channels serving municipal community centers in Queensland and Western Australia.
Global Commercial Fitness Equipment Market Vendor Landscape
Integrated platform providers and manufacturing-scale specialists split the market between recurring revenue capture and unit cost optimization. Technogym S.p.A. leverages connected ecosystem subscriptions alongside hardware sales, while Johnson Health Tech competes on Asian production base efficiency. The competitive landscape is consolidating through distributor network acquisitions and software-hardware convergence partnerships rather than pure manufacturing capacity expansion.
Among Italian-origin integrated platform providers, Technogym S.p.A. exemplifies the connected-ecosystem archetype with recurring software revenue models. Life Fitness represents the geographic coverage specialist archetype through extensive distributor partnerships spanning fragmented community center procurement channels. Johnson Health Tech occupies the manufacturing-scale position anchored across Taiwanese and Chinese production bases. These three companies illustrate the strategic divergence between platform stickiness, distribution breadth, and production efficiency that defines competitive positioning in this sector.
| Leading Market Players |
|---|
| Technogym S.p.A. |
| Life Fitness |
| Precor Incorporated |
| Core Health & Fitness |
| Johnson Health Tech |
| Cybex International |
| Brunswick Corporation |
| TRUE Fitness |
| Torque Fitness |
| Others |
Supply Flow & Price Mechanics
Hebei Province steel alloy smelting concentrates the upstream cost structure for commercial-grade treadmill frames, anchoring margin capture in aftermarket service tiers rather than hardware production alone. Chinese motor winding suppliers in the Yangtze River Delta feed continuous-duty drive systems to final assemblers in Italy and Germany, creating geographic asymmetry between input costs and pricing power.
Pricing Analysis
Extended warranty and preventive maintenance contracts drive lifetime value capture as gym operators shift from capital expenditure to operational expenditure treatment. Three-tier pricing structure across premium connected platforms, standard electronic equipment, and economy mechanical units separates procurement budgets by facility sophistication. Pricing pressure stems from used equipment resale channels capturing municipal community center demand that would otherwise flow to new orders. Boutique studios in Texas and Florida show lowest price sensitivity as private equity backing enables leasing structures with bundled software access.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for motor drive system procurement. Manufacturing clusters in northern Italy, southern Germany, and China's eastern seaboard draw from Taiwanese and South Korean electronic control module suppliers. Commercial-grade polyurethane cushioning depends on REACH-compliant formulations facing 18-month qualification cycles. Distribution runs through direct sales for large gym chains and extensive distributor networks for fragmented municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Commercial Fitness Equipment Market sits in early-cycle expansion as connected platform subscriptions penetrate boutique studio segments previously served by basic mechanical equipment. Corporate wellness mandate expansion in Germany and France accelerates dedicated procurement budget formation for on-site facilities.
For Market Incumbents: Pre-empt software-hardware convergence threats by deepening captive supply of biomechanical sensor arrays and cloud-based training programming. Anchor defensive positioning through ISO 20957 certification investment that delays challenger product launches by 6-12 months. Control distributor partnerships in fragmented community center channels to limit emerging entrant geographic coverage. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-aligned domestic manufacturing incentives for fitness equipment assembly. Target rehabilitation clinic verticals in Australia and the United Kingdom where GDPR-compliant biometric data collection capabilities remain scarce among traditional mechanical equipment firms. Pursue white-label connected platform partnerships with provincial gym chains in China scaling beyond 10 million active users. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed multi-location gym operators in Texas and Florida favoring capital-light leasing structures. Long-term viability over the coming decade hinges on recurring revenue multiples from software subscriptions rather than hardware replacement cycles. Watch for inflection signals in corporate wellness mandate expansion across German and French employer-sponsored fitness benefit programs.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Platform Integration | Technogym's ecosystem locks in recurring software revenue alongside hardware sales. |
| EU Green Deal Compliance Investment | REACH-aligned polyurethane reformulation secures CE marking for European health club access. |
| Aftermarket Service Network Expansion | Life Fitness distributor partnerships capture fragmented community center procurement channels. |
| Asian Manufacturing Scale Buildout | Johnson Health Tech's Taiwanese-invested facilities in Xiamen anchor production cost efficiency. |
| Biomechanical Sensor Array Deployment | UK and Australian health club pilots reduce injury liability exposure through real-time feedback. |
Methodological Framework
Desk research of trade customs data, equipment safety filings, and gym operator procurement databases preceded structured interviews with maintenance directors at multi-location chains, plant engineers at steel alloy suppliers, and aftermarket service heads at distributor networks. Primary fieldwork with health club operators in Germany and corporate wellness program managers in France validated secondary estimates of connected platform adoption rates. Bottom-up equipment unit forecasts triangulated against top-down fitness facility investment projections across the analysis window.
Baseline assumptions held fixed steel input cost volatility and EU Green Deal emission threshold timelines while varying boutique studio expansion rates and corporate wellness mandate penetration. Segmentation modeling tracked product type, end user facility category, technology tier, and distribution channel across the projection horizon. CAGRs derived from equipment refresh cycle analysis and membership base scaling in China and India. Industry-specific inputs included ISO 20957 certification timeline delays and REACH substance restriction compliance costs.
Stress conditions across steel alloy price bands, certification backlog durations, and connected platform cybersecurity talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about gym chain capital availability and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
North America Exercise Bike Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Cardio Fitness Trampolines Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
BMI Machine Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
China Fitness Rings Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Home Fitness Market