
 Virtual Reality Fitness Market | 2026-2036
Virtual Reality Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality Fitness Market Insights
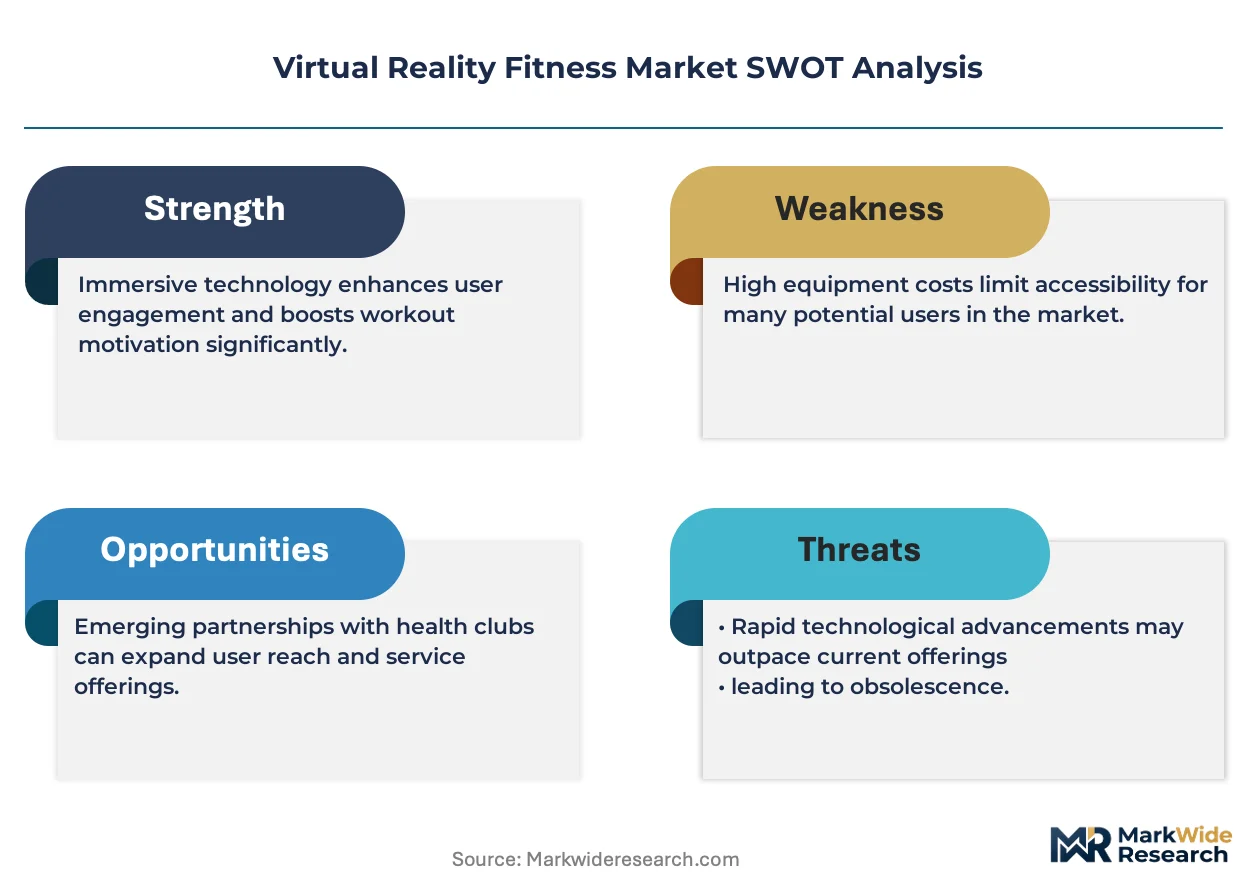
A capital-intensity divergence between headset manufacturers and content studios is unwinding competitive dynamics across the sector. Meta leverages its captive hardware-install base to subsidize content acquisition and control distribution economics. FitXR anchors its position through exclusive studio partnerships that lock in choreography intellectual property. Schell Games competes on development velocity, releasing new fitness titles faster than pure-play hardware rivals can match.
Virtual Reality Fitness denotes immersive exercise experiences delivered through head-mounted displays combining stereoscopic visual rendering, six-degrees-of-freedom motion tracking, and spatial audio to simulate instructor-led classes or gamified workouts in synthetic environments. The primary commercial purpose replaces physical gym attendance with location-flexible, data-rich training sessions that capture biomechanical performance metrics for user feedback and progression tracking. Applications dominate current revenue as recurring subscription models outperform one-time game purchases, while Fitness Equipment represents the fastest-growing product type as dedicated resistance peripherals and haptic-enabled accessories migrate from novelty to standard kit. Motion Tracking technology leads margin pools through patent-protected sensor fusion algorithms that differentiate premium tiers from basic accelerometer implementations.
FDA oversight of software-as-medical-device claims shapes how rehabilitation-focused content gets marketed to clinical end users, while FCC regulations govern wireless transmission standards for standalone headset connectivity. GDPR and the EU AI Act impose biometric data processing constraints that increase compliance costs for European personal user deployments. Stakeholders must monitor evolving classification thresholds that determine whether fitness algorithms with health diagnostic features trigger medical device scrutiny in key jurisdictions.
Market Dynamics
Hardware subsidization by ecosystem owners is compressing content-studio margins and forcing independent developers toward exclusive distribution deals or direct-to-consumer pivots. This capital asymmetry between headset manufacturers and software creators defines current competitive pressure.
Growth Catalysts
- Biometric Data Frameworks:GDPR and the EU AI Act establish processing standards that reduce legal uncertainty for motion-tracking deployments in European personal user segments. Compliance clarity accelerates studio investment.
- Post-Pandemic Habit Persistence:Home-based workout routines cemented during 2020-2021 continue driving headset purchases among personal users who prioritize location flexibility over gym commuting.
- FCC Wireless Standards:Updated transmission protocols for standalone headsets enable lower-latency motion tracking, improving user experience in high-intensity interval training applications.
Market Restraints
- Display Panel Concentration:Advanced OLED and micro-OLED supply concentrates among Korean and Taiwanese component suppliers, creating input cost volatility for headset manufacturers.
- Motion Sickness Thresholds:Latency limitations in sub-premium sensor fusion implementations restrict session duration for sensitive users, capping engagement metrics.
- FDA Classification Friction:Software-as-medical-device thresholds create marketing constraints for rehabilitation-focused content targeting clinical end users in the United States.
Strategic Opportunities
- German Clinical Rehabilitation:Underpenetrated physical therapy applications in German-speaking markets offer expansion paths for FDA-cleared content seeking European CE marking reciprocity.
- Haptic Peripheral Integration:Convergence of resistance hardware with force-feedback gloves creates immersive strength-training experiences beyond cardio-centric current offerings.
- IRA Wellness Incentives:United States tax-advantaged health savings account eligibility for prescribed fitness technology expands addressable buyer base among employer-sponsored plans.
Industry Challenges
- Sensor Fusion Talent Scarcity:Specialized computer vision and IMU calibration expertise required for six-degrees-of-freedom tracking commands premium compensation, constraining studio hiring velocity.
- CE-MDR Dual Certification Timelines:European medical device regulation overlap with general product safety directives extends go-to-market timelines for rehabilitation content developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality Fitness Market |
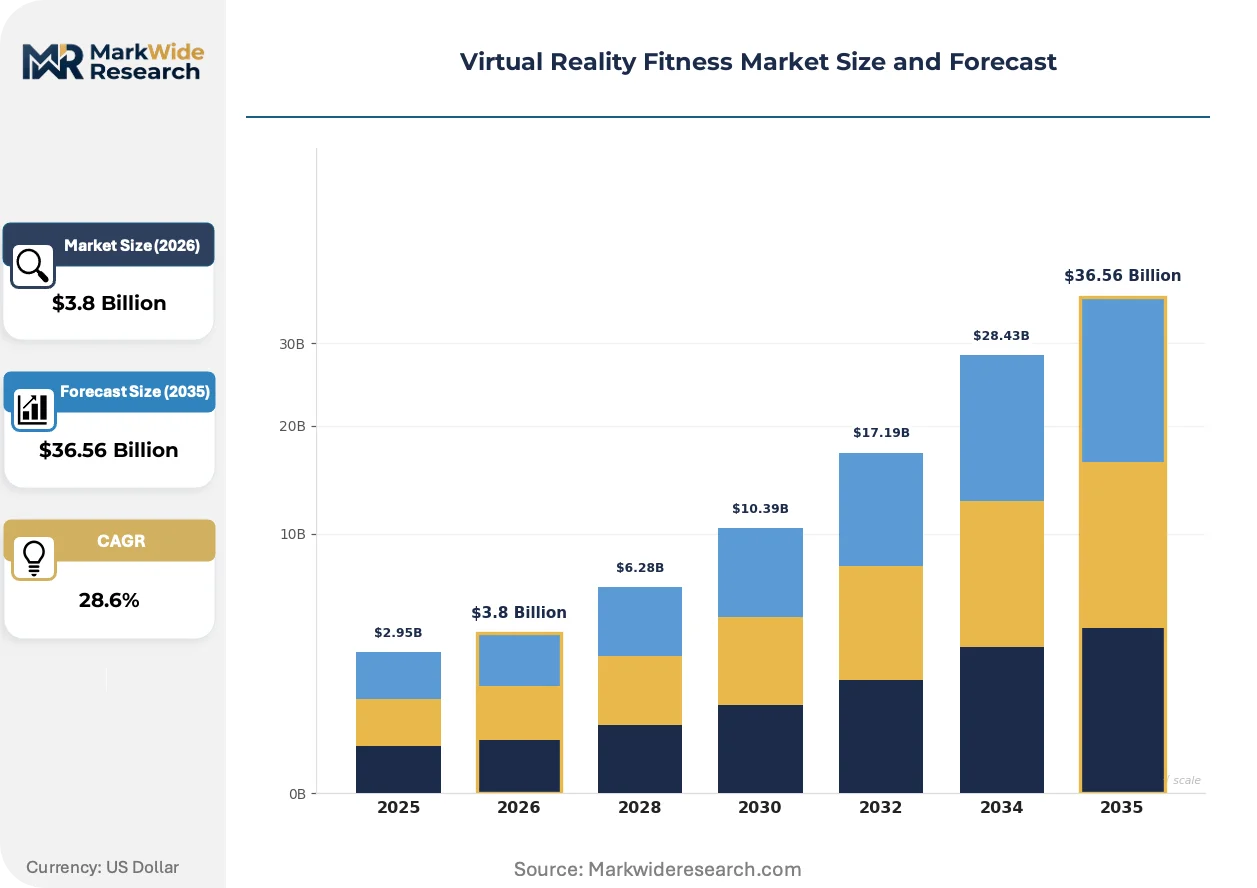
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Games, Applications, Fitness Equipment, Accessories End User: Personal Users, Gyms, Rehabilitation Centers, Corporate Wellness Technology: Motion Tracking, Haptic Feedback, Visual Displays, Audio Integration Distribution Channel: Online Retail, Physical Stores, Fitness Studios, Subscription Services |
| Companies Covered | FIIT, EGYM, FitXR, Pvolve, Echelon Fitness Multimedia, Supernatural, iFIT, Schell Games, Meta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality Fitness Market Trends and Innovations
Motion capture infrastructure is migrating from studio-owned hardware to cloud-based processing pipelines, altering cost structures and enabling smaller content creators to compete on production values previously reserved for well-capitalized incumbents.
Inside-out tracking systems using onboard cameras and machine-vision algorithms are decomposing the premium attached to external base station setups. Mid-tier headset manufacturers adopt these configurations to reduce total system cost for personal users. The shift compresses price differentiation between entry-level and enthusiast hardware tiers.
GDPR Article 9 special-category processing requirements and the EU AI Act's biometric identification classifications impose algorithmic audit obligations on European deployments. Studios must document fairness metrics and human oversight protocols for motion-derived health inferences. Rehabilitation applications face the steepest compliance burden, with some developers bifurcating product versions between clinical and consumer feature sets.
Subscription fatigue among digital fitness consumers is shortening evaluation windows and elevating cancellation friction as a retention priority. Studios respond with hybrid pricing that bundles hardware financing with content access, locking in twelve-to-twenty-four-month commitments. California and New York metropolitan clusters show the highest concentration of these bundled offerings, reflecting disposable income and early-adopter density.
Virtual Reality Fitness Market Segmentation
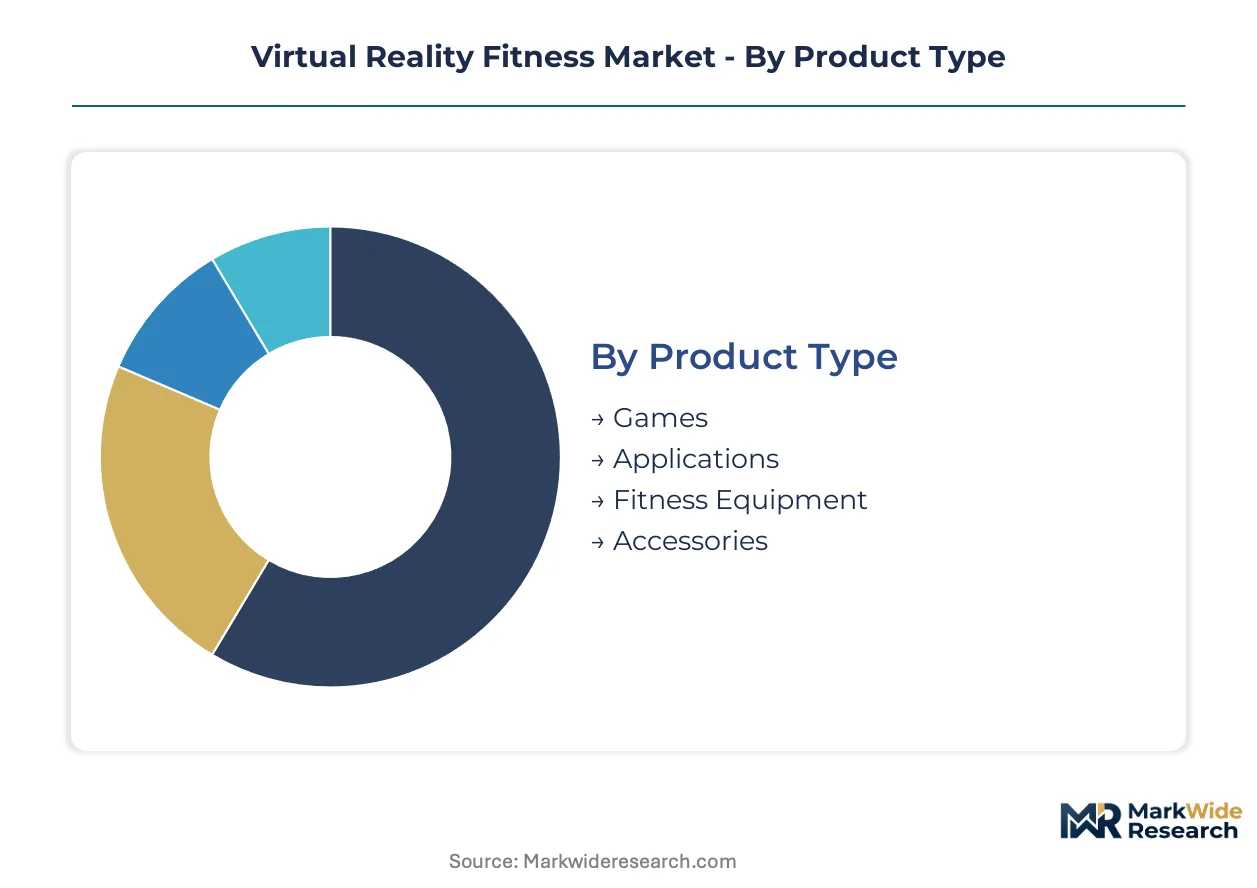
Segmentation in Virtual Reality Fitness reveals how regulatory frameworks, hardware economics, and user behavior patterns fragment addressable demand across distinct commercial pathways. Understanding these divides enables stakeholders to align product development with compliance requirements and purchasing modalities.
Product Type:
FDA software-as-medical-device thresholds and EU AI Act biometric classifications create divergent compliance burdens across product formats, reshaping where studios allocate development resources.
- Games:Gamified workout experiences leverage competitive mechanics and progression systems to sustain engagement. Demand concentrates among personal users in the United States seeking entertainment value alongside physical exertion, though FDA marketing constraints limit rehabilitation claims.
- Applications:Subscription-based fitness platforms deliver instructor-led classes and biomechanical feedback through recurring revenue models. California and New York metropolitan clusters show the highest concentration of these bundled offerings, reflecting early-adopter density and disposable income thresholds.
- Fitness Equipment:Dedicated resistance peripherals and haptic-enabled accessories.
- Accessories:Supplementary hardware including protective gear, charging stations, and storage solutions.
Applications handles the majority of throughput; Fitness Equipment is expanding most quickly on share.
End User:
Cost tier differentiation separates enterprise deployments with compliance departments from price-sensitive individual purchasers.
- Personal Users:Individual consumers purchasing for home-based workouts. Post-pandemic habit persistence drives headset adoption among users prioritizing location flexibility.
- Gyms:Commercial fitness facilities integrating VR stations into member offerings. These deployments require durable hardware specifications and multi-user sanitation protocols that elevate procurement costs.
- Rehabilitation Centers:Clinical environments deploying therapeutic movement programs. German-speaking markets offer expansion paths for FDA-cleared content seeking European CE marking reciprocity, though CE-MDR dual certification timelines extend go-to-market schedules.
- Corporate Wellness:Employer-sponsored fitness benefits integrated into health plans. United States tax-advantaged health savings account eligibility for prescribed fitness technology expands addressable buyer base among employer-sponsored plans.
Personal Users handles the majority of throughput; Rehabilitation Centers is gaining share fastest.
Technology:
Margin concentration follows patent-protected implementations that differentiate premium tiers from commodity alternatives.
- Motion Tracking:Six-degrees-of-freedom sensor fusion algorithms combining IMU data with computer vision. Patent-protected implementations command premium pricing and differentiate premium hardware tiers from basic accelerometer alternatives.
- Haptic Feedback:Force-feedback systems simulating resistance and tactile sensation. Convergence with resistance hardware creates immersive strength-training experiences beyond cardio-centric current offerings.
- Visual Displays:Stereoscopic rendering through OLED and micro-OLED panels. Korean and Taiwanese component supplier concentration creates input cost volatility for headset manufacturers.
- Audio Integration:Spatial audio systems enhancing immersion and instructor cue clarity.
Motion Tracking handles the majority of throughput; Haptic Feedback is climbing the fastest.
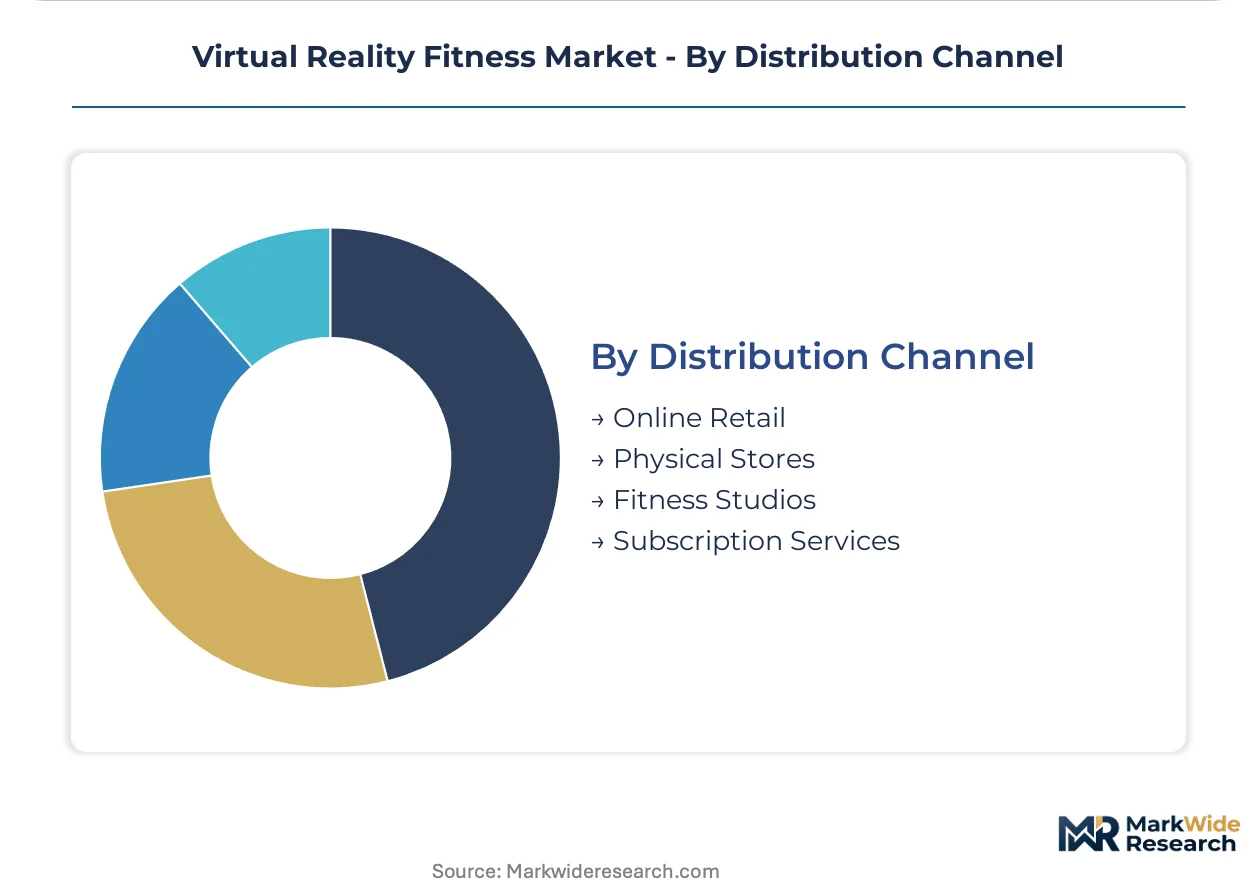
Distribution Channel:
Volume flows through direct-to-consumer pathways while physical retail retains importance for hardware trial and fit verification.
- Online Retail:E-commerce platforms and manufacturer-direct storefronts. These channels dominate hardware sales where specifications are standardized and fit uncertainty is low.
- Physical Stores:Brick-and-mortar electronics and sporting goods retailers. Trial experiences remain critical for headset fit verification and motion sickness sensitivity assessment.
- Fitness Studios:Location-based VR fitness facilities offering pay-per-session access.
- Subscription Services:Recurring content access bundled with hardware financing. Hybrid pricing models lock in twelve-to-twenty-four-month commitments, elevating cancellation friction as a retention priority.
Online Retail handles the majority of throughput; Subscription Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Personal users in the United States demonstrate the lowest price elasticity, absorbing bundled hardware-subscription premiums, while emerging-market buyers in India and Southeast Asia remain highly sensitive to upfront headset costs. European demand splits between GDPR-compliant premium tiers and stripped-down consumer versions. Hardware supply chains concentrate in East Asian component clusters, creating divergent landed costs across Atlantic and Pacific trade routes.
United States
Employer-sponsored wellness programs and health savings account eligibility expand the corporate buyer base beyond individual consumers. FDA software-as-medical-device thresholds constrain how rehabilitation-focused content reaches clinical end users, forcing feature bifurcation. California and New York metropolitan clusters host the densest concentration of subscription-based fitness studios and early-adopter personal users.
Germany
Physical therapy applications remain underpenetrated relative to the country's clinical infrastructure capacity. CE-MDR dual certification timelines extend go-to-market schedules for rehabilitation content developers seeking reciprocity with FDA-cleared platforms. Bavaria and North Rhine-Westphalia anchor medical device development clusters where studios navigate EU AI Act biometric audit obligations.
United Kingdom
Post-pandemic home workout habit persistence drives headset adoption among London and Southeast England professionals prioritizing location flexibility. The Information Commissioner's Office enforces GDPR Article 9 special-category processing requirements for motion-derived health inferences. Greater Manchester and Scotland host emerging fitness technology incubators targeting corporate wellness procurement.
China
Domestic headset manufacturers leverage local OLED and micro-OLED supply chains to compress production costs for price-sensitive personal users. MIIT wireless transmission standards govern standalone device connectivity, creating regulatory divergence from FCC protocols. Shenzhen and Beijing hardware ecosystems supply componentry to international brands while nurturing indigenous content studios.
South Korea
Advanced display panel manufacturing concentration among Korean suppliers creates input cost leverage over global headset assemblers. MFDS medical device classification frameworks shape how rehabilitation content enters clinical channels. Seoul Capital Area and Busan-Ulsan industrial corridors anchor both component supply and domestic VR fitness platform development.
Virtual Reality Fitness Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with ecosystem owners subsidizing hardware to capture recurring content revenue while independent studios compete on production velocity and exclusive intellectual property. The market structure consolidates around three strategic tiers: captive hardware-content ecosystems, pure-play content studios with exclusive distribution deals, and development specialists competing on release cadence. Dominant competitive moves include exclusive studio partnerships locking in choreography IP and hybrid pricing models bundling hardware financing with twelve-to-twenty-four-month content commitments.
Within the ecosystem-owner tier, Meta anchors hardware-install base economics that subsidize content acquisition and control distribution terms. Among pure-play content studios, FitXR and Schell Games exemplify divergent positioning strategies—FitXR securing exclusive choreography partnerships while Schell Games competes on development velocity with faster title release cycles. These three companies occupy positions that illustrate how capital asymmetry between hardware manufacturers and software creators defines current competitive pressure across the sector.
| Leading Market Players |
|---|
| FIIT |
| EGYM |
| FitXR |
| Pvolve |
| Echelon Fitness Multimedia |
| Supernatural |
| iFIT |
| Schell Games |
| Meta |
| Others |
Pricing and Supply Chain Analysis
FDA software-as-medical-device thresholds and EU AI Act biometric audit obligations gate both hardware qualification and subscription pricing tiers simultaneously, forcing studios to maintain parallel certification tracks that segment their addressable base by compliance burden rather than pure feature differentiation.
Pricing Analysis
Recurring subscription revenue and bundled hardware financing drive lifetime value across personal user segments. The dominant pricing structure combines SaaS-tiered content access with twelve-to-twenty-four-month hardware lease commitments, locking in predictable cash flows. Price differentiation rests on motion tracking precision tiers and GDPR compliance certification levels. Cost compression in mid-tier sensor fusion hardware intensifies as Chinese manufacturers enter the standalone headset space. Personal users in India and Southeast Asia exhibit the highest price sensitivity, while United States corporate wellness buyers absorb bundled premiums with minimal elasticity.
Supply Chain Analysis
Container availability constraints on Pacific trade lanes elevate inbound logistics costs for North American hardware assemblers sourcing from East Asian component hubs. Korean and Taiwanese suppliers dominate advanced OLED and micro-OLED display panel production, creating concentrated input dependencies for headset manufacturers. Critical components draw from South Korean sensor foundries, Chinese PCB fabrication facilities, and Taiwanese optical lens specialists. Single-source vulnerability in micro-OLED supply exposes assemblers to allocation rationing during demand spikes. Distribution runs through manufacturer-direct online storefronts for standardized hardware, with physical retail retaining importance for fit verification and motion sickness assessment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in switching costs: twelve-to-twenty-four-month hardware-subscription bundles create substantial exit friction that protects incumbent recurring revenue bases against pure-play content challengers.
For Market Incumbents: Consolidate exclusive choreography intellectual property through long-term studio partnerships that lock out competitors from premium content libraries. Deepen backward integration into motion tracking sensor calibration capabilities to reduce dependence on scarce computer vision talent pools. The emerging threat of cloud-based motion capture pipelines enabling smaller creators to match production values demands preemptive capacity investment in proprietary capture infrastructure. For New Entrants and Emerging Players: Differentiate on haptic peripheral integration for strength-training applications, a white-space segment underserved by current cardio-centric offerings. Target German rehabilitation centers seeking FDA-cleared content with CE-MDR reciprocity pathways, the most penetrable clinical geography given underpenetrated physical therapy infrastructure. Pursue direct-to-consumer pivots with hybrid pricing that decouples hardware financing from content subscriptions, avoiding exclusive distribution dependency on Meta's subsidized ecosystem. For Investors and Strategic Acquirers: EU AI Act biometric classification enforcement reshapes the acquisition landscape toward studios with documented algorithmic audit capabilities and human-in-the-loop protocols. Long-term viability favors targets with clinical-consumer product bifurcation experience that can navigate divergent regulatory thresholds without duplicative development overhead. Watch FDA software-as-medical-device threshold clarifications as the critical inflection signal determining whether rehabilitation content attracts medical device multiples or consumer software valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Studio Partnership | Locks in choreography IP that differentiates subscription tiers from commodity fitness content. |
| Haptic Peripheral Integration | Extends addressable demand beyond cardio into strength-training modalities with higher equipment attach rates. |
| CE-MDR Dual Certification | Opens German rehabilitation centers to FDA-cleared content through European medical device reciprocity pathways. |
| Cloud Motion Capture Pipeline | Reduces production cost barriers for smaller studios competing on visual fidelity with well-capitalized incumbents. |
| Hybrid Hardware-Subscription Bundling | Elevates cancellation friction through twelve-to-twenty-four-month commitments that protect recurring revenue bases. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with VR fitness studio executives, hardware procurement leads at headset manufacturers, physical therapy clinic administrators, corporate wellness benefit managers, and motion tracking algorithm engineers. Secondary validation drew from FDA 510(k) filings for software-as-medical-device classifications, EU AI Act implementation guidance documents, FCC wireless transmission standard updates, and SEC disclosures from publicly traded fitness technology platforms. Bottom-up unit economics modeling triangulated against top-down market sizing from component supply chain interviews.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, end user category, technology tier, and distribution channel. CAGRs were derived from installed base growth assumptions for standalone headsets, subscription renewal rate trajectories, and haptic peripheral attach rate penetration curves. Industry-specific forecast inputs included motion sickness tolerance thresholds affecting session duration metrics and GDPR Article 9 compliance cost estimates for European biometric data processing.
The analysis sits within stated boundaries; outcomes outside sustained post-pandemic home workout habit persistence, stable OLED panel supply allocation, and current FDA software-as-medical-device classification thresholds would require recalibration. Forecasts reflect documented assumptions regarding hardware subsidization sustainability by ecosystem owners and rehabilitation content regulatory clarity across Atlantic jurisdictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Smart Bike Trainers Market