
 Gym Accessories Market | 2026-2036
Gym Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Accessories Market Outlook
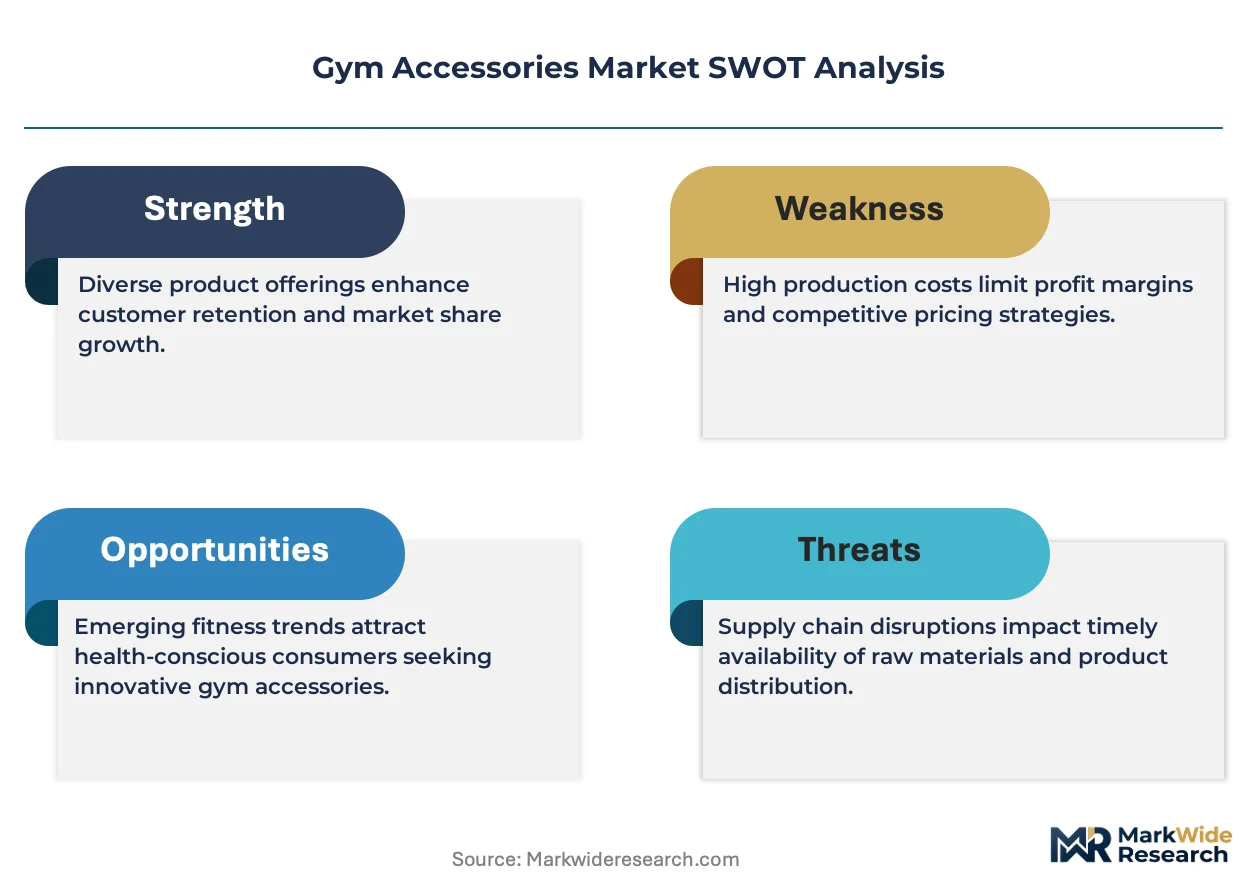
Premium-grade commercial specifications is rotating through the Gym Accessories Market as clubs and hotels replace entry-level inventory with certified performance equipment. Nike leverages its apparel-to-equipment ecosystem to sustain cross-category loyalty among institutional buyers. Rogue Fitness anchors its position through captive steel-forging operations in Ohio that supply Olympic barbell and rig manufacturing. Technogym competes on integrated digital-physical platforms that extend beyond hardware into subscription-based training protocols.
Gym accessories comprise auxiliary fitness equipment including resistance devices, protective gear, flooring systems, and load-bearing implements, typically manufactured from vulcanized rubber, high-density foam, cold-rolled steel, or woven synthetic textiles with specified tensile ratings and shore hardness values, designed to support strength training, flexibility protocols, and injury prevention in commercial, institutional, or residential exercise environments. Weights and resistance bands currently dominate volume shipments to commercial facilities, while mats and flooring solutions command higher margin pools due to specialized installation requirements and replacement cycles. Online retail channels are capturing share fastest among casual gym goers and beginners, though specialty stores retain structural importance for professional athletes seeking calibrated competition-grade equipment.
The US Consumer Product Safety Commission enforces flammability and mechanical safety standards that shape rubber and foam product formulations, while ASTM International protocols govern load-bearing equipment ratings that determine commercial gym procurement eligibility. ISO 20957 fixed training equipment standards create baseline compliance costs that filter smaller manufacturers from institutional supply chains. Stakeholders must monitor evolving state-level extended producer responsibility frameworks for synthetic material recycling, as these will increasingly determine which material platforms—rubber versus steel versus fabric—retain cost-competitive manufacturing pathways.
Market Dynamics
ISO 20957 fixed training equipment standards are compressing supplier eligibility for institutional procurement, filtering smaller rubber-composite manufacturers from commercial gym supply chains while elevating certified producers with captive testing facilities.
Growth Catalysts
- California's SB 54 extended producer responsibility framework:Mandatory synthetic material recycling quotas are accelerating demand for steel-alternative platforms in premium home-gym installations.
- Boutique fitness studio expansion:Specialized HIIT and Pilates chains are retrofitting flooring systems with vulcanized rubber composites certified to tightened durability benchmarks.
- Smart sensor integration:Load-bearing implements with embedded force measurement are capturing procurement budgets from traditional calibrated plates in commercial chain retrofits.
Market Restraints
- Petroleum-linked input volatility:Synthetic rubber and high-density foam formulations face margin pressure from feedstock price swings that resist hedging at mid-manufacturer scale.
- Ohio steel-forging concentration:Olympic barbell and rig manufacturing relies on a narrow geographic base of captive forging operations, creating supply vulnerability for North American institutional buyers.
- ASTM F1749-15(2020) calibration complexity:Competition-grade equipment certification timelines extend 14-18 months, freezing smaller producers out of professional athlete segments.
Strategic Opportunities
- Subscription-integrated hardware platforms:Training protocol software bundled with resistance devices is opening recurring revenue streams beyond one-time equipment sales.
- Texas and Florida sub-regional clusters:Premium home-gym density in exurban developments around Dallas-Fort Worth and Miami-Dade is outpacing national installation rates.
- US Consumer Product Safety Commission flammability rulemaking:Pending updates to 16 CFR Part 1632 for foam products will advantage manufacturers with pre-positioned compliant formulations.
Industry Challenges
- Shore hardness calibration technician scarcity:Qualified materials testing personnel for rubber-composite quality assurance are concentrated among legacy industrial suppliers, constraining new entrant scale-up.
- Legacy flooring removal and substrate preparation:Specialized installation requirements for replacement cycles in commercial facilities demand certified contractor networks that lag equipment manufacturing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Accessories Market |
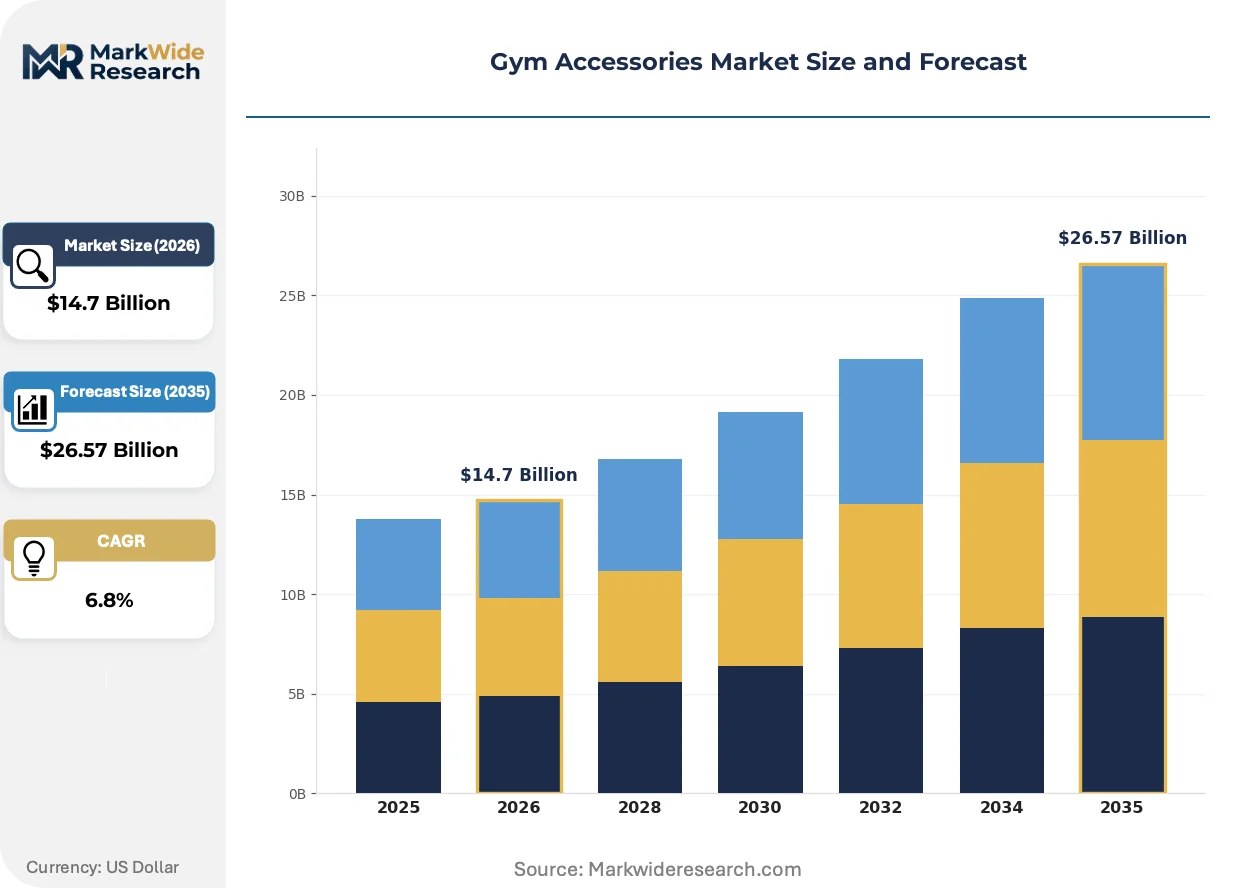
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weights, Mats, Bands, Gloves User Type: Professional Athletes, Casual Gym Goers, Fitness Enthusiasts, Beginners Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Material: Rubber, Foam, Steel, Fabric |
| Companies Covered | Nike, Life Fitness, Core Health & Fitness, Rogue Fitness, Technogym, Concept2, Adidas, Peloton Interactive, Body-Solid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Accessories Market Strategic Shifts
Digital-physical convergence is restructuring how gym accessories generate value, with hardware margins compressing while software-integrated platforms capture training data monetization. Material science advances and regulatory tightening are simultaneously reshaping manufacturing inputs and compliance architecture.
Modular rig systems with standardized connection interfaces are decomposing traditional fixed-installation gym layouts. Hotel fitness centers and corporate wellness facilities are adopting these reconfigurable platforms to accommodate rotating class formats without capital-intensive room rebuilds. The technology is decomposing the long replacement cycles that previously protected legacy flooring and rigging suppliers.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber products are forcing reformulation of vulcanized composites used in flooring and load-bearing implements. European boutique fitness chains are accelerating procurement from suppliers with pre-certified ECHA-compliant material platforms. North American exporters to EU institutional buyers must now maintain dual formulation inventories or abandon that channel entirely.
Certification-driven preference shifts are compressing supplier selection timelines for commercial procurement teams. Facility managers now prioritize ASTM- and ISO-documented equipment over price-competitive uncertified alternatives, even in budget-constrained retrofit scenarios. This behavioral change is most visible in United States multi-location fitness chains where liability exposure drives standardization across properties.
Gym Accessories Market Segmentation
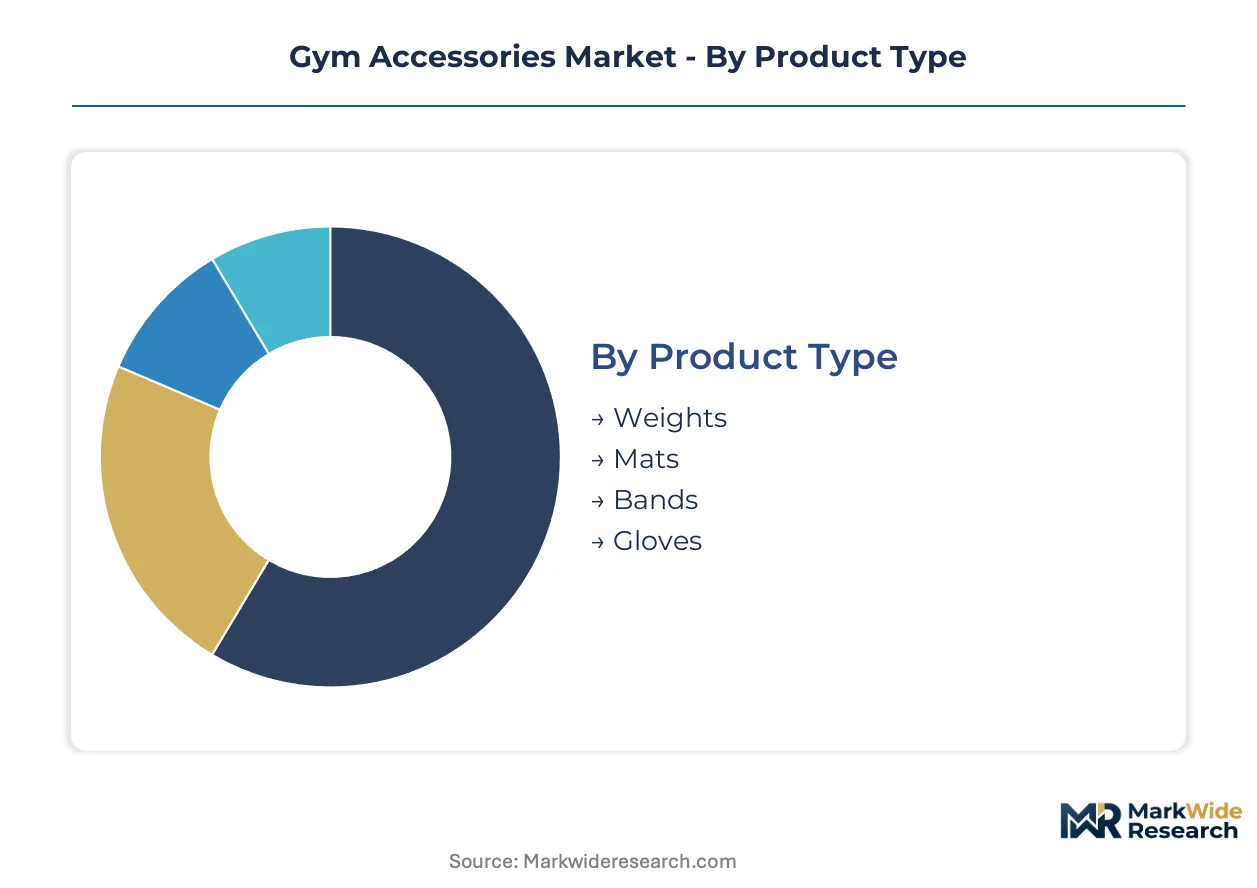
Segmentation in the Gym Accessories Market reveals how ISO 20957 compliance costs and ASTM calibration requirements reshape competitive positioning across product tiers. Material specifications and distribution economics create divergent margin structures that reward specialized supply chain configurations.
Product Type:
ASTM F1749-15(2020) calibration timelines and ISO 20957 durability benchmarks segment commercial eligibility, with certified producers capturing institutional procurement while uncertified alternatives serve residential price sensitivity.
- Weights:Olympic barbells and calibrated plates manufactured from cold-rolled steel with specified tensile ratings dominate commercial facility procurement budgets. Rogue Fitness anchors North American supply through captive Ohio forging operations that meet institutional load-bearing standards.
- Mats:Vulcanized rubber composites with shore hardness values certified to tightened durability benchmarks command premium margin pools due to specialized substrate preparation and replacement cycle complexity. Boutique fitness studios in California drive accelerated procurement as SB 54 recycling quotas reshape material formulation preferences.
- Bands:Resistance devices utilizing woven synthetic textiles with specified tensile ratings serve rehabilitation protocols and travel fitness applications where load precision matters less than portability.
- Gloves:Protective gear manufactured from leather and synthetic blends addresses grip security and callus prevention in high-repetition training environments.
Weights handles the majority of throughput; Mats is the fastest mover on share.
User Type:
Application intensity and certification requirements stratify procurement economics, with competition-grade equipment demanding 14-18 month calibration timelines that freeze casual purchasers out of professional supply chains.
- Professional Athletes:Competition-grade equipment seekers require ASTM-documented load ratings and ISO-certified manufacturing traceability. Specialty stores retain structural importance for this segment as online channels lack calibration documentation depth.
- Casual Gym Goers:Price-sensitive purchasers prioritize convenience over specification documentation, driving online retail channel capture. Entry-level resistance bands and uncertified weight sets satisfy intermittent training protocols without capital intensity.
- Fitness Enthusiasts:Dedicated home-gym installers in Texas and Florida sub-regional clusters demand mid-tier equipment with partial certification documentation. This segment balances performance credibility against budget constraints through direct-to-consumer brand relationships.
- Beginners:First-time purchasers exhibit highest channel fluidity, migrating between online retail promotional pricing and supermarket impulse displays before establishing brand loyalty.
Professional Athletes concentrates procurement value; Casual Gym Goers expands most quickly on volume.
Distribution Channel:
Customer sophistication and specification urgency determine channel economics, with certification documentation requirements and installation complexity creating structural advantages for physical retail in premium tiers.
- Online Retail:E-commerce platforms capture fastest share expansion among price-sensitive segments and geographic markets lacking specialty store density. Digital-physical convergence enables subscription-integrated hardware bundling that extends revenue beyond one-time equipment sales.
- Specialty Stores:Physical retail with certified staff and calibration documentation retains dominance for professional athlete and institutional buyer segments where liability exposure demands specification verification.
- Supermarkets:Mass retail channels serve impulse purchase occasions and beginner entry points with limited SKU depth and minimal technical support infrastructure.
- Direct Sales:Manufacturer-owned channels enable margin retention and customer data capture for premium home-gym installation segments requiring consultation-driven configuration.
Online Retail leads volume expansion; Specialty Stores anchors value concentration.
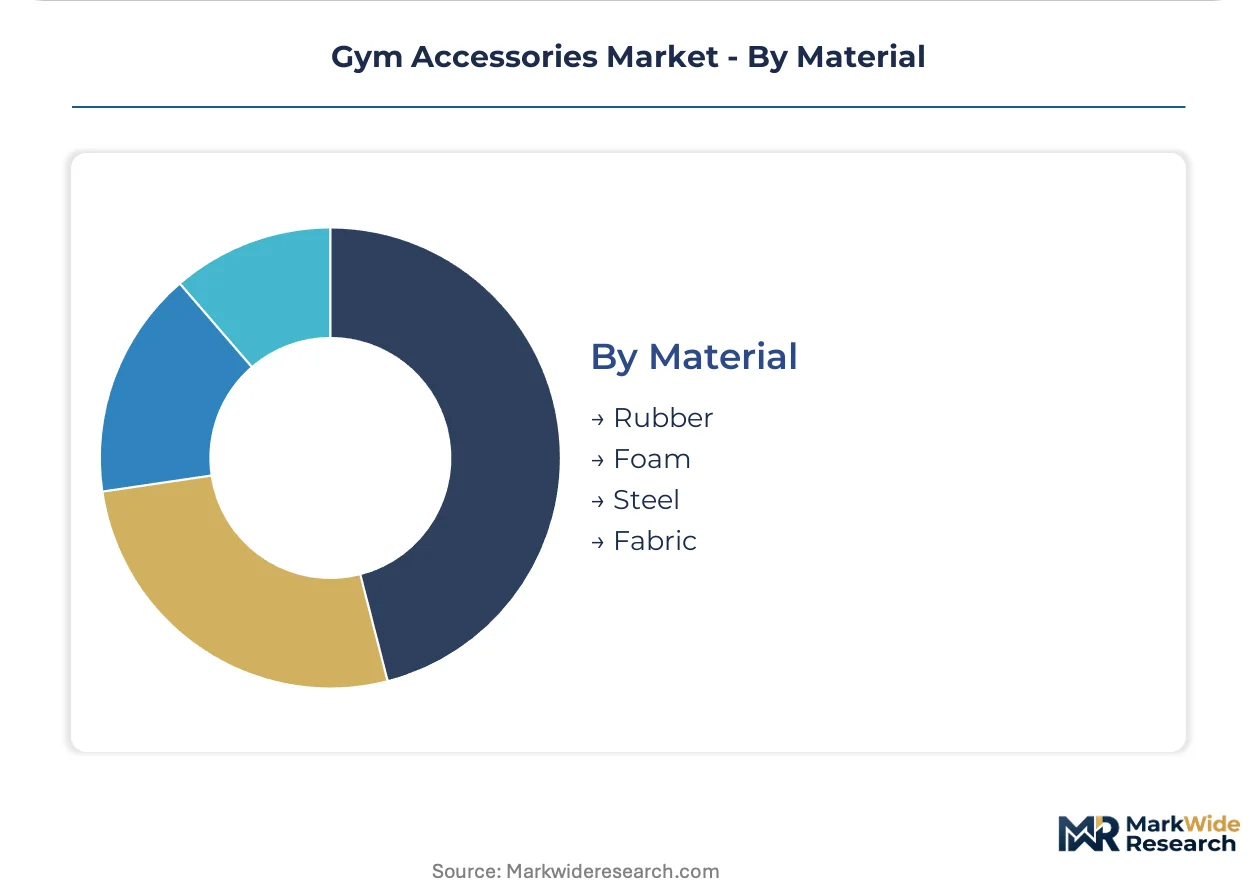
Material:
REACH Annex XVII restrictions and California SB 54 extended producer responsibility frameworks are forcing dual-formulation inventory strategies that reshape cost structures across rubber and steel alternatives.
- Rubber:Vulcanized composites face reformulation pressure from polycyclic aromatic hydrocarbon restrictions in EU markets. North American exporters must maintain ECHA-compliant inventories or abandon European boutique fitness procurement channels entirely.
- Foam:High-density formulations for protective gear and flooring systems confront US Consumer Product Safety Commission flammability rulemaking updates to 16 CFR Part 1632. Manufacturers with pre-positioned compliant formulations gain procurement preference in pending regulatory transitions.
- Steel:Cold-rolled and forged implements for load-bearing equipment concentrate production in Ohio captive operations, creating geographic supply vulnerability for North American institutional buyers.
- Fabric:Woven synthetic textiles with specified tensile ratings serve resistance band and glove manufacturing with lower regulatory compliance burden than rubber or foam alternatives.
Steel dominates commercial load-bearing applications; Rubber faces steepest regulatory transformation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in gym accessories tilt toward net-importing advanced economies while manufacturing concentrates in steel-forging and rubber-processing zones with established industrial infrastructure. The United States absorbs the largest import volume of premium certified equipment, offsetting domestic production concentrated in Ohio forging operations.
United States
Commercial chain retrofits and premium home-gym installations drive equipment procurement across Texas and Florida sub-regional clusters. The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1632 that shape foam and rubber product formulations. Dallas-Fort Worth and Miami-Dae exurban developments outpace national installation rates for mid-tier certified equipment.
Germany
Boutique fitness studio expansion in Berlin and Munich accelerates demand for REACH Annex XVII-compliant rubber flooring systems. ECHA restrictions on polycyclic aromatic hydrocarbons force reformulation of vulcanized composites used in load-bearing implements. The North Rhine-Westphalia industrial corridor hosts specialized calibration facilities serving competition-grade equipment procurement across the EU.
China
Export manufacturing of resistance bands and textile-based accessories serves price-sensitive segments in North America and Europe. GB standards administered by SAMR govern domestic product safety while dual carbon goals pressure energy-intensive steel forging operations. The Yangtze River Delta concentration of woven synthetic textile producers supplies global resistance device demand.
United Kingdom
Post-pandemic commercial gym reopenings in London and Manchester trigger flooring replacement cycles with ISO 20957-certified durability specifications. The Health and Safety Executive coordinates with ASTM International protocols for imported load-bearing equipment acceptance. Scotland's emerging boutique fitness chains source ECHA-compliant rubber composites through Dutch distribution hubs.
Japan
Aging-population rehabilitation protocols expand demand for low-load resistance devices in Tokyo and Osaka metropolitan areas. METI industrial standards and JIS certification requirements filter uncertified imports from regional supply chains. The Nagoya manufacturing belt concentrates precision steel processing for competition-grade barbell components serving domestic and export markets.
Gym Accessories Market Competitive Environment
Listed leaders compete with private specialists across certification depth and material integration capabilities. The vendor base stratifies into three tiers: apparel-to-equipment ecosystems with cross-category loyalty programs, captive manufacturing operators controlling upstream steel and rubber inputs, and digital-physical platform builders monetizing subscription protocols. Strategic moves concentrate on backward integration into forging and vulcanization capacity and geographic clustering around institutional procurement hubs.
Within the captive manufacturing tier, Rogue Fitness exemplifies vertical control through Ohio-based steel-forging operations. Nike represents the apparel-to-equipment ecosystem archetype with cross-category institutional buyer relationships. Technogym occupies a position on the digital-physical convergence vector, bundling hardware with subscription-based training protocols.
| Leading Market Players |
|---|
| Nike |
| Life Fitness |
| Core Health & Fitness |
| Rogue Fitness |
| Technogym |
| Concept2 |
| Adidas |
| Peloton Interactive |
| Body-Solid |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month ASTM F1749-15(2020) calibration timelines concentrate pricing power among certified producers with captive testing facilities, while uncertified manufacturers compete on speed-to-delivery for residential segments. This lead-time differential separates institutional procurement budgets from price-sensitive home-gym installations, with ISO 20957 compliance costs filtering smaller rubber-composite suppliers from commercial gym supply chains entirely.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with competition-grade equipment commanding substantial premiums for ASTM-documented load ratings and ISO-certified manufacturing traceability. Price differentiation hinges on certification grade and volume scale, with boutique fitness studios absorbing higher per-unit costs for specialized flooring systems while casual gym goers drive price erosion through online retail channels. Pricing pressure stems from petroleum-linked input volatility in synthetic rubber formulations, squeezing margins at mid-manufacturer scale. Casual gym goers exhibit highest price sensitivity, while professional athletes and institutional buyers demonstrate inelastic demand for documented compliance.
Supply Chain Analysis
Inventory cycles for cold-rolled steel implements stretch longer than rubber-composite lead times, with Olympic barbell and rig manufacturing concentrated in Ohio captive forging operations. Geographic supply concentration centers on the United States for load-bearing steel equipment, China for woven synthetic textile resistance devices, and Germany for REACH Annex XVII-compliant rubber formulations. Raw material dependencies rest on petroleum-derived synthetic rubber, high-density foam feedstocks, and cold-rolled steel billets. Single-source vulnerability pervades the Ohio steel-forging base, creating supply risk for North American institutional buyers. Distribution runs through specialty stores for certified equipment and online retail for entry-level segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among multi-location fitness chains and boutique studio networks, with procurement standardization across properties reducing supplier count and amplifying price negotiation leverage for certified equipment.
For Market Incumbents: Secure backward integration into vulcanized rubber composite production or captive steel-forging capacity to defend margin position against petroleum-linked input volatility and Ohio supply concentration risk. Invest in ISO 20957 testing facility expansion to accelerate calibration timelines and freeze out smaller competitors from institutional procurement cycles. Prioritize subscription-integrated hardware platforms that extend revenue beyond one-time equipment sales and create switching costs for boutique fitness studio clients. For New Entrants and Emerging Players: Lead with digital-physical convergence offerings targeting fitness enthusiasts in Texas and Florida sub-regional clusters, where premium home-gym density outpaces national installation rates and mid-tier equipment demand exceeds certified supply. Exploit the white space in modular rig systems with standardized connection interfaces for hotel fitness centers and corporate wellness facilities seeking reconfigurable platforms. Deploy direct-to-consumer brand relationships with consultation-driven configuration to bypass specialty store channel control. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 20957 compliance costs and ASTM calibration complexity are structurally filtering smaller rubber-composite manufacturers from commercial gym supply chains, creating acquisition targets among distressed mid-tier producers. Target vertically integrated operators with captive testing facilities and ECHA-compliant material platforms for European market access. Watch California SB 54 extended producer responsibility enforcement as the signal for which material platforms—steel versus rubber versus fabric—retain cost-competitive manufacturing pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Steel-Forging Expansion | Ohio-based operations insulate Rogue Fitness from supply vulnerability and anchor institutional procurement relationships. |
| ECHA-Compliant Rubber Reformulation | REACH Annex XVII pre-certification enables North American exporters to maintain European boutique fitness channel access. |
| Subscription-Integrated Hardware Launch | Technogym bundles load-bearing implements with training protocol software to capture recurring revenue streams. |
| Modular Rig System Development | Standardized connection interfaces decompose fixed-installation gym layouts for hotel and corporate wellness retrofit demand. |
| Specialty Store Channel Deepening | Certified staff and calibration documentation retain structural importance for professional athlete segments where liability exposure demands specification verification. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association publications, with insights drawn from interviews with gym equipment procurement managers, boutique fitness studio operators, rubber composite plant engineers, and ASTM calibration facility technicians. Secondary validation sources include US Consumer Product Safety Commission flammability standards documentation, ISO 20957 fixed training equipment protocols, ECHA REACH Annex XVII restriction updates, and SEC filings from listed fitness equipment manufacturers. Bottom-up demand modeling triangulates against top-down market sizing across product type, user segment, distribution channel, and material composition dimensions.
Segmentation dimensions modeled encompass product type (weights, mats, bands, gloves), user archetype (professional athletes, fitness enthusiasts, casual gym goers, beginners), distribution channel (online retail, specialty stores, supermarkets, direct sales), and material platform (rubber, foam, steel, fabric). CAGRs derive from historical shipment volume analysis projected through the analysis window, with growth assumptions calibrated to boutique fitness studio expansion rates, premium home-gym installation density in Texas and Florida sub-regional clusters, and smart sensor integration adoption curves in commercial chain retrofits.
Underlying assumptions cover sustained petroleum-linked input volatility, ISO 20957 standard enforcement continuity, and California SB 54 recycling quota implementation, with deviation risk concentrated in REACH Annex XVII expansion to additional rubber composite categories and Ohio steel-forging supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Home Gym Equipment Market