
 Smart Sports Equipment Market | 2026-2036
Smart Sports Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sports Equipment Market Intelligence
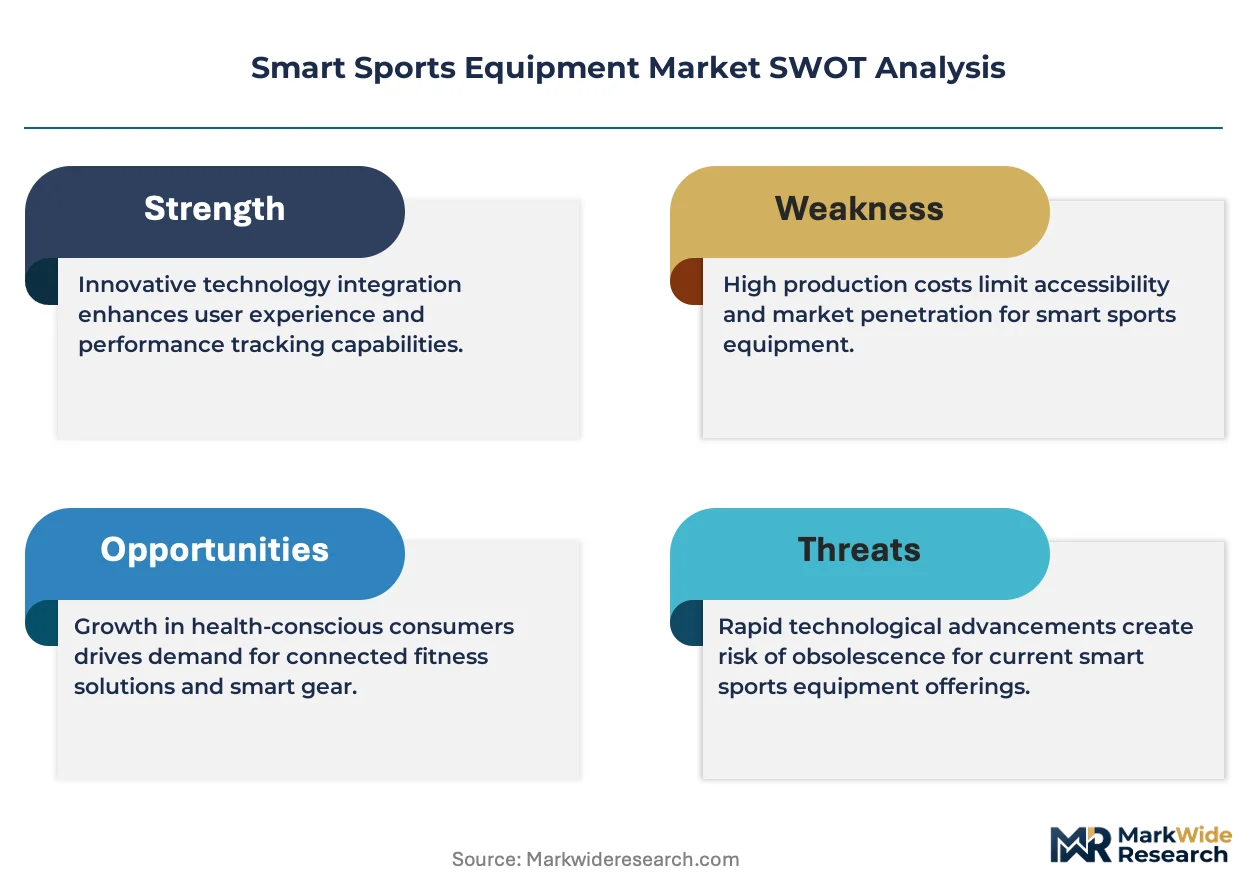
The EU's Ecodesign for Sustainable Products Regulation, emphasizing device longevity, is expanding design considerations for smart sports equipment. Garmin leverages its extensive portfolio in GPS and wearable technology across both consumer and professional markets. WHOOP differentiates with a subscription-based model focused on recovery and strain monitoring. Catapult sustains its leadership in the elite team sports analytics segment through sophisticated player tracking systems.
Smart sports equipment refers to athletic gear embedded with electronic sensors, microprocessors, and connectivity modules like Bluetooth or RFID. These devices often incorporate accelerometers and biometric sensors to capture kinematic and physiological data during physical activity. Their primary function is providing athletes and coaches with objective, real-time performance feedback. Wearable devices represent the largest product type, while applications in performance monitoring and data analysis show significant uptake among professional athletes and sports academies.
Product compliance is shaped by multiple frameworks, including FCC regulations in the United States for radio frequency emissions and CE marking in Europe for safety standards. Data privacy is a critical consideration, with regulations like the EU's GDPR dictating how personal athletic data is collected, stored, and managed. Future competitive advantage will depend on integrating advanced AI analytics while navigating a complex landscape of international data privacy and device interoperability standards.
Market Dynamics
The convergence of consumer-driven wellness tracking with the data demands of elite athletics defines the market's structure. This dual-demand dynamic is shaped by sensor miniaturization, which enables new applications, and data privacy frameworks like GDPR that govern their use.
Growth Catalysts
- Maturing Sensor Technology:The increased sophistication and lower power requirements of Bluetooth and IoT sensors enable more accurate, real-time kinematic and physiological data capture, expanding feasible product applications.
- Professional Sports Adoption:Intense competition among professional franchises and NCAA athletic programs drives investment in performance analytics tools to gain a competitive edge in training, strategy, and injury prevention.
- Public Health Initiatives:Government and WHO-endorsed campaigns promoting physical activity and preventative health indirectly stimulate demand for consumer-grade smart equipment that helps individuals monitor their fitness goals.
Market Restraints
- High Initial Investment:The significant upfront cost of comprehensive, team-based player tracking systems remains a substantial barrier for semi-professional leagues, smaller colleges, and amateur sports organizations.
- Data Privacy Compliance:Navigating disparate data protection regulations, such as Europe's GDPR and the US's HIPAA, creates legal and operational complexity for companies handling sensitive personal athletic data.
- Interoperability Standards:A lack of universally accepted data communication protocols among different manufacturers' devices creates a fragmented ecosystem, hindering seamless data aggregation for athletes using multiple products.
Strategic Opportunities
- Youth and Amateur Sports:Significant white space exists in equipping youth leagues and amateur clubs in markets like Brazil and India, where grassroots adoption of performance technology lags behind professional-level interest.
- Corporate Wellness Programs:Device data on strain, recovery, and sleep can be repurposed for corporate wellness platforms, creating a new B2B sales channel focused on employee health and productivity.
- Predictive Injury Analytics:Integrating AI and machine learning to analyze longitudinal data offers the potential to move from descriptive performance tracking to predictive modeling of injury risk and optimal recovery.
Industry Challenges
- Complex Regulatory Approvals:Each new product must navigate a multi-layered compliance landscape, including FCC regulations for radio emissions in the United States and CE marking for safety in the European Union.
- Cybersecurity Threats:Protecting sensitive biometric and performance data from theft or manipulation is a critical operational challenge, as a single high-profile data breach could severely damage consumer trust.
- Data Integration Burden:Coaches and athletes face difficulty integrating new streams of sensor data into established training methodologies and software platforms without creating information overload and workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sports Equipment Market |
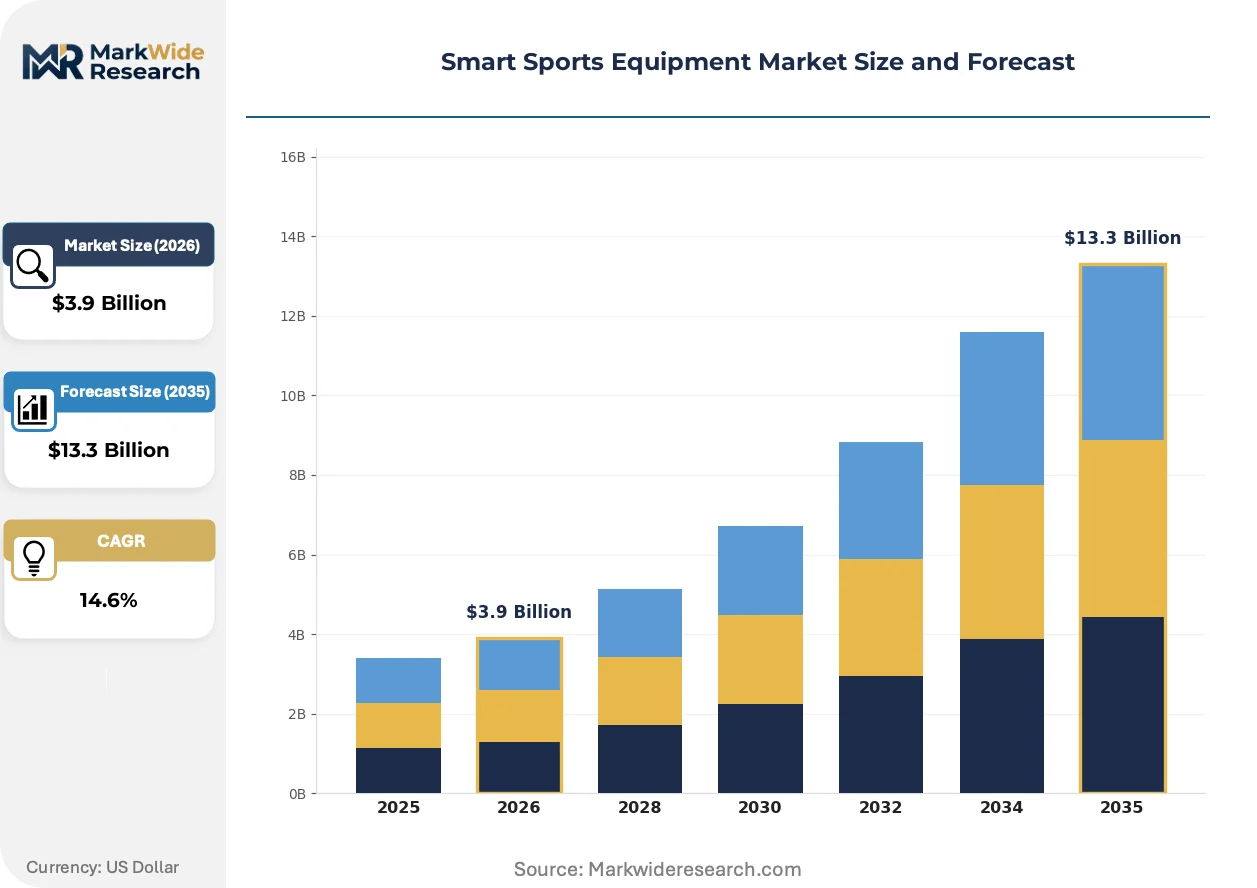
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $13.3 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Balls, Fitness Trackers, Connected Gear Technology: IoT, Bluetooth, RFID, Cloud Computing Application: Training, Performance Monitoring, Injury Prevention, Data Analysis End User: Athletes, Coaches, Fitness Enthusiasts, Sports Academies |
| Companies Covered | Hudl, Nextiles, Garmin, Apple, Proteus Motion, WHOOP, Plantiga, Samsung, Catapult, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sports Equipment Market Strategic Shifts & Innovations
Personalization is the central theme, with AI-driven analytics converting raw sensor data into actionable training and recovery advice. Concurrently, regulatory forces like the EU's Ecodesign directive are compelling manufacturers to prioritize hardware longevity and sustainability in their product development cycles.
Embedded fabric sensors woven directly into athletic apparel are designed to capture biomechanical and physiological data without requiring discrete devices. Professional teams and sports science institutes are the primary adopters, seeking more naturalistic data capture during competition. This development is modularizing the smart equipment ecosystem, unbundling sensor function from a specific device like a watch or chest strap.
Sustainability regulations are influencing hardware design. The EU's Ecodesign for Sustainable Products Regulation mandates design for durability, repairability, and battery replaceability, challenging short-lifecycle models. Manufacturers targeting the European market are re-evaluating material selection and assembly processes to comply with these new longevity standards.
Subscription-based business models are gaining traction over one-time hardware sales. This shift provides athletes with continuous software updates, personalized coaching, and community features while giving companies a recurring revenue stream. The trend is most visible in the wearable device segment within the United States and Western Europe, where consumers readily embrace software-as-a-service offerings.
Smart Sports Equipment Market Segmentation
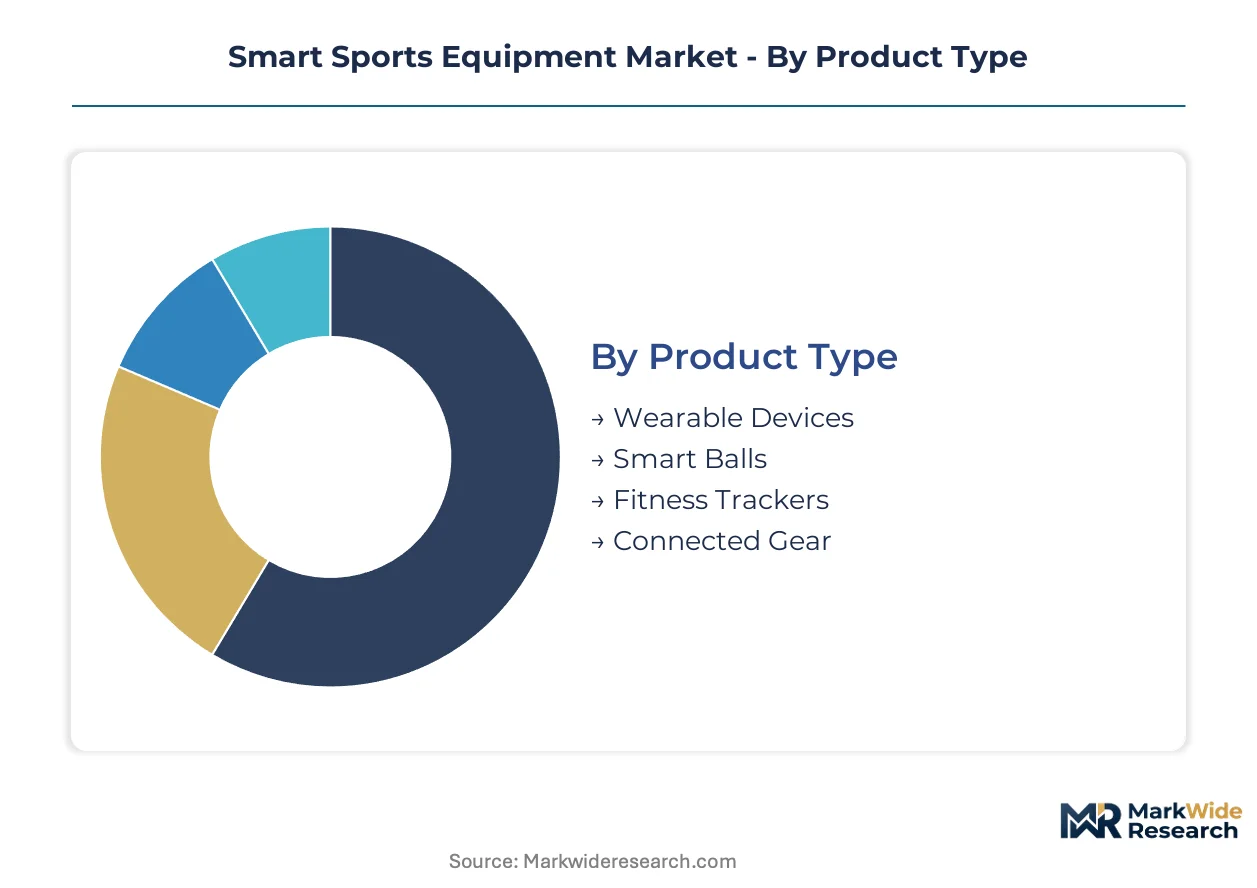
Understanding the varied segments within the smart sports equipment market is crucial for product development and market penetration strategies. This granular breakdown helps identify specific user needs, technological preferences, and regulatory considerations across diverse applications. Each segment possesses unique characteristics that influence its growth trajectory and competitive dynamics.
Product Type:
Product types face varying regulatory hurdles; for instance, devices with radio frequency emissions like wearable devices require FCC certification in the United States, while others like smart balls primarily focus on CE marking for safety in Europe.
- Wearable Devices:These devices, often integrated into clothing or worn as accessories, capture biometric and kinematic data through embedded sensors. Demand concentrates in the United States, driven by fitness enthusiast communities and professional sports leagues seeking real-time performance feedback.
- Smart Balls:Equipped with internal sensors, these specialized sports balls track parameters like speed, spin, and trajectory, providing objective data for skill development. Their adoption is significant in sports academies and professional training environments, particularly in European football and American basketball.
- Fitness Trackers:These devices primarily monitor basic health metrics like steps, calories, and sleep, catering to general wellness and public health initiatives.
- Connected Gear:This category includes equipment like smart rackets and golf clubs, integrating sensors to analyze specific sport-related movements and provide technique feedback.
Wearable Devices sits at the top of the volume ranking, with Connected Gear climbing the fastest.
Technology:
The underlying technology often dictates the range of applications supported, from real-time data streaming for immediate feedback to long-term data storage solutions for historical analysis.
- IoT:IoT integration enables seamless data transfer from smart equipment to cloud platforms for advanced analytics and remote monitoring, facilitating comprehensive athlete management. Professional sports organizations in the United States leverage IoT for large-scale player tracking and strategic insights.
- Bluetooth:Low-power Bluetooth connectivity is fundamental for short-range wireless communication between devices and smartphones, enabling immediate data synchronization and user interaction. Its widespread adoption in consumer wearables across Western Europe simplifies data access for individual athletes.
- RFID:RFID tags are primarily used for asset tracking and inventory management of equipment, ensuring efficient logistics in large sports facilities.
- Cloud Computing:Cloud computing provides scalable infrastructure for storing, processing, and analyzing vast amounts of athletic performance data, supporting AI-driven insights and personalized coaching.
IoT technology is seeing broad enterprise adoption, while Bluetooth remains critical for consumer-grade devices.
Application:
Different applications cater to distinct customer needs, ranging from individual fitness enthusiasts to elite professional sports organizations, each demanding specific functionalities from their smart equipment.
- Performance Monitoring:This application focuses on objective measurement of an athlete's physical output, technique, and physiological responses, providing data for optimization. Professional teams globally rely on this for competitive advantage and strategic planning.
- Training:Smart equipment in this segment provides interactive guidance and structured programs to improve specific skills or fitness, often incorporating real-time feedback loops. Sports academies in India and Brazil are increasingly integrating these tools for athlete development.
- Injury Prevention:Utilizing biometric and kinematic data, these applications identify patterns indicating elevated injury risk, allowing for proactive interventions and workload management.
- Data Analysis:This involves sophisticated processing of raw sensor data using AI and machine learning to extract actionable insights for coaches, athletes, and sports scientists.
Performance Monitoring applications are directly enhancing athlete development, with Injury Prevention gaining traction for long-term athlete welfare.
End User:
The maturity level of end-users influences the sophistication of equipment demanded, from basic fitness tracking for novices to advanced analytics for seasoned professionals requiring granular data.
- Athletes:This segment includes individual athletes from amateur to professional levels who use smart equipment for personal performance tracking, skill improvement, and fitness. Professional athletes in major US sports leagues are significant consumers of advanced wearable technology.
- Coaches:Coaches utilize smart equipment to monitor team performance, assess individual player development, and inform strategic decisions during training. Collegiate athletic programs across North America depend on these tools for talent assessment.
- Fitness Enthusiasts:Individuals focused on general health and wellness use smart equipment to track daily activity, monitor fitness progress, and stay motivated.
- Sports Academies:These institutions adopt smart equipment to enhance training methodologies, identify talent, and provide data-driven insights for developing athletes.
Professional Athletes drive significant investment in advanced equipment, as Sports Academies increasingly adopt technology for talent development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smart sports equipment market thrives on concentrated athletic talent and advanced technology development across key regions. Professional sports organizations and research hubs drive demand for sophisticated data capture and analysis tools. This regional distribution reflects varying adoption rates and regulatory landscapes.
United States
Professional sports franchises and fitness enthusiast communities drive substantial demand for smart sports equipment. FCC regulations govern radio frequency emissions for connected devices, ensuring product compliance. Technology hubs like Silicon Valley, California, foster innovation in sensor and data analytics platforms.
Germany
European football clubs and sports science research institutions generate demand for advanced player tracking systems. CE marking ensures product safety, while GDPR dictates stringent data privacy standards for personal athletic data. Munich's robust engineering sector supports the development of precision smart sports equipment.
India
Sports academies and a burgeoning fitness-conscious population contribute to the expanding market for training aids. The country's national health initiatives indirectly stimulate consumer-grade smart equipment adoption. Technology centers in Bangalore integrate AI analytics for personalized coaching and performance feedback.
Brazil
Youth leagues and professional football academies exhibit strong interest in performance monitoring and skill development tools. Government initiatives promoting physical activity foster demand for accessible smart fitness devices. São Paulo's vibrant startup ecosystem supports localized development of smart sports equipment solutions.
Japan
Advanced sports science research and elite athlete development programs drive demand for precision equipment. METI guidelines influence data management practices for personal health and performance metrics. Tokyo's strong electronics industry supports the innovation and miniaturization of smart sensor technology.
Smart Sports Equipment Market Key Industry Players
Capital-heavy hardware manufacturers compete with asset-light software and data analytics providers in the smart sports equipment market. This creates a tiered structure where established electronics brands coexist with specialized sports tech startups. Two strategic archetypes dominate: integrated solution providers offering end-to-end ecosystems, and niche innovators focusing on specific data capture or analysis. Strategic partnerships and portfolio diversification represent dominant competitive moves among market participants.
Specialists in performance monitoring and recovery analytics, such as Garmin, exemplify integrated hardware-software ecosystems for both consumer and professional users. WHOOP occupies a distinct position with its subscription-based model, primarily focusing on physiological recovery and strain management. Catapult, a provider of sophisticated player tracking systems, anchors the elite team sports analytics segment. These companies represent different approaches to leveraging sensor data for athletic improvement and competitive advantage.
| Leading Market Players |
|---|
| Hudl |
| Nextiles |
| Garmin |
| Apple |
| Proteus Motion |
| WHOOP |
| Plantiga |
| Samsung |
| Catapult |
| Others |
Cost & Logistics Intelligence
Sensor component costs, particularly for miniaturized biometric and kinematic sensors, significantly influence the final pricing tiers for smart sports equipment from manufacturing to consumer sales. This cost factor then shapes the investment decisions for product development and market entry points across different user segments.
Pricing Analysis
Subscription-based service models, rather than unbundled hardware sales, increasingly dominate the market for smart sports equipment, especially in wearable devices. Price differentiation stems from advanced AI analytics capabilities and the level of personalized coaching and recovery insights offered. Pricing pressure stems from increasing competition in the consumer wellness segment, where basic fitness trackers offer lower-cost alternatives. Professional sports organizations demonstrate the lowest price sensitivity, prioritizing performance gains, while fitness enthusiasts exhibit higher price sensitivity for advanced features.
Supply Chain Analysis
Single-source vulnerability sits with specialized sensor manufacturers, particularly those producing low-power Bluetooth and IoT components. Geographic supply concentration for these microelectronics primarily centers in Taiwan, South Korea, and China. Raw material dependencies include rare earth elements for sensor fabrication and specialized polymers for device casings. Regulatory restrictions on technology exports represent a structural supply chain risk. Downstream distribution runs through established electronics retailers and direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU's Ecodesign for Sustainable Products Regulation driving demand for more durable and repairable smart equipment designs. This regulatory push encourages innovation in product lifecycle management.
For Market Incumbents: Deploy strategic portfolio diversification to mitigate competitive threats from niche startups. Invest in advanced AI analytics to maintain a technological edge against emerging data platforms. Develop repairable and modular product lines to comply with evolving sustainability regulations like the EU's Ecodesign directive, extending hardware longevity. Secure key component supply agreements to reduce reliance on volatile spot markets.
For New Entrants and Emerging Players: A price-point gap exists between premium professional-grade systems and basic consumer fitness trackers, offering an entry opportunity. Target youth leagues and amateur sports organizations in underserved markets like Brazil and India, where grassroots adoption of performance technology lags. A go-to-market angle focusing on accessible, real-time technique feedback for skill development can capture early market share.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized data analytics capabilities meet hardware manufacturing expertise, favoring integrated solution providers. Long-term viability over a 5-10 year window favors companies that can scale AI-driven predictive analytics for injury prevention. Acquisition targets should include firms with robust data privacy frameworks and strong intellectual property in fabric-integrated sensors. The signal to watch is the widespread adoption of interoperability standards, which will unlock new data aggregation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Predictive Analytics | This initiative converts raw sensor data into actionable insights for injury prevention and performance optimization, enhancing athlete welfare. |
| Develop Fabric-Integrated Sensors | Embedding sensors directly into apparel captures naturalistic biomechanical data, improving comfort and accuracy for professional athletes. |
| Expand Subscription-Based Services | This model provides recurring revenue streams and fosters continuous engagement through software updates and personalized coaching. |
| Invest in Sustainable Product Design | Prioritizing durability and repairability aligns with Ecodesign regulations, reducing environmental impact and enhancing brand reputation. |
| Form Strategic Partnerships with Sports Academies | Collaborating with training institutions provides direct access to athlete data for product refinement and market penetration in developing regions. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary data validation. We engaged with diverse stakeholders, including sports scientists, professional coaches, equipment manufacturers' R&D leads, and athletic program directors. Secondary sources included FCC filings, CE marking documentation, academic sports science journals, and national health initiative reports. This approach facilitated both bottom-up and top-down triangulation of market data.
The analytical framework anchored the forecast window to comparable historical reference periods, building a robust model for market projections. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived from a multi-factor regression analysis, incorporating technology maturation curves and professional sports investment trends. Key industry-specific forecast inputs included sensor miniaturization rates and sports league technology adoption budgets.
Caveats apply where shifts in international data privacy regulations or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding continued investment in sports science and stable economic conditions in key markets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Smart Fitness Market