
 UK Gym Accessories Market | 2026-2036
UK Gym Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
UK Gym Accessories Market Insights
Aftermarket service revenue for gym accessory refurbishment and recalibration is reconfiguring how UK manufacturers capture lifetime customer value. Jordan Fitness leverages its domestic manufacturing base to control replacement parts distribution. Physical Company sustains competitive positioning through specialty retail partnerships across England's boutique fitness chains. Watson Gym Equipment anchors its brand in the premium commercial segment with bespoke steel fabrication capabilities.
UK gym accessories encompass portable and fixed equipment designed for resistance, flexibility, and cardiovascular training, typically manufactured from vulcanized rubber, cast iron, or thermoplastic elastomers with load ratings certified for commercial use. Their primary commercial purpose is to enable progressive overload and movement variation in spaces where large machine-based circuits prove impractical. Dumbbells and kettlebells occupy the core revenue pool due to universal application across strength protocols, while resistance bands represent the fastest-expanding category as physiotherapy clinics integrate them into post-operative rehabilitation programmes. Distribution through specialty stores retains margin density, though online retailers are capturing volume growth from home gym setups.
BIS standards govern product safety and material composition for rubber-based accessories sold in the UK market, while the Office for Product Safety and Standards monitors compliance with weight tolerance and structural integrity requirements. These frameworks elevate manufacturing costs for imported goods but simultaneously protect domestic producers from substandard competition. Stakeholders must monitor how post-Brexit conformity assessment procedures reshape supplier access and certification timelines.
Market Dynamics
Boutique fitness studios and independent personal trainers are expanding equipment procurement budgets, while the Office for Product Safety and Standards enforces stricter durability standards for rubber-coated free weights. This tension between demand expansion and compliance elevation defines current market structure.
Growth Catalysts
- Boutique Studio Expansion:Small-format fitness operators across Greater London and Manchester are increasing capital expenditure on portable resistance equipment. These buyers prioritize space-efficient configurations over traditional machine-based circuits.
- REACH Compliance:EU-derived chemical safety standards for vulcanized rubber components are filtering into UK procurement specifications. Buyers now demand certified material composition documentation from all suppliers.
- Physiotherapy Integration:Post-operative rehabilitation programmes in NHS trusts and private clinics are standardizing resistance band protocols. This clinical adoption creates institutional demand pull distinct from commercial gym procurement.
Market Restraints
- Cast Iron Price Volatility:Foundry energy costs and scrap metal input fluctuations compress margin predictability for dumbbell and kettlebell manufacturers. Domestic producers face squeezed working capital cycles.
- Asian Supply Concentration:Thermoplastic elastomer sourcing remains concentrated in East Asian polymer processors. UK manufacturers carry inventory risk from extended maritime lead times and currency exposure.
- Substitution by Bodyweight Training:Calisthenics coaching methodologies reduce equipment dependency for certain strength protocols. Free digital programming accelerates this displacement in home gym segments.
Strategic Opportunities
- Scottish Wellness Corridors:Edinburgh and Glasgow exhibit underpenetrated boutique fitness density relative to population concentration. First-mover equipment suppliers can anchor regional distribution partnerships.
- Sensor-Embedded Wearables Convergence:Integration of load-cell technology into traditional free weights enables rep-tracking and form-feedback. This hybrid category commands premium positioning in personal training studios.
- Extended Producer Responsibility:Anticipated UK regulations on rubber product end-of-life processing will favor domestic refurbishment capabilities. Aftermarket service infrastructure becomes a compliance-mandated competitive advantage.
Industry Challenges
- Polymer Chemist Recruitment:Formulation expertise for thermoplastic elastomer durability under cyclic loading remains scarce in UK manufacturing labor markets. Technical hiring timelines extend six to nine months.
- BIS Certification Timelines:Third-party structural integrity testing for new product lines creates six-month launch delays. Smaller manufacturers lack capital to maintain parallel certification pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Gym Accessories Market |
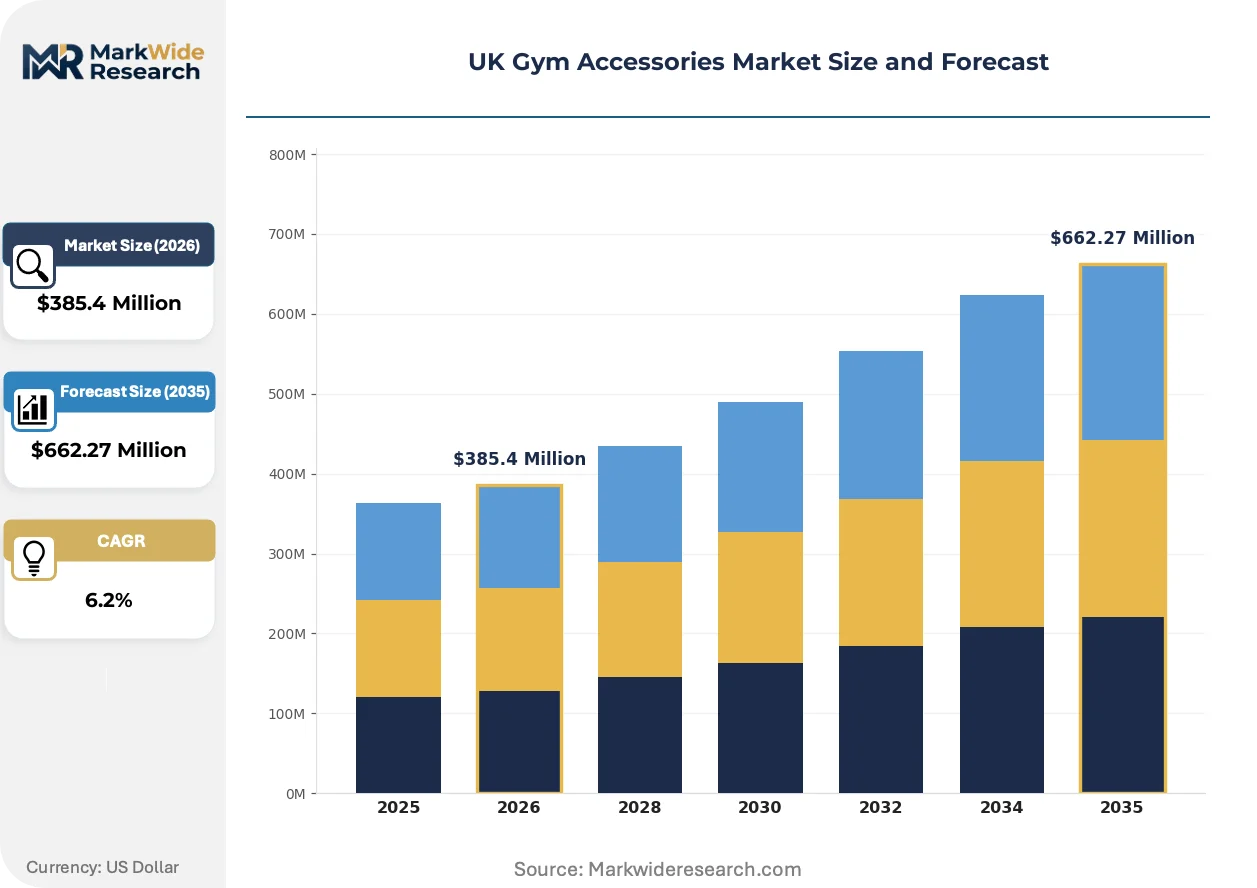
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistance Bands, Yoga Mats, Dumbbells, Kettlebells, Foam Rollers, Jump Ropes End User: Fitness Enthusiasts, Personal Trainers, Gym Facilities, Wellness Centers, Physical Therapy Clinics Distribution Channel: Specialty Stores, Online Retailers, Sporting Goods Outlets, Direct Manufacturer Sales, Fitness Centers Usage Type: Strength Training, Flexibility Exercises, Cardio Workouts, Rehabilitation, Balance Training |
| Companies Covered | Jordan Fitness, Physical Company, Exigo, Apollo Power & Fitness, York Fitness, Origin Fitness, Watson Gym Equipment, Cerberus Strength, Primal Strength, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Gym Accessories Market Trends and Innovations
Digital integration is reconfiguring how resistance equipment delivers value, moving beyond physical load provision toward data-capture functionality. Three distinct vectors are compressing traditional product boundaries.
Smart load-cell sensors embedded within kettlebell and dumbbell handles are virtualizing the personal training relationship. Boutique studios in Manchester's wellness districts deploy these connected devices to deliver remote form correction. The technology is compressing the geographic radius within which trainers can monetize client relationships.
REACH substance restrictions on polycyclic aromatic hydrocarbons in rubber compounding are elevating formulation costs for imported accessories. UK distributors now face documentary compliance requirements that domestic manufacturers bypass through BIS-certified supply chains. Premium commercial segments absorb these cost differentials; economy-tier imports lose shelf space in specialty retail.
Subscription-based equipment refresh models are displacing outright purchase in corporate wellness programmes. Facilities management providers in Greater London's premium office clusters bundle accessory replacement into service contracts. This shift transfers inventory risk from end-users to distributors with refurbishment capabilities.
UK Gym Accessories Market Segmentation
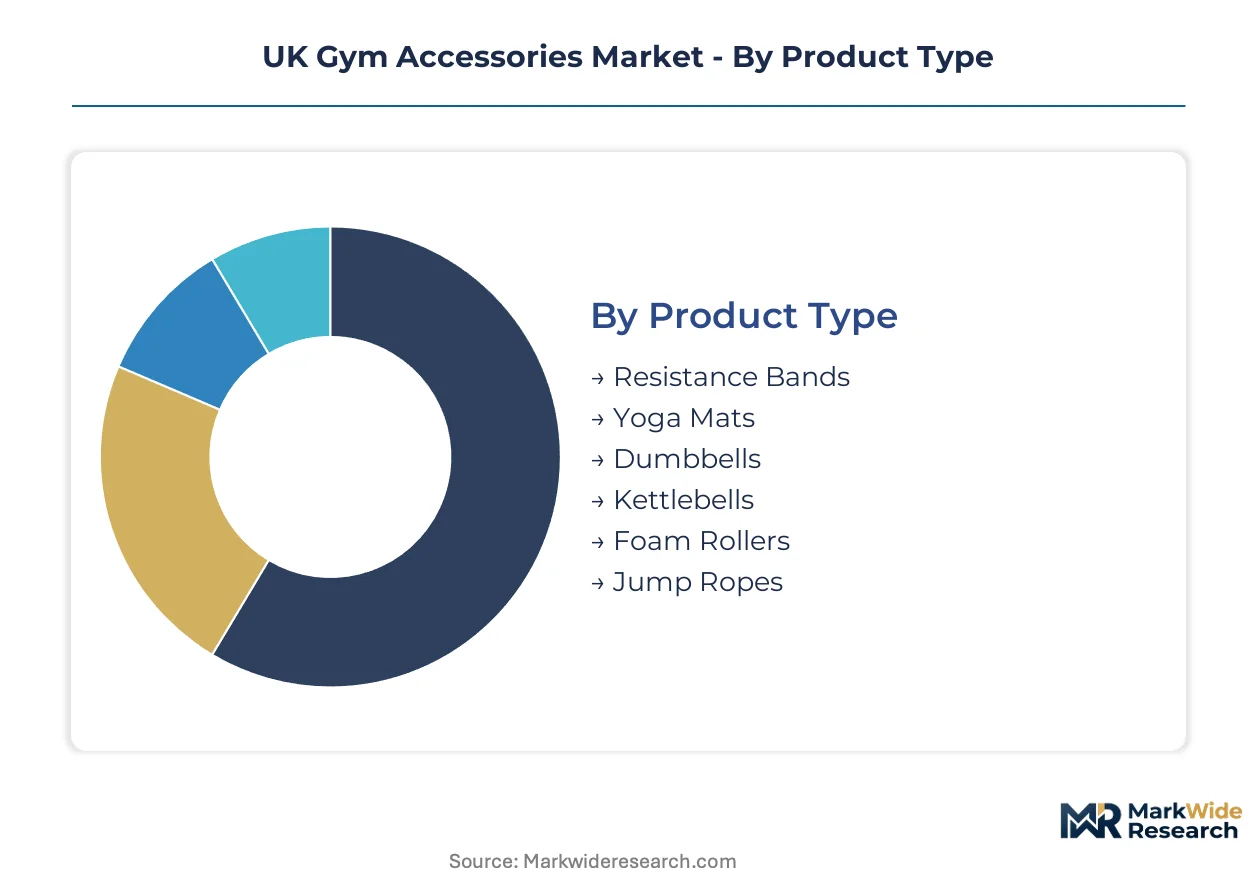
Segmentation in the UK gym accessories market exposes divergent margin structures across procurement contexts. Product durability requirements and distribution economics vary sharply between clinical rehabilitation settings and high-traffic commercial facilities.
Product Type:
The maturity spectrum spans established cast iron categories against emerging sensor-integrated formats.
- Dumbbells:Cast iron or rubber-coated hexagonal designs with knurled steel handles dominate commercial procurement. Greater London's premium gym clusters absorb the highest volume of pro-grade sets as boutique studios replace fixed machines with free-weight stations.
- Resistance Bands:Latex or fabric-loop constructions with graduated tension ratings enable progressive loading without storage footprint. NHS trusts and private physiotherapy clinics in Manchester's wellness districts are standardizing these protocols for post-operative rehabilitation, creating institutional demand distinct from consumer purchases.
- Kettlebells:Cast iron or steel competition-grade designs with color-coded weight identification serve ballistic training protocols.
- Yoga Mats:PVC, TPE, or natural rubber constructions with closed-cell density provide grip surfaces for floor-based movement.
- Foam Rollers:EVA or EPP foam cylinders with varying surface textures target myofascial release applications.
- Jump Ropes:PVC-coated steel cable or beaded designs with weighted handles support cardiovascular conditioning.
Dumbbells handle the majority of throughput; resistance bands are expanding most quickly on share.
End User:
Cost tier stratification separates capital-intensive facility procurement from individual enthusiast purchases.
- Gym Facilities:Commercial-grade equipment with BIS-certified load ratings and extended warranty terms. These buyers prioritize vulcanized rubber durability over price sensitivity, particularly in Greater London's high-turnover premium clusters.
- Physical Therapy Clinics:Medical-grade accessories with documented material composition for NHS procurement compliance. REACH-derived chemical safety standards now filter into specification sheets, elevating documentation requirements above standard commercial tiers.
- Personal Trainers:Portable configurations enabling mobile client sessions across multiple locations.
- Fitness Enthusiasts:Home gym setups with space-efficient storage and online research-driven selection.
- Wellness Centers:Holistic programming equipment spanning mind-body modalities.
Gym Facilities command the highest absolute spend per account; Physical Therapy Clinics are gaining share fastest through NHS standardization.
Distribution Channel:
Volume concentration favors direct relationships for large-format buyers, while fragmentation characterizes individual consumer access.
- Specialty Stores:Curated showrooms with equipment testing and staff technical expertise. These outlets retain margin density through England's boutique fitness chains, though floor space constraints limit inventory breadth.
- Direct Manufacturer Sales:Bulk procurement contracts with refurbishment service attachments. Jordan Fitness leverages domestic manufacturing to control replacement parts distribution through this channel.
- Online Retailers:Price-transparent platforms capturing home gym volume growth with extended maritime lead times on imported goods.
- Sporting Goods Outlets:Mass-market accessibility with limited commercial-grade penetration.
- Fitness Centers:Bundled equipment refresh models embedded in corporate wellness service contracts.
Direct Manufacturer Sales anchor the highest-value transactions; Online Retailers are climbing the fastest on transaction volume.
Usage Type:
Application focus determines material specification intensity and replacement frequency cycles.
- Strength Training:Progressive overload equipment with calibrated load increments and drop-resistant construction. Cast iron price volatility from foundry energy costs compresses margin predictability for manufacturers serving this core category.
- Rehabilitation:Controlled resistance with documented tension curves for clinical protocol adherence. Thermoplastic elastomer sourcing concentration in East Asian polymer processors creates inventory risk for UK distributors serving this segment.
- Flexibility Exercises:Static stretching and dynamic range-of-motion support equipment.
- Cardio Workouts:High-impact durable designs for repetitive motion endurance.
- Balance Training:Unstable surface and proprioceptive challenge configurations.
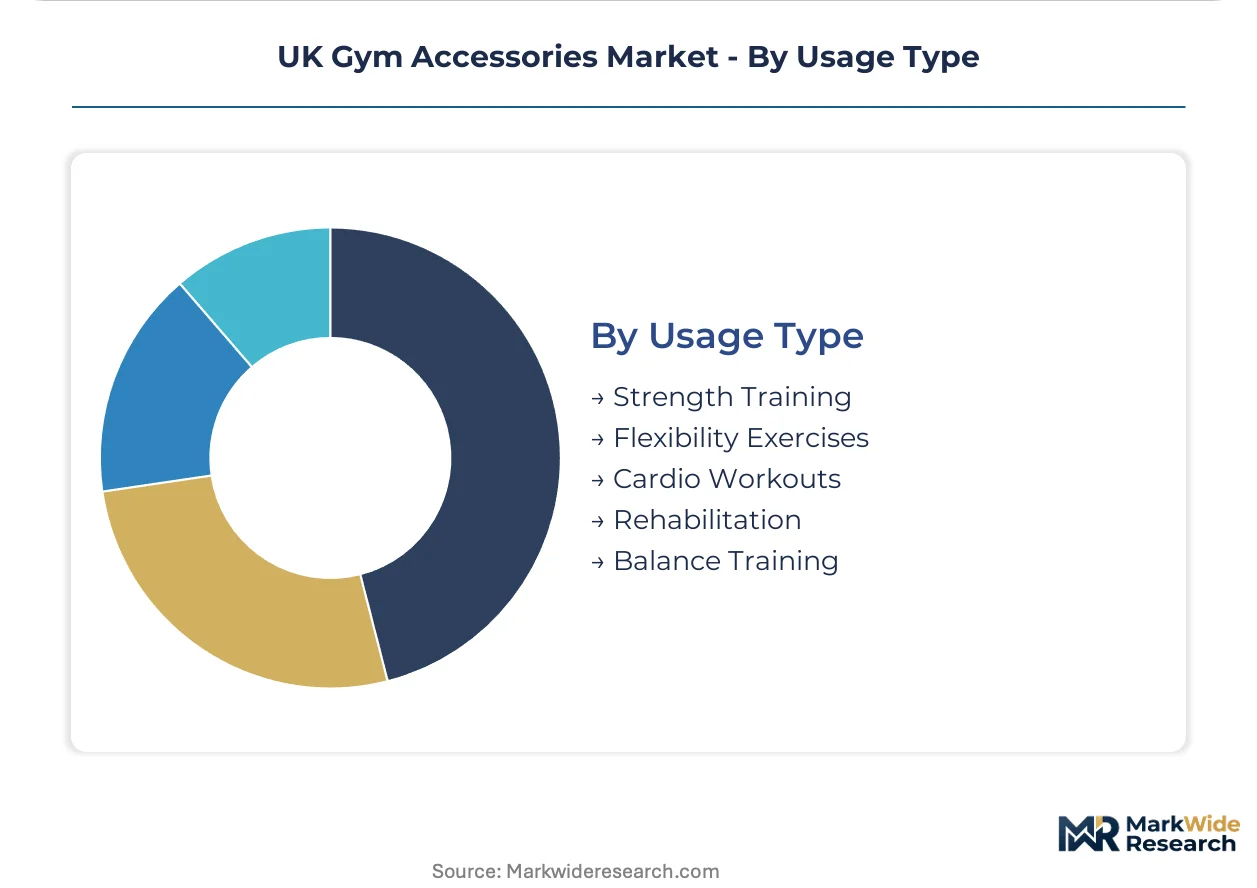
Strength Training generates the highest equipment turnover; Rehabilitation shows the steepest expansion trajectory as clinical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across UK sub-regions. Greater London's premium gym clusters absorb price premiums for BIS-certified equipment, while Northern England and Scottish markets remain acutely sensitive to import-driven cost fluctuations.
Greater London
Boutique fitness studios in Shoreditch and Canary Wharf drive procurement of space-efficient free-weight configurations. The Office for Product Safety and Standards enforces REACH-derived chemical documentation requirements for all rubber-coated imports. Wimbledon and Kensington wellness corridors concentrate specialist retail partnerships serving high-turnover commercial facilities.
North England
Manchester's emerging wellness districts anchor institutional demand from NHS trusts standardizing resistance band rehabilitation protocols. BIS certification timelines create six-month launch delays for smaller manufacturers entering this market. Leeds and Liverpool clusters exhibit growing procurement from independent personal trainers seeking portable equipment configurations.
Scotland
Edinburgh and Glasgow present underpenetrated boutique fitness density relative to population concentration. The country's national product safety regulator applies EU-legacy durability standards to rubber-based accessories. Glasgow's merchant city district is attracting first-mover equipment suppliers establishing regional distribution partnerships.
Midlands
Birmingham's industrial heritage supports domestic manufacturing of cast iron free weights with compressed working capital cycles. Foundry energy costs from regional metal processors generate margin unpredictability for local producers. Coventry and Leicester clusters concentrate refurbishment service providers capturing aftermarket revenue from corporate wellness programmes.
Wales
Cardiff and Swansea markets demonstrate accelerating home gym setup demand through online retail channels. Extended maritime lead times from East Asian polymer processors create inventory risk for resistance band distributors. The Welsh Government's active travel programmes indirectly stimulate complementary fitness equipment procurement.
UK Gym Accessories Market Competitive Landscape
Capability concentration sits with domestic fabricators holding BIS-certified supply chains; scale advantage sits with distributors leveraging specialty retail partnerships across England's boutique fitness chains. The vendor base separates into three tiers: domestic manufacturers controlling replacement parts distribution, import-reliant wholesalers serving price-sensitive home gym segments, and hybrid operators blending refurbishment capabilities with direct sales. Consolidation pressure operates through extended producer responsibility regulations favoring established refurbishment infrastructure. Competitive moves center on geographic expansion into Scottish wellness corridors and portfolio diversification toward sensor-embedded equipment categories.
Among UK-based manufacturers, Jordan Fitness and Watson Gym Equipment exemplify the domestic fabrication archetype with captive control over replacement parts distribution. Physical Company occupies a position within the specialty retail partnership tier, sustaining competitive positioning through curated showroom relationships across England's boutique fitness chains. These three entities represent distinct strategic postures: backward-integrated manufacturing, premium commercial segment focus, and distribution-centric market coverage.
| Leading Market Players |
|---|
| Jordan Fitness |
| Physical Company |
| Exigo |
| Apollo Power & Fitness |
| York Fitness |
| Origin Fitness |
| Watson Gym Equipment |
| Cerberus Strength |
| Primal Strength |
| Others |
Pricing and Supply Chain Analysis
East Asian polymer processors in Taiwan and South Korea anchor thermoplastic elastomer supply for UK resistance band manufacturers, their capacity utilization swings directly transmitting into landed cost volatility for Manchester's physiotherapy distributors. Foundry energy costs in Midlands metalworking clusters feed through to cast iron free-weight pricing with compressed working capital cycles squeezing domestic producers.
Pricing Analysis
Aftermarket service revenue from refurbishment and recalibration contracts drives lifetime value capture for UK gym accessory manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified commercial-grade equipment from REACH-compliant imports and uncertified economy-tier goods. Pricing pressure stems from cast iron price volatility compressing margin predictability for dumbbell and kettlebell producers. Home gym enthusiasts exhibit highest price sensitivity; Greater London's premium boutique studios absorb premium positioning with minimal elasticity.
Supply Chain Analysis
REACH substance restrictions on polycyclic aromatic hydrocarbons function as de facto export controls limiting rubber compound flows from non-compliant Asian processors into UK distribution channels. Vulcanized rubber sourcing concentrates in Malaysia and Indonesia; cast iron feedstock draws from domestic Midlands foundries and European scrap metal markets. Single-source vulnerability sits with East Asian thermoplastic elastomer processors carrying extended maritime lead times. Distribution runs through specialty retail partnerships and direct manufacturer contracts with refurbishment service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer chemist formulation expertise for thermoplastic elastomer durability under cyclic loading remains acutely scarce in UK manufacturing labor markets, extending technical hiring timelines and constraining domestic product development velocity.
For Market Incumbents: Harden BIS certification pipelines by maintaining parallel third-party structural integrity testing tracks, eliminating six-month launch delays that cede first-mover advantage to import-reliant competitors. Anchor replacement parts distribution through direct manufacturer sales channels, denying aftermarket revenue to refurbishment specialists. Defend against sensor-embedded equipment convergence by accelerating load-cell technology partnerships with Manchester's connected-fitness boutiques. For New Entrants and Emerging Players: Scottish wellness corridors in Edinburgh and Glasgow represent the most penetrable entry point, exhibiting boutique fitness density significantly below population-weighted benchmarks against Greater London saturation. NHS trust standardization of resistance band rehabilitation protocols creates institutional demand pull distinct from crowded commercial gym procurement. Pursue regional distribution partnerships with Glasgow's merchant city district landlords before incumbent specialty retailers consolidate shelf space. For Investors and Strategic Acquirers: Long-term, this sits as a refurbishment-infrastructure play because anticipated extended producer responsibility regulations on rubber product end-of-life processing will mandate domestic recycling capabilities, transforming aftermarket service infrastructure from competitive advantage into compliance requirement. Target domestic manufacturers with captive BIS-certified supply chains and existing refurbishment operations. Monitor Office for Product Safety and Standards enforcement patterns for early signals of regulatory acceleration that would compress valuation windows for import-dependent distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Equipment Development | Load-cell integration into kettlebell handles commands premium positioning in Manchester's connected-fitness boutiques. |
| Scottish Distribution Partnership | First-mover regional anchoring captures underpenetrated Edinburgh and Glasgow wellness corridor expansion. |
| Refurbishment Capability Buildout | Domestic rubber processing infrastructure satisfies anticipated extended producer responsibility compliance mandates. |
| REACH-Compliant Supply Chain Certification | BIS-certified material documentation bypasses documentary requirements filtering into UK procurement specifications. |
| Corporate Wellness Service Contract | Bundled equipment refresh models transfer inventory risk from end-users to distributors with refurbishment capabilities. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with equipment procurement managers at NHS trusts, boutique studio owners in Greater London and Manchester, polymer chemists at domestic manufacturers, and specialty retail buyers; alongside secondary validation through BIS certification records, Office for Product Safety and Standards enforcement disclosures, and trade customs data on rubber and cast iron imports. Bottom-up segment sizing triangulated against top-down market value estimates.
Forecast inputs considered product type maturity curves, end-user procurement budget trajectories, and distribution channel shift velocities across the analysis window. Segmentation dimensions modeled include product durability tier, institutional versus consumer procurement context, and geographic demand cluster density. CAGRs derived from weighted average of historical volume trends and forward-looking buyer intention surveys, with specific adjustment for foundry energy cost volatility and REACH compliance timeline uncertainty.
Practitioners should monitor polymer chemist hiring pipeline depth, BIS certification backlog duration, and REACH enforcement intensity for early signals of supply-side constraint or regulatory acceleration. Forecasts reflect assumptions regarding continued boutique fitness studio expansion, stable NHS rehabilitation protocol standardization, and moderate cast iron price volatility. Material shifts in extended producer responsibility implementation timing or East Asian maritime logistics disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Smart Gym Equipment Market