
 Smart Treadmill Market | 2026-2036
Smart Treadmill Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Treadmill Market Insights
Embedded software engineering talent is bifurcating the competitive landscape, as manufacturers that secure firmware and IoT development teams unlock subscription revenue while others remain hardware-dependent. Peloton Interactive leverages its vertically integrated content platform to sustain recurring membership income alongside equipment sales. NordicTrack anchors its position through iFit-enabled interactive training that differentiates its hardware from commodity treadmill producers. Technogym competes in the premium commercial segment where brand strength and direct channel control support pricing power across European gym chains.
A smart treadmill is an electromechanical running deck integrated with microprocessor-controlled variable-speed motors, incline actuators, and network connectivity enabling real-time biometric feedback and content streaming. The primary commercial purpose is to deliver personalized, data-driven cardio workouts while capturing usage analytics for operators and subscribers. Foldable and compact product types are capturing the fastest expansion as urban apartment dwellers prioritize space efficiency, while commercial-grade non-foldable units retain the deepest margin pools in long-term gym service contracts. Bluetooth and wearable integration technologies are maturing rapidly, though smart sensors that enable gait analysis and predictive maintenance represent the emerging differentiation layer where R&D investment is concentrating.
FCC certification governs radio-frequency emissions for US-bound connected treadmills, while the EU's CE marking and RoHS compliance restrict hazardous substances in electrical components and mandate electromagnetic compatibility. Japan's METI enforces standby power regulations that shape motor controller design for products entering that market. Stakeholders must weigh whether to absorb certification costs across multiple regulatory regimes or concentrate development resources on jurisdictions with the highest subscription attach rates.
Market Dynamics
Embedded firmware engineering scarcity is bifurcating the competitive landscape, as manufacturers that secure IoT development teams unlock recurring subscription revenue while hardware-dependent competitors face margin compression from commodity treadmill producers.
Growth Catalysts
- EU Green Deal ecodesign requirements:Mandates for lower standby power consumption are accelerating motor controller redesigns that differentiate compliant manufacturers in European procurement cycles.
- Boutique fitness studio expansion:Premium studio chains are retrofitting cardio floors with connected equipment that captures usage analytics and enables membership tiering based on equipment access.
- Bluetooth and wearable integration:Maturing protocols for real-time biometric feedback are elevating baseline consumer expectations and shortening replacement cycles for non-connected legacy units.
Market Restraints
- Rare earth magnet supply concentration:Variable-speed motor production depends on neodymium supply chains concentrated in Chinese processing facilities, exposing manufacturers to input volatility and export restriction risk.
- Multi-jurisdiction certification costs:FCC, CE marking, and METI standby power regulations impose overlapping compliance burdens that disproportionately burden mid-scale producers lacking dedicated regulatory affairs teams.
- Space-efficient home fitness substitutes:Compact rowing machines and connected stationary bikes compete for the same urban apartment square footage and subscription budget allocation.
Strategic Opportunities
- Predictive maintenance sensor convergence:Gait analysis algorithms combined with vibration monitoring create service contract revenue streams in commercial gym chains seeking to minimize equipment downtime.
- Hotel wellness program penetration:Luxury hospitality operators are expanding in-room fitness amenities as a brand differentiation lever, creating specification opportunities for whisper-quiet deck designs.
- Japan METI standby power incentives:Sub-national efficiency programs reward sub-one-watt idle consumption, opening procurement channels for manufacturers that engineer motor controllers to exceed baseline compliance.
Industry Challenges
- Firmware security talent scarcity:Connected treadmill architectures require embedded systems engineers with IoT security expertise, a skill set concentrated in automotive and aerospace sectors with deeper compensation pools.
- Legacy gym management system integration:Retrofitting connected equipment into facilities running decade-old access control and billing platforms demands costly middleware development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Treadmill Market |
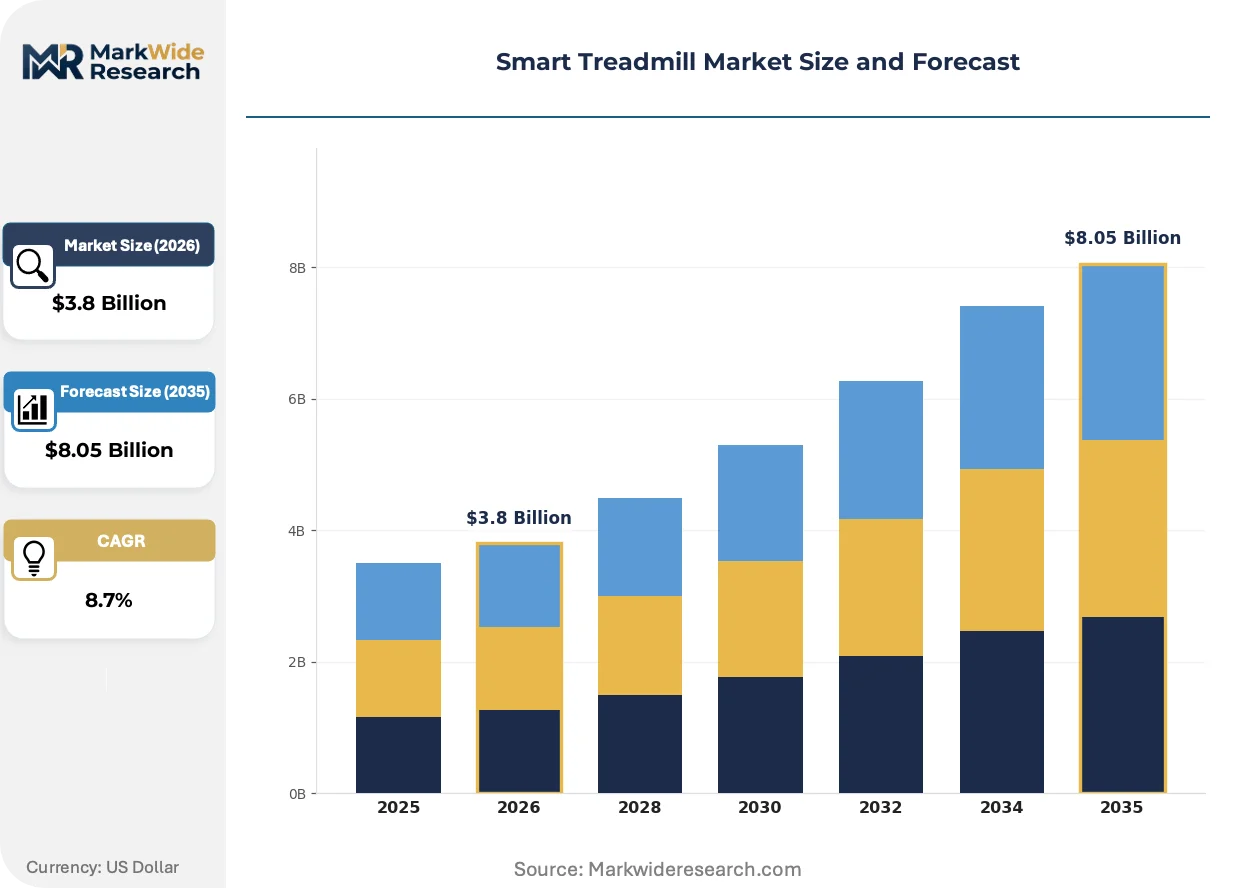
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Non-Foldable, Compact, Commercial Technology: Wi-Fi, Bluetooth, Smart Sensors, Wearable Integration End User: Home Users, Gyms, Rehabilitation Centers, Hotels Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Peloton Interactive, NordicTrack, ProForm, Life Fitness, Technogym, Precor, Nautilus, Sole Fitness, Horizon Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Treadmill Market Trends and Innovations
Smart sensor architectures are compressing the form factor and cost structure of biometric feedback systems, enabling differentiation beyond content streaming to hardware-integrated performance optimization.
Force-sensing resistor arrays embedded in running decks are miniaturizing from laboratory gait analysis equipment into consumer-accessible form factors. Boutique fitness studios are adopting these systems fastest, using real-time ground reaction force data to customize running programs. This sensor integration is miniaturizing the competitive moat that previously required expensive wearable ecosystems.
The EU AI Act's risk classification framework is reshaping how manufacturers deploy automated coaching algorithms that adjust speed and incline based on user biometrics. Systems categorized as high-risk face conformity assessment requirements that extend product launch timelines. Treadmill producers serving European commercial gym chains are responding by segregating AI-enabled features by market, maintaining simpler control architectures for EU-bound units.
Subscription unbundling from hardware purchases is fragmenting the traditional bundled pricing model that dominated home fitness. Direct-to-consumer channels are displacing retail partnerships for connected equipment, as manufacturers capture customer relationships and recurring revenue directly. Germany exhibits this pattern most acutely, where Peloton and NordicTrack have built dedicated fulfillment infrastructure to bypass electronics retailers and control the entire ownership experience.
Smart Treadmill Market Segmentation
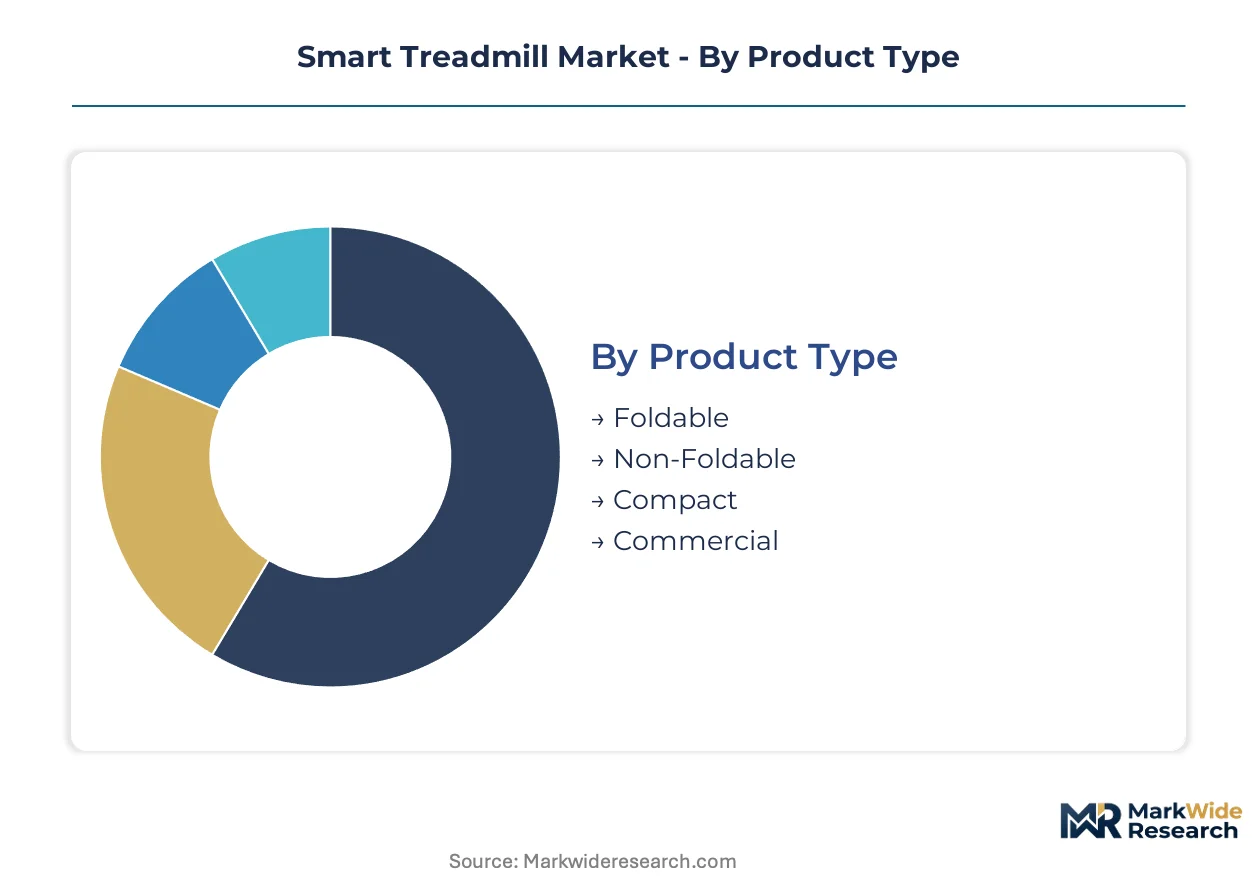
Smart treadmill manufacturers engineer product architectures around distinct usage environments and connectivity requirements. Segment-specific certification burdens and margin structures determine which configurations justify dedicated production lines versus modular platform derivatives.
Product Type:
FCC and CE marking requirements diverge sharply between motorized folding mechanisms and fixed-frame commercial units, with foldable designs facing additional electromagnetic compatibility testing for hinge-integrated wiring.
- Foldable:Hinge-actuated deck designs with reinforced locking mechanisms support vertical storage. Urban apartment dwellers in Germany and Japan drive procurement as residential square footage contracts. EU ecodesign standby power mandates favor motor controllers that minimize idle draw in compact footprints.
- Non-Foldable:Rigid frame construction with reinforced shock absorption systems supports sustained commercial duty cycles. Boutique fitness studios in New York and London specify these units for high-frequency member usage where deck stability outweighs spatial flexibility.
- Compact:Reduced-dimension running surfaces below 140cm deck length target secondary home fitness spaces. Japanese METI standby power incentives reward sub-one-watt idle consumption in these smaller motor configurations.
- Commercial:Heavy-gauge steel construction with AC inverter motors rated for continuous operation. Long-term service contracts with European gym chains generate recurring maintenance revenue streams.
Established volume favors non-foldable units in commercial procurement; emerging adoption favors foldable configurations in residential retrofit cycles.
Technology:
Component costs and patent licensing structures stratify connectivity implementations, with basic radio modules commoditizing while sensor fusion architectures command premium positioning.
- Wi-Fi:802.11ac/ax modules enable cloud-synced workout libraries and firmware over-the-air updates. Subscription-dependent business models in the United States and Germany require reliable streaming bandwidth for live class delivery.
- Bluetooth:Low-energy protocols for heart rate strap and headphone pairing have become baseline expectations. The protocol's maturity shortens hardware development cycles for mid-range product tiers.
- Smart Sensors:Force-sensing resistor arrays and accelerometer clusters enable gait analysis and predictive maintenance alerts. Boutique studios adopt these fastest for real-time ground reaction force feedback.
- Wearable Integration:API connections to Apple Watch, Garmin, and Samsung Health ecosystems consolidate biometric data streams. This capability is climbing the fastest in consumer purchasing criteria.
Bluetooth penetration dominates unit shipments; smart sensor integration is gaining share fastest in premium positioning.
End User:
Procurement authority and total cost of ownership calculations vary dramatically across buyer types, from individual consumers to facility managers with decade-long capital planning horizons.
- Home Users:Individual purchasers prioritizing space efficiency and content subscription bundles. Direct-to-consumer channels in Germany bypass electronics retailers to capture customer relationships.
- Gyms:Commercial operators requiring usage analytics for membership tiering and predictive maintenance to minimize equipment downtime. European chains retrofit cardio floors with connected units.
- Rehabilitation Centers:Medical-grade specifications with gait monitoring for physical therapy protocols. FDA classification considerations shape feature deployment in United States facilities.
- Hotels:Luxury hospitality operators expanding in-room fitness amenities as brand differentiation. Whisper-quiet deck designs open specification opportunities in premium properties.
Gym procurement anchors commercial volume; hotel wellness programs represent the steepest expansion trajectory for premium installations.
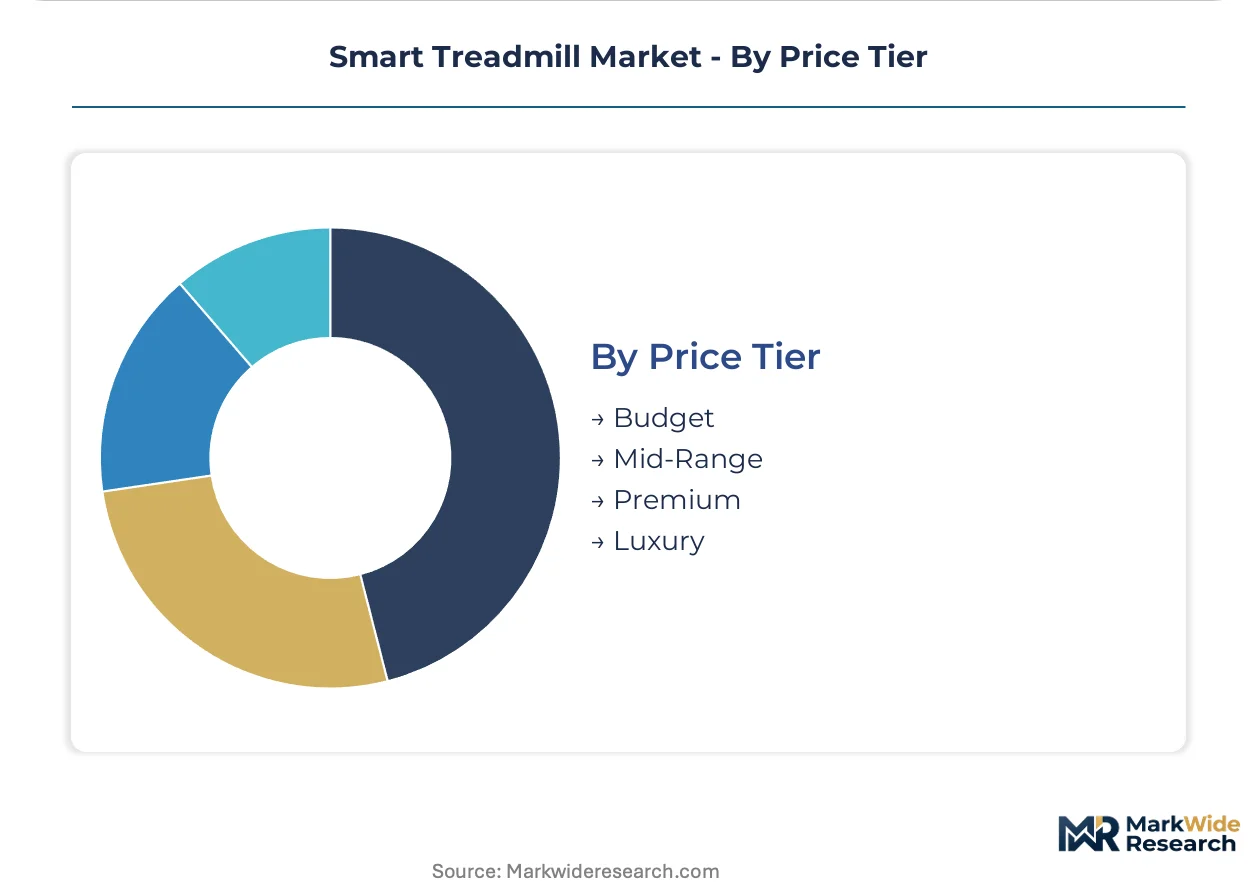
Price Tier:
Bill-of-materials flexibility and certification cost absorption capacity determine viable positioning, with regulatory compliance burdens compressing margins at the lowest tier.
- Budget:DC motor platforms with basic LED displays and limited connectivity. Chinese manufacturing concentrates supply for this tier, though FCC and CE marking costs strain profitability.
- Mid-Range:Inverter motor systems with tablet integration and subscription-capable software stacks. This tier captures the largest unit volumes in North American and European retail.
- Premium:Large-format touchscreens, live class streaming, and advanced biomechanical feedback. Peloton and NordicTrack dominate this tier through vertically integrated content platforms.
- Luxury:Custom finishes, concierge onboarding, and white-glove installation services. Technogym competes here through direct channel control and brand strength in European commercial segments.
Mid-range configurations drive aggregate revenue; premium tier positioning is expanding most quickly in subscription-attach rate optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification governs radio-frequency emissions for US-bound connected treadmills, while the EU's CE marking and RoHS compliance restrict hazardous substances in electrical components. Boutique fitness studios in Germany and hotel wellness programs in Japan concentrate procurement of connected cardio equipment.
Germany
Commercial gym chains in Berlin and Munich are retrofitting cardio floors with network-connected treadmills that capture usage analytics for membership tiering. The EU Green Deal's ecodesign requirements mandate lower standby power consumption, pressuring motor controller redesigns. Bavaria's industrial corridor hosts precision manufacturing clusters supplying sensor-integrated deck components to domestic equipment producers.
United States
Peloton Interactive and NordicTrack have built dedicated fulfillment infrastructure to bypass electronics retailers and control direct-to-consumer relationships. FCC certification imposes electromagnetic compatibility testing burdens that strain mid-scale producers lacking dedicated regulatory affairs teams. New York and Los Angeles anchor boutique fitness studio expansion, driving specification of commercial-grade non-foldable units with predictive maintenance capabilities.
Japan
METI standby power regulations enforce sub-one-watt idle consumption requirements that shape motor controller design for products entering this market. Sub-national efficiency programs reward manufacturers that engineer controllers to exceed baseline compliance. Tokyo and Osaka concentrate luxury hospitality operators expanding in-room fitness amenities, creating specification opportunities for whisper-quiet deck designs.
United Kingdom
Boutique fitness studios in London are adopting force-sensing resistor arrays for real-time ground reaction force feedback to customize running programs. The EU AI Act's risk classification framework reshapes deployment of automated coaching algorithms, with high-risk systems facing extended conformity assessment timelines. Manchester and Birmingham host commercial gym chains retrofitting facilities with connected equipment integrated into legacy management systems.
China
Variable-speed motor production depends on neodymium supply chains concentrated in Chinese processing facilities, exposing manufacturers to input volatility. Domestic producers supply DC motor platforms with basic LED displays for budget-tier export markets. Shenzhen and Guangzhou clusters concentrate firmware engineering talent for IoT development teams that unlock subscription revenue models.
Smart Treadmill Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the smart treadmill market, with vertical integration into content platforms separating subscription-capable manufacturers from hardware-dependent competitors. The competitive landscape bifurcates between firms that capture recurring membership income alongside equipment sales and those facing margin compression from commodity producers. Three archetypes dominate: vertically integrated content-hardware platforms, premium commercial equipment specialists, and contract manufacturers serving private-label retail channels. Dominant competitive moves include direct-to-consumer channel expansion bypassing traditional electronics retailers and predictive maintenance sensor integration to capture commercial service contract revenue.
Within the vertically integrated tier, Peloton Interactive exemplifies the content-platform archetype through its subscription-dependent business model, while NordicTrack anchors the interactive training segment with iFit-enabled differentiation. Technogym occupies a position in the premium commercial segment where brand strength and direct channel control support pricing power across European gym chains. These three firms represent distinct strategic postures: content-capture, software-hardware fusion, and commercial-brand premiumization.
| Leading Market Players |
|---|
| Peloton Interactive |
| NordicTrack |
| ProForm |
| Life Fitness |
| Technogym |
| Precor |
| Nautilus |
| Sole Fitness |
| Horizon Fitness |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts with European gym chains lock in both neodymium magnet supply access and predictable maintenance pricing visibility. These multi-year agreements insulate manufacturers from rare earth volatility while compressing margins for hardware-only competitors lacking subscription attach rates.
Pricing Analysis
German commercial procurement commands a 15-20% premium over North American residential channels due to EU Green Deal compliance costs and embedded predictive maintenance sensors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and software capability. Pricing pressure stems from Chinese DC motor platforms flooding budget segments. Home users in compact urban apartments exhibit highest price sensitivity; luxury hospitality operators show lowest.
Supply Chain Analysis
Strategic stockpiling of neodymium magnets and motor controllers dominates inventory strategy over just-in-time approaches due to Chinese export restriction risks. Manufacturing concentrates in China, Germany, and Taiwan for motor assemblies, deck components, and sensor modules respectively. Raw material dependencies include rare earth magnets, cold-rolled steel, and force-sensing resistor arrays. Single-source vulnerability in Chinese rare earth processing threatens input stability. Distribution runs through direct-to-consumer channels and commercial fitness equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected treadmills face substitution pressure from compact rowing machines and stationary bikes competing for identical urban apartment square footage and subscription budgets. Incumbents must architect defensible positioning against these space-efficient alternatives.
For Market Incumbents: Compound firmware engineering capabilities through captive IoT development teams to sustain subscription revenue differentiation against hardware-dependent competitors. Deepen backward integration into sensor-integrated deck manufacturing to control predictive maintenance service contract margins. Defend against boutique fitness studio consolidation by embedding usage analytics that enable membership tiering.
For New Entrants and Emerging Players: Differentiate on whisper-quiet motor designs targeting Japan METI standby power incentives and luxury hospitality in-room fitness specifications. White-space opportunities concentrate in hotel wellness programs across Tokyo and Osaka, and rehabilitation center gait monitoring systems requiring FDA-classified medical-grade architectures. Pursue direct specification relationships with hospitality procurement directors bypassing traditional equipment distributors.
For Investors and Strategic Acquirers: Firmware-integrated equipment specialists with established iFit or comparable platform ecosystems represent the highest-conviction acquisition archetype for subscription revenue capture. Long-term viability hinges on software-hardware fusion capabilities that transcend commodity motor manufacturing. Watch for inflection when METI standby power regulations tighten below one-watt thresholds, advantaging engineered motor controller investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Sensor Integration | Enables recurring service contract revenue with European gym chains seeking minimized equipment downtime. |
| Direct-to-Consumer Channel Expansion | Bypasses electronics retailers in Germany to capture customer relationships and subscription attach rates. |
| METI Standby Power Compliance Investment | Opens Japanese procurement channels through sub-one-watt motor controller engineering. |
| Force-Sensing Resistor Array Miniaturization | Compresses gait analysis costs for boutique studio adoption and real-time ground reaction force feedback. |
| Firmware Security Talent Acquisition | Addresses embedded systems engineering scarcity concentrated in automotive and aerospace compensation pools. |
Research Methodology
Desk research of SEC filings, EU regulatory databases, and fitness equipment trade publications preceded structured interviews with commercial gym procurement directors, embedded firmware engineers, hospitality wellness program managers, and motor controller manufacturing specialists. Primary fieldwork with equipment distributors and boutique studio operators was cross-validated against customs records and neodymium supply chain disclosures. Bottom-up unit shipment estimates were triangulated with top-down subscription revenue projections.
Variance decomposition across product type, technology tier, end-user segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU AI Act conformity assessment timelines, METI standby power incentive structures, and rare earth magnet price volatility assumptions.
The analysis sits within stated boundaries; outcomes outside sustained boutique fitness studio expansion or stable Chinese rare earth export policies would require recalibration. Forecasts reflect documented assumptions regarding subscription attach rate trajectories and certification cost absorption capacity. Revision becomes warranted when neodymium supply disruption crosses thresholds affecting motor controller production economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Gymnastic Bench Market