
 Boutique Fitness Studio Market | 2026-2036
Boutique Fitness Studio Market Size, Share, and Industry Trends Forecast 2026-2036
Boutique Fitness Studio Market Analytics
Modular membership packaging is shifting how consumers engage boutique fitness, with studios unbundling traditional all-access passes into tiered, activity-specific subscriptions. Burn Boot Camp leverages its franchise model to sustain rapid geographic expansion across suburban markets. OrangeTheory Fitness anchors its competitive position through data-driven heart-rate monitoring technology embedded in every class. Club Pilates differentiates by occupying the premium reformer-based segment with consistent instructor certification standards.
A boutique fitness studio denotes a specialized, small-format exercise facility typically under 4,000 square feet, offering curated class-based programming with dedicated equipment such as reformers, spin bikes, or heavy bags, designed to deliver high-intensity, instructor-led workouts in a community setting. Pilates and yoga studios command the highest per-session pricing due to equipment capital requirements and certified instructor scarcity, while cycling formats compete on throughput volume with standardized 45-minute class structures. Monthly subscription models dominate revenue stability, though punch cards retain relevance among sporadic users and seasonal demand fluctuations.
US-based operators navigate FDA oversight for wearable biometric devices and FCC compliance for wireless heart-rate transmission systems integrated into studio technology stacks. Local zoning boards and health departments in cities like New York and Austin impose occupancy limits and ventilation standards that directly constrain class capacity and studio layout design. Stakeholders must monitor evolving municipal fitness facility regulations and consumer privacy frameworks governing biometric data collection as technology penetration deepens across the sector.
Market Dynamics
Wearable biometric integration and app-based booking platforms are compressing studio operating models while FDA oversight of heart-rate monitoring devices and municipal zoning constraints reshape capital deployment decisions across metropolitan markets.
Growth Catalysts
- Biometric Data Monetization:Studios leverage FCC-compliant wireless transmission systems to sell aggregated performance analytics to health insurers and corporate wellness programs, creating ancillary revenue streams beyond membership fees.
- Municipal Fitness Incentives:Cities including Austin and Denver offer property tax abatements for wellness facilities in designated opportunity zones, reducing effective lease costs for studio operators.
- Reformer Equipment Leasing:Specialized financing vehicles for Pilates apparatus lower barrier-to-entry for independent instructors transitioning to studio ownership.
Market Restraints
- Certified Instructor Scarcity:Reformer-based formats require 500+ hour certification programs with limited annual cohort capacity, constraining class expansion velocity.
- Real Estate Concentration:Prime retail corridors in Manhattan and Brooklyn command rents exceeding $80 per square foot annually, absorbing 35-40% of studio operating budgets.
- Substitution by Home Fitness:Connected stationary bikes and smart mirrors with live class streaming capture commuters and parents with scheduling constraints.
Strategic Opportunities
- Corporate On-Site Deployment:Employers in Austin and Los Angeles contract mobile reformer setups and instructor teams for campus wellness programs, bypassing consumer acquisition costs.
- Medicaid Fitness Integration:Several states now reimburse qualified fitness programming for diabetes prevention and obesity management, opening reimbursement pathways for medically-affiliated studios.
- AI-Generated Programming:Machine learning platforms analyze member biometric histories to auto-generate personalized class recommendations, increasing retention metrics.
Industry Challenges
- Instructor Burnout and Turnover:High-intensity formats demand physical output from coaches, with average tenure below 18 months at high-volume cycling studios.
- Biometric Data Compliance:HIPAA-aligned privacy frameworks for wearable-collected heart-rate and metabolic data require legal infrastructure most independent operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boutique Fitness Studio Market |
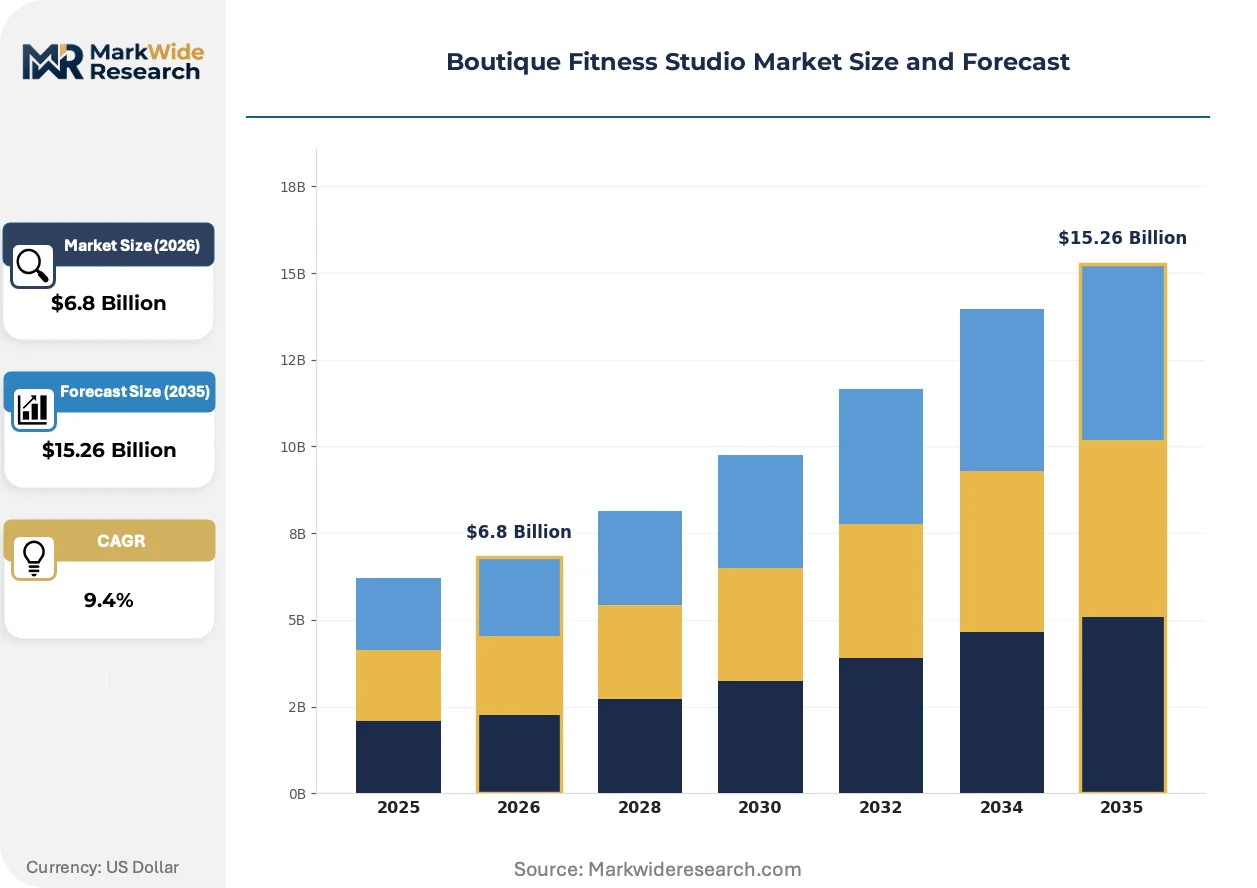
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Studio Type: Pilates, Yoga, Cycling, Dance Service Offering: Personal Training, Group Classes, Online Sessions, Workshops Membership Model: Monthly Subscription, Punch Cards, Pay-As-You-Go, Annual Passes Target Demographic: Young Professionals, Seniors, College Students, Families |
| Companies Covered | StretchLab, Burn Boot Camp, Club Pilates, Pure Barre, HOTWORX, OrangeTheory Fitness, JETSET Pilates, 9Round, F45 Training, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boutique Fitness Studio Market Evolving Landscape
Studio technology stacks are converging around predictive analytics and automated member lifecycle management, while regulatory scrutiny of health claims intensifies and consumer expectations for personalization harden.
Real-time heart-rate variability monitoring is rewriting how instructors calibrate intensity across class segments. Premium cycling and boot camp formats embed Polar and Garmin transmission protocols into every session, enabling leaderboard rankings and post-class recovery scoring. This biometric layer is compressing differentiation between budget and premium tiers as baseline expectations shift.
FDA guidance documents on general wellness devices versus regulated medical equipment are tightening marketing claims around calorie burn accuracy and cardiovascular benefit quantification. Studios must scrub promotional materials of specific disease prevention language or pursue 510(k) clearance pathways. New York and California attorneys general have initiated enforcement sweeps targeting studios making unsubstantiated metabolic claims.
Subscription fatigue is fragmenting how consumers construct fitness portfolios. Urban professionals increasingly stack single-format memberships across 3-4 specialized studios rather than committing to all-access packages, forcing operators to defend retention through community programming rather than pricing lock-in. This pattern concentrates in Los Angeles and Austin where studio density permits geographic convenience without format compromise.
Boutique Fitness Studio Market Segmentation
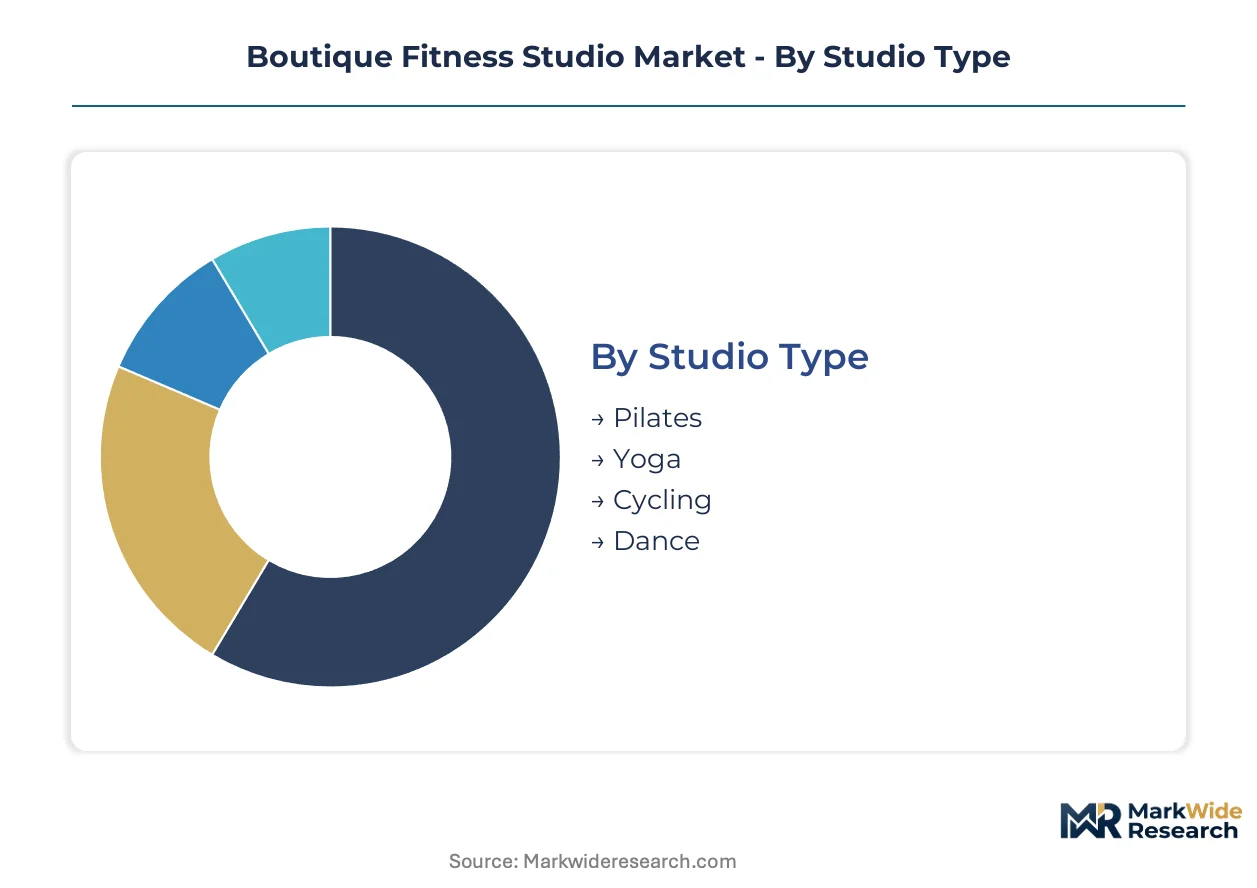
Studio operators calibrate equipment investments, instructor certification pipelines, and real estate footprints against distinct segment economics. Format-specific capital requirements and demographic lifetime value profiles determine which segments attract multi-unit franchise expansion versus independent owner-operators.
Studio Type:
Equipment intensity and instructor credentialing costs drive format selection for new market entrants.
- Pilates:Reformer apparatus requires $15,000-$25,000 per machine with specialized flooring and ventilation systems. Demand concentrates in affluent coastal suburbs where physical therapy referrals and postpartum recovery needs sustain premium pricing.
- Cycling:Standardized 45-minute class structures maximize throughput with 30-50 bikes per studio. Volume clusters in dense metropolitan corridors where commuter convenience and leaderboard competition mechanics drive repeat attendance.
- Yoga:Minimal equipment requirements lower barrier-to-entry for independent instructors. Heated vinyasa and restorative sub-formats differentiate through ambiance design rather than capital deployment.
- Dance:Choreography licensing and instructor performance backgrounds create talent scarcity constraints. Hip-hop and ballroom sub-formats attract episodic participation for wedding preparation and social recreation.
Volume sits with Cycling; growth tilts toward Pilates.
Service Offering:
Revenue stability and labor utilization rates vary sharply across service modalities.
- Group Classes:Fixed instructor costs spread across 20-40 participants yield contribution margins exceeding 60% at mature studios. Capacity constraints in reformer-based formats limit class expansion velocity.
- Personal Training:Premium hourly rates command 3-4x group class pricing with dedicated equipment access. Demand concentrates among injury recovery clients and executives with scheduling inflexibility.
- Online Sessions:Livestream and on-demand libraries extend geographic reach beyond studio catchment areas. Subscription pricing pressure intensifies as Peloton and Apple Fitness+ set baseline expectations.
- Workshops:Weekend-intensive formats address certification completion and specialized skill acquisition. Teacher training programs generate ancillary revenue while building instructor pipelines.
Margin concentration favors Group Classes; expansion trajectory is steepest for Online Sessions.
Membership Model:
Cash flow predictability and customer acquisition economics diverge across commitment structures.
- Monthly Subscription:Recurring revenue foundations support studio valuation multiples and equipment financing terms. Urban millennials demonstrate highest retention when autopay integrates with employer wellness stipends.
- Annual Passes:Upfront cash collection funds expansion capital but concentrates cancellation risk in economic downturns. Corporate wellness partnerships increasingly substitute for individual annual commitments.
- Punch Cards:Per-session flexibility accommodates seasonal demand fluctuations and sporadic users. Austin and Los Angeles operators report 15-20% of revenue from this modality.
- Pay-As-You-Go:Highest per-session pricing captures trial users and tourist traffic with minimal commitment friction. Conversion rates to subscription models vary by studio community programming intensity.
Revenue stability anchors with Monthly Subscription; customer acquisition efficiency gains most rapidly with Pay-As-You-Go.
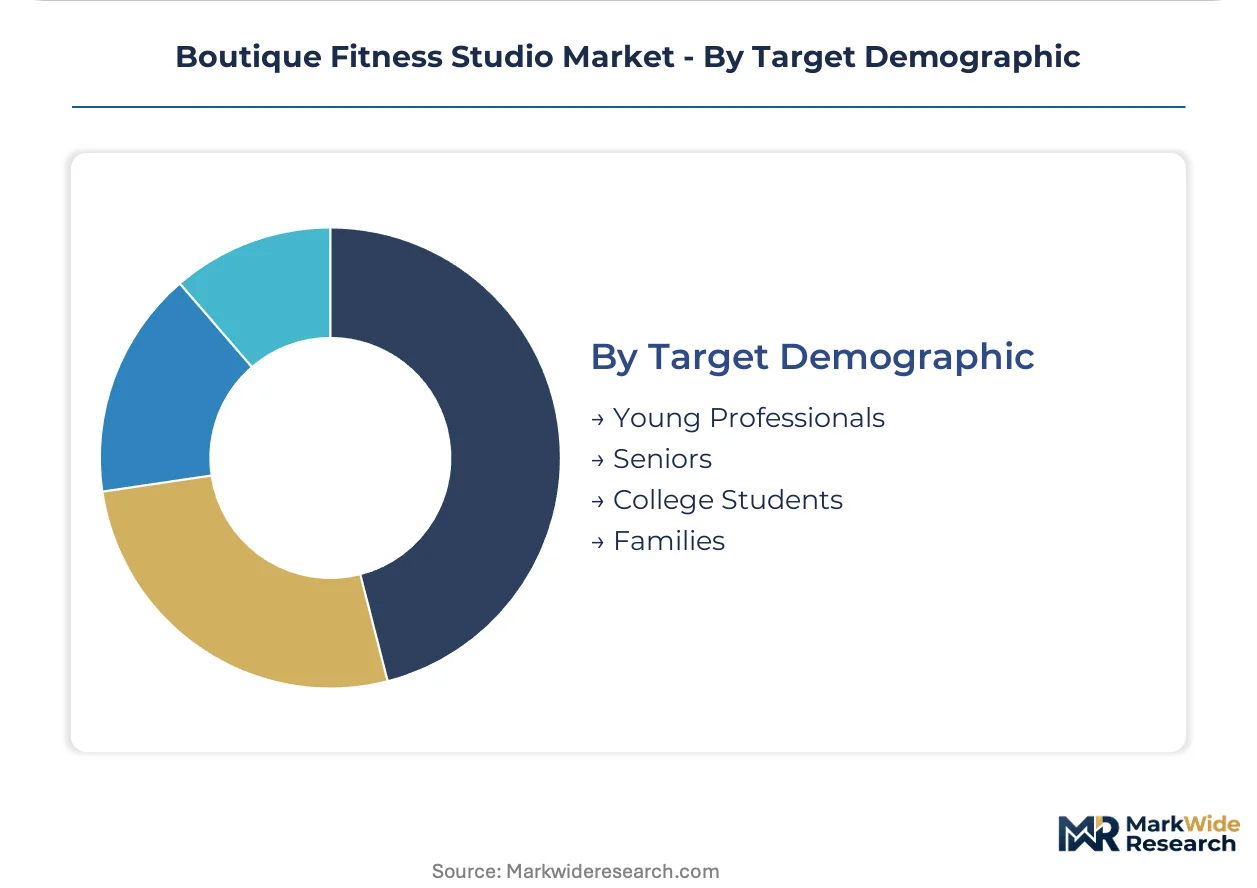
Target Demographic:
Lifetime value calculations and format preferences reshape studio location and programming decisions.
- Young Professionals:Pre-work and post-work time slots drive peak utilization with premium pricing tolerance. LinkedIn and Instagram integration amplifies referral networks and social proof mechanics.
- Seniors:Low-impact formats and balance-focused programming address fall prevention and chronic condition management. Medicare Advantage fitness benefits increasingly subsidize participation.
- College Students:Campus-adjacent locations and semester-aligned pricing capture price-sensitive demand with high churn. University recreation center partnerships reduce standalone real estate requirements.
- Families:Childcare integration and parent-child class formats extend addressable hours. Suburban franchise operators prioritize this segment for weekend volume and retention.
Spending concentration rests with Young Professionals; demographic expansion is broadest among Seniors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Austin, Denver, and designated wellness corridors concentrate studio development through municipal tax abatements. These incentives compress lease burdens and accelerate franchise penetration into suburban catchments.
United States
Urban millennials and Gen Z professionals drive specialized format demand across dense metropolitan clusters. FDA oversight of wearable biometric devices shapes technology deployment in New York and Los Angeles studios. Manhattan and Brooklyn absorb 35-40% of operating budgets through prime retail rents exceeding $80 per square foot annually.
Canada
Employer wellness stipends integrate with autopay systems to sustain monthly subscription retention. Health Canada guidelines govern marketing claims around cardiovascular benefit quantification. Toronto and Vancouver anchor studio density with cycling formats competing on commuter convenience.
United Kingdom
Reformer-based Pilates commands premium per-session pricing through equipment capital requirements and instructor certification scarcity. GDPR-aligned privacy frameworks constrain biometric data collection practices. London's fitness corridor sustains boutique penetration through affluent suburban catchments.
Germany
Corporate wellness partnerships substitute for individual annual commitments in major metropolitan employers. CE marking requirements apply to imported wearable transmission systems. Berlin and Munich concentrate studio development through mixed-use retail redevelopment zones.
Australia
Medicare Advantage fitness benefits increasingly subsidize senior participation in low-impact formats. TGA oversight applies to heart-rate monitoring devices marketed with specific health claims. Sydney and Melbourne sustain premium pricing tolerance through coastal affluent demographics.
Boutique Fitness Studio Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around franchise scalability, premium equipment intensity, and technology integration depth. Three archetypes dominate: multi-format franchise holding companies, single-format premium specialists, and technology-enabled subscription platforms. Geographic expansion and biometric data monetization represent the dominant competitive vectors reshaping capital deployment decisions.
Within the franchise-scalability tier, Burn Boot Camp and OrangeTheory Fitness exemplify rapid suburban penetration models. Club Pilates anchors the premium reformer-based segment through consistent instructor certification standards. These three entities occupy positions that reflect divergent bets on equipment intensity versus throughput volume.
| Leading Market Players |
|---|
| StretchLab |
| Burn Boot Camp |
| Club Pilates |
| Pure Barre |
| HOTWORX |
| OrangeTheory Fitness |
| JETSET Pilates |
| 9Round |
| F45 Training |
| Others |
Value Network & Pricing Analysis
Urban millennials and Gen Z professionals cluster in dense metropolitan corridors where subscription autopay integration with employer wellness stipends anchors the dominant monthly recurring revenue model. This buyer concentration compresses price elasticity and rewards studios that bundle biometric hardware with membership tiers.
Pricing Analysis
Premium-mid-economy pricing differentiation separates reformer-based Pilates studios from high-throughput cycling formats and budget boot camp operators. Lead-time-driven pricing angles reward studios with certified instructor pipelines and equipment financing already in place, commanding 15-25% per-session premiums over entrants facing 6-12 month instructor certification delays. Price differentiation hinges on equipment capital intensity and instructor credential tier, with FDA-cleared biometric systems and 500-hour Pilates certifications sustaining top-tier positioning. Cost compression in cycling formats is intensifying because standardized bike fleets and 45-minute class structures enable rapid capacity scaling. Sporadic users and seasonal demand segments exhibit highest price sensitivity, while young professionals with employer wellness subsidies demonstrate lowest sensitivity to per-session rate increases.
Supply Chain Analysis
Regional distribution centers for reformer apparatus concentrate in Germany and Italy, where Balanced Body and Gratz Industries maintain fabrication facilities serving North American and European studio networks. Hub-and-spoke patterns for wearable biometric devices draw from Taiwan and South Korea, with Polar and Garmin transmission protocols assembled through FCC-compliant facilities before customs clearance into US metropolitan markets. Raw material dependencies span aircraft-grade aluminum for reformer frames, Bluetooth Low Energy chipsets for heart-rate monitors, and specialized flooring systems for vibration dampening. Single-source vulnerability concentrates in 500-hour Pilates certification programs with limited annual cohort capacity, constraining instructor pipeline expansion. Distribution runs through franchise development networks for multi-unit operators and direct-to-studio procurement for independent owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in boutique fitness is accelerating into a vertical-integration race as operators pursue captive supply chains for certified instructors and proprietary biometric technology stacks. Control over these upstream levers separates scalable franchise models from margin-constrained independents.
For Market Incumbents: Deepen instructor certification pipeline ownership through captive training academies and apprenticeship structures, insulating against 18-month average tenure burnout at high-volume cycling studios. Pursue backward integration into wearable hardware development or exclusive licensing agreements with Polar and Garmin to lock in FCC-compliant transmission protocols before regulatory scrutiny intensifies. These moves defend against emerging technology-enabled subscription platforms and substitution by connected home fitness equipment.
For New Entrants and Emerging Players: The price-point gap between premium reformer-based studios and economy cycling formats opens white-space targeting for mid-tier hybrid formats combining strength training with low-impact recovery modalities. Underserved suburban corridors in Austin and Denver opportunity zones offer lowest customer acquisition costs through municipal tax abatements. Medicaid fitness integration in several states creates reimbursement pathway positioning for medically-affiliated studios targeting diabetes prevention and obesity management programming.
For Investors and Strategic Acquirers: The window for entry favors technology-enabled platforms with AI-generated programming capabilities and biometric data monetization infrastructure already deployed. Long-term viability across the projection horizon rests on studios demonstrating retention metrics above industry benchmarks through community programming rather than pricing lock-in. Acquisition targets should exhibit proprietary instructor certification standards and established corporate wellness partnerships. The signal to watch is FDA enforcement sweep intensity targeting unsubstantiated metabolic claims, which will accelerate consolidation among non-compliant independent operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Instructor Certification Academy Development | Captive pipeline reduces 500-hour certification bottlenecks and turnover replacement costs. |
| Biometric Data Platform Integration | FCC-compliant systems enable ancillary revenue from health insurers and corporate wellness programs. |
| Corporate On-Site Deployment Partnership | Employer contracts in Austin and Los Angeles bypass consumer acquisition cost structures. |
| Medicaid Reimbursement Pathway Establishment | Qualified programming for diabetes prevention opens state-level revenue diversification. |
| AI-Generated Programming Investment | Machine learning platforms analyze member biometric histories to auto-generate personalized retention mechanics. |
Research Methodology
Document review covered SEC filings of publicly traded fitness operators, municipal zoning board records in New York and Austin, and FDA guidance documents on general wellness devices, complemented by interviews with studio franchise development officers, Pilates certification program directors, corporate wellness benefit managers, and commercial real estate brokers specializing in retail fitness leasing. Secondary validation drew from FCC equipment authorization databases, health department inspection records, and trade association membership surveys. Bottom-up studio count estimates triangulated against top-down metropolitan market sizing.
Cross-reference between historical subscription retention patterns and expert panel input on post-pandemic demand elasticity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include studio type, service offering, membership model, and target demographic, with geographic regulatory cluster as an additional industry-specific layer. CAGRs were derived through trend extrapolation adjusted for municipal incentive program rollouts and wearable technology penetration curves. Forecast inputs incorporated instructor certification pipeline capacity constraints and prime retail rent absorption rates in Manhattan and Brooklyn.
Inputs from studio operators and certification program administrators were available through the study window; gaps in proprietary biometric data monetization contract terms introduce uncertainty bands around ancillary revenue projections. Forecasts reflect documented assumptions on municipal tax abatement program continuity and FDA enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
South America Health and Fitness Club Market