
 Aqua Gym Equipment Market | 2026-2036
Aqua Gym Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aqua Gym Equipment Market Intelligence
Connected sensor integration in aquatic bikes and resistance systems is reshaping how trainers and therapists monitor real-time biomechanical feedback during submerged workouts. HYDRO-FIT, Inc. leverages its long-standing specialization in water aerobics gear to sustain brand loyalty among institutional buyers across North American fitness centers. HydroWorx International, Inc. anchors its competitive position through advanced underwater treadmill technology that dominates rehabilitation clinic procurement cycles. BECO-Beermann GmbH & Co. KG competes aggressively on manufacturing scale, controlling cost-efficient production of rubber and foam accessories for European mass-market distribution.
Aqua gym equipment encompasses specialized apparatus engineered for resistance-based exercise in submerged environments, typically constructed from corrosion-resistant plastics, closed-cell foam, marine-grade rubber, or stainless steel with buoyancy-calibrated designs to exploit water viscosity for load modulation. The primary commercial purpose centers on delivering low-impact cardiovascular conditioning and musculoskeletal rehabilitation where gravity-induced joint stress must be minimized. Resistance equipment and aquatic bikes command the deepest margin pools due to higher unit values and replacement part ecosystems, while water aerobics gear occupies volume leadership through accessible price points that penetrate school and home user segments. Rehabilitation applications lead end-use demand structurally, though weight loss programming at fitness centers represents the fastest-growing application channel as aquatic HIIT protocols gain professional trainer certification.
FDA clearance requirements for medical-grade aquatic rehabilitation equipment shape product development timelines and clinical marketing claims in the United States, while the EU's REACH chemicals framework and CE marking obligations govern foam additive formulations and stainless steel surface treatments for European market access. Germany's KBA-influenced product safety culture extends into municipal procurement standards that elevate testing rigor for publicly tendered pool installations. Stakeholders must monitor how evolving ISO standards for aquatic fitness equipment interoperability with digital health platforms will determine which manufacturers retain institutional contract eligibility versus facing exclusion from integrated wellness system architectures.
Market Dynamics
The EU Green Deal's material mandates are forcing equipment manufacturers to reformulate foam and plastic compositions, creating a structural cost pressure that reshapes procurement eligibility for municipal wellness contracts across Europe.
Growth Catalysts
- REACH Chemicals Framework:Reformulation requirements for corrosion-resistant plastics and closed-cell foam additives are accelerating R&D investment in bio-based marine-grade rubber alternatives that meet CE marking obligations for European market access.
- Rehabilitation Clinics:Institutional buyers are expanding aquatic therapy programs as non-invasive patient recovery modalities, creating sustained procurement cycles for underwater treadmills and resistance systems with FDA clearance pathways.
- Germany:Municipal wellness infrastructure investments and aging-population health priorities concentrate demand pull for aquatic fitness systems in publicly tendered pool installations governed by KBA-influenced safety standards.
Market Restraints
- Petrochemical Input Volatility:Closed-cell foam and marine-grade rubber production depends on petroleum-derived feedstocks, exposing margin stability to crude oil price swings that compress working capital for mid-scale manufacturers.
- Stainless Steel Supply Concentration:Marine-grade 316L stainless steel sourcing clusters with specialized metallurgical suppliers in East Asia, creating geographic concentration risk for corrosion-resistant frame components.
- Biomechanical Sensor Calibration:Submerged electronics face technical limitations in pressure-rated housing design that delay connected aquatic bike deployment timelines and inflate warranty reserve requirements.
Strategic Opportunities
- ISO Standard Evolution:Emerging interoperability requirements for aquatic fitness equipment with digital health platforms create regulatory tailwinds for manufacturers investing in API-ready sensor architectures ahead of certification mandates.
- Fitness Center Weight Loss Programming:Aquatic HIIT protocol certification by professional trainer bodies is opening emerging application channels that displace traditional land-based cardiovascular equipment in commercial gym floor plans.
- Home User Segment:Accessible price points for water aerobics gear are penetrating residential pools in suburban North American markets, creating channel innovation through direct-to-consumer buoyancy-calibrated accessory bundles.
Industry Challenges
- FDA 510(k) Clearance Timelines:Medical-grade aquatic rehabilitation equipment faces certification complexity that extends product development cycles and restricts clinical marketing claims until predicate device equivalence is established.
- Submerged Electronics Integration:Legacy pool infrastructure lacks connectivity backbones for real-time biomechanical feedback systems, forcing equipment makers to bundle installation retrofit costs that inflate total contract values.
- Polymer Formulation Talent Scarcity:Specialized expertise in buoyancy-calibrated corrosion-resistant material science remains concentrated among aging technical workforces in European compound manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aqua Gym Equipment Market |
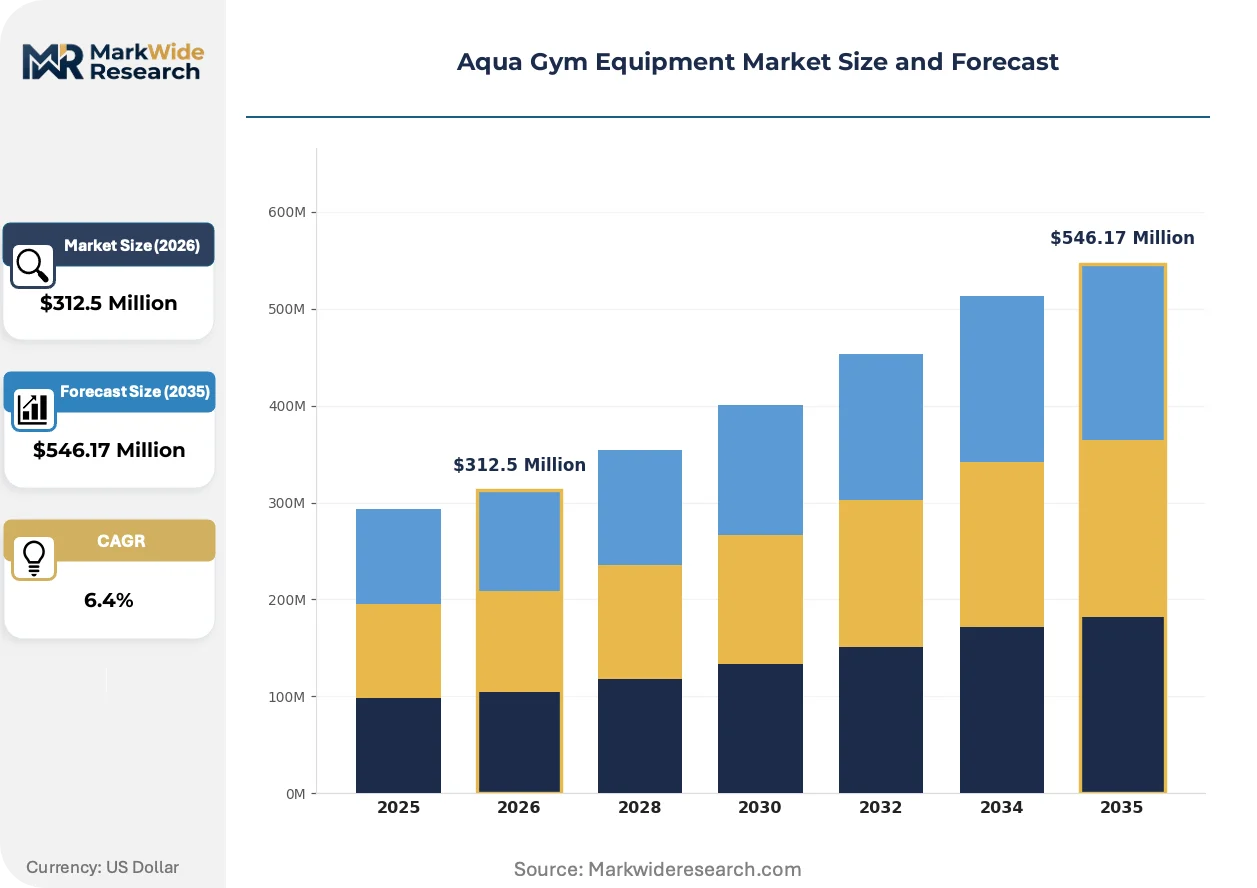
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistance Equipment, Water Aerobics Gear, Pool Noodles, Aquatic Bikes End User: Fitness Centers, Rehabilitation Clinics, Home Users, Schools Application: Rehabilitation, Weight Loss, Muscle Toning, Endurance Training Material: Plastic, Rubber, Foam, Stainless Steel |
| Companies Covered | HYDRO-FIT, Inc., TEXAS REC, HydroWorx International, Inc., PlayCore, Inc., AquaJogger, Acquapole S.a.s., Sprint Aquatics, Aqua Creek Products, BECO-Beermann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aqua Gym Equipment Market Strategic Shifts & Innovations
Connected sensor architectures and sustainable material reformulation are converging to redefine competitive positioning in aquatic fitness equipment, with regulatory compliance and buyer procurement sophistication accelerating technology adoption curves.
Submersible pressure-rated sensor arrays embedded in aquatic bikes and resistance systems are digitizing real-time biomechanical feedback capture for trainers and therapists monitoring submerged workouts. Rehabilitation clinics in Germany and the United States are piloting these installations at accelerated procurement cycles. The structural consequence is compressing equipment replacement timelines as institutions demand API-ready interoperability with electronic health record platforms.
REACH chemicals framework amendments governing foam additive formulations and stainless steel surface treatments are tightening compliance windows for European market access. Equipment makers must reformulate closed-cell foam compositions and submit updated technical documentation to notified bodies for CE marking renewal. Aquatic accessory manufacturers serving mass-market distribution face the most acute reformulation cost absorption pressures.
Institutional procurement committees at municipal wellness facilities are consolidating vendor relationships around integrated wellness system architectures that bundle aquatic fitness equipment with digital health platform subscriptions. Fitness center chains in North America are displacing standalone equipment purchases with multi-year service contracts that include preventive maintenance and software updates. This pattern is most visible in Germany, where KBA-influenced municipal procurement standards elevate testing rigor and favor vendors with demonstrated interoperability certification.
Aqua Gym Equipment Market Segmentation
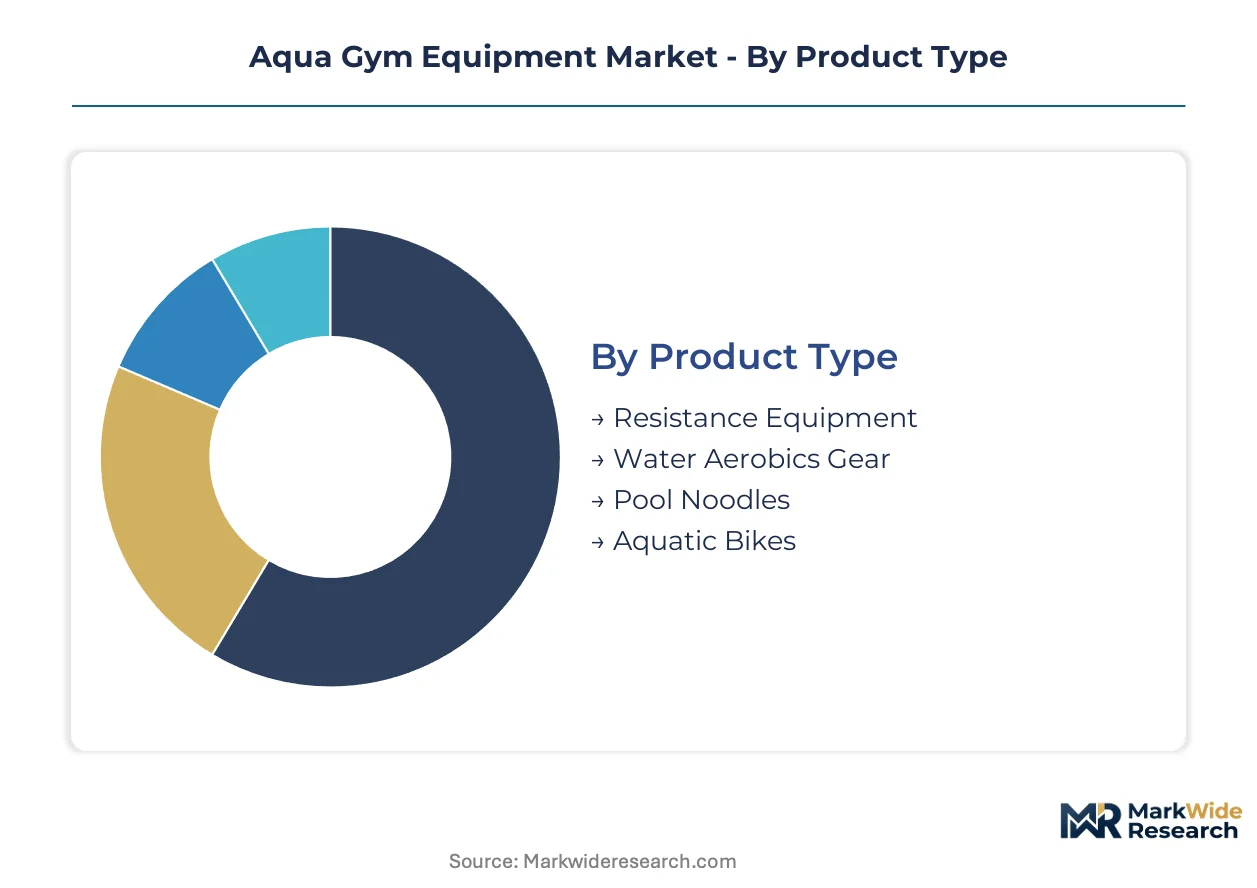
Equipment configuration and material specification in aquatic fitness create distinct service ecosystems. Each segment demands specialized maintenance protocols and replacement part availability that shape vendor profitability and buyer loyalty.
Product Type:
After-sales intensity varies sharply across product categories, with precision mechanical systems requiring technical support contracts that generate recurring revenue streams for manufacturers.
- Resistance Equipment:Comprising drag fins, water dumbbells, and tether systems engineered with marine-grade rubber and closed-cell foam for calibrated viscosity resistance. Demand concentrates in German rehabilitation clinics where KBA-influenced municipal procurement standards mandate documented durability testing and preventive maintenance schedules.
- Aquatic Bikes:Submersible stationary cycles with pressure-rated sensor housings and corrosion-resistant drive trains designed for submerged biomechanical feedback capture. Fitness centers in North America are expanding procurement of connected models that integrate with electronic health record platforms, though submerged electronics calibration delays deployment timelines.
- Water Aerobics Gear:Buoyancy belts, cuffs, and barbells constructed from closed-cell foam formulations meeting REACH chemical framework additive restrictions. Schools and municipal pools drive volume through accessible price points and minimal maintenance requirements.
- Pool Noodles:Extruded polyethylene foam cylinders for basic flotation support and beginner resistance exercises. Residential pool owners and school physical education programs constitute the primary demand base.
By volume, water aerobics gear leads. By growth pace, aquatic bikes are climbing the fastest.
End User:
Procurement sophistication diverges across buyer types, with institutional purchasers demanding interoperability certification and home users prioritizing direct-to-consumer accessibility.
- Rehabilitation Clinics:FDA-cleared aquatic therapy installations featuring underwater treadmills and sensor-integrated resistance systems for non-invasive patient recovery protocols. German and US clinical buyers dominate procurement cycles with multi-year service contracts bundling equipment and software subscriptions.
- Fitness Centers:Commercial gyms deploying aquatic HIIT stations and group exercise configurations to differentiate cardiovascular programming. North American chains are displacing land-based equipment with submerged alternatives as professional trainer certification expands.
- Home Users:Residential pool owners purchasing buoyancy-calibrated accessory bundles through direct-to-consumer channels. Suburban North American markets show particular penetration for water aerobics gear at accessible price points.
- Schools:Educational institutions sourcing basic resistance equipment and pool noodles for physical education curricula and adaptive sports programs. Municipal procurement committees govern purchasing with standardized safety specifications.
Rehabilitation clinics command the highest contract values. Fitness centers are expanding most quickly as aquatic HIIT protocols gain certification traction.
Application:
Clinical outcomes versus wellness programming creates divergent equipment specifications and replacement cycle patterns across use cases.
- Rehabilitation:Medically supervised musculoskeletal recovery protocols utilizing underwater treadmills and sensor-monitored resistance systems to minimize gravity-induced joint stress. German rehabilitation clinics and US physical therapy centers anchor demand with insurance-reimbursable treatment modalities.
- Weight Loss:Aquatic HIIT and cardiovascular conditioning programs exploiting water viscosity for elevated caloric expenditure without impact loading. Fitness centers in North America are the primary growth channel as professional trainer bodies certify submerged interval protocols.
- Muscle Toning:Resistance-based strength training using drag fins and water dumbbells for concentric-focused load application. Municipal wellness facilities and home users share demand with accessible equipment price points.
- Endurance Training:Sustained aerobic conditioning through aquatic bikes and tethered swimming systems for low-impact cardiovascular development. Competitive swimmers and aging fitness populations drive specialized procurement.
Rehabilitation generates the deepest margin pools. Weight loss programming is gaining share fastest as commercial gym floor plans reconfigure.
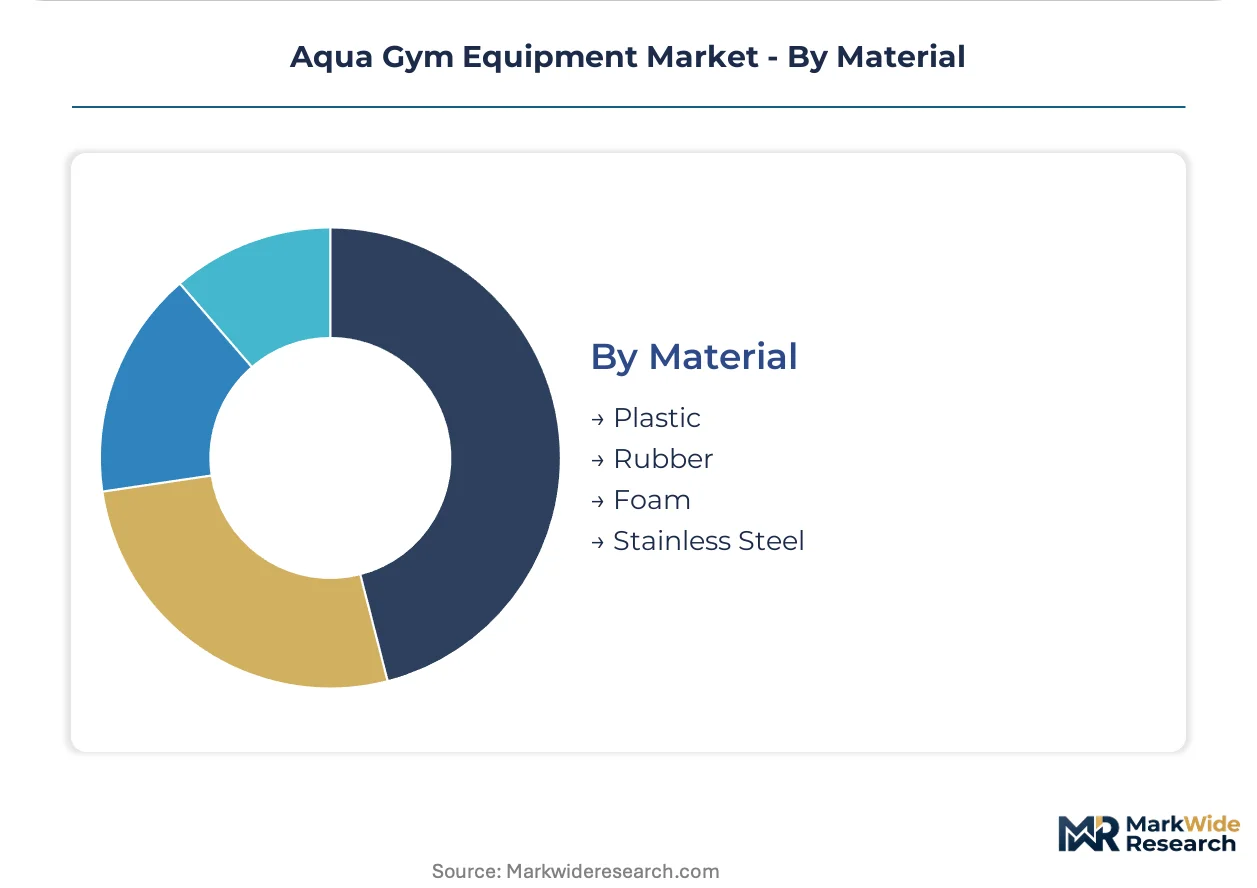
Material:
REACH chemicals framework amendments and EU Green Deal mandates are forcing reformulation timelines that reshape supplier relationships and cost structures.
- Stainless Steel:Marine-grade 316L alloys for frame components and underwater treadmill structures requiring corrosion resistance in chlorinated environments. Sourcing concentration in East Asian metallurgical suppliers creates geographic vulnerability for European and North American equipment makers.
- Foam:Closed-cell polyethylene and EVA formulations for buoyancy devices and protective padding subject to REACH additive restrictions and bio-based replacement R&D. Mass-market accessory manufacturers face acute reformulation cost absorption pressures.
- Rubber:Marine-grade elastomers for resistance bands, tether systems, and sealed component housings. Petrochemical feedstock volatility exposes margin stability to crude oil price swings.
- Plastic:Corrosion-resistant thermoplastics for housing enclosures and structural components in non-load-bearing applications. EU Green Deal sustainable manufacturing mandates accelerate recycled content integration requirements.
Plastic dominates production volume. Stainless steel commands the steepest expansion trajectory as connected equipment integration demands precision metalwork.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export aquatic rehabilitation systems to rehabilitation clinics across the United States and North American fitness chains, establishing the primary transatlantic trade corridor for precision-engineered submerged fitness equipment.
United States
FDA-cleared underwater treadmills anchor procurement at rehabilitation clinics in Florida and Arizona, where aging demographics drive insurance-reimbursable aquatic therapy expansion. Medicare reimbursement codes for hydrotherapy influence equipment specification standards. Physical therapy chains in the Southwest concentrate demand for sensor-integrated resistance systems.
Germany
KBA-influenced municipal procurement standards govern publicly tendered pool installations in Bavaria and North Rhine-Westphalia, elevating testing rigor for aquatic fitness systems. REACH chemicals framework amendments force foam additive reformulation timelines for CE marking renewal. Stuttgart-area metallurgical suppliers specialize in marine-grade 316L stainless steel for corrosion-resistant frame components.
Japan
PMDA medical device classification requirements shape development timelines for aquatic rehabilitation equipment targeting geriatric care facilities. METI subsidies for senior wellness infrastructure accelerate municipal pool modernization in the Kansai region. Osaka-based fabricators supply buoyancy-calibrated accessories to domestic fitness chains and export markets.
China
Dual carbon goals under MEE oversight accelerate recycled plastic content mandates for fitness equipment manufacturing in the Yangtze River Delta. NMPA medical device registration creates compliance pathways for rehabilitation-grade aquatic systems. Shanghai-area compound manufacturers develop bio-based marine-grade rubber alternatives to REACH-restricted formulations.
Australia
TGA medical device standards govern therapeutic aquatic equipment imports for physiotherapy networks in New South Wales and Victoria. Municipal wellness infrastructure investments in Queensland prioritize corrosion-resistant designs for chlorinated outdoor pool environments. Sydney-based distributors consolidate procurement relationships with German and US equipment makers.
Aqua Gym Equipment Market Key Industry Players
On the supply side, the industry is moderately concentrated around specialized manufacturers with distinct capability anchors in rehabilitation technology, mass-market foam accessories, and connected sensor integration. Three archetypes dominate: precision rehabilitation system builders, high-volume foam and rubber accessory producers, and emerging digital fitness platform integrators. Competitive moves center on strategic partnerships with electronic health record vendors and backward integration into sustainable polymer formulation.
Within the rehabilitation-specialist tier, HydroWorx International, Inc. and HYDRO-FIT, Inc. exemplify divergent positioning—one anchoring clinical-grade underwater treadmill technology, the other sustaining institutional loyalty through water aerobics specialization. BECO-Beermann GmbH & Co. KG occupies the scale-driven manufacturing position, representing European mass-market distribution efficiency for rubber and foam accessories subject to REACH reformulation pressures.
| Leading Market Players |
|---|
| HYDRO-FIT, Inc. |
| TEXAS REC |
| HydroWorx International, Inc. |
| PlayCore, Inc. |
| AquaJogger |
| Acquapole S.a.s. |
| Sprint Aquatics |
| Aqua Creek Products |
| BECO-Beermann GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Overcapacity in East Asian foam compound manufacturing is pressuring margin structures across European and North American equipment tiers, forcing suppliers to absorb reformulation costs while buyers consolidate procurement around bundled service contracts.
Pricing Analysis
Current-generation connected aquatic bikes with pressure-rated sensor housings command substantial premiums over prior-generation mechanical units, while next-generation API-integrated systems are entering pilot pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared rehabilitation systems from fitness-center grade equipment and mass-market water aerobics accessories. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because REACH-mandated foam reformulation is squeezing mid-scale manufacturers. Schools and municipal pools exhibit highest price sensitivity; rehabilitation clinics demonstrate lowest sensitivity due to insurance reimbursement structures.
Supply Chain Analysis
Extended payment terms from German municipal procurement committees are forcing working capital stress onto component suppliers, particularly foam compound manufacturers facing REACH compliance deadlines. Marine-grade 316L stainless steel draws from East Asian metallurgical clusters; closed-cell foam formulations rest on European petrochemical feedstocks; bio-based rubber alternatives are emerging from Shanghai-area R&D facilities. Single-source vulnerability concentrates in specialized pressure-rated sensor housing fabrication. Distribution runs through institutional procurement committees at municipal wellness facilities and direct-to-consumer channels for residential accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aqua gym equipment is fundamentally a service-attach opportunity where preventive maintenance contracts and software subscription layers are expanding faster than hardware unit sales, particularly in German rehabilitation clinic procurement cycles.
For Market Incumbents: Build certification moats by accelerating FDA 510(k) pathway investments for next-generation underwater treadmills before predicate device equivalence windows narrow. Consolidate position through backward integration into sustainable polymer formulation to deflect REACH reformulation cost pressures. Lock in multi-year service contracts with North American fitness center chains displacing land-based equipment.
For New Entrants and Emerging Players: Mid-market aquatic HIIT stations in suburban North American fitness centers represent the most penetrable entry point, as professional trainer certification expands and floor-plan reconfiguration creates procurement openings. Target direct-to-consumer buoyancy-calibrated accessory bundles for residential pool owners through digital-native channel strategies bypassing institutional procurement gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision rehabilitation system builders with established hospital system partnerships and FDA-cleared installed bases. Long-term viability favors manufacturers with demonstrated interoperability certification ahead of ISO standard mandates. Watch for inflection signals in municipal wellness infrastructure bond issuance volumes in Bavaria and North Rhine-Westphalia.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Reformulation | European foam additive reformulation secures CE marking renewal and municipal procurement eligibility. |
| API-Ready Sensor Architecture | Interoperability certification with electronic health record platforms determines institutional contract retention. |
| Preventive Maintenance Contract Bundling | Multi-year service agreements with German rehabilitation clinics generate recurring revenue beyond hardware sales. |
| Bio-Based Marine-Grade Rubber R&D | Shanghai-area compound development addresses petrochemical feedstock volatility and EU Green Deal mandates. |
| Aquatic HIIT Trainer Certification | Professional body credentialing expands fitness center application channels displacing land-based equipment. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aquatic therapy program directors, municipal procurement committee members, biomedical engineers specifying rehabilitation equipment, fitness center operations managers, and foam compound manufacturing technical directors. Secondary validation drew from FDA 510(k) device filings, REACH technical documentation submissions to ECHA, German municipal tender databases, hospital GPO contract repositories, and Medicare hydrotherapy reimbursement code updates. Bottom-up equipment shipment data triangulated against top-down wellness infrastructure investment flows.
Calibration anchored volume and value outputs to documented procurement cycles, material cost trajectories, and regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, application purpose, material specification, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical installation data and forward infrastructure commitment announcements. Industry-specific forecast inputs incorporated KBA-influenced municipal testing standards and PMDA medical device classification pathways.
Macroeconomic conditions sit as an overlay; deviation in municipal bond issuance volumes, crude oil price trajectories, or Medicare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance windows and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
Australia Gym Accessories Market