
 Smart Gym Equipment Market | 2026-2036
Smart Gym Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Gym Equipment Market Analytics
EU energy efficiency standards under the Ecodesign Directive are decoupling smart gym equipment procurement from traditional power-hungry analog alternatives. Peloton leverages its vertically integrated content platform to sustain subscriber retention alongside hardware sales. NordicTrack anchors North American distribution through its parent company's retail channel density. Tonal differentiates via electromagnetic resistance technology that eliminates physical weight stacks.
Smart gym equipment encompasses digitally connected fitness machines integrating IOT sensors, biomechanical feedback systems, and cloud-based performance analytics to deliver adaptive training protocols. Units typically incorporate load cells measuring force output within one-percent accuracy, enabling real-time form correction and progressive overload programming. Connected Fitness Systems command the widest margin pools by bundling recurring subscription revenue with hardware sales. Smart Weights represent the fastest-expanding product category as space-constrained urban consumers prioritize compact form factors. AI Personal Trainers within the technology stack extract premium pricing by reducing dependence on human coaching hours.
FCC certification requirements govern wireless transmission protocols for IOT-integrated equipment sold in the United States, while CE marking mandates electromagnetic compatibility testing for European market access. The EU AI Act imposes transparency obligations on algorithmic workout recommendations, compelling vendors to document training data provenance and decision logic. Stakeholders must monitor evolving interoperability standards between proprietary platforms and third-party wearable sensors, as ecosystem lock-in risks alienating institutional buyers seeking open architecture.
Market Dynamics
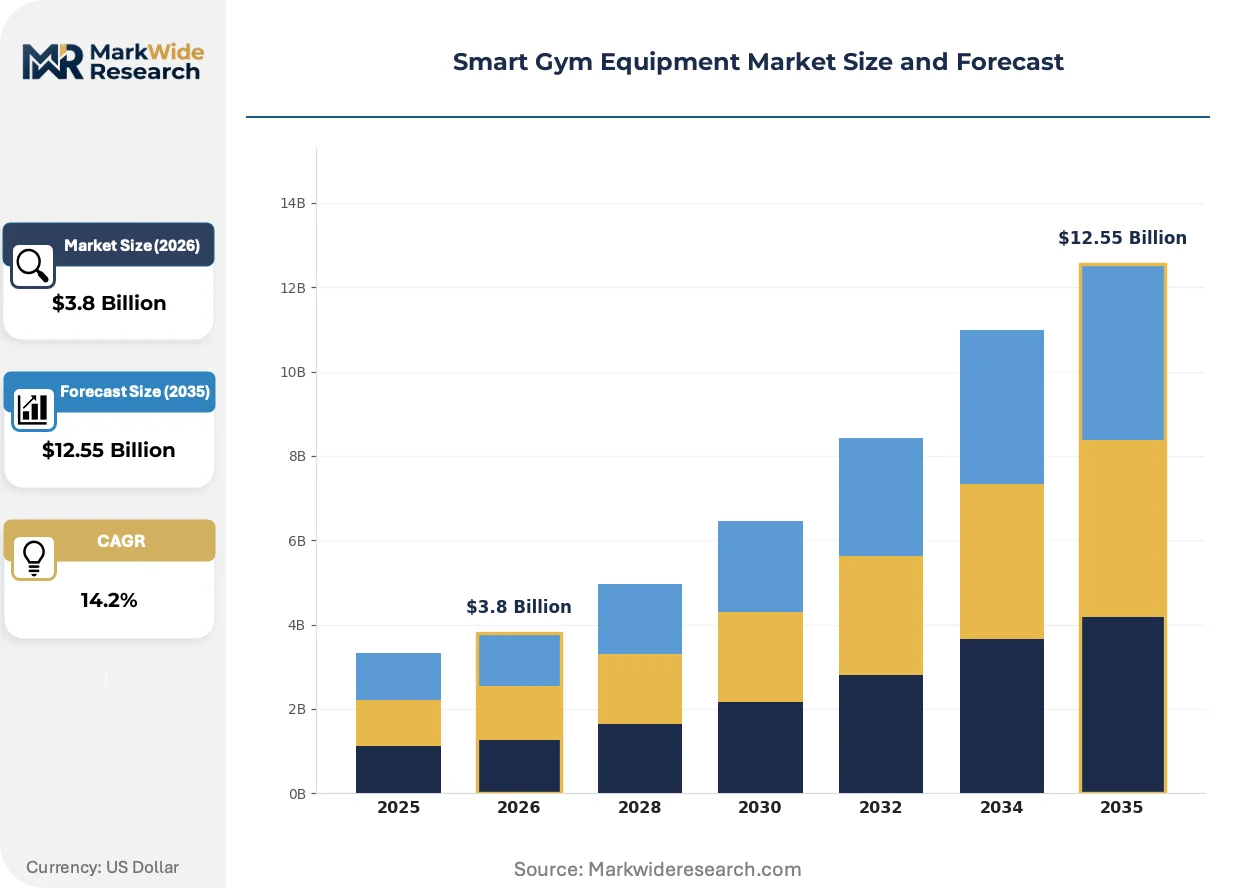
The smart gym equipment sector is undergoing a fundamental restructuring as EU energy efficiency mandates under the Ecodesign Directive force hardware redesigns while subscription bundling redefines revenue capture away from one-time equipment sales.
Growth Catalysts
- Corporate Wellness Mandates:Large employers in the United States are expanding connected fitness procurement for employee health initiatives, treating smart equipment as deductible wellness infrastructure.
- EU Green Deal Pressure:Standby power consumption limits are accelerating replacement cycles for legacy analog machines across European health clubs seeking compliance.
- Electromagnetic Resistance:Elimination of physical weight stacks via electromagnetic systems reduces mechanical failure rates and floor load requirements for urban residential buyers.
Market Restraints
- Semiconductor Supply Concentration:Load cell signal processors and Bluetooth SoCs face sourcing bottlenecks from concentrated East Asian foundry capacity.
- FCC Certification Timelines:Wireless protocol approvals for IOT-integrated equipment create 4-6 month market entry delays for new hardware SKUs.
- Human Coaching Substitution:Budget-conscious consumers retain preference for traditional personal training, limiting AI trainer penetration in price-sensitive segments.
Strategic Opportunities
- Space-Constrained Urban Dwellers:Compact smart weights targeting Tokyo, Singapore, and New York City apartments address square-footage limitations that bar traditional home gym setups.
- Interoperability Standards:Open API architectures enabling third-party wearable sensor integration create wedge opportunities against ecosystem-locked incumbents.
- EU AI Act Compliance Services:Transparency documentation for algorithmic workout recommendations represents an adjacent revenue stream for vendors with proven training data governance.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time biomechanical feedback programming requires specialized expertise in signal processing and edge computing that outpaces current workforce supply.
- Cloud Infrastructure Capex:Maintaining sub-100ms latency for live class streaming demands distributed server investments that strain mid-tier vendor balance sheets.
- CE Marking Electromagnetic Testing:Compatibility certification for European market access involves iterative redesign cycles that compress already narrow hardware margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Gym Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Treadmills, Smart Bikes, Smart Weights, Connected Fitness Systems Technology: IOT Integration, Wearable Sensors, AI Personal Trainers, Mobile Applications End User: Fitness Enthusiasts, Personal Trainers, Health Clubs, Corporate Gyms Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Fitness Equipment Distributors |
| Companies Covered | Peloton, MaxPro, Tonal, Aviron, Bowflex, Speediance, NordicTrack, Vitruvian, Tempo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Gym Equipment Market Evolving Landscape
Hardware-software bundling is converging with biometric sensor proliferation to transform equipment vendors into recurring-revenue platforms, while regulatory pressure on algorithmic transparency and energy consumption accelerates technical differentiation.
Computer vision form correction is converging with edge-deployed neural networks to enable real-time rep counting and posture alerts without cloud dependency. Boutique studio chains in the United States are piloting these systems to reduce instructor headcount per class. The technology is converging with existing camera infrastructure to compress the cost premium versus sensor-laden alternatives.
The EU AI Act's transparency obligations for algorithmic workout recommendations are forcing vendors to document training data provenance and decision logic. This regulatory friction is elevating compliance costs for smaller hardware manufacturers. European institutional buyers are now requiring algorithmic audit trails as standard procurement criteria, privileging established vendors with dedicated governance functions.
Residential buyers are unbundling after-sales service contracts from hardware purchases, preferring manufacturer-direct troubleshooting over third-party maintenance agreements. This behavioral shift is compressing dealer margin pools in North American distribution channels. Health club chains remain the exception, negotiating captive service agreements to minimize equipment downtime liability.
Smart Gym Equipment Market Segmentation
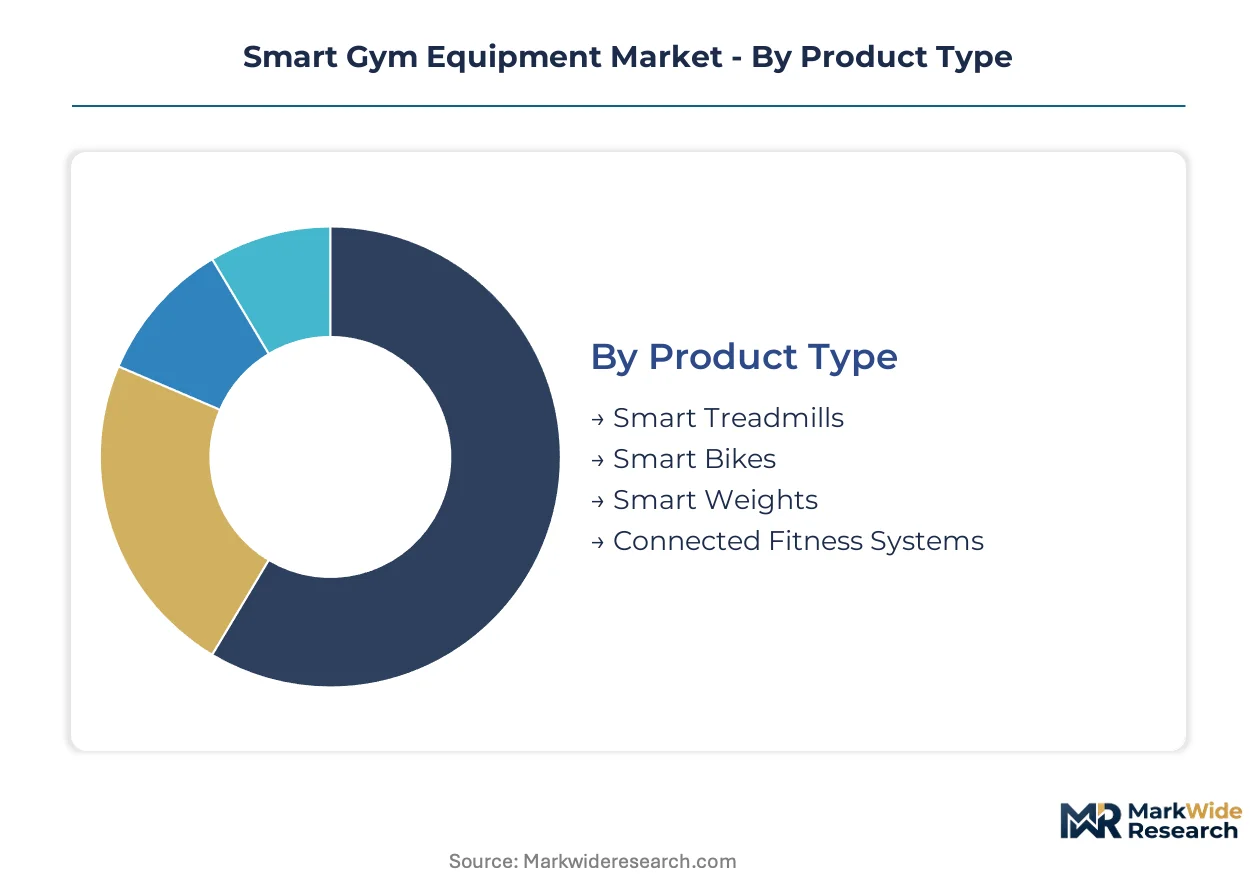
Smart gym equipment procurement patterns diverge sharply across buyer sophistication, space constraints, and subscription appetite. Segmentation reveals where hardware margins concentrate versus where recurring revenue platforms capture lifetime value.
Product Type:
Purchase decisions in this category pivot on floor space requirements and content bundling willingness.
- Smart Treadmills:Deck-integrated shock absorption systems and incline motors rated for continuous duty cycles define technical specifications. Demand clusters in United States suburban households where dedicated home gym rooms accommodate 7-foot footprints, though electromagnetic drive maintenance costs deter some commercial buyers.
- Smart Bikes:Magnetic resistance flywheels with wattage accuracy within 2% enable power-based training protocols. United States health club chains and boutique studios drive procurement volume, with flywheel weight preferences splitting between 35-pound home units and 40-plus-pound commercial variants.
- Smart Weights:Adjustable load mechanisms replacing 16 individual dumbbells address Tokyo and New York City apartment square-footage constraints. Space-constrained urban dwellers prioritize compact form factors that eliminate traditional rack storage.
- Connected Fitness Systems:Wall-mounted electromagnetic resistance units with integrated displays bundle hardware and content subscriptions. Corporate wellness programs treat these as deductible infrastructure for employee health initiatives.
Volume sits with Smart Bikes; growth tilts toward Smart Weights.
Technology:
Stack complexity determines whether vendors capture one-time hardware margins or recurring platform revenue.
- IOT Integration:Load cells measuring force output within one-percent accuracy enable real-time form correction. FCC certification requirements for wireless transmission protocols create 4-6 month approval delays for new hardware SKUs entering the United States market.
- Wearable Sensors:Heart rate variability and motion tracking data feed adaptive training algorithms. Interoperability standards between proprietary platforms and third-party devices remain unresolved, alienating institutional buyers seeking open architecture.
- AI Personal Trainers:Algorithmic workout recommendations reduce dependence on human coaching hours. EU AI Act transparency obligations compel vendors to document training data provenance and decision logic, elevating compliance costs.
- Mobile Applications:Cloud-based performance analytics and progressive overload programming extend hardware utility. Sub-100ms latency requirements for live class streaming strain mid-tier vendor cloud infrastructure budgets.
Revenue concentrates in IOT Integration; steepest expansion trajectory belongs to AI Personal Trainers.
End User:
Budget authority and technical sophistication separate institutional procurement from individual purchasing.
- Fitness Enthusiasts:Residential buyers with established training routines seek biomechanical feedback for progressive overload. After-sales service contract unbundling compresses dealer margin pools as troubleshooting shifts manufacturer-direct.
- Personal Trainers:Client management tools and remote form correction capabilities extend service reach. AI trainer penetration remains limited in price-sensitive segments where human coaching retains preference.
- Health Clubs:Equipment uptime liability drives captive service agreements and predictive maintenance contracts. EU Green Deal standby power consumption limits accelerate replacement cycles for legacy analog machines.
- Corporate Gyms:Employee wellness program budgets treat connected fitness systems as deductible infrastructure. Procurement decisions prioritize subscription bundling that delivers measurable engagement metrics to HR departments.
Health Clubs anchor current volume; Corporate Gyms are gaining share fastest.
Distribution Channel:
Channel selection determines margin retention and customer data ownership.
- Online Retail:Direct-to-consumer platforms capture first-party purchasing behavior and enable subscription attach at point of sale. Shipping logistics for 300-plus-pound equipment units create damage liability and white-glove delivery cost pressures.
- Specialty Stores:Hands-on trials and staff expertise justify premium pricing for complex electromagnetic resistance systems. Floor space constraints in urban retail locations limit inventory breadth.
- Direct Sales:Manufacturer-controlled channels eliminate intermediary margins and enable subscription bundling. Sales force compensation structures must balance hardware commission against recurring revenue lifetime value.
- Fitness Equipment Distributors:Bulk procurement relationships with health club chains and corporate buyers leverage existing service infrastructure. Distributor consolidation is reducing independent channel options for emerging vendors.
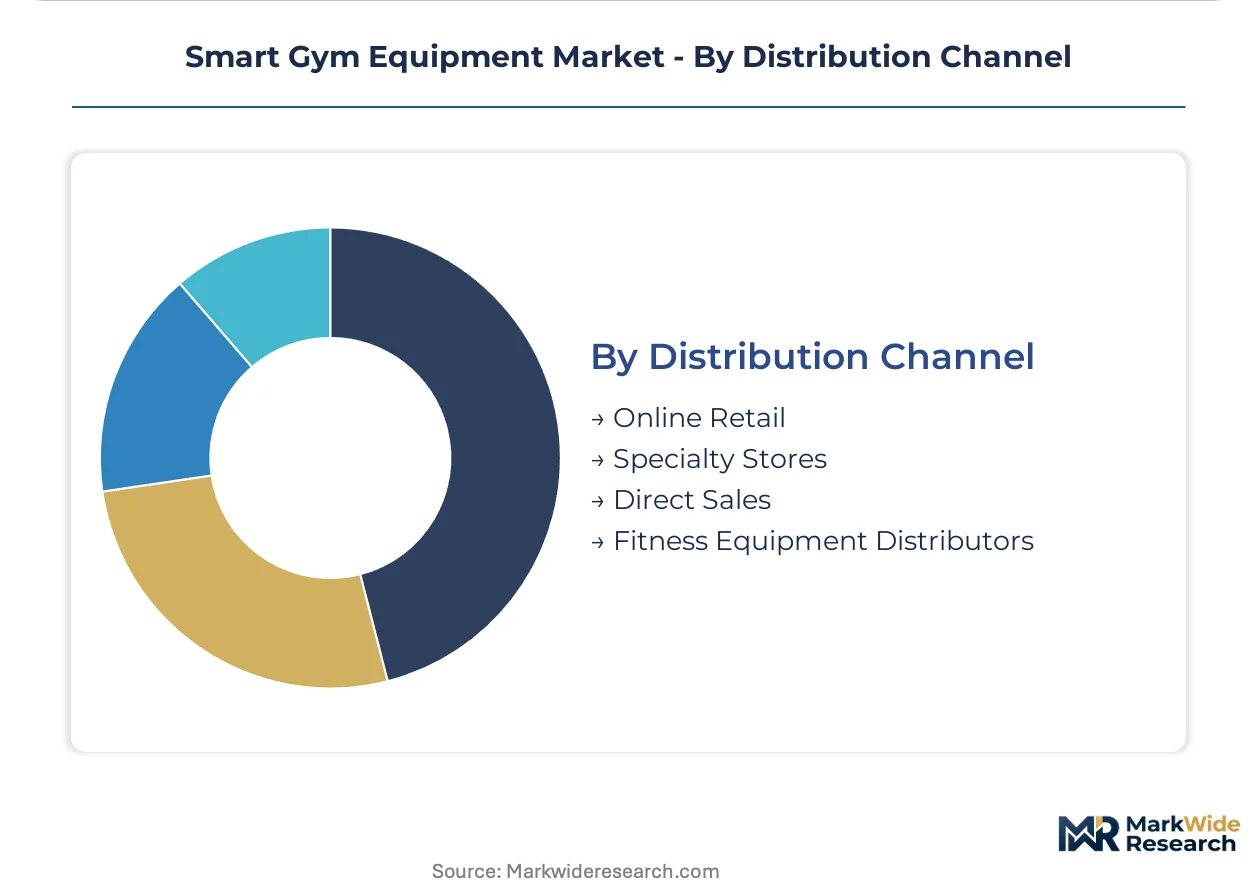
Direct Sales commands the widest margins; Online Retail shows the steepest volume climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the smart gym equipment design ecosystem, with venture-backed hardware startups clustering near sensor technology suppliers and cloud infrastructure providers. Corporate wellness procurement from Silicon Valley technology firms creates a concentrated demand node for connected fitness systems.
United States
Health club chains in Texas and Florida drive commercial procurement volume, while residential buyers in New York and Los Angeles prioritize space-efficient electromagnetic resistance systems. FCC certification timelines for wireless-enabled equipment create 4-6 month market entry delays. Austin and Miami emerge as testbed markets for AI-integrated training platforms targeting affluent urban professionals.
Germany
Industrial engineering expertise in Bavaria and Baden-Württemberg supports precision manufacturing of load cell sensors and electromagnetic drive systems. EU Green Deal standby power consumption limits accelerate replacement cycles for legacy analog machines in Frankfurt and Berlin health clubs. Munich-based fitness equipment distributors consolidate procurement relationships with corporate wellness programs.
Japan
Space-constrained Tokyo apartments generate premium demand for compact smart weights replacing traditional dumbbell racks. METI energy efficiency guidelines pressure manufacturers to reduce idle power draw in IOT-connected devices. Osaka industrial clusters specialize in miniaturized motor systems for residential fitness equipment.
United Kingdom
Boutique studio chains in London pilot computer vision form correction systems to reduce instructor headcount per class. CE marking electromagnetic compatibility testing creates iterative redesign cycles for European market access. Manchester and Birmingham distribution hubs serve corporate gym installations across the Midlands and Northern England.
Australia
Commercial health clubs in Sydney and Melbourne prioritize predictive maintenance contracts to minimize equipment downtime liability. The country's national communications regulator governs wireless transmission protocols for IOT-integrated fitness devices. Brisbane emerges as a regional service hub for Asia-Pacific warranty and technical support operations.
Smart Gym Equipment Market Competitive Landscape
The competitive structure tilts toward content-integrated hardware platforms over standalone equipment vendors. Market concentration clusters around vertically integrated players bundling subscription services with electromagnetic resistance systems. Three archetypes dominate: premium content platforms, compact space-efficient specialists, and commercial-grade durability manufacturers. Strategic moves center on backward integration into sensor manufacturing and geographic expansion through direct-to-consumer channels.
Among North American content-platform players, Peloton and Tonal exemplify the subscription-hardware bundling model. NordicTrack occupies a position within the established fitness equipment tier leveraging parent company retail channel density. Speediance represents the compact-form-factor specialist archetype targeting Asia-Pacific urban residential markets.
| Leading Market Players |
|---|
| Peloton |
| MaxPro |
| Tonal |
| Aviron |
| Bowflex |
| Speediance |
| NordicTrack |
| Vitruvian |
| Tempo |
| Others |
Value Network & Pricing Analysis
Corporate wellness procurement mandates for connected fitness systems with measurable engagement metrics are forcing manufacturers to bundle subscription revenue streams with hardware, compressing pure equipment margins while elevating total cost of ownership calculations for buyers.
Pricing Analysis
Subscription attach rates at point of sale anchor value-based pricing for connected fitness systems, with corporate wellness programs and health club chains demonstrating lowest price sensitivity due to deductible infrastructure treatment and uptime liability concerns. Three-tier pricing structure across premium electromagnetic resistance systems, standard connected bikes, and compact smart weights reflects floor space constraints and content bundling willingness. Cost compression in mid-tier hardware is intensifying because residential buyers unbundle after-sales service contracts and shift troubleshooting manufacturer-direct. Fitness enthusiasts seeking biomechanical feedback represent the most price-sensitive segment, while corporate gyms prioritize engagement metric deliverability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for load cell signal processors and Bluetooth SoCs are compelling health club chains and corporate buyers to qualify multiple East Asian foundry suppliers, extending procurement cycles but mitigating single-source vulnerability. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, with electromagnetic drive system assembly anchored in Germany and Japan. Raw material dependencies span rare earth elements for motor magnets, precision aluminum extrusions for frame construction, and high-grade copper for electromagnetic coils. Tariff exposure on Chinese electronic components represents the dominant structural risk. Distribution runs through direct-to-consumer platforms capturing first-party data, specialty stores enabling hands-on trials, and consolidated fitness equipment distributors serving institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart gym equipment sector sits in a technology-transition phase as electromagnetic resistance systems displace physical weight stacks, compressing mechanical failure rates and floor load requirements while forcing legacy manufacturers to retool production lines.
For Market Incumbents: Cement subscription retention through backward integration into sensor manufacturing and exclusive content licensing, defending against compact-form-factor specialists targeting space-constrained urban dwellers. Prioritize open API architectures to neutralize ecosystem lock-in risks alienating institutional buyers seeking wearable sensor interoperability. Capacity addition in Bavaria and Baden-Württemberg precision manufacturing clusters secures load cell supply continuity. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms with white-glove delivery capabilities targeting Tokyo and New York City apartment dwellers prioritizing compact smart weights over traditional rack storage. Space-constrained urban residential markets in Asia-Pacific represent the most penetrable geography, with electromagnetic resistance technology enabling premium positioning against established bike and treadmill incumbents. Corporate wellness procurement channels offer fastest path to volume given deductible infrastructure treatment. For Investors and Strategic Acquirers: Re-rating potential sits with electromagnetic resistance technology specialists given EU Green Deal standby power consumption mandates accelerating replacement cycles for legacy analog machines. Long-term viability favors vendors bundling recurring subscription revenue with hardware and demonstrating algorithmic transparency compliance under EU AI Act obligations. Watch for FCC certification timeline compression as signal of regulatory arbitrage capability and faster SKU velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of load cells measuring force output within one-percent accuracy reduces procurement bottlenecks from East Asian foundries. |
| Open API Architecture Development | Third-party wearable sensor integration neutralizes ecosystem lock-in risks for institutional buyers seeking interoperability. |
| EU AI Act Compliance Documentation | Algorithmic audit trails for workout recommendations satisfy transparency obligations and privilege vendors in European procurement. |
| Compact Form Factor R&D Investment | Adjustable load mechanisms replacing traditional dumbbell racks address Tokyo and New York City square-footage constraints. |
| Corporate Wellness Channel Expansion | Deductible infrastructure treatment enables subscription bundling with measurable engagement metrics for HR departments. |
Research Methodology
Trade publications, customs databases, and SEC filings formed the secondary backbone, supplemented by primary interviews with connected fitness platform executives, health club procurement directors, corporate wellness program managers, and electromagnetic drive system engineers. Bottom-up unit shipment estimates triangulated against top-down subscription revenue analysis across product type, technology stack, end user category, and distribution channel dimensions.
Historical trendline analysis of hardware shipment volumes and subscription attach rates informed projection modeling across the analysis window, with segmentation by smart treadmills, smart bikes, smart weights, and connected fitness systems. CAGRs derived from curve-fitting observed adoption patterns against corporate wellness program expansion, EU regulatory replacement cycles, and urban residential space constraints. Forecast inputs incorporated FCC certification timeline distributions, electromagnetic compatibility testing iteration cycles, and cloud infrastructure latency requirements for live class streaming.
Semiconductor supply disruptions, EU AI Act enforcement intensity, and corporate wellness budget elasticity are the dominant revision risks. Deviation in electromagnetic resistance component availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Argentina Gym Accessories Market