
 Indoor Smart Bikes Market | 2026-2036
Indoor Smart Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Smart Bikes Market Insights
Taiwanese electronics manufacturing is consolidating around precision motor control and sensor integration for connected fitness hardware. Peloton sustains brand strength through proprietary content ecosystems and direct-to-consumer channel control. Wahoo Fitness leverages open-platform compatibility to compete across multiple training software environments. NordicTrack anchors its position through parent-company manufacturing scale and in-house content production.
Indoor smart bikes are stationary cycling devices equipped with electromagnetic resistance systems, integrated power measurement sensors, and wireless connectivity protocols that transmit real-time performance data to companion applications. These machines serve commercial and residential users seeking quantified, programmable cardiovascular training with software-mediated coaching and social competition features. Spin bikes and stationary bikes occupy the largest installed base, while folding bikes represent the fastest-growing configuration as urban consumers prioritize space efficiency. Bluetooth and ANT+ connectivity dominate current specifications, though Wi-Fi-enabled models are gaining share among premium home users seeking richer data streaming without smartphone tethering.
FCC certification governs wireless transmission compliance for US-bound equipment, while CE marking and REACH substance restrictions regulate European market access. China's MIIT enforces radio equipment type approval and GB standards for electromagnetic compatibility. Stakeholders must monitor evolving cybersecurity mandates for connected health devices and anticipate how right-to-repair legislation in multiple jurisdictions affects hardware-service bundling strategies.
Market Dynamics
Electromagnetic resistance calibration and real-time power meter integration are compressing hardware differentiation cycles, forcing manufacturers to compete through software-mediated training experiences rather than mechanical specifications alone.
Growth Catalysts
- Home Fitness Infrastructure:Residential consumers in the United States, Germany, and China are outfitting dedicated workout spaces with connected cardio equipment. FCC certification requirements for wireless transmission ensure baseline interoperability across third-party training applications.
- REACH Substance Standards:European regulatory pressure on hazardous materials in electronics is accelerating design-for-recycling protocols across supplier networks. Manufacturers achieving full material disclosure gain preferential placement with sustainability-focused retail channels.
- Bluetooth Low Energy Protocols:Open wireless standards enable seamless data handoff between bikes, heart rate monitors, and mobile training platforms. This technical architecture lowers switching costs for consumers evaluating competing hardware brands.
Market Restraints
- Precision Motor Supply Concentration:Taiwan-based suppliers control critical electromagnetic resistance actuator production. Disruption to this geographic cluster propagates manufacturing delays across multiple finished goods brands.
- Input Cost Volatility:Neodymium rare earth pricing fluctuations directly impact permanent magnet motor costs. Long-term supply contracts with Chinese processors remain difficult to secure at predictable rates.
- Right-to-Repair Legislation:Emerging mandates in multiple US states and EU member countries threaten hardware-service bundling strategies. Manufacturers relying on subscription revenue to subsidize equipment pricing face margin compression from forced component accessibility.
Strategic Opportunities
- Urban Space Constraints:Folding bike configurations address apartment dwellers in dense metropolitan areas where permanent equipment placement is impractical. Japanese and South Korean consumers demonstrate particular willingness to pay premiums for stowable form factors.
- Wi-Fi Streaming Capability:Direct internet connectivity eliminates smartphone tethering requirements and enables richer video content delivery. Premium residential segments in Germany and the United States show accelerating preference for untethered operation.
- Cybersecurity Mandates:Connected health device regulations emerging from FDA and European cybersecurity frameworks create compliance barriers for smaller competitors. Early certification investments by established manufacturers build defensive moats around market position.
Industry Challenges
- Power Measurement Calibration Expertise:Strain gauge installation and temperature compensation require specialized technicians scarce in contract manufacturing environments. Quality variation across production batches damages brand reputation when consumers compare data accuracy.
- Cross-Platform Certification Complexity:ANT+ and Bluetooth qualification processes impose multi-month timeline extensions on product launches. Delayed market entry cedes seasonal purchasing windows to faster-moving competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Smart Bikes Market |
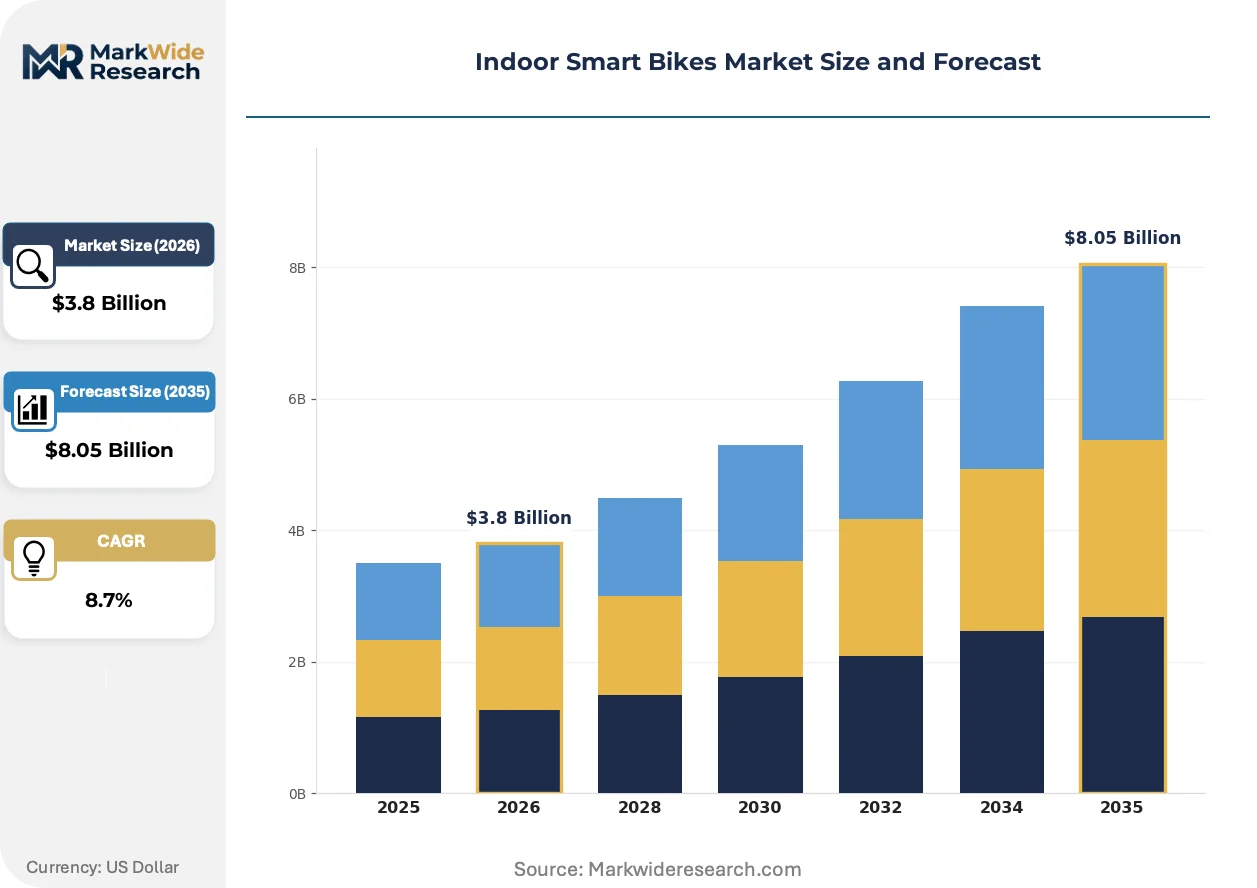
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Bikes, Folding Bikes, Spin Bikes, Recumbent Bikes Connectivity: Bluetooth, Wi-Fi, ANT+, Wired End User: Gyms, Home Users, Corporate Fitness, Rehabilitation Centers Feature: Interactive Coaching, Performance Metrics, Custom Workouts, Integration with Fitness Apps |
| Companies Covered | Wahoo Fitness, Zwift, Tacx, Peloton, NordicTrack, Schwinn Fitness, Horizon Fitness, JetBlack, Elite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Smart Bikes Market Trends and Innovations
Software-defined workout experiences are displacing hardware-centric competitive positioning, with real-time data visualization and algorithmic coaching becoming primary purchase determinants over frame geometry or resistance specifications.
Electromagnetic resistance systems with closed-loop torque control are consolidating technical leadership among premium equipment manufacturers. These systems enable instantaneous resistance adjustments synchronized to virtual terrain gradients in training simulations. High-engagement residential users in the United States and Germany demonstrate willingness to pay substantial premiums for precise wattage fidelity. The technology is consolidating competitive advantage around firmware calibration capabilities rather than mechanical engineering heritage.
EU cybersecurity requirements for connected health devices under the MDR and emerging AI Act classifications are reshaping product development roadmaps. Manufacturers must demonstrate secure data transmission architectures and algorithmic transparency for automated coaching features. Premium Wi-Fi-enabled models face the most stringent documentation burdens, with CE marking timelines extending by four to six months for products incorporating machine-generated training recommendations. German and French regulatory authorities are conducting the most aggressive pre-market conformity assessments.
Direct-to-consumer channel preference is fragmenting traditional sporting goods retail relationships. Urban consumers increasingly research equipment through social fitness communities before purchasing through manufacturer-controlled digital storefronts. This pattern concentrates customer data ownership with hardware brands and compresses distributor margin pools. The shift is most visible among millennial and Generation Z buyers in dense metropolitan markets across the United States and United Kingdom.
Indoor Smart Bikes Market Segmentation
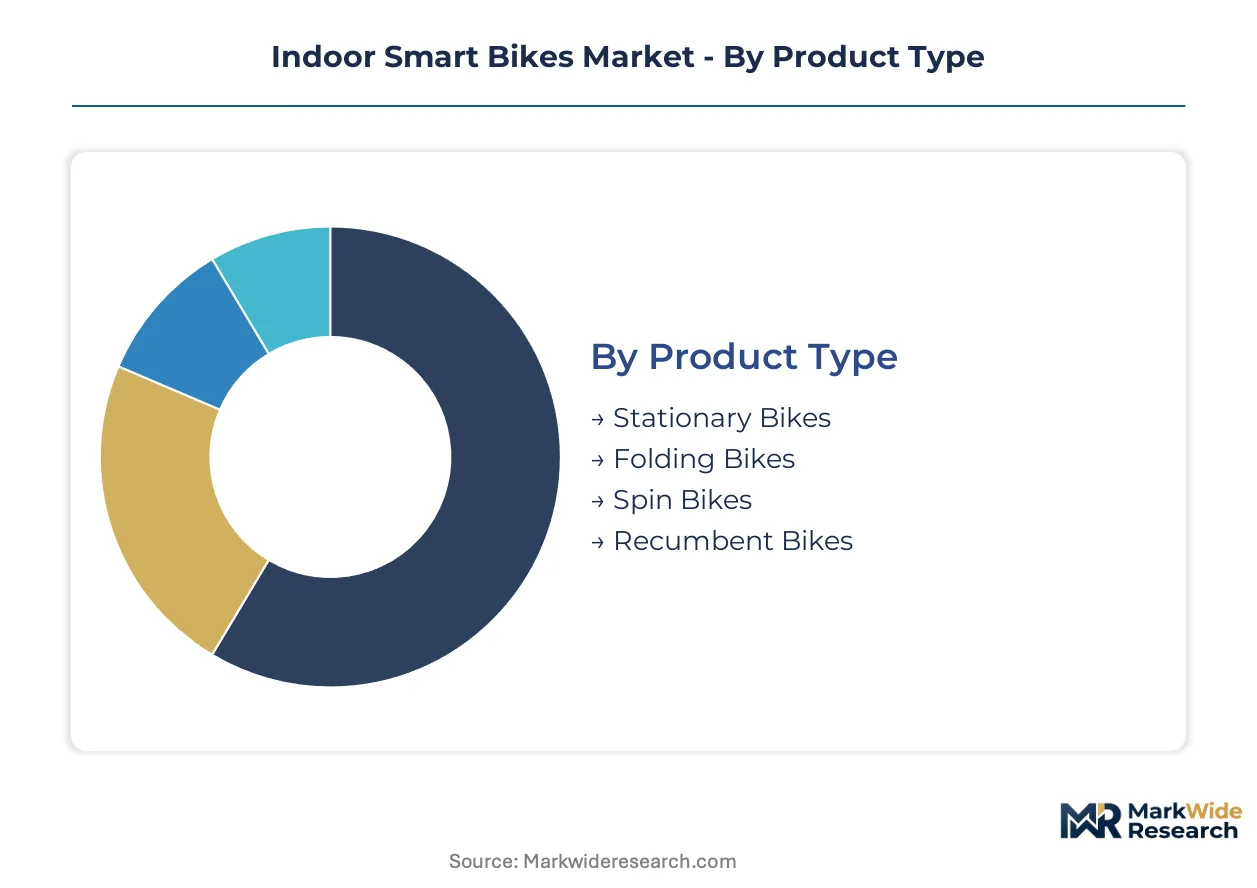
Segmentation in the indoor smart bikes market reveals divergent hardware requirements across user environments and technical integration preferences. Equipment specifications vary dramatically between commercial facilities demanding durability certifications and residential users prioritizing connectivity flexibility. Understanding these structural divides enables targeted positioning against distinct procurement criteria and replacement cycles.
Product Type:
Upgrade cycles differ sharply across form factors, with commercial installations running 5-7 year depreciation schedules while residential equipment faces 3-4 year technology obsolescence pressures.
- Spin Bikes:These machines feature heavy flywheel designs with fixed-gear drivetrains that simulate road cycling dynamics through momentum-based resistance. Demand concentrates in United States boutique fitness studios and German commercial gym chains where instructor-led classes drive utilization rates. FCC certification requirements for electromagnetic resistance systems add compliance overhead that favors established suppliers with regulatory expertise.
- Stationary Bikes:Traditional upright configurations with adjustable magnetic resistance dominate installed base volumes through lower price positioning and familiar ergonomics. Japanese and South Korean residential consumers demonstrate particular attachment to compact footprint models that accommodate apartment living constraints without dedicated workout rooms.
- Folding Bikes:Collapsible frame designs with quick-release mechanisms address space-constrained urban environments where permanent equipment placement is impractical. Chinese and United Kingdom metropolitan buyers show accelerating preference for stowable configurations.
- Recumbent Bikes:Seated positioning with lumbar support targets rehabilitation protocols and senior fitness demographics seeking reduced joint impact. German rehabilitation centers and United States medical fitness facilities constitute primary demand nodes.
Volume placements concentrate in Stationary Bikes; the faster expansion belongs to Folding Bikes.
Connectivity:
Cost tier stratification runs through wireless protocol implementation, with premium Wi-Fi modules adding substantial bill-of-materials overhead against baseline Bluetooth configurations.
- Bluetooth:Low Energy protocols enable seamless pairing with heart rate monitors, power meters, and mobile training applications through standardized profiles. United States and German residential users prioritize this specification for compatibility across Zwift, TrainerRoad, and proprietary platform ecosystems.
- ANT+:Dedicated fitness device protocol maintains dedicated following among serious cyclists requiring simultaneous multi-sensor connectivity without Bluetooth congestion. This specification concentrates in performance-oriented segments across Australia and Netherlands cycling communities.
- Wi-Fi:Direct internet connectivity eliminates smartphone tethering requirements and enables richer video streaming for immersive training content. Premium residential segments in Germany and United States show accelerating preference for untethered operation with independent firmware update capabilities.
- Wired:USB-C and Ethernet connections persist in commercial installations where electromagnetic interference concerns override wireless convenience priorities. Chinese corporate fitness centers favor this architecture for centralized device management.
Bluetooth dominates current shipment volumes; Wi-Fi is climbing the fastest as premium home fitness infrastructure expands.
End User:
Application-specific durability requirements create divergent procurement patterns, with commercial facilities demanding commercial-grade frame warranties and residential users prioritizing software subscription bundles.
- Home Users:Residential consumers seeking connected workout experiences represent the volume anchor, with United States, Germany, and China leading connected fitness infrastructure development. These buyers evaluate equipment through lens of content ecosystem integration and space efficiency.
- Gyms:Commercial fitness facilities require IP-rated electronics, reinforced frame construction, and centralized fleet management capabilities. This segment concentrates procurement decisions in United States health club chains and German municipal sports facilities.
- Corporate Fitness:Employer-sponsored wellness programs drive installations in technology sector campuses and financial services headquarters. Japanese and South Korean corporate campuses demonstrate particular willingness to fund premium equipment for employee retention objectives.
- Rehabilitation Centers:Medical fitness facilities demand precise power measurement calibration and clinical-grade documentation for insurance reimbursement protocols. German rehabilitation networks and United States hospital-affiliated wellness centers constitute primary demand nodes.
Home Users anchor shipment volumes; Corporate Fitness shows steepest expansion trajectory as employer wellness budgets recover.
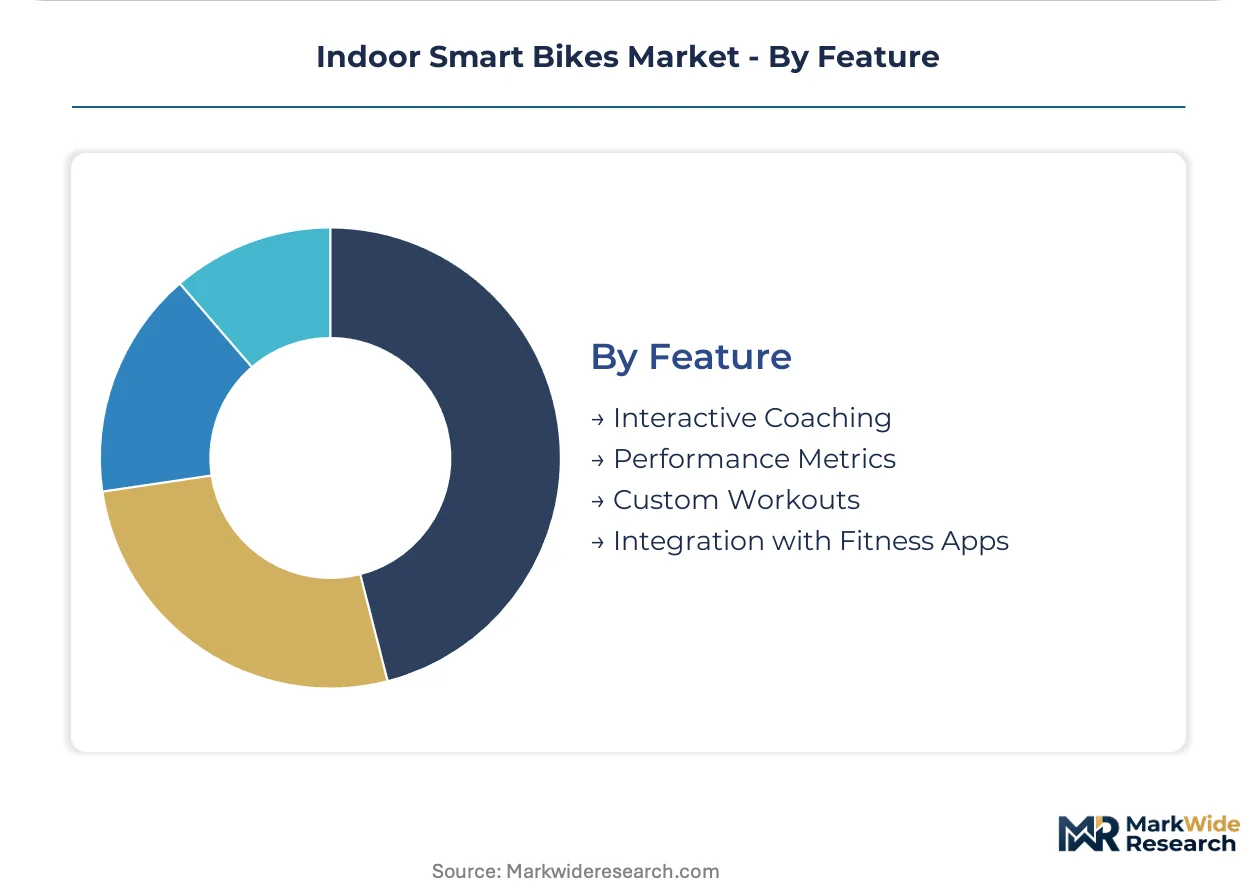
Feature:
Margin concentration aligns with software-mediated functionality, with algorithmic coaching capabilities commanding substantial premiums over basic performance display configurations.
- Performance Metrics:Real-time power output, cadence, and heart rate visualization form baseline expectation across all price tiers. This functionality concentrates demand in German and United States markets where quantified training protocols dominate consumer education.
- Interactive Coaching:Live and on-demand instructor-led sessions with dynamic resistance synchronization represent premium tier differentiator. Peloton and NordicTrack proprietary content ecosystems anchor this positioning in North American residential segments.
- Integration with Fitness Apps:Open-platform compatibility enabling data export to Strava, TrainingPeaks, and Apple Health appeals to technically sophisticated users. Wahoo Fitness leverages this architecture to compete across multiple software environments.
- Custom Workouts:User-programmable interval structures and target-based training plans attract self-directed athletes seeking autonomy from subscription dependencies. This feature shows particular traction among Australian and British cycling enthusiasts.
Performance Metrics captures baseline volume; Interactive Coaching is gaining share fastest as content subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese precision motor clusters anchor electromagnetic resistance manufacturing for connected fitness hardware. German regulatory frameworks and United States consumer infrastructure drive differentiated demand patterns across major economies.
United States
Residential consumers outfit dedicated home fitness spaces with Wi-Fi-enabled equipment for untethered content streaming. FCC certification mandates govern wireless transmission compliance for all radio-equipped devices entering the market. Austin and San Francisco metropolitan areas concentrate early-adopter demand for premium interactive coaching platforms.
Germany
Quantified training protocols dominate consumer education, with cyclists demanding precise wattage fidelity and open-platform compatibility. CE marking and REACH substance restrictions regulate European market access for electromagnetic equipment. Bavaria hosts rehabilitation centers and municipal sports facilities that constitute primary commercial demand nodes for medical-grade installations.
China
Urban apartment dwellers in dense metropolitan areas drive accelerating preference for folding bike configurations that address space constraints. MIIT enforces radio equipment type approval and GB standards for electromagnetic compatibility across all connected devices. Yangtze River Delta manufacturing clusters consolidate around sensor integration and firmware calibration capabilities for export-bound finished goods.
Japan
Corporate wellness budgets fund premium equipment installations across technology sector campuses seeking employee retention advantages. METI oversees industrial standards for consumer electronics and connected health devices. Tokyo and Osaka metropolitan areas demonstrate particular willingness to pay premiums for stowable form factors accommodating compact residential footprints.
United Kingdom
Millennial and Generation Z buyers in dense urban markets research equipment through social fitness communities before purchasing through direct-to-consumer channels. Emerging right-to-repair legislation threatens hardware-service bundling strategies across multiple jurisdictions. London anchors demand concentration, with Manchester and Birmingham showing expanding residential adoption of connected cardio infrastructure.
Indoor Smart Bikes Market Competitive Landscape
Global majors compete with regional champions across content ecosystem control and manufacturing scale. The vendor base stratifies into three tiers: proprietary platform operators with captive content production, open-platform hardware specialists emphasizing interoperability, and contract manufacturers supplying white-label equipment to retail channels. Dominant competitive moves include direct-to-consumer channel expansion and backward integration into precision motor supply.
Within the proprietary ecosystem tier, Peloton and NordicTrack exemplify content-anchored positioning through in-house production capabilities and subscription-mediated customer relationships. Wahoo Fitness occupies a distinct position as an open-platform specialist, enabling seamless data handoff across third-party training environments without captive content dependencies. These three companies represent divergent strategic bets on whether hardware margins or recurring subscription revenue will dominate long-term value capture.
| Leading Market Players |
|---|
| Wahoo Fitness |
| Zwift |
| Tacx |
| Peloton |
| NordicTrack |
| Schwinn Fitness |
| Horizon Fitness |
| JetBlack |
| Elite |
| Others |
Pricing and Supply Chain Analysis
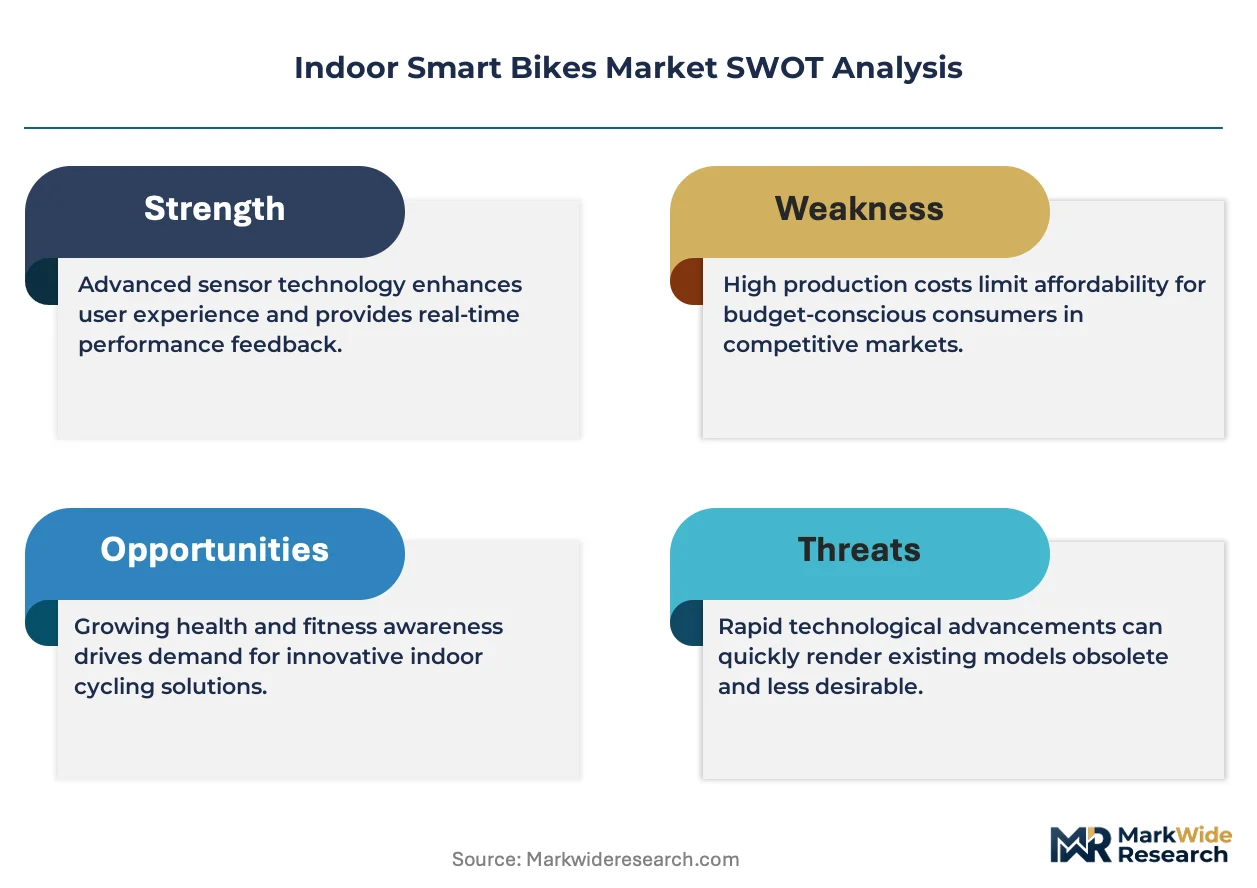
Neodymium rare earth price indices cascade through electromagnetic resistance motor costs, compressing margins for manufacturers lacking long-term Chinese processor contracts while forcing premium-tier brands to absorb volatility through subscription revenue pools.
Pricing Analysis
Warranty and service-bundling configurations separate hardware pricing tiers, with incumbents like Peloton and NordicTrack embedding multi-year content subscriptions to mask equipment costs while open-platform specialists unbundle hardware from software. Three-tier pricing structure across premium, standard, and economy levels reflects electromagnetic resistance precision grades and power meter calibration certification tiers. Cost compression in economy segments intensifies as white-label contract manufacturers from Yangtze River Delta clusters compete on volume scale. Corporate fitness buyers in Japan and South Korea demonstrate lowest price sensitivity due to employee retention budget allocations, while United Kingdom millennial residential consumers exhibit highest elasticity to unbundled hardware pricing.
Supply Chain Analysis
Electromagnetic resistance actuator production rests on Taiwanese precision motor clusters, with secondary sensor integration capabilities concentrating in Chinese Yangtze River Delta manufacturing hubs and tertiary firmware calibration expertise anchoring in German industrial automation centers. Critical inputs include neodymium permanent magnets, strain gauge assemblies for power measurement, and Bluetooth Low Energy chipset modules. Single-source vulnerability propagates from Taiwan-based electromagnetic component suppliers, where disruption cascades across multiple finished goods brands simultaneously. Distribution runs through direct-to-consumer digital storefronts that concentrate customer data ownership with hardware brands while compressing traditional sporting goods retail margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive control over precision motor supply and proprietary content production separates sustainable margin structures from commodity hardware traps.
For Market Incumbents: Deepen backward integration into Taiwanese electromagnetic resistance actuator supply through equity stakes or exclusive offtake agreements with precision motor specialists. Fortify proprietary content ecosystem moats against open-platform interoperability threats by accelerating in-house production capacity in United States and German markets. Prioritize FCC and CE cybersecurity pre-certification investments to exploit compliance timeline barriers facing smaller competitors.
For New Entrants and Emerging Players: Direct-to-consumer digital storefront operators present the most accessible channel partnership avenue for bypassing entrenched retail relationships. White-space concentration sits in folding bike configurations for Chinese and United Kingdom urban apartment dwellers, where space-constrained demographics remain underserved by incumbent bulk-focused portfolios. Attack through Wi-Fi-enabled untethered operation as a premium feature bypass, targeting German and United States residential segments frustrated by smartphone tethering requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor open-platform hardware specialists with established ANT+ and Bluetooth certification portfolios in Taiwanese manufacturing corridors. Long-term viability hinges on recurring revenue attachment rates rather than equipment shipment volumes, with five-to-ten-year value capture concentrating in software-mediated customer relationships. Watch right-to-repair legislative progression across United States statehouses and EU member countries as the critical inflection signal for hardware-service bundling strategy durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motor Supply | Captive Taiwanese electromagnetic actuator sourcing insulates against neodymium price volatility and Taiwan cluster disruption risks. |
| Proprietary Content Ecosystem Expansion | In-house production capabilities in United States and German markets lock subscription revenue streams against open-platform commodification. |
| Cybersecurity Pre-Certification Investment | Early FDA and EU MDR compliance documentation builds four-to-six-month timeline moats against smaller competitors. |
| Folding Bike Configuration Development | Collapsible frame engineering addresses Chinese and United Kingdom urban space constraints with premium pricing acceptance. |
| Wi-Fi Streaming Capability Integration | Direct internet connectivity eliminates smartphone tethering for German and United States premium residential segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with connected fitness hardware engineering directors, electromagnetic component procurement leads at Taiwanese motor suppliers, content platform executives, and commercial gym fleet managers across United States and German markets. FCC equipment authorization databases, MIIT radio type approval registries, and REACH substance restriction compliance filings provided certification timeline and regulatory burden quantification. Bottom-up equipment shipment estimates triangulated against top-down consumer spending flows through sporting goods retail channels and direct-to-consumer digital storefronts.
Data-stream reconciliation across manufacturer production schedules, component supplier order books, and third-party training platform user growth metrics informed the analytical framework. Segmentation modeling spanned product type, connectivity protocol, end-user environment, and feature tier across the projection horizon. CAGRs derived from regression analysis of replacement cycle compression, technology obsolescence acceleration, and content subscription attachment rate trajectories. Industry-specific inputs included electromagnetic resistance system bill-of-materials cost curves and power measurement calibration technician scarcity indices.
Several conditions sit outside the modeled scope, including potential neodymium export restriction implementations, abrupt right-to-repair legislative mandates, and pandemic-scale demand shocks. Forecasts reflect assumptions around sustained Bluetooth Low Energy protocol dominance and gradual Wi-Fi capability premium migration. A small set of named triggers warrants ongoing watch: Taiwan semiconductor cluster geopolitical stability, EU AI Act automated coaching feature reclassifications, and United States state-level repair accessibility legislation progression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Smart Fitness Wear Market