
 Home Gym Equipment Market | 2026-2036
Home Gym Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Home Gym Equipment Market Outlook
Chinese manufacturing capacity for steel-framed fitness machines is hardening as domestic producers scale output for export markets. ICON Health & Fitness leverages vertical integration across design and assembly to sustain margin control in North American channels. Johnson Health Tech anchors its position through geographic dominance across Asia-Pacific distribution networks. Technogym differentiates via specialized smart equipment ecosystems that command premium positioning among fitness enthusiasts.
Home gym equipment encompasses mechanically and electronically powered apparatus designed for cardiovascular conditioning, resistance training, and flexibility exercise within residential settings, typically constructed from powder-coated steel tubing, polymer composites, and embedded sensor arrays rated for cyclic loading between 100 and 500 pounds. Its primary commercial purpose centers on delivering health club-equivalent training modalities without facility membership requirements. Treadmills and exercise bikes within the product type segment represent mature revenue pools with established replacement cycles, while smart equipment and biomechanical sensors under the technology dimension capture the fastest-growing margin concentration as subscription-linked hardware gains share. The distribution channel structure shows online retail pulling volume from specialty stores as direct-to-consumer logistics networks mature.
Consumer Product Safety Commission standards govern mechanical stability and electrical safety for equipment sold in the United States, while EU CE marking under the Machinery Directive enforces operational safety thresholds for European market access. China's GB standards and SAMR oversight regulate electromagnetic compatibility and structural load ratings for domestically manufactured units. Stakeholders must monitor evolving interoperability protocols between proprietary sensor platforms and third-party fitness applications as ecosystem lock-in risks reshape purchasing decisions.
Market Dynamics
Smart equipment integration with biomechanical sensors is compressing replacement cycles and reshaping margin structures across residential fitness hardware, as subscription-linked ecosystems displace standalone mechanical devices.
Growth Catalysts
- EU CE marking under the Machinery Directive:Harmonized safety standards reduce certification friction for cross-border equipment sales, accelerating market access for compliant manufacturers.
- Connected workout ecosystems:Fitness enthusiasts demand hardware-software bundles that track biometric performance, pulling premium spending toward sensor-embedded platforms.
- Residential fitness infrastructure investment:Post-pandemic habit persistence in the United States, China, and Germany sustains durable equipment demand across cardiovascular and resistance categories.
Market Restraints
- Steel and polymer composite input volatility:Powder-coated steel tubing and polymer feedstock price swings compress margins for mid-tier equipment producers without captive material sourcing.
- Chinese manufacturing concentration:Domestic producers scaling export output create supply-side dependency risk for brands lacking geographic diversification in assembly operations.
- Proprietary sensor platform lock-in:Ecosystem interoperability gaps force consumers into single-vendor hardware-software pairings, limiting switching flexibility and dampening replacement demand.
Strategic Opportunities
- Direct-to-consumer logistics maturation:Online retail channel expansion enables bypass of specialty store markups, capturing margin recovery for brands with captive fulfillment networks.
- EU Green Deal circularity requirements:Upcoming durability and recyclability mandates favor equipment designed for component modularity and end-of-life material recovery.
- Biomechanical sensor-AI convergence:Real-time form correction and personalized programming integration opens premium pricing tiers for AI-enabled coaching hardware.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for sensor arrays and cloud connectivity outpaces qualified labor supply, extending product development timelines.
- Multi-jurisdiction certification complexity:Simultaneous compliance with US CPSC mechanical standards, EU CE marking, and China GB electromagnetic requirements fragments testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Gym Equipment Market |
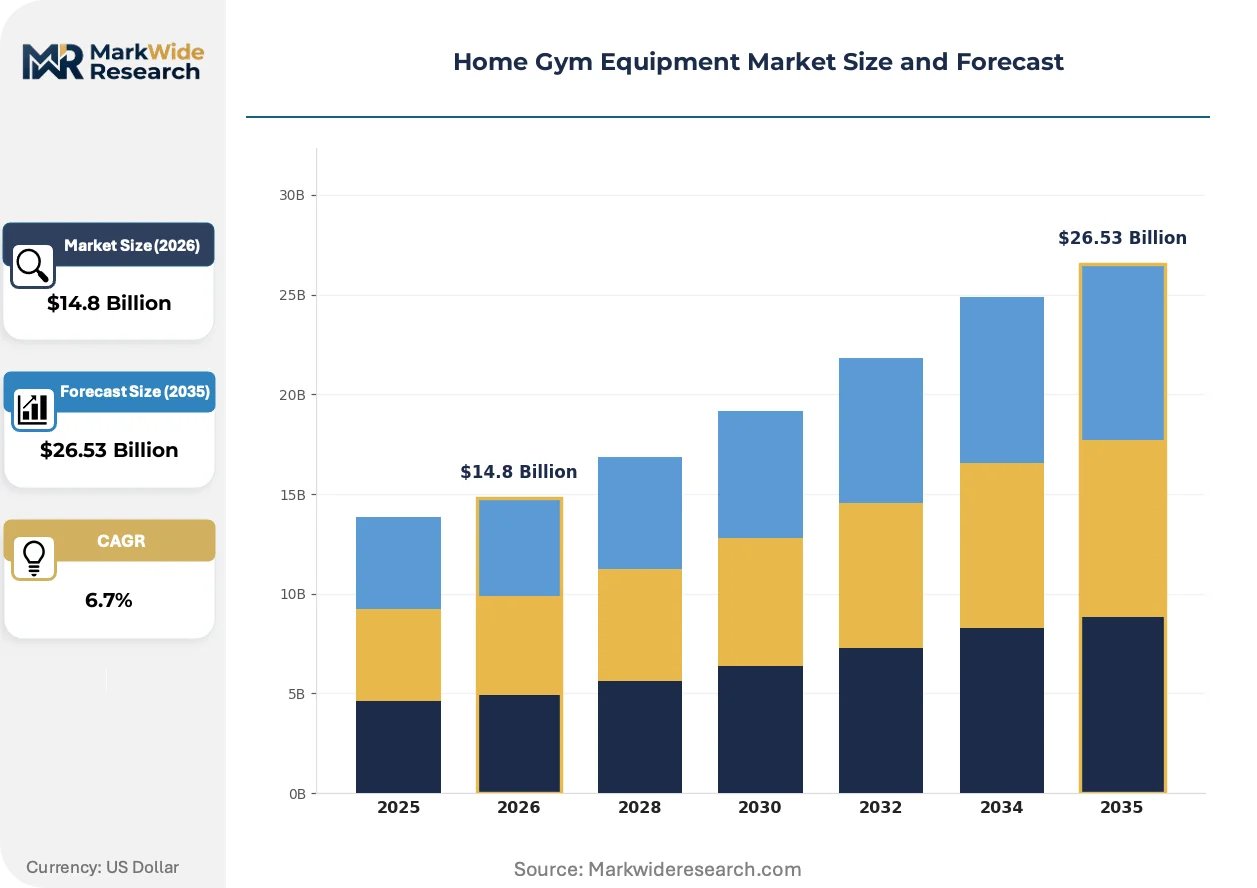
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Exercise Bikes, Weight Benches, Dumbbells Technology: Smart Equipment, Foldable Machines, Biomechanical Sensors, Resistance Systems End User: Fitness Enthusiasts, Professional Athletes, Homeowners, Personal Trainers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Fitness Centers |
| Companies Covered | ICON Health & Fitness, Johnson Health Tech, Technogym, Life Fitness, Peloton Interactive, Core Health & Fitness, Nautilus, Precor, Tonal Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Gym Equipment Market Strategic Shifts
Hardware-software convergence is redefining value capture in residential fitness, as equipment vendors pivot from unit sales toward recurring revenue architectures tied to performance data monetization.
Biomechanical sensor arrays embedded in resistance and cardiovascular equipment are automating real-time form analysis and load adjustment. Fitness enthusiasts and rehabilitation clinics are adopting these platforms fastest, replacing static workout programming with adaptive coaching. This automation is compressing the addressable market for personal training services while expanding hardware attach rates.
China's GB standards and SAMR oversight are tightening electromagnetic compatibility testing for domestically manufactured units with wireless connectivity. The regulatory burden falls heaviest on export-oriented producers targeting European and North American markets, forcing parallel certification tracks. Sensor-embedded treadmills and connected bikes face the steepest compliance cost escalation as transmission power limits harden.
After-sales service unbundling is fragmenting traditional warranty bundles into subscription-tier maintenance and software update packages. Specialty retail channels in Germany and the United States are losing attachment revenue as direct-to-consumer brands capture service relationships. This shift is most visible among premium equipment buyers who prioritize seamless digital integration over in-person technical support.
Home Gym Equipment Market Segmentation
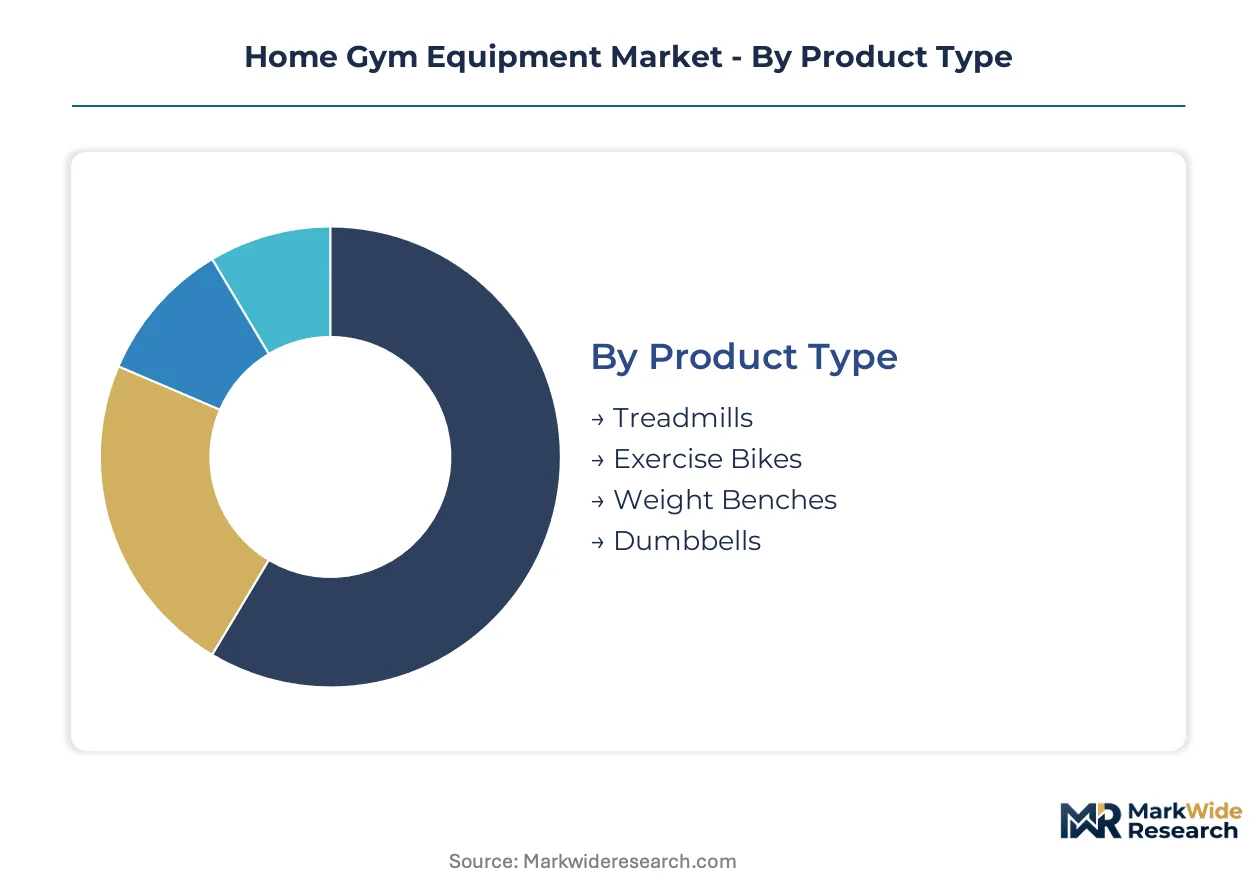
Segmentation in home gym equipment reveals divergent margin structures between mature mechanical categories and emerging sensor-integrated platforms. Understanding where volume concentrates versus where premium pricing power accumulates shapes portfolio allocation for manufacturers and channel strategy for distributors.
Product Type:
Volume leadership sits with established cardio platforms while strength equipment commands replacement-driven premiums.
- Treadmills:Motorized belt systems with 2.5 to 4.0 continuous horsepower motors and cushioned deck suspension define this segment. Demand concentrates in the United States and Germany where residential basement and garage conversions sustain 7-to-10-year replacement cycles. Deck belt wear and motor controller failures drive predictable aftermarket revenue.
- Exercise Bikes:Magnetic resistance flywheels paired with belt-drive transmissions dominate contemporary designs. Fitness enthusiasts in China and the United States pull volume toward connected models with integrated tablet mounts and subscription-linked content platforms. Seat ergonomics and Q-factor adjustability differentiate premium from mid-tier offerings.
- Weight Benches:Adjustable incline mechanisms with 600 to 1,000-pound load ratings serve home strength training. Powder-coated steel frames with polyurethane padding resist garage humidity degradation.
- Dumbbells:Hexagonal rubber-coated cast iron and selectorized adjustable systems compete for space-constrained users. Rapid weight-change mechanisms command pricing premiums over fixed-weight sets.
Today's leader: Treadmills. Tomorrow's challenger: Dumbbells with integrated load-sensing connectivity.
Technology:
Hardware sophistication separates subscription-capturing ecosystems from commoditized mechanical alternatives.
- Smart Equipment:Embedded touchscreens with Wi-Fi connectivity and proprietary operating systems enable live class streaming and performance data storage. Fitness enthusiasts in Germany and the United States demonstrate willingness to pay hardware premiums for software-locked content ecosystems. Cloud infrastructure costs and content licensing fees compress net margins despite elevated retail prices.
- Biomechanical Sensors:Accelerometer and gyroscope arrays embedded in handles and pedals capture motion patterns for real-time form feedback. Rehabilitation clinics and performance-focused homeowners in China adopt these platforms fastest for injury prevention and load optimization. Calibration complexity and firmware update requirements extend customer support obligations.
- Foldable Machines:Hinge mechanisms and telescoping frames enable vertical storage in space-constrained apartments. Urban residential buyers in high-density Chinese and German cities prioritize footprint reduction over maximum stability.
- Resistance Systems:Fan-based air resistance, magnetic eddy current braking, and elastic band mechanisms compete across price tiers. Maintenance requirements and resistance curve consistency determine commercial versus residential suitability.
Smart Equipment captures the steepest expansion trajectory as subscription economics reshape vendor revenue models.
End User:
Training intensity and technical sophistication segment buyer priorities across equipment specifications.
- Fitness Enthusiasts:Users completing four or more weekly sessions with structured programming demands. This segment drives sensor-embedded equipment adoption and subscription attachment in the United States and China. Performance tracking integration and social sharing features influence purchase decisions more than absolute load capacity.
- Professional Athletes:Individuals with sport-specific conditioning requirements and access to coaching infrastructure. Home equipment purchases supplement rather than replace facility-based training in Germany and the United States. Force plate integration and velocity-based training compatibility command specification priority.
- Homeowners:General health maintenance buyers prioritizing convenience and aesthetic integration with residential spaces. Noise dampening and visual minimalism outweigh performance metrics for this volume segment.
- Personal Trainers:Independent operators building client-facing mobile training businesses. Equipment portability and rapid setup capability enable session delivery across multiple residential locations.
Fitness Enthusiasts anchor current premium spending. Personal Trainers represent the fastest-climbing adoption vector for portable connected systems.
Distribution Channel:
Logistics infrastructure maturity and customer acquisition economics determine channel viability across equipment categories.
- Online Retail:E-commerce platforms with white-glove delivery and assembly services capture treadmill and exercise bike volume. Direct-to-consumer brands in the United States and China bypass specialty retail markups through captive fulfillment networks. Return logistics costs for 200-plus pound equipment units strain unit economics.
- Specialty Stores:Physical showrooms with test-ride capabilities and in-house service technicians retain strength equipment and high-consideration cardio purchases. German and United States markets sustain these channels through premium positioning and installation service bundling. Floor space productivity pressure drives consolidation among independent operators.
- Direct Sales:Manufacturer-owned websites with subscription bundling and trade-in programs. Customer data capture and recurring revenue attachment justify higher customer acquisition spending.
- Fitness Centers:Commercial facility partnerships for member home equipment discounts and lease-to-own arrangements. Brand exposure through facility placement drives residential purchase consideration.
Online Retail leads transaction volume. Direct Sales channels gain share fastest through subscription-linked hardware economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as Chinese producers exploit compliance-cost gaps to capture export volume, while US and European brands absorb certification burdens to defend premium positioning. Equipment flows concentrate through three demand poles with divergent infrastructure investment cycles.
United States
Residential basement conversions and garage gym builds sustain replacement demand for motorized cardio platforms. Consumer Product Safety Commission mechanical stability standards govern market access, with electrical safety testing adding cost layers for connected equipment. Dallas-Fort Worth logistics clusters anchor white-glove delivery networks for direct-to-consumer brands.
China
Domestic fitness enthusiasts pull volume toward subscription-linked bikes and sensor-embedded strength platforms. GB standards and SAMR electromagnetic compatibility oversight tighten for wireless-enabled units, forcing parallel certification tracks for export-oriented producers. Yangtze River Delta manufacturing bases scale steel-framed machine output for North American and European channels.
Germany
CE marking under the Machinery Directive enforces operational safety thresholds that filter out low-cost competitors. EU Green Deal circularity requirements favor equipment designed for component modularity and end-of-life material recovery. Bavarian engineering clusters specialize in precision resistance mechanisms and embedded sensor calibration systems.
Japan
Space-constrained urban apartments drive foldable machine adoption with vertical storage priority. METI energy efficiency guidelines and JIS structural load standards shape product specifications for domestic manufacturers. Osaka-Kansai industrial zones concentrate compact resistance system fabrication for premium residential segments.
United Kingdom
Post-pandemic habit persistence sustains demand across cardiovascular and resistance categories despite economic headwinds. UKCA marking transition from CE standards creates temporary certification friction for EU-sourced inventory. London-Southeast logistics corridors specialize in last-mile assembly services for online retail channels.
Home Gym Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart equipment and biomechanical sensor integration to capture subscription-linked revenue pools. The market structures around three player archetypes: vertically integrated North American assemblers controlling captive supply chains, Asia-Pacific fabricators leveraging manufacturing scale for export penetration, and European specialists commanding premium positioning through design differentiation. Competitive moves concentrate on direct-to-consumer channel buildout and ecosystem lock-in through proprietary software-hardware bundles.
Among North American operators, ICON Health & Fitness and Peloton Interactive exemplify divergent strategic vectors within connected fitness—one through manufacturing breadth, the other through content-subscription economics. Johnson Health Tech anchors the Asia-Pacific scale tier with geographic distribution dominance. Technogym occupies the European premium specialist position, representing ecosystem-based differentiation through integrated smart equipment platforms.
| Leading Market Players |
|---|
| ICON Health & Fitness |
| Johnson Health Tech |
| Technogym |
| Life Fitness |
| Peloton Interactive |
| Core Health & Fitness |
| Nautilus |
| Precor |
| Tonal Systems |
| Others |
Value Chain & Pricing Dynamics
Backward integration into steel tubing and motor controller production anchors margin control for North American assemblers while Chinese producers exploit scale economies to compress export pricing. This structural divergence separates premium ecosystem vendors from commodity hardware suppliers across residential fitness channels.
Pricing Analysis
Distributor markups on specialty retail floors compress to 15-25 percent as direct-to-consumer brands capture treadmill and exercise bike volume through captive fulfillment networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor integration depth and subscription bundling rather than mechanical load capacity alone. Cost compression in mid-tier magnetic resistance systems is intensifying because Yangtze River Delta fabricators are scaling export output. Homeowners represent the most price-sensitive buyer archetype, while fitness enthusiasts demonstrate inelastic demand for biomechanical sensor-embedded platforms with proprietary content ecosystems.
Supply Chain Analysis
Freight cost escalation on trans-Pacific container routes is forcing inventory positioning shifts toward regional fulfillment nodes in Dallas-Fort Worth and Rotterdam port zones. Manufacturing gravity centers on China for steel-framed machine fabrication, Taiwan for motor controller semiconductors, and Germany for precision resistance mechanism engineering. Powder-coated steel tubing, polymer composite feedstock, and embedded sensor arrays constitute the critical input trinity. Single-source vulnerability concentrates in Chinese electromagnetic component supply for wireless-enabled units. Distribution runs through hybrid direct-to-consumer and white-glove delivery networks that bypass traditional specialty retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential fitness hardware has entered a late-cycle quality phase where replacement demand tilts toward sensor-integrated platforms with subscription attach. Fitness enthusiasts now treat biomechanical feedback and adaptive programming as baseline specifications rather than premium upgrades.
For Market Incumbents: Deploy ecosystem lock-in through proprietary sensor-to-cloud architecture to defend against direct-to-consumer entrants eroding specialty retail relationships. ICON Health & Fitness and Johnson Health Tech should deepen captive supply of motor controllers and electromagnetic components to offset Chinese export pricing pressure. Certification investment in simultaneous CPSC, CE marking, and GB standards compliance creates switching costs for mid-tier competitors lacking testing infrastructure scale. For New Entrants and Emerging Players: EU Green Deal circularity requirements in Germany open a window for modular equipment designs with end-of-life material recovery guarantees that incumbent warranty bundles do not address. Portable connected strength systems for personal trainers represent the most penetrable white-space segment, with rapid-setup capability and client data portability as the decisive go-to-market angle. Target rehabilitation clinic procurement channels in China where biomechanical sensor adoption outpaces residential fitness enthusiast penetration. For Investors and Strategic Acquirers: Roll-up economics work for smart equipment specialists with captive firmware development teams because embedded systems engineering talent scarcity extends product development timelines and inflates standalone R&D costs. Platform consolidation across sensor calibration, cloud infrastructure, and content licensing creates margin recovery potential. Watch for inflection when direct-to-consumer brands achieve sustained positive unit economics on white-glove delivery and assembly services.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses specialty retail markups and captures customer data for subscription attachment. |
| Biomechanical Sensor Platform Integration | Enables real-time form correction that commands premium pricing from fitness enthusiasts. |
| Multi-Jurisdiction Certification Investment | Simultaneous CPSC, CE marking, and GB compliance filters out undercapitalized competitors. |
| Modular Design for Circularity Compliance | EU Green Deal durability mandates favor component replaceability and material recovery. |
| Captive Firmware Development Capacity | In-house embedded systems teams accelerate sensor-to-cloud product cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement managers at commercial fitness chains, residential facility developers, rehabilitation clinic directors, and aftermarket service technicians with secondary validation through CPSC recall databases, EU RAPEX safety notifications, SAMR product registration filings, and customs trade flow records. Bottom-up equipment shipment aggregation and top-down residential fitness expenditure estimation triangulated market sizing across the projection horizon.
Segment-weighting approaches distributed volume and value estimates across product type, technology tier, end-user intensity, and distribution channel dimensions. CAGRs derived from replacement cycle compression analysis and subscription penetration curves. Forecast inputs included steel and polymer composite price indices, logistics cost trajectories, and regulatory compliance burden escalation for wireless-enabled equipment categories.
Revisions become necessary when electromagnetic compatibility standards tighten beyond current GB and CE marking thresholds, or when logistics cost normalization alters direct-to-consumer unit economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Gym Mats Market