
 Gym Mats Market | 2026-2036
Gym Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Mats Market Analysis
Multi-source procurement for rubber feedstock is pivoting toward vertically integrated compounders as volatility in synthetic latex pricing strains contract manufacturers. Regupol America Corp. leverages captive recycling facilities in Pennsylvania to control post-consumer tire supply for its flooring division. Tarkett S.A. anchors European demand through its Reims plant, which processes bio-based polyurethane alternatives for premium studio installations. Manduka differentiates via closed-loop natural rubber sourcing from certified plantations in Southeast Asia.
Gym mats are engineered floor coverings, typically fabricated from vulcanized rubber, expanded polyvinyl chloride, or ethylene-vinyl acetate foam, with thicknesses ranging from 10mm for low-impact yoga to 25mm for Olympic weightlifting platforms, designed to attenuate impact forces and prevent substrate damage. Rubber formulations dominate commercial fitness center installations due to superior compression set resistance under loaded barbell drops, while thermoplastic elastomer mats are gaining share among home users seeking portability and odor-neutral profiles. The 20mm thickness tier captures the highest margin pool in strength training applications, where durability specifications exceed residential standards by a factor of three.
The US Consumer Product Safety Commission monitors flammability standards for foam-based exercise equipment, while California's Department of Toxic Substances Control enforces phased restrictions on short-chain chlorinated paraffins in rubber compounding. The EU REACH regulation mandates disclosure of Substances of Very High Concern in PVC plasticizer formulations, compelling importers to reformulate or face market exclusion. Stakeholders must track evolving per- and polyfluoroalkyl substance restrictions in anti-slip coatings, as several US states and EU member countries are expanding ban lists beyond current federal thresholds.
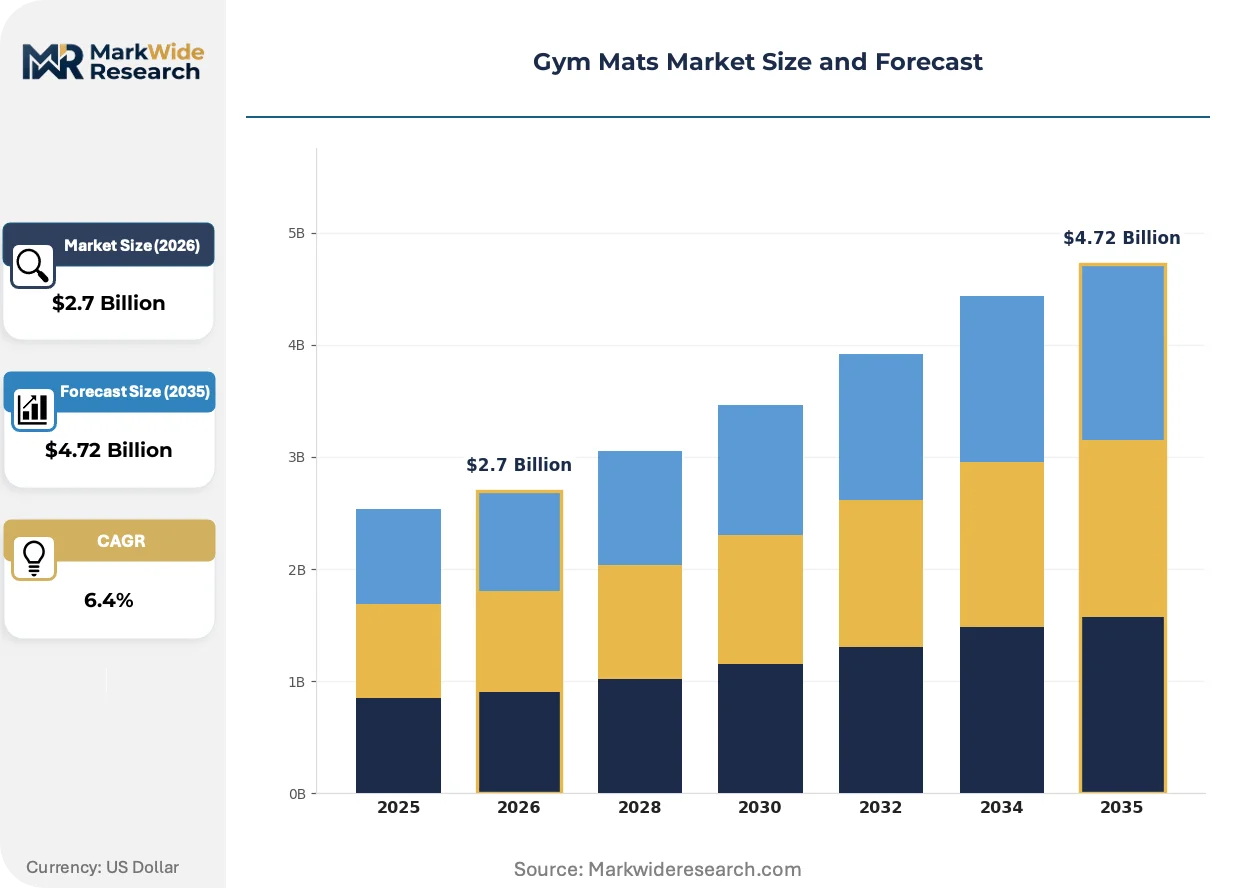
Market Dynamics
Phthalate compliance mandates and synthetic latex price volatility are compressing margin structures for contract manufacturers while rewarding vertically integrated compounders with captive rubber recycling streams.
Growth Catalysts
- REACH SVHC Disclosure:The EU's Substances of Very High Concern framework compels PVC plasticizer reformulation, creating replacement demand for compliant mat inventories across German fitness chains and Nordic studio operators.
- Boutique Fitness Expansion:CrossFit boxes and specialized strength training facilities in China's tier-one cities are shortening equipment replacement cycles from five-year to eighteen-month intervals.
- Post-Consumer Tire Recycling:Captive shredding and devulcanization facilities in Pennsylvania and Ohio supply controlled feedstock for commercial rubber flooring, insulating manufacturers from spot-market synthetic latex swings.
Market Restraints
- Petrochemical Input Volatility:Ethylene and propylene derivative pricing for EVA and TPE formulations fluctuates with refinery crack spreads, squeezing compounders without long-term offtake agreements.
- Southeast Asian Rubber Concentration:Natural latex sourcing clusters in southern Thailand and Malaysian plantations expose processors to climate disruption and export quota variability.
- California Proposition 65:Phased restrictions on DINP and DIDP plasticizers force dual-SKU inventory strategies for vendors serving US West Coast distribution channels.
Strategic Opportunities
- India Fitness Infrastructure:The country's PLI scheme for sports goods manufacturing offers tariff advantages for domestic rubber compounding investments targeting gym chain procurement.
- Bio-Based Polyurethane:Castor oil-derived polyols from European suppliers enable premium positioning for studio installations seeking carbon footprint differentiation.
- Direct-to-Studio Distribution:Bypassing traditional sporting goods wholesalers, manufacturers are building captive e-commerce portals for boutique fitness operators seeking customized thickness and color specifications.
Industry Challenges
- Flammability Certification Timelines:US Consumer Product Safety Commission testing protocols for foam-based exercise equipment extend product launch windows by four to six months.
- Devulcanization Process Integration:Blending post-consumer crumb rubber with virgin compounds at scale requires capital-intensive mixing equipment that mid-tier manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Mats Market |
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, TPE, Rubber, EVA Thickness: 10mm, 15mm, 20mm, 25mm End User: Fitness Centers, Home Users, Sports Teams, Schools Application: Yoga, Pilates, Strength Training, Aerobics |
| Companies Covered | Regupol America Corp., American Floor Mats, Inc., Tarkett S.A., Lululemon Athletica Inc., Net World Sport Ltd., Gerflor SA, Rubber-Cal, LLC, Manduka, Forbo International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Mats Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are compressing product development cycles while fragmenting procurement patterns across commercial and residential buyer segments.
Thermoplastic elastomer formulations with odor-neutral profiles are consolidating share in home fitness applications where portability and storage convenience outweigh compression set specifications. Residential buyers prioritize roll-out convenience over the durability metrics that dominate commercial procurement. This consolidation is compressing the addressable market for vulcanized rubber in sub-15mm thickness categories.
California's Department of Toxic Substances Control enforces phased restrictions on short-chain chlorinated paraffins in rubber compounding, compelling reformulation of anti-slip coatings and fire-retardant additives. Manufacturers serving North American distribution must maintain parallel inventory streams or abandon the West Coast market. Commercial fitness center operators in the state face accelerated replacement schedules as existing mat inventories approach compliance deadlines.
Boutique studio operators are unbundling equipment procurement from traditional full-service gym fit-out contractors, establishing direct relationships with specialized flooring vendors for customized specification. This disintermediation collapses distributor margins while rewarding manufacturers with in-house design and logistics capabilities. The pattern is most visible in Germany's industrial fitness corridor and Shanghai's premium studio clusters.
Gym Mats Market Segmentation
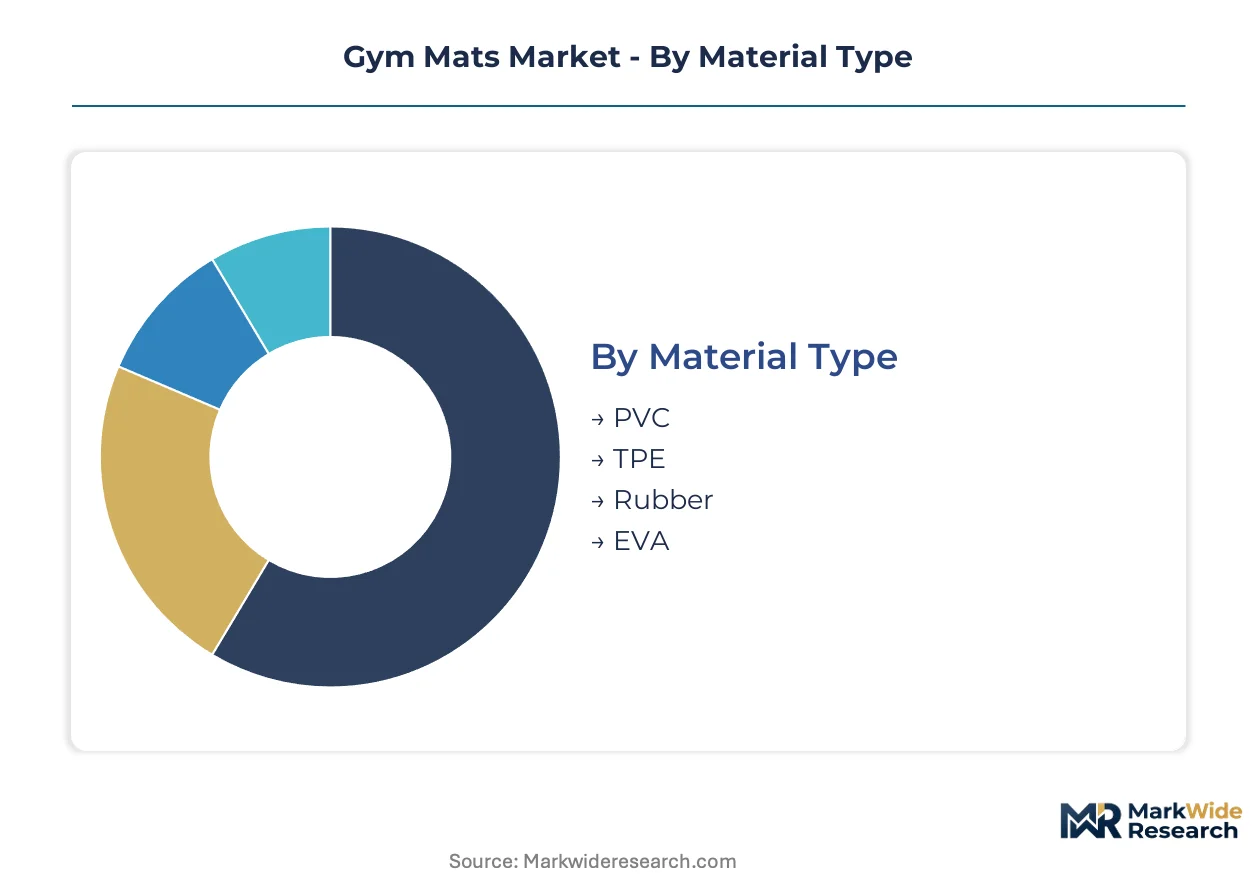
Segmentation in gym mats reveals divergent engineering priorities across buyer types. Commercial fitness operators prioritize compression set resistance under loaded barbell drops, while residential users trade durability for portability and odor-neutral profiles. Material chemistry and thickness specifications fragment procurement patterns between these constituencies.
Material Type:
The customization-vs-standardization spectrum runs from commodity PVC formulations to plantation-certified natural rubber with full chain-of-custody documentation. Specifiers in boutique studios increasingly demand material passports disclosing Substances of Very High Concern under EU REACH frameworks.
- Rubber:Vulcanized rubber formulations deliver superior compression set resistance for Olympic weightlifting platforms and commercial strength training zones. German fitness chains and CrossFit boxes in China's tier-one cities specify 20mm+ rubber constructions for loaded barbell drop zones, driven by durability requirements that exceed residential standards by a factor of three.
- TPE:Thermoplastic elastomer mats consolidate share in home fitness applications where odor-neutral profiles and roll-out convenience outweigh compression specifications. Residential buyers in California's Proposition 65 jurisdiction favor TPE to avoid phthalate disclosure requirements, compressing addressable demand for vulcanized rubber in sub-15mm categories.
- PVC:Expanded polyvinyl chloride remains standard for budget commercial installations and school procurement, though REACH SVHC disclosure mandates are forcing reformulation of plasticizer systems across European distribution channels.
- EVA:Ethylene-vinyl acetate foam dominates lightweight portable segments for yoga and Pilates practitioners prioritizing travel convenience over substrate protection.
Most installed capacity flows through Rubber. Expansion is steepest in TPE.
Thickness:
Cost tier stratification separates premium commercial specifications from economy residential offerings, with margin concentration at intermediate thicknesses serving crossover strength training applications.
- 20mm:The 20mm tier captures the highest margin pool in strength training applications, balancing sufficient impact attenuation for loaded barbell work with material efficiency for large-format commercial installations. Boutique fitness studios in Germany's industrial fitness corridor specify this thickness for functional training zones, driven by insurance liability requirements for dropped equipment protection.
- 10mm:10mm constructions serve low-impact yoga and Pilates applications where portability and storage density outweigh impact force dissipation. Home users in Shanghai's premium residential clusters favor this specification for apartment-based practice, compressing demand for thicker alternatives in urban residential segments.
- 15mm:15mm mats occupy the mid-market for mixed-use home gyms and school physical education departments balancing cost and basic impact protection.
- 25mm:25mm platforms serve dedicated Olympic weightlifting installations and sports team training facilities requiring maximum force attenuation for repeated maximal lifts.
Volume concentrates at 20mm. Steepest expansion trajectory belongs to 10mm.
End User:
Customer type determines specification stringency, with commercial operators enforcing durability testing protocols that residential buyers bypass entirely.
- Fitness Centers:Commercial fitness center operators enforce compression set testing and flammability certification under US Consumer Product Safety Commission protocols, extending product qualification timelines by four to six months. These buyers specify vulcanized rubber for high-traffic zones, with replacement cycles compressing from five-year to eighteen-month intervals in CrossFit and boutique strength training formats.
- Home Users:Residential procurement prioritizes odor-neutral thermoplastic elastomer formulations and roll-out convenience over laboratory durability metrics. California's Department of Toxic Substances Control restrictions on short-chain chlorinated paraffins accelerate turnover in West Coast residential inventories.
- Sports Teams:Collegiate and professional athletic programs specify 25mm rubber platforms for Olympic weightlifting training, with procurement centralized through specialized flooring contractors rather than general sporting goods distributors.
- Schools:Educational institutions favor 15mm PVC or EVA constructions for physical education departments, constrained by public procurement budgets and simplified maintenance requirements.
Procurement volume flows through Fitness Centers. Share is climbing fastest in Home Users.
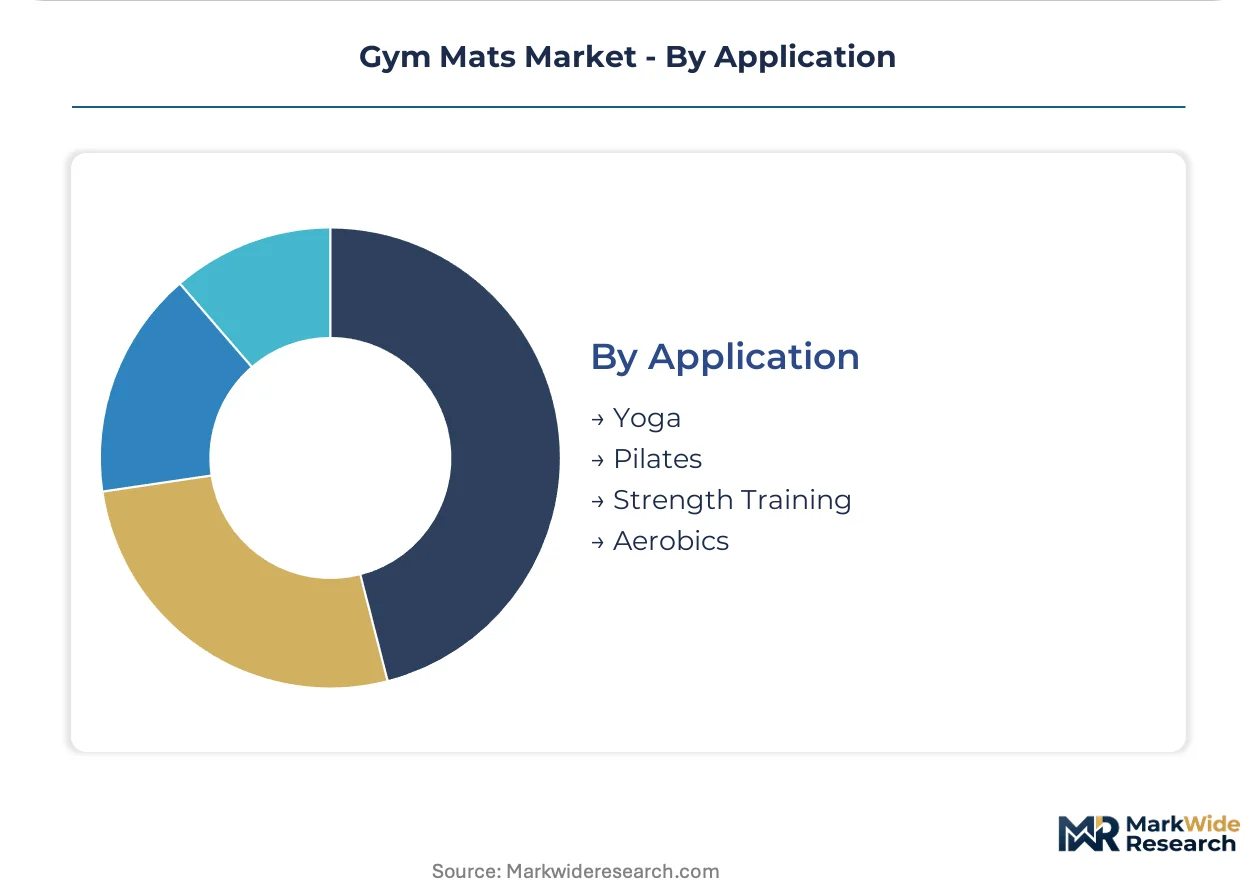
Application:
Application-specific loading patterns dictate material selection, with high-impact strength training demanding fundamentally different engineering from low-impact mind-body disciplines.
- Strength Training:Loaded barbell and dumbbell work requires vulcanized rubber with compression set resistance below 15% after repeated 500kg drop tests. Boutique operators in China's tier-one cities and Germany's Ruhr industrial corridor specify premium formulations with captive recycled tire content for sustainability positioning.
- Yoga:Low-impact static positioning favors 10mm TPE or natural rubber with textured anti-slip surfaces. Practitioners in California's Proposition 65 jurisdiction drive demand for phthalate-free and per- and polyfluoroalkyl substance-free surface treatments.
- Pilates:Controlled movement patterns on specialized equipment require thinner, denser mats with closed-cell construction for hygiene and equipment stability.
- Aerobics:High-repetition impact exercise demands cushioned EVA or TPE constructions with rapid rebound characteristics for joint protection during plyometric movements.
Specification standardization is highest in Strength Training. Application diversity is expanding fastest in Yoga.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting production investment toward regions with stable compliance costs, as manufacturers seek to avoid the margin compression from dual-SKU strategies forced by fragmented chemical restrictions.
United States
California's Department of Toxic Substances Control enforces phased restrictions on short-chain chlorinated paraffins in rubber compounding, compelling manufacturers to maintain parallel inventory streams for West Coast distribution. The US Consumer Product Safety Commission monitors flammability standards for foam-based exercise equipment, extending product qualification timelines. CrossFit boxes and boutique studios in Texas and Florida are compressing equipment replacement cycles to eighteen-month intervals.
Germany
German fitness chains specify 20mm+ rubber constructions for functional training zones, driven by insurance liability requirements for dropped equipment protection. The EU REACH regulation mandates disclosure of Substances of Very High Concern in PVC plasticizer formulations, forcing reformulation across European distribution channels. The Ruhr industrial corridor hosts concentrated demand from premium studio operators seeking captive recycled tire content for sustainability positioning.
China
Tier-one city gym chains in Shanghai and Beijing are shortening mat replacement cycles as boutique fitness formats expand. The Ministry of Ecology and Environment enforces dual carbon goals that favor domestic processors with integrated devulcanization capabilities. Yangtze River Delta manufacturing clusters supply controlled feedstock for commercial rubber flooring, insulating producers from spot-market synthetic latex volatility.
India
The country's PLI scheme for sports goods manufacturing offers tariff advantages for domestic rubber compounding investments targeting gym chain procurement. Maharashtra and Gujarat industrial zones are attracting capacity expansion from contract manufacturers seeking to serve Middle East and African export markets. Delhi-NCR fitness operators are unbundling equipment procurement from traditional full-service gym fit-out contractors.
United Kingdom
London and Southeast England studio clusters are establishing direct relationships with specialized flooring vendors for customized thickness and color specifications. The UK's post-Brexit regulatory framework maintains alignment with EU REACH SVHC disclosure requirements, preserving market access for compliant importers. Midlands-based distributors are consolidating procurement for independent boutique operators seeking phthalate-free formulations.
Gym Mats Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based material differentiation and direct-to-studio distribution channels. The vendor base stratifies across three tiers: integrated compounders with captive recycling streams, specialized flooring contractors serving commercial fit-outs, and branded consumer goods specialists. Two dominant competitive moves are reshaping positioning: backward integration into post-consumer tire processing and bypass of traditional sporting goods wholesalers through captive e-commerce portals.
Within the integrated compounder tier, Regupol America Corp. and Tarkett S.A. exemplify upstream control strategies, while Manduka occupies a position in the plantation-certified natural rubber segment. Among specialty fabricators, Rubber-Cal, LLC and American Floor Mats, Inc. represent the commercial flooring contractor archetype. These named entities serve as anchors for understanding how material sourcing advantages and distribution model innovation are concentrating margin capture.
| Leading Market Players |
|---|
| Regupol America Corp. |
| American Floor Mats, Inc. |
| Tarkett S.A. |
| Lululemon Athletica Inc. |
| Net World Sport Ltd. |
| Gerflor SA |
| Rubber-Cal, LLC |
| Manduka |
| Forbo International SA |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between 20mm commercial rubber constructions and sub-15mm residential TPE alternatives manifests in divergent margin structures and sourcing strategies across the gym mats industry. Premium tier specifications command captive recycling feedstock and certified plantation documentation, while commodity tiers compete on spot-market synthetic latex arbitrage and standardized PVC formulations.
Pricing Analysis
Distributor markups compress as boutique studios disintermediate traditional sporting goods wholesalers through direct manufacturer portals. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with REACH SVHC-compliant formulations and Proposition 65 phthalate-free alternatives commanding substantial premiums over legacy PVC constructions. Pricing pressure stems from ethylene and propylene derivative volatility for EVA and TPE compounders lacking long-term offtake agreements. Home users in California exhibit highest price sensitivity due to mandatory dual-SKU inventory costs, while German fitness chains demonstrate lowest sensitivity given insurance liability mandates for dropped equipment protection.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta manufacturing clusters and Pennsylvania recycling facilities are tightening operational flexibility for tier-one suppliers. Geographic concentration centers on China for virgin rubber compounding, Germany for bio-based polyurethane processing, and the United States for post-consumer tire devulcanization. Raw material dependencies include natural latex from Thai and Malaysian plantations, synthetic rubber from petrochemical crackers, and castor oil-derived polyols from European suppliers. Single-source vulnerability in Southeast Asian natural latex exposes processors to climate disruption and export quota variability. Distribution runs through specialized flooring contractors for commercial fitness center fit-outs, with direct-to-studio e-commerce gaining share in boutique segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gym mats market reads as a late-cycle quality story where boutique fitness expansion and regulatory compliance mandates are elevating specification requirements toward premium, certified constructions with full material traceability.
For Market Incumbents: Deepen backward integration into post-consumer tire processing to insulate margin structures from synthetic latex spot-market volatility. Regupol America Corp.'s captive Pennsylvania shredding facilities demonstrate how controlled feedstock supply neutralizes petrochemical input swings. Prioritize REACH SVHC certification investment to capture replacement demand across German fitness chains as legacy PVC inventories face market exclusion. For New Entrants and Emerging Players: Launch via direct-to-studio e-commerce portals targeting India's PLI scheme beneficiaries and Middle East export corridors. Maharashtra and Gujarat industrial zones offer tariff-advantaged rubber compounding capacity with underpenetrated gym chain procurement relationships. Target bio-based polyurethane differentiation using European castor oil polyol suppliers to position for carbon footprint-conscious studio operators in Germany's Ruhr corridor. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack capital for devulcanization equipment integration and dual-SKU inventory strategies. Long-term viability favors integrated compounders with captive recycling streams and in-house logistics capabilities over contract manufacturers exposed to margin compression. Watch for California DTSC enforcement acceleration against short-chain chlorinated paraffins as an inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tire Recycling | Captive shredding facilities in Pennsylvania and Ohio neutralize synthetic latex price volatility for commercial rubber flooring. |
| Bio-Based Polyurethane Transition | Castor oil-derived polyols from European suppliers enable premium studio positioning under EU Green Deal carbon frameworks. |
| Direct-to-Studio Distribution Launch | Bypassing traditional sporting goods wholesalers collapses distributor margins while rewarding manufacturers with design capabilities. |
| REACH SVHC Compliance Certification | Material passport disclosure mandates across German fitness chains and Nordic studios create replacement demand for compliant inventories. |
| India PLI Scheme Manufacturing Investment | Domestic rubber compounding capacity in Maharashtra targets tariff advantages for Middle East and African export markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with rubber compounders, fitness center procurement directors, boutique studio operators, and flooring installation contractors alongside secondary validation. Trade data from customs authorities, chemical industry association reports, SEC filings from listed flooring manufacturers, and regulatory disclosure databases from ECHA and California DTSC anchored the analysis. Bottom-up volume modeling across material type and thickness tiers triangulated against top-down market sizing from regional production cluster assessments.
Segment-weighting approaches distributed value and volume across rubber, TPE, PVC, and EVA material categories, with thickness specifications from 10mm to 25mm and end-user splits between commercial fitness centers, home users, sports teams, and educational institutions. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory-driven inventory turnover, with inputs from synthetic latex pricing indices and plantation rubber export quotas.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction expansion in anti-slip coatings and severe climate disruption in Thai rubber belt harvesting. Practitioners should monitor California DTSC enforcement calendars and EU REACH SVHC candidate list updates for early signals of compliance-driven replacement demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
South Korea Gym Accessories Market