
 Gymnastic Bench Market | 2026-2036
Gymnastic Bench Market Size, Share, and Industry Trends Forecast 2026-2036
Gymnastic Bench Market Analytics
Direct-to-institution sales is tilting as dominant channel strategy for gymnastic bench procurement, bypassing traditional retail intermediaries to secure bulk contracts with educational and sports federations. Spieth Gymnastics leverages its German engineering heritage to dominate European federation supply chains. American Athletic sustains domestic manufacturing scale for U.S. collegiate and Olympic training center contracts. Gymnova SAS anchors its position through specialized competition-grade certifications that restrict market access for uncertified rivals.
A gymnastic bench is a padded, rigid platform apparatus engineered for skill development, conditioning, and competitive routine preparation in artistic gymnastics, typically constructed with steel or hardwood frames supporting high-density foam surfaces covered in synthetic leather or carpet. Manufacturing emphasizes dimensional tolerances, load-bearing capacity, and surface friction coefficients to meet FIG apparatus standards and ensure athlete safety during dynamic movements. Training benches and tumbling benches lead volume demand from schools and athletic clubs, while adjustable benches command premium positioning among professional teams seeking multi-function equipment. Steel-framed products dominate commercial durability requirements, though wood retains preference in European markets where traditional craftsmanship aligns with club procurement aesthetics.
ISO 5903 apparatus standards and FIG equipment norms govern international competition eligibility, compelling manufacturers to maintain certified production lines or face exclusion from official procurement channels. In the United States, ASTM F1749 playground and sports equipment guidelines influence institutional liability assessments, while European manufacturers navigate CE marking and REACH chemical compliance for foam and synthetic surface materials. Stakeholders must monitor evolving national sports federation budget allocations and certification reciprocity agreements between regulatory bodies to anticipate procurement cycle timing and geographic expansion feasibility.
Market Dynamics
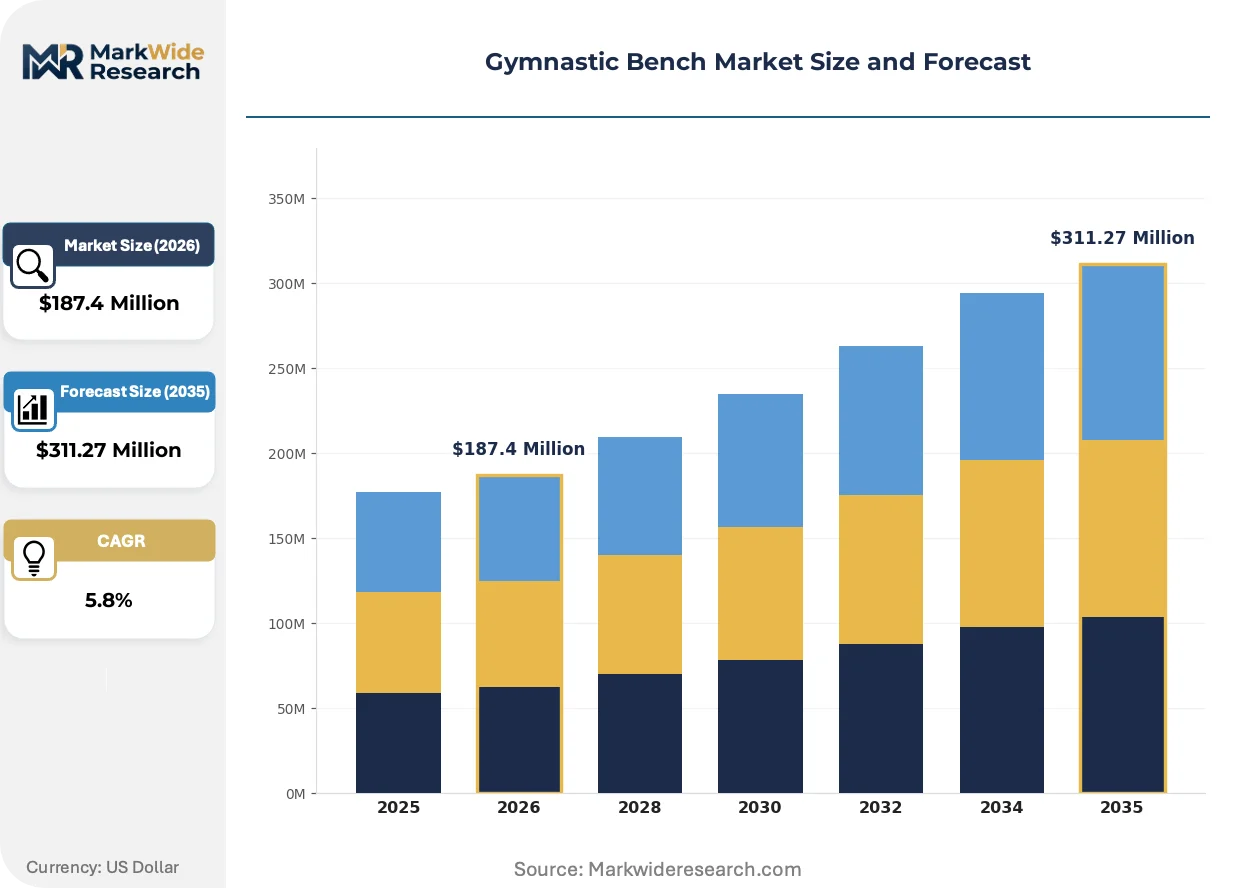
Federation procurement cycles and FIG certification reciprocity agreements are compressing vendor qualification timelines, forcing manufacturers to synchronize production capacity with national sports budget approvals rather than independent commercial calendars.
Growth Catalysts
- Federal sports funding:Germany's federal sports budget allocations and the United States' investment in Olympic training infrastructure sustain institutional replacement cycles for competition-grade apparatus.
- FIG apparatus standards:International Gymnastics Federation equipment norms mandate certified production lines, creating procurement barriers that protect incumbent suppliers with established certification pathways.
- High-density foam surfaces:Advances in synthetic leather bonding and carpet friction coefficient engineering enable manufacturers to meet dynamic load-bearing requirements for elite training environments.
Market Restraints
- Steel price volatility:Commercial-grade bench frames depend on steel input costs, exposing manufacturers to raw material margin compression without pass-through mechanisms in fixed-price federation contracts.
- CE marking complexity:European manufacturers face REACH chemical compliance costs for foam and synthetic materials, elevating production expenses relative to non-CE markets.
- Wood frame durability limits:Traditional hardwood construction preferred in European club aesthetics requires higher maintenance cycles than steel alternatives, constraining total addressable market expansion.
Strategic Opportunities
- Adjustable bench multi-functionality:Professional teams seeking equipment versatility create premium positioning for manufacturers capable of engineering height and angle modulation systems.
- Direct-to-institution channel bypass:Bulk contract negotiation with educational and sports federations eliminates retail intermediary margins and secures multi-year revenue visibility.
- ASTM F1749 alignment:United States institutional liability assessments under playground and sports equipment guidelines reward manufacturers with documented safety compliance, differentiating certified suppliers in litigation-sensitive procurement environments.
Industry Challenges
- ISO 5903 certification timelines:Competition-grade apparatus approval requires sustained laboratory testing and documentation, delaying market entry for new product lines by 12-18 months.
- Skilled foam fabrication labor:High-density surface construction demands specialized bonding technicians, creating workforce bottlenecks in manufacturing clusters without established gymnastics equipment heritage.
- Legacy frame integration:Clubs with existing hardwood bench investments resist full apparatus replacement, forcing suppliers to engineer retrofit compatibility or sacrifice upgrade revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gymnastic Bench Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Training Bench, Folding Bench, Adjustable Bench, Tumbling Bench Material: Wood, Steel, Foam, Synthetic End User: Schools, Athletic Clubs, Home Users, Professional Teams Size: Standard, Mini, Custom, Oversized |
| Companies Covered | Spieth Gymnastics, Gymnova SAS, Janssen-Fritsen, Kübler Sport GmbH, DimaSport, MTB Group, Continental Sports Ltd, American Athletic, Norbert's Athletic Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gymnastic Bench Market Evolving Landscape
Sensor-embedded training surfaces and digital performance analytics are penetrating elite gymnastics facilities, converting static apparatus into data-capture nodes that reshape how coaches evaluate athlete progression and equipment utilization.
Force-sensitive resistor arrays integrated beneath bench padding enable real-time measurement of impact distribution and repetition counting. National Olympic training centers in Germany and the United States are piloting these systems for routine optimization. This sensor architecture is digitizing how federations allocate equipment budgets toward measurable performance outcomes rather than durability metrics alone.
REACH chemical compliance enforcement through ECHA is accelerating foam formulation substitutions across European manufacturing. Manufacturers reformulating synthetic leather and carpet surfaces to eliminate restricted substances face temporary production line reconfiguration costs. German and French suppliers with in-house chemical laboratories are absorbing these transitions faster than smaller competitors dependent on third-party material sourcing.
Club procurement committees are unbundling after-sales service from equipment purchase contracts, negotiating separate maintenance agreements with regional specialists rather than manufacturer-authorized technicians. This disintermediation compresses vendor service margins while expanding independent repair market participation. The pattern is most pronounced in United States collegiate programs with dedicated equipment managers seeking cost control flexibility.
Gymnastic Bench Market Segmentation
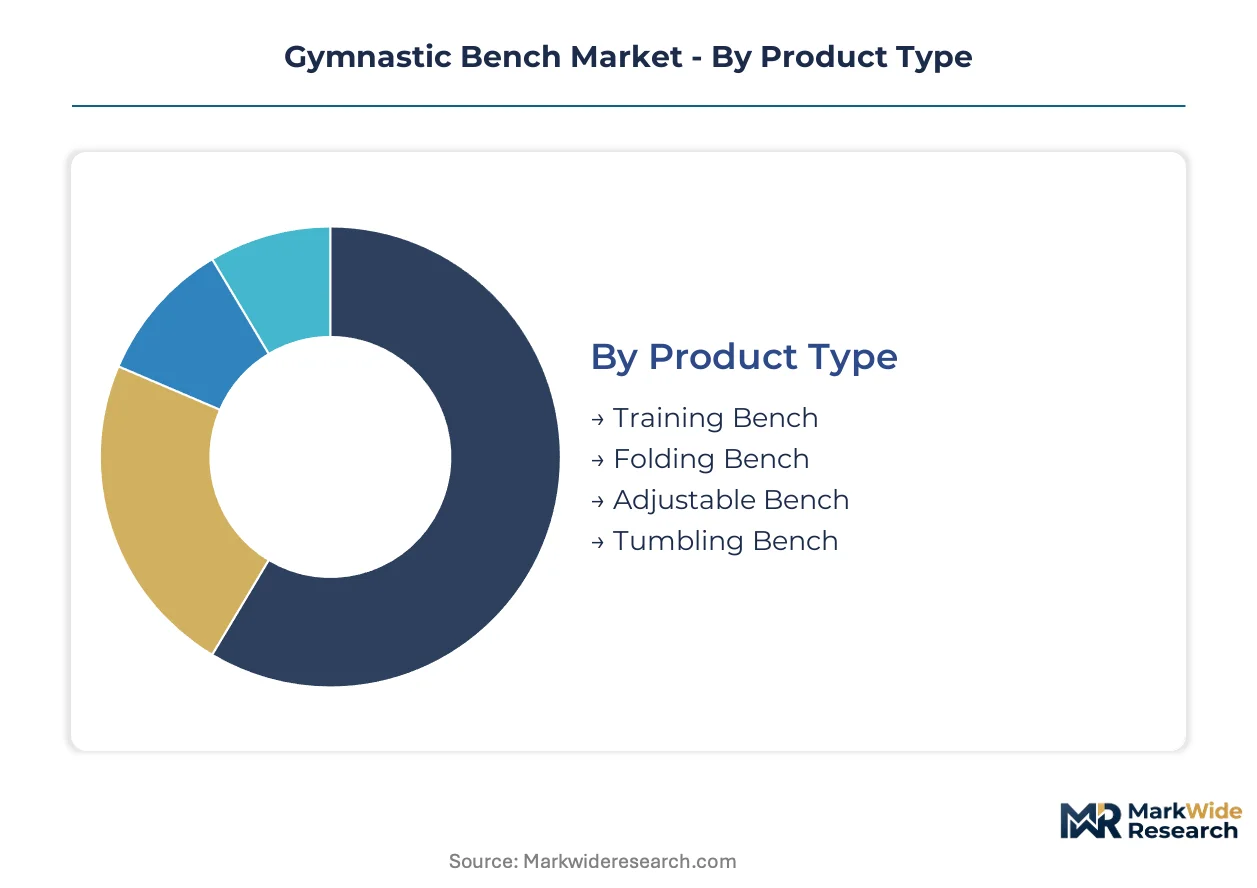
Segmentation in gymnastic bench procurement reveals divergent technical requirements across institutional and consumer tiers. Federation-certified apparatus demands diverge sharply from home fitness equipment, creating distinct manufacturing specifications and distribution channels within the same product category.
Product Type:
Application context determines structural engineering priorities across bench categories.
- Training Bench:Fixed-height padded platforms with steel reinforcement dominate school and club procurement for foundational skill development. German and United States athletic federations specify these for standardized curriculum deployment across regional training centers.
- Adjustable Bench:Height and angle modulation systems command premium positioning among professional teams seeking multi-function equipment for diverse routine preparation. National Olympic training centers in both Germany and the United States prioritize these for elite athlete programming.
- Folding Bench:Collapsible frame designs address space-constrained facilities requiring rapid reconfiguration of training floors.
- Tumbling Bench:Extended runway configurations support momentum-based skill progression in competitive preparation environments.
Training bench holds installed capacity. Adjustable bench is rotating up the share rankings.
Material:
Cost tier and durability expectations shape raw material selection across customer segments.
- Steel:Commercial-grade welded frames satisfy institutional liability requirements and FIG load-bearing specifications. United States collegiate programs and Olympic training centers mandate steel construction for high-frequency use environments.
- Foam:High-density polyurethane formulations with calibrated compression resistance enable dynamic impact absorption for elite training. REACH chemical compliance through ECHA is forcing formulation substitutions among European manufacturers.
- Wood:Traditional hardwood construction retains preference in German and French club markets where craftsmanship aesthetics align with procurement committees.
- Synthetic:Bonded surface coverings including synthetic leather and carpet materials deliver friction coefficient control for athlete safety.
Steel dominates commercial procurement volume. Foam is gaining share fastest through certification requirements.
End User:
Customer type dictates pricing tolerance, certification stringency, and replacement cycle frequency.
- Schools:Federal sports funding in Germany and institutional procurement through U.S. collegiate systems sustain bulk replacement cycles for standardized apparatus.
- Professional Teams:National Olympic training centers and elite clubs demand FIG-certified competition-grade equipment with documented ASTM F1749 alignment for liability protection.
- Athletic Clubs:Private membership facilities balance durability requirements with aesthetic preferences, particularly in European markets.
- Home Users:Individual consumers prioritize collapsible designs and price accessibility over federation certification standards.
Schools hold installed capacity. Professional teams are rotating up the share rankings.
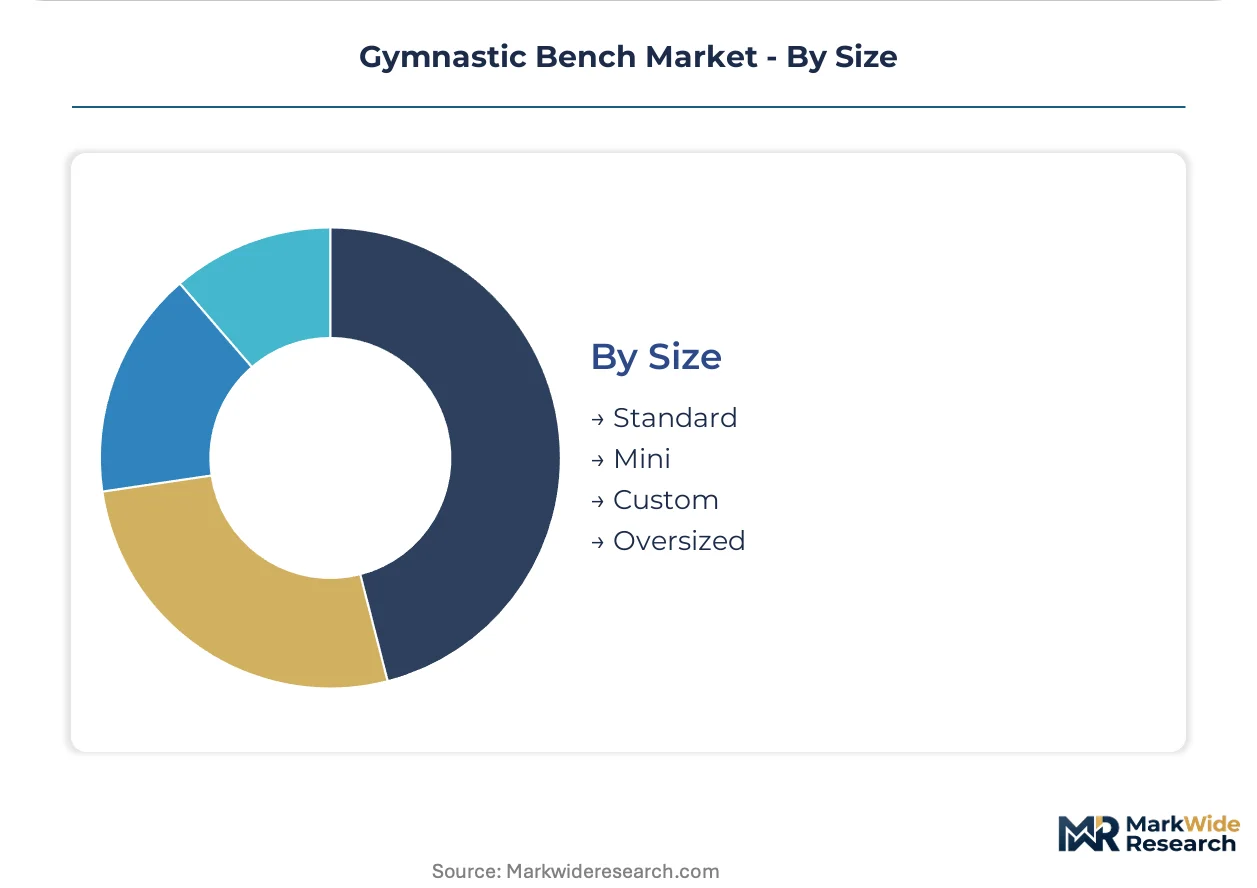
Size:
Volume requirements and facility constraints create dimensional specialization across deployment contexts.
- Standard:FIG-specified dimensions govern competition eligibility and dominate federation procurement specifications in both Germany and the United States.
- Custom:Facility-specific modifications accommodate non-standard training spaces or specialized routine preparation requirements.
- Mini:Reduced-scale designs serve youth programming and introductory skill development in space-limited school environments.
- Oversized:Extended platforms support advanced tumbling progressions and multi-athlete training configurations.
Standard size holds installed capacity. Custom configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal sports funding mechanisms and FIG certification reciprocity agreements are concentrating procurement activity in markets with established gymnastics infrastructure and standardized institutional purchasing channels.
United States
Collegiate athletic programs and Olympic training centers drive apparatus replacement cycles through NCAA and USOPC procurement frameworks. ASTM F1749 compliance requirements shape institutional liability assessments for competition-grade equipment. Colorado Springs anchors domestic demand concentration through the U.S. Olympic & Paralympic Training Center's equipment standardization programs.
Germany
Bundesstiftung Sport federal allocations sustain club and school procurement through standardized regional training center networks. DIN standards alignment with FIG apparatus norms creates certification efficiency for domestic manufacturers. Stuttgart and Frankfurt metropolitan clusters concentrate federation-affiliated equipment suppliers serving southwestern state sports associations.
France
Ministry of Sport facility modernization grants accelerate municipal gymnasium apparatus replacement in preparation for major event hosting cycles. ECHA REACH enforcement drives foam formulation substitutions among domestic surface material suppliers. Lyon and Grenoble manufacturing clusters specialize in competition-grade bench production for federation export contracts.
China
General Administration of Sport of China provincial training base investments expand apparatus procurement for national team development pipelines. GB standards convergence with FIG technical specifications enables certified production line qualification. Shanghai and Guangdong manufacturing zones scale steel-frame bench output for domestic federation and Southeast Asian export markets.
Japan
Japan Sports Agency facility subsidy programs support municipal gymnasium equipment modernization in advance of international event hosting rotations. JIS standards alignment with FIG apparatus norms streamlines certification pathways for domestic manufacturers. Nagoya industrial clusters produce specialized training benches for JOC-affiliated regional development centers.
Gymnastic Bench Market Competitive Landscape
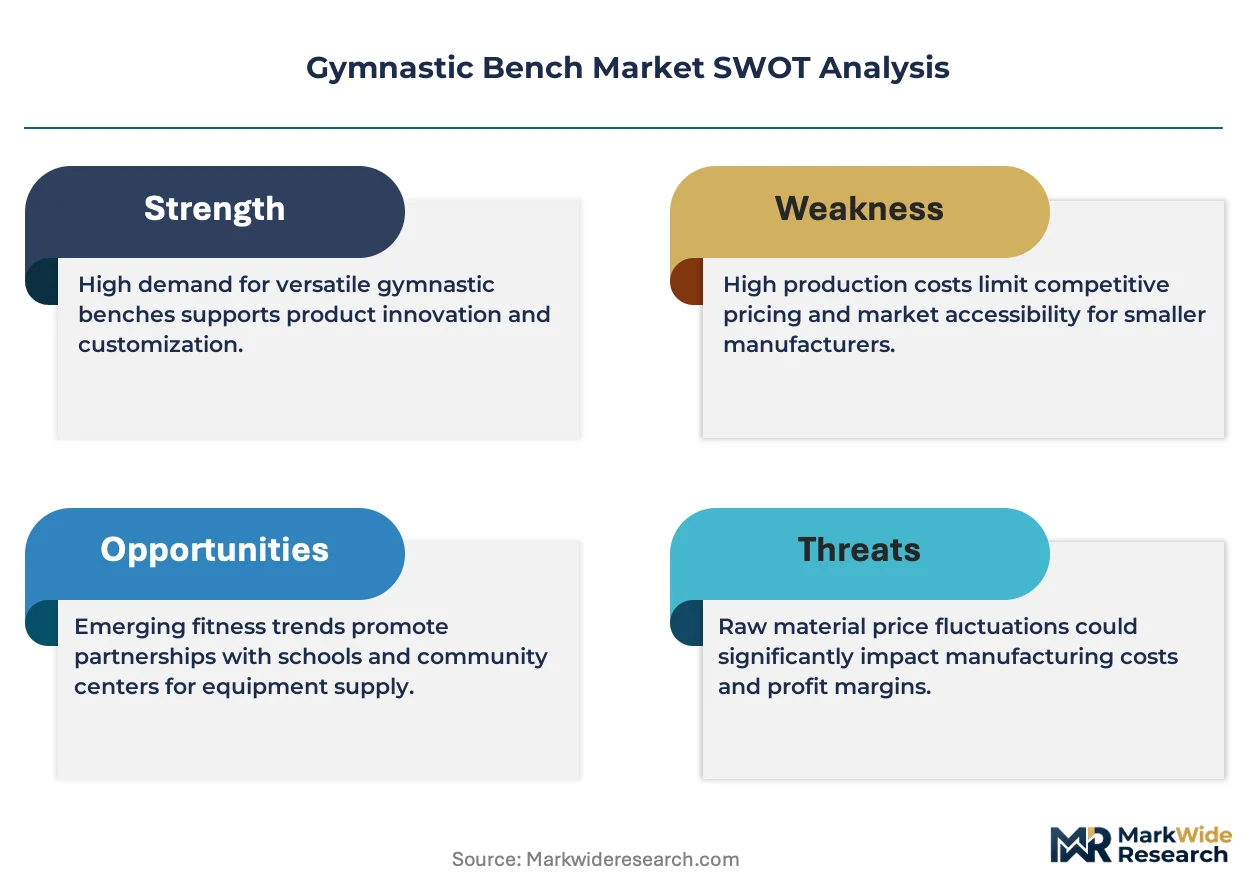
On the supply side, the industry is structured around certification-dependent tiering that privileges incumbents with established FIG laboratory relationships and documented production line audits. Federation procurement contracts concentrate volume among suppliers with multi-decade certification track records, while smaller fabricators occupy regional club and school segments with lower compliance thresholds. Three archetypes dominate: heritage European engineering houses, North American institutional specialists, and Asian scale manufacturers. Competitive positioning depends on certification maintenance investments and direct-to-federation sales channel cultivation rather than price competition.
Among heritage European engineering houses, Spieth Gymnastics and Gymnova SAS exemplify the certification-anchored tier that dominates federation supply chains through multi-generational FIG apparatus relationships. Janssen-Fritsen occupies a position within this same archetype, representing Dutch manufacturing traditions in competition-grade apparatus. These entities anchor the premium segment where certification documentation rather than unit economics determines procurement outcomes.
| Leading Market Players |
|---|
| Spieth Gymnastics |
| Gymnova SAS |
| Janssen-Fritsen |
| Kübler Sport GmbH |
| DimaSport |
| MTB Group |
| Continental Sports Ltd |
| American Athletic |
| Norbert's Athletic Products |
| Others |
Value Network & Pricing Analysis
Stuttgart's manufacturing cluster concentrates European federation-grade bench production, translating certification-holding capacity into pricing power over institutional buyers locked into FIG-compliant procurement channels. This geographic concentration enables incumbent suppliers to command premium positioning while newer entrants absorb 12-18 month ISO 5903 laboratory testing delays without revenue.
Pricing Analysis
Certification level creates the primary spread between premium FIG-grade apparatus and uncertified training equipment. Three-tier pricing structure separates federation-specified competition benches from institutional training models and consumer-grade home fitness units. Pricing pressure stems from steel input cost volatility that manufacturers cannot fully pass through fixed-price multi-year federation contracts. Schools and municipal programs exhibit highest price sensitivity, while national Olympic training centers prioritize documented ASTM F1749 alignment over unit economics.
Supply Chain Analysis
Extended payment terms from federation procurement cycles force manufacturers to maintain supply-chain finance facilities or absorb working capital strain. Production concentrates in Germany, the United States, and China, with each hub serving distinct certification and cost-tier requirements. Steel framing, high-density polyurethane foam, and synthetic leather coverings constitute the critical input trinity. Single-source vulnerability runs through REACH-compliant foam formulation suppliers in Europe. Distribution runs through direct-to-institution contracts that bypass retail intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded training surfaces represent the substitution threat that static apparatus incumbents must neutralize through digital capability integration or partnership strategies.
For Market Incumbents: Entrench federation relationships through accelerated FIG certification reciprocity investments that compress rival qualification timelines. Deepen backward integration into high-density foam fabrication to capture margin from REACH-driven formulation transitions and eliminate third-party chemical laboratory dependencies that delay production line reconfiguration. For New Entrants and Emerging Players: China's provincial training base expansion outside Shanghai and Guangdong manufacturing zones offers underpenetrated institutional demand with less entrenched incumbent presence. Target municipal gymnasium modernization programs in France's Ministry of Sport grant cycles, positioning collapsible folding bench designs that address space-constrained facility requirements without requiring full competition-grade certification investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage European engineering houses with established FIG laboratory relationships over Asian scale manufacturers facing certification barrier extension. Long-term viability rests on sensor-embedded product line integration capability. Acquisition targets should demonstrate in-house chemical formulation expertise to absorb ECHA enforcement transitions. Watch federation budget allocation timing signals as procurement cycle inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| FIG Certification Fast-Track Investment | Compresses 12-18 month laboratory testing timelines to outpace rival market entry. |
| Sensor-Embedded Surface Development | Converts static benches into data-capture nodes for Olympic training center contracts. |
| REACH-Compliant Foam Backward Integration | Eliminates third-party chemical laboratory dependencies accelerating formulation transitions. |
| Direct-to-Federation Channel Expansion | Bypasses retail intermediaries to secure multi-year bulk contract revenue visibility. |
| Regional Service Network Disintermediation | Captures maintenance revenue from club procurement committees unbundling after-sales agreements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with gymnastics equipment procurement officers, federation technical directors, foam fabrication specialists, and institutional facility managers; and secondary validation through FIG apparatus norm documentation, ECHA REACH substance restriction databases, ASTM F1749 safety guideline records, and national sports federation budget allocation disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across product type, material composition, end-user category, and dimensional specifications.
Forecast inputs incorporated federation procurement cycle timing, certification reciprocity agreement expansion trajectories, and raw material cost pass-through elasticity across the projection horizon. Segmentation modeling spanned training versus competition-grade equipment tiers, steel versus wood frame construction preferences, and institutional versus consumer distribution channels. CAGRs derived from regression analysis of historical replacement cycle patterns mapped against projected federal sports funding allocations.
Practitioners should monitor steel price volatility indices and ECHA substance restriction proposal timelines for early signals of margin compression or formulation reconfiguration requirements. Forecasts reflect assumptions of sustained FIG certification reciprocity and stable national sports budget trajectories. Macroeconomic contraction, regulatory deviation, or sensor technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Indoor Smart Bikes Market