
 Edge Banding Materials Market | 2026-2036
Edge Banding Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Banding Materials Market Intelligence
Polypropylene edge banding is recalibrating cost-performance benchmarks across mid-range furniture lines as manufacturers seek alternatives to PVC amid regulatory pressure on chlorinated polymers. SURTECO GmbH leverages its European coating technology base to sustain premium positioning in wood-veneer laminates. REHAU Ltd. anchors its competitiveness through integrated polymer compounding operations that control raw material quality for ABS edge banding. Veena Polymers dominates Indian domestic supply with specialized extrusion capabilities serving Gujarat and Maharashtra furniture clusters.
Edge banding materials are narrow strips, typically 0.4 to 3.0 millimeters in thickness, applied to the exposed edges of particleboard, MDF, and plywood substrates through hot-melt adhesive bonding or laser fusion to provide moisture protection and aesthetic finish matching surface laminates. PVC formulations currently lead volume consumption across furniture manufacturing applications due to their balance of flexibility, durability, and cost, though ABS segments are capturing faster growth in European cabinetry markets where recyclability credentials influence specification decisions. Pre-glued roll formats concentrate margin pools through convenience premiums charged to carpentry workshops and smaller fabricators lacking in-house adhesive application equipment.
EPA TSCA Title VI formaldehyde emission standards and the EU REACH Regulation's restrictions on phthalate plasticizers are compelling reformulation of PVC edge banding toward non-phthalate stabilizer systems, while China's GB standards for interior decoration materials impose parallel compliance burdens on export-oriented manufacturers. ISO 9001 quality management certification has become a baseline market access requirement for suppliers serving multinational furniture brands. Stakeholders must monitor evolving polymer substitution patterns as bio-based thermoplastic developments challenge conventional petroleum-derived edge banding economics.
Market Dynamics
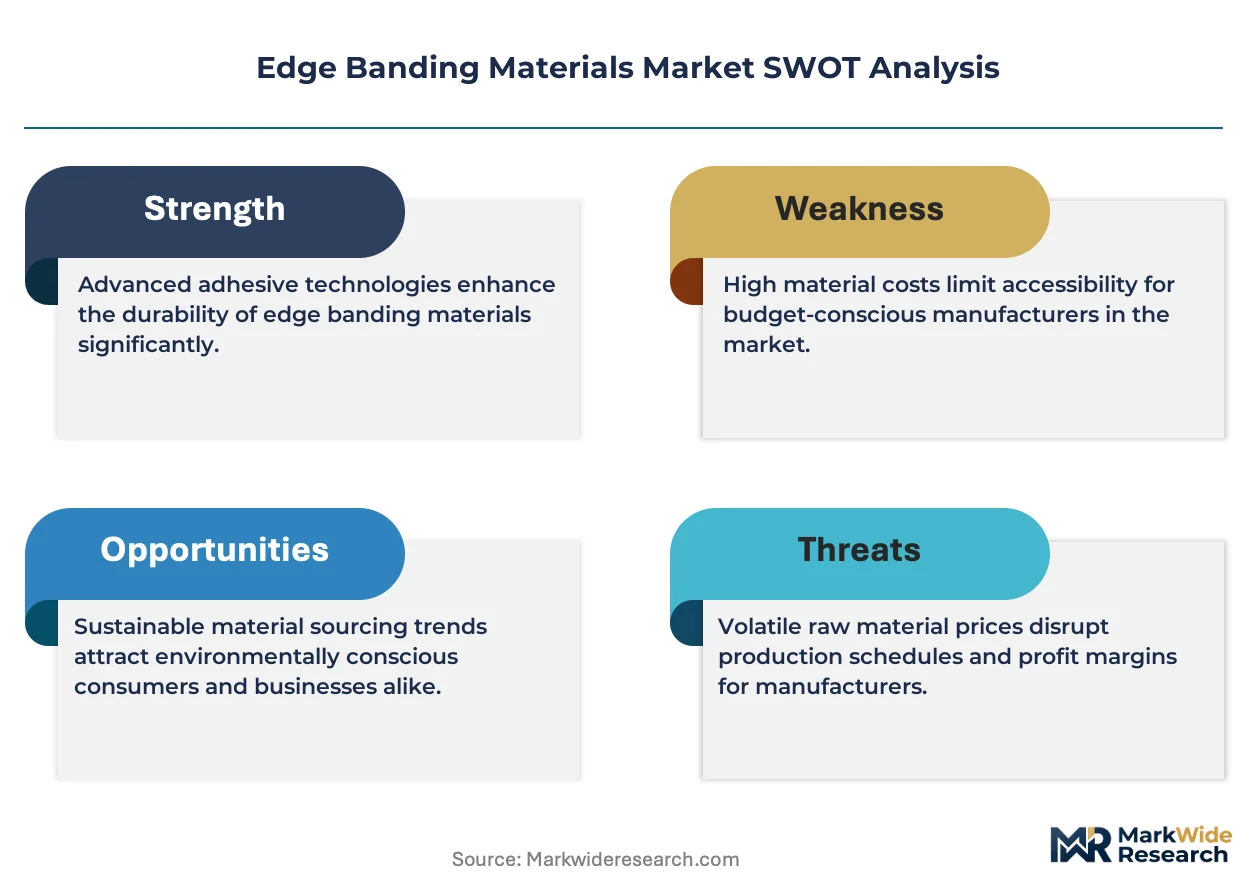
Regulatory pressure on chlorinated polymers is fragmenting competitive positioning across edge banding materials, forcing manufacturers to reconfigure formulation strategies and raw material sourcing while furniture brands accelerate specification audits for compliance documentation.
Growth Catalysts
- REACH phthalate restrictions:European cabinetry manufacturers are redirecting procurement toward ABS and polypropylene formulations, creating specification momentum for non-PVC alternatives in export-oriented production.
- Residential furniture manufacturing clusters:Guangdong Province's integrated supply chains absorb high volumes of thermoplastic edge banding, anchoring procurement scale for cost-competitive PVC and ABS grades.
- Laser fusion bonding technology:Premium furniture lines in Germany and Italy are adopting solvent-free edge application systems, eliminating adhesive inventory costs and accelerating production throughput.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price swings directly compress margins on PVC and ABS edge banding, constraining pricing flexibility for extrusion specialists without backward integration into polymer compounding.
- Supply concentration in East Asian resin production:Overreliance on Chinese and South Korean petrochemical complexes for base polymers creates exposure to regional logistics disruptions and export licensing delays.
- Technical performance gaps in bio-based alternatives:Current thermoplastic starch and PLA formulations lack the moisture resistance and dimensional stability required for kitchen and bathroom cabinetry applications.
Strategic Opportunities
- Underpenetrated Indian organized furniture retail:Gujarat and Maharashtra manufacturing clusters present whitespace for ABS edge banding suppliers as modular kitchen adoption accelerates in Tier-2 cities.
- EPA TSCA Title VI compliance services:Third-party certification and chain-of-custody documentation for low-formaldehyde substrates create adjacent revenue streams for material distributors serving US export markets.
- Pre-glued roll convenience premium:Carpentry workshops lacking hot-melt equipment represent a channel expansion opportunity through format innovation rather than formulation change.
Industry Challenges
- Polymer formulation talent scarcity:Specialized expertise in non-phthalate stabilizer systems and compatibilizer chemistry commands premium compensation, constraining R&D throughput at mid-tier extruders.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of EPA TSCA Title VI, EU REACH, and China GB standard compliance extends product launch cycles and strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Banding Materials Market |
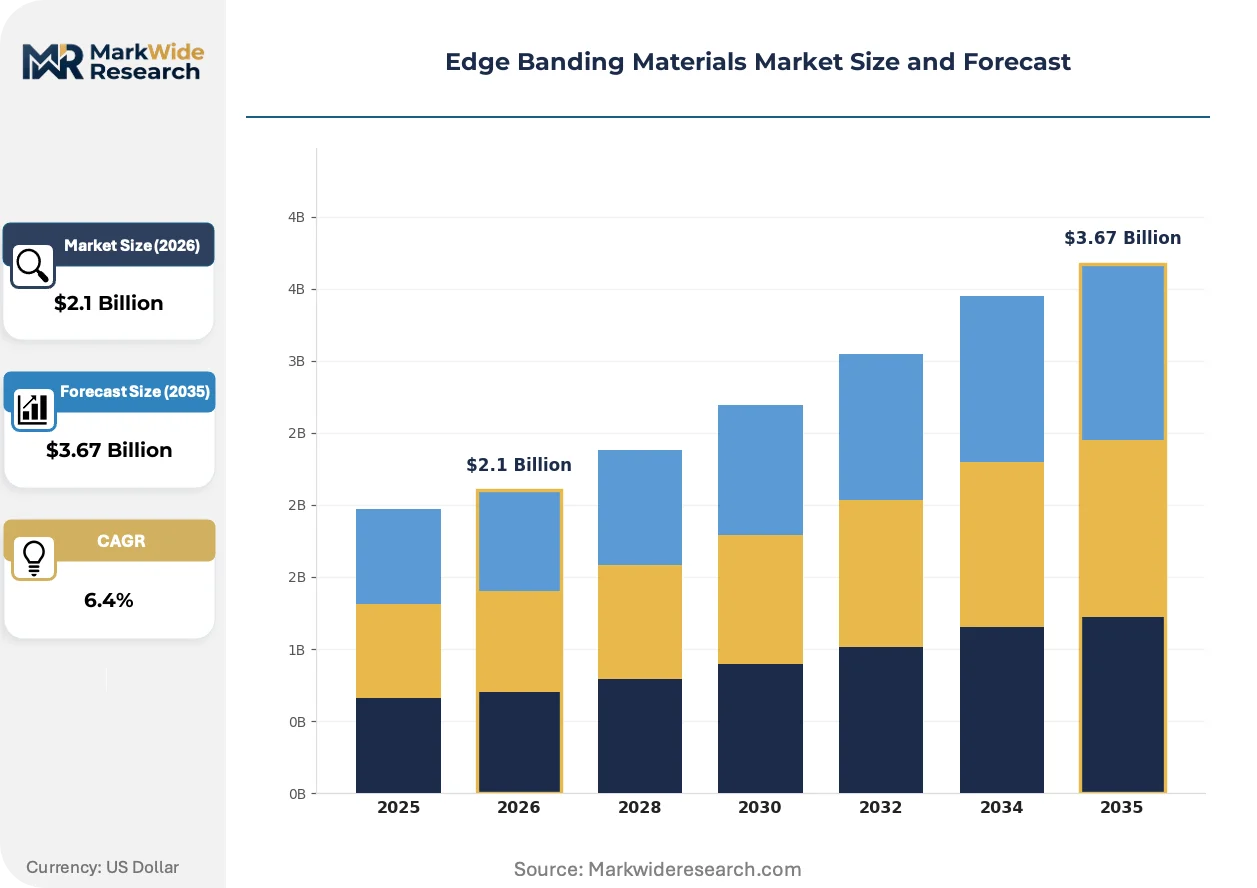
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, ABS, Wood Veneer, Acrylic, Melamine, Polypropylene Application: Furniture Manufacturing, Interior Decoration, Cabinetry, Office Fixtures, Retail Fixtures, Display Units Form: Rolls, Strips, Sheets, Pre-glued, Solid, Laminated End User: Carpentry Workshops, Furniture Assemblers, Interior Designers, Cabinet Fabricators, Shopfitters, Exhibit Builders |
| Companies Covered | Vaibhav Industries, E3 Panels, SURTECO GmbH, Gdecor Industries India Private Limited, EdgeCo Incorporated, REHAU Ltd., Veena Polymers, Paramount Composites India, Squareone Decor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Banding Materials Market Strategic Shifts & Innovations
Laser-compatible edge banding substrates and non-chlorinated polymer formulations are converging to redefine manufacturing economics and environmental compliance benchmarks across furniture production.
Polypropylene edge banding is consolidating its position in mid-range furniture specifications as manufacturers seek cost-performance parity with PVC while satisfying retailer sustainability scorecards. European kitchen cabinet producers have accelerated adoption since 2023, compressing the historical price premium versus conventional formulations. The technology is consolidating supply relationships around extruders with dedicated polypropylene compounding lines and color-matching capabilities.
REACH restrictions on phthalate plasticizers are forcing reformulation of flexible PVC edge banding toward calcium-zinc and organotin stabilizer systems. Industrial consequence includes elevated raw material costs and shorter formulation patent windows as compounders race to secure non-phthalate supply agreements. German and Italian cabinetry OEMs are most affected, responding with supplier consolidation toward REACH-registered compounders with documented substitution roadmaps.
Specification audits by multinational furniture brands are compressing supplier qualification cycles from multi-year frameworks to annual compliance reviews. Distributors serving IKEA, Herman Miller, and Steelcase are replacing transactional spot purchasing with integrated supply contracts bundling certification documentation, inventory management, and color consistency guarantees. This pattern is most visible in Poland and Vietnam, where export-oriented manufacturing hubs serve as compliance gateways to EU and North American retail channels.
Edge Banding Materials Market Segmentation
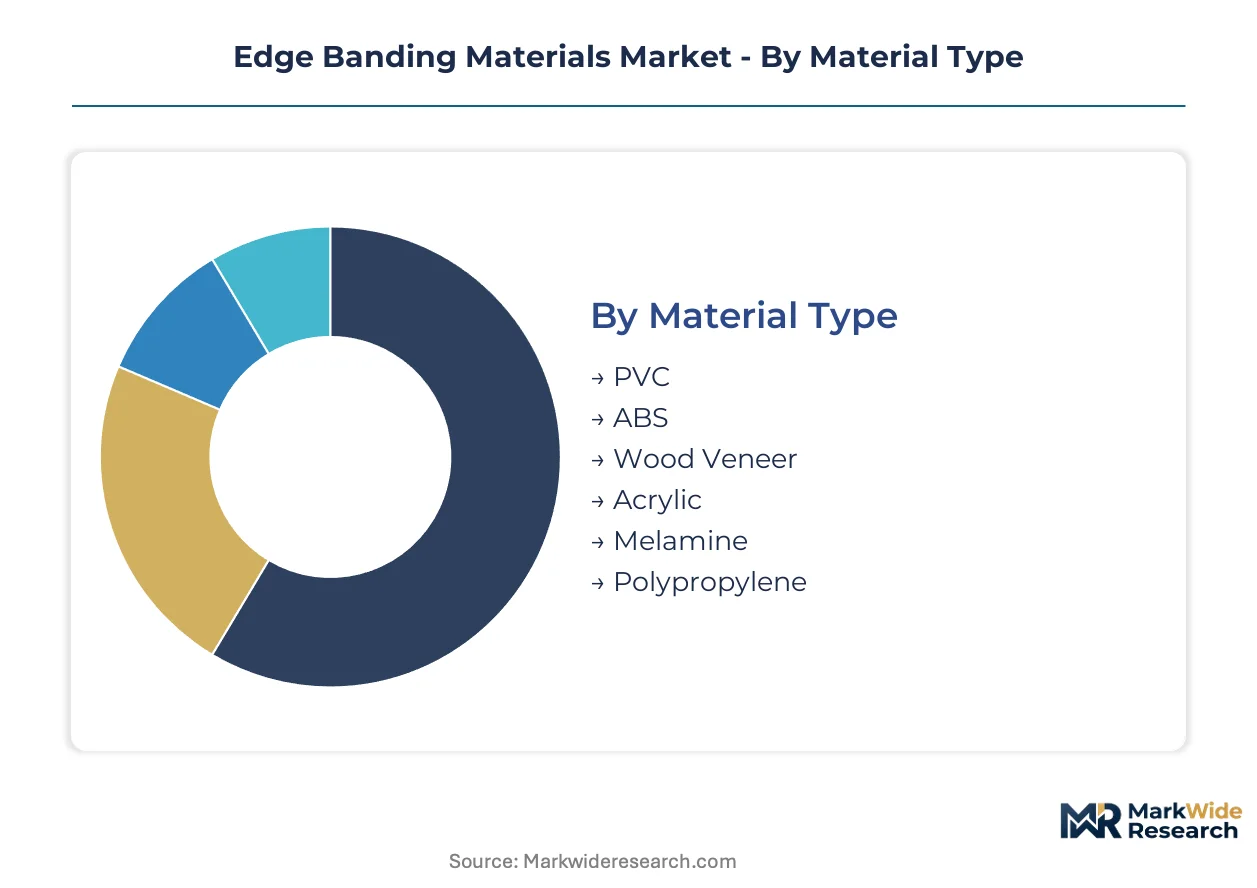
Edge banding procurement patterns diverge sharply across material chemistry, application intensity, and customer sophistication. Specification decisions cascade through furniture manufacturing clusters based on regulatory exposure, production scale, and adhesive application capabilities.
Material Type:
Replacement cycles for edge banding materials accelerate as REACH phthalate restrictions and EPA formaldehyde standards force reformulation investments, compressing the effective lifespan of legacy PVC specifications in export-oriented production.
- PVC:Chlorinated polymer formulations dominate volume consumption through flexibility, durability, and cost equilibrium across standard furniture lines. Guangdong Province manufacturing clusters absorb substantial procurement volumes despite regulatory pressure on phthalate plasticizers compelling stabilizer system transitions.
- ABS:Acrylonitrile-butadiene-styrene compositions capture specification momentum in European cabinetry markets where recyclability credentials influence procurement decisions. German kitchen OEMs have consolidated supply relationships around REACH-registered compounders with documented substitution roadmaps.
- Wood Veneer:Natural substrate laminates sustain premium positioning through aesthetic authenticity in high-end residential applications.
- Acrylic:Thermoplastic formulations deliver optical clarity and UV resistance for display fixture applications requiring visual impact.
- Melamine:Paper-impregnated thermoset surfaces provide cost-competitive edge protection matching laminate countertops in mass-market cabinetry.
- Polypropylene:Non-chlorinated polymer grades consolidate mid-range furniture specifications as manufacturers seek cost-performance parity with PVC while satisfying retailer sustainability scorecards.
Volume placements concentrate in PVC formulations; the faster expansion belongs to ABS and polypropylene alternatives.
Application:
Cost tier differentiation across application segments separates commodity specification from performance-grade procurement, with moisture exposure and visual prominence determining material selection thresholds.
- Furniture Manufacturing:Residential cabinetry production drives aggregate demand as particleboard and MDF substrate protection requirements scale with modular kitchen adoption. Chinese export manufacturers balance PVC cost advantages against ABS specification premiums for EU-bound shipments.
- Interior Decoration:Architectural millwork and built-in installations require color-matched edge solutions coordinating with surface laminate palettes. Italian design studios specify laser-compatible substrates enabling solvent-free bonding for premium residential contracts.
- Cabinetry:Kitchen and bathroom applications impose moisture resistance requirements favoring thermoplastic formulations over paper-based alternatives.
- Office Fixtures:Commercial workstation and storage systems prioritize durability under mechanical stress and frequent cleaning protocols.
- Retail Fixtures:Point-of-sale and showroom installations demand rapid color consistency across batch production runs.
- Display Units:Exhibition and museum applications combine aesthetic requirements with handling durability for reusable modular systems.
Procurement scale clusters in furniture manufacturing; display units and retail fixtures are climbing the fastest as experiential commerce investments expand.
Form:
Customer type and production infrastructure dictate format selection, with adhesive application capabilities creating sharp segmentation between integrated manufacturers and downstream fabricators.
- Rolls:Continuous coil formats enable high-throughput automated edge banding machinery in integrated furniture plants. Large-scale manufacturers in Poland and Vietnam specify jumbo rolls minimizing changeover downtime on German-engineered edge processing equipment.
- Strips:Cut-to-length segments serve manual application workflows in smaller fabrication shops lacking capital equipment investments. Indian carpentry workshops in Gujarat prefer pre-cut strips reducing material waste on low-volume custom projects.
- Sheets:Flat stock formats accommodate specialty cutting operations for curved or irregular edge profiles.
- Pre-glued:Hot-melt adhesive pre-applied formats command convenience premiums from workshops lacking in-house adhesive systems.
- Solid:Extruded monolithic profiles deliver structural edge protection for heavy-use commercial applications.
- Laminated:Multi-layer constructions combine substrate performance with surface aesthetic matching capabilities.
Roll formats dominate integrated manufacturing; pre-glued configurations are gaining share fastest among workshop-tier customers.
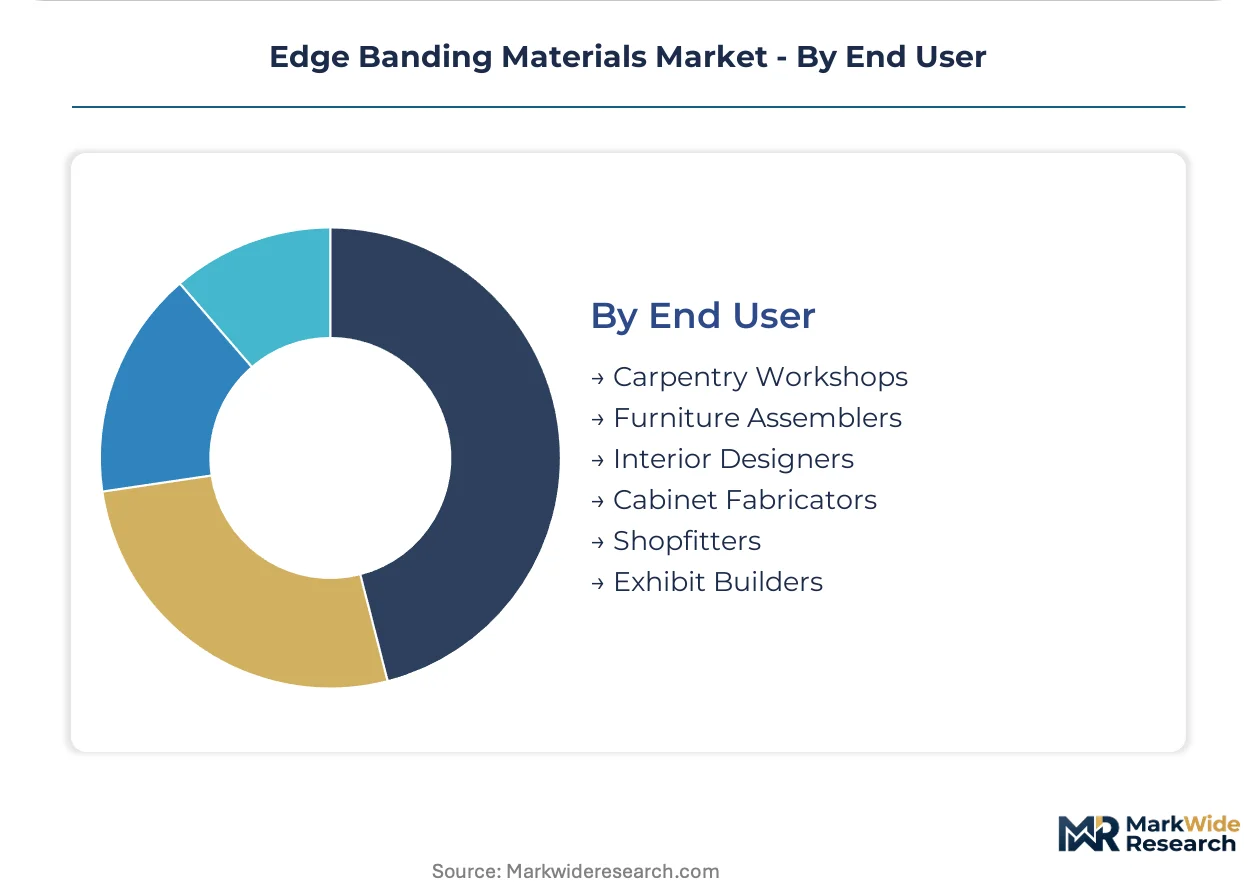
End User:
Technical sophistication and batch size variability separate end-user segments, with certification requirements and color consistency demands filtering supplier relationships.
- Carpentry Workshops:Small-scale woodworkers prioritize format convenience and minimum order flexibility over unit economics. Maharashtra furniture clusters source pre-glued rolls through regional distributors lacking technical specification support.
- Furniture Assemblers:Mid-tier manufacturers balance material cost against production throughput requirements on semi-automated equipment. Polish export-oriented assemblers maintain dual-source strategies for PVC and ABS grades contingent on destination market regulations.
- Interior Designers:Specification professionals prioritize aesthetic coordination and sample availability for project-based procurement.
- Cabinet Fabricators:Dedicated kitchen and bath specialists demand moisture-resistant formulations with documented compliance chain-of-custody.
- Shopfitters:Retail environment contractors require rapid turnaround on color-matched production runs with installation support.
- Exhibit Builders:Temporary structure specialists balance visual impact requirements with material reusability and storage efficiency.
Procurement volume concentrates among furniture assemblers; cabinet fabricators are expanding most quickly as modular kitchen adoption penetrates Tier-2 urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province's furniture manufacturing clusters absorb substantial procurement volumes of thermoplastic edge banding, anchoring demand concentration in export-oriented production serving North American and European retail channels.
China
Guangdong Province's integrated supply chains process high volumes of PVC and ABS edge banding for cabinetry export manufacturing. GB standards for interior decoration materials impose compliance burdens on manufacturers shipping to regulated markets. Dongguan and Foshan furniture clusters drive specification scale for cost-competitive thermoplastic grades.
Germany
Kitchen OEMs in Baden-Württemberg and Bavaria consolidate supply relationships around REACH-registered compounders with documented substitution roadmaps. ECHA restrictions on phthalate plasticizers accelerate procurement redirection toward ABS formulations. Stuttgart-area fabricators adopt laser-compatible substrates for solvent-free bonding in premium residential contracts.
United States
EPA TSCA Title VI formaldehyde emission standards compel reformulation investments across particleboard-dependent furniture manufacturing. Southeast manufacturing hubs in North Carolina and Virginia absorb specification-grade edge banding for domestic cabinetry production. Distributors serving multinational brands bundle certification documentation with inventory management services.
India
Gujarat and Maharashtra furniture clusters present whitespace for ABS edge banding suppliers as modular kitchen adoption accelerates in Tier-2 cities. BIS quality certification requirements filter supplier access to organized retail channels. Ahmedabad and Mumbai manufacturing zones source pre-glued roll formats through regional distribution networks.
Poland
Export-oriented manufacturing hubs serve as compliance gateways to EU retail channels for edge banding distributors. Polish furniture assemblers maintain dual-source strategies for PVC and ABS grades contingent on destination market regulations. Poznań and Wrocław production zones concentrate procurement scale for German-engineered edge processing equipment.
Edge Banding Materials Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium specification tiers consolidating around REACH-registered compounders while commodity volumes fragment across regional extrusion specialists. Market structure reflects a three-tier hierarchy: integrated polymer compounders controlling raw material quality, dedicated edge banding extruders with color-matching capabilities, and downstream distributors bundling certification services. Dominant competitive moves include backward integration into polymer compounding operations and geographic expansion through distributor partnerships in underpenetrated manufacturing clusters.
Within the European coating technology tier, SURTECO GmbH exemplifies premium positioning through specialized laminate capabilities, while REHAU Ltd. anchors competitiveness via integrated polymer operations. Among Indian domestic suppliers, Veena Polymers occupies a position serving Gujarat and Maharashtra furniture clusters with specialized extrusion capabilities. These three entities represent distinct archetypes: European technology-led specialists, integrated polymer compounders, and regional scale-focused fabricators.
| Leading Market Players |
|---|
| Vaibhav Industries |
| E3 Panels |
| SURTECO GmbH |
| Gdecor Industries India Private Limited |
| EdgeCo Incorporated |
| REHAU Ltd. |
| Veena Polymers |
| Paramount Composites India |
| Squareone Decor |
| Others |
Cost & Logistics Intelligence
Export-oriented furniture assemblers in Poland and Vietnam concentrate procurement scale for specification-grade edge banding, anchoring contract-based pricing that bundles certification documentation with volume commitments. This buyer concentration forces tiered pricing structures across premium REACH-registered formulations, standard PVC grades for domestic markets, and economy polypropylene alternatives.
Pricing Analysis
Volume placements in commodity PVC grades generate thin margins offset by specification premiums on ABS and laser-compatible substrates. Pricing stratifies across premium REACH-registered compounder tiers, standard non-phthalate PVC formulations, and economy polypropylene alternatives driven by certification level and color-matching capability. Cost compression in standard PVC runs through feedstock volatility, while premium tiers maintain pricing power through documented substitution roadmaps. Small carpentry workshops exhibit highest price sensitivity; German kitchen OEMs show lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Base polymer supply rests on Chinese and South Korean petrochemical complexes for PVC resin, German compounders for specialty ABS grades, and Saudi Arabian feedstock for polypropylene. Raw material dependencies include phthalate plasticizers facing REACH restriction, calcium-zinc stabilizer alternatives, and colorant masterbatches for batch consistency. Single-source vulnerability concentrates in East Asian resin production exposed to regional logistics disruptions. Distribution runs through regional distributors bundling certification services in Poland and Vietnam, direct mill relationships for large German assemblers, and fragmented dealer networks serving Indian carpentry clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance burdens are consolidating the edge banding materials market, forcing mid-tier extruders without REACH registration or polymer compounding capabilities toward exit or acquisition.
For Market Incumbents: Acquire specialized color-matching and laser-compatible substrate capabilities to defend against polypropylene substitution in mid-range furniture lines. Secure backward integration into polymer compounding operations controlling raw material quality for ABS formulations. Prioritize certification investment in EPA TSCA Title VI documentation services bundling inventory management for US export channels. For New Entrants and Emerging Players: Begin with pre-glued roll format distribution targeting Indian carpentry workshops in Gujarat and Maharashtra lacking hot-melt equipment. Capture whitespace in Tier-2 city modular kitchen adoption through regional distributor partnerships rather than direct mill competition. Emphasize convenience premium capture over formulation innovation in initial market entry. For Investors and Strategic Acquirers: The window for entry favors compounders with documented non-phthalate stabilizer roadmaps and established REACH registration. Long-term viability hinges on regulatory compliance capacity rather than scale alone. Watch laser fusion adoption rates in Italian and German premium cabinetry as inflection indicator for substrate technology shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REHAU Ltd. exemplifies margin control through captive ABS resin production. |
| REACH Registration and Substitution Roadmap Documentation | German kitchen OEMs now require documented phthalate-free transition plans from suppliers. |
| Laser-Compatible Substrate Development | Italian design studios specify solvent-free bonding systems for premium residential contracts. |
| Pre-Glued Roll Format Expansion | Indian carpentry workshops in Ahmedabad pay convenience premiums lacking adhesive equipment. |
| Regional Distributor Partnership in Export Hubs | Polish assemblers serve as compliance gateways to EU retail channels for compounders. |
Research Approach
Multi-period observation of polymer substitution patterns, regulatory filing timelines, and furniture export volumes anchored the trend analysis, supplemented by interviews with extrusion plant managers, procurement leads at German kitchen OEMs, regulatory affairs directors at compounders, and distribution channel partners in India and Poland. Secondary validation drew from ECHA REACH registration databases, EPA TSCA Title VI compliance filings, Chinese customs trade data for thermoplastic edge banding, and SEC 10-K disclosures from listed furniture manufacturers. Bottom-up volume modeling triangulated against top-down spending estimates from residential construction and furniture manufacturing indices.
Segment-weighting applied material type, application intensity, and end-user sophistication dimensions across the projection horizon, with material chemistry receiving highest weight given regulatory-driven substitution dynamics. CAGRs derived from fitted growth curves incorporating petrochemical feedstock price scenarios and furniture manufacturing cluster expansion rates. Industry-specific inputs included laser fusion equipment installation counts in European cabinetry plants and modular kitchen adoption penetration curves in Indian Tier-2 cities.
Underlying measurement precision varies by segment; PVC volume estimates carry tighter precision than emerging bio-based alternatives where commercial deployment remains limited. Forecasts reflect assumptions on regulatory enforcement timelines and polymer formulation innovation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Silicone Film Market
Specialty Materials
India Collagen Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Elastic Films Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market