
 Surface Technology Market | 2026-2036
Surface Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Technology Market Analytics
Automotive-grade corrosion resistance is unwinding legacy specifications across the surface technology value chain. Saint-Gobain leverages its ceramics expertise to dominate thermal barrier coatings for aerospace turbines. Bodycote plc anchors its position through captive heat-treatment networks in industrial clusters. Nordson Corporation specializes in precision dispensing equipment that controls film-thickness uniformity for electronics manufacturers.
Surface technology encompasses controlled modification of substrate properties through deposition, removal, or transformation processes, typically achieving thickness precision from nanometers to millimeters depending on the technique employed. Plasma coating achieves bond strengths exceeding 70 MPa for turbine blade thermal protection, while electroplating delivers controlled chromium layers for wear resistance in hydraulic cylinders. Coatings command the largest value pool due to recurring maintenance cycles in heavy industry, yet vapor deposition is expanding fastest as semiconductor fabs demand atomic-layer precision for interconnect metallization. Medical applications concentrate margin in biocompatible ceramic films, where regulatory certification creates durable supplier lock-in.
EPA emission standards for hexavalent chromium plating shape process chemistry investments across US manufacturing regions. REACH restrictions on perfluorinated compounds in Europe are redirecting R&D toward fluorine-free pretreatment systems. China's MEE enforces wastewater discharge limits that favor closed-loop electroplating operations over conventional open-bath configurations. Stakeholders must weigh capital allocation between incremental coating efficiency and transformative dry-process technologies as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Automotive electrification is rewiring surface technology specifications as OEMs abandon legacy corrosion standards designed for internal combustion architectures. Tier-1 suppliers must recertify coating systems for aluminum battery housings and copper busbars that carry high-voltage loads.
Growth Catalysts
- REACH Phase-Out Schedules:ECHA restrictions on hexavalent chromium and cadmium are forcing coating houses to qualify trivalent alternatives and thin-film ceramics, opening specification windows for qualified suppliers.
- Turbine Blade Refurbishment Cycles:Aerospace MRO demand for thermal barrier coating reapplication is accelerating as global fleet operating hours recover and engine OEMs extend maintenance intervals.
- Semiconductor Interconnect Scaling:Atomic layer deposition is displacing conventional sputtering for copper barrier-seed layers below 7nm nodes, pulling equipment and precursor chemistry demand.
Market Restraints
- Precious Metal Volatility:Palladium and rhodium price swings in electroplating baths compress job-shop margins and deter long-term contracting with automotive OEMs.
- Specialty Gas Concentration:Supply of high-purity silane and tungsten hexafluoride for CVD processes concentrates among three global producers, creating input vulnerability for domestic deposition facilities.
- Technical Limitation in Thick-Film Ceramics:Plasma-sprayed thermal barrier coatings above 500 microns suffer spallation under thermal cycling, capping performance gains for next-generation turbine inlet temperatures.
Strategic Opportunities
- India Industrial Corridors:PLI scheme incentives for specialty steel and automotive component manufacturing are creating first-mover advantage for coating service providers establishing captive facilities in Tamil Nadu and Gujarat.
- Solid-State Battery Interfaces:Sulfide electrolyte compatibility demands novel ceramic-polymer hybrid coatings that prevent lithium dendrite penetration, an unsolved materials stack.
- Fluorine-Free Pretreatment Mandates:EU F-Gas Regulation and national bans on PFAS are redirecting R&D budgets toward zirconium-based conversion coatings and silane adhesion promoters.
Industry Challenges
- Plasma Physics Expertise Scarcity:Operating high-enthalpy spray torches and PECVD reactors requires rare combinations of materials science and vacuum engineering training that outpaces vocational pipeline output.
- Multi-Site Certification Burden:Nadcap accreditation for aerospace coating and NADCAP heat treatment demands synchronized audits across distributed facility networks, stretching quality management bandwidth.
- Legacy ERP Integration:Job shops running decades-old production scheduling systems face friction deploying IoT-enabled thickness monitoring and predictive maintenance analytics without wholesale replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Technology Market |
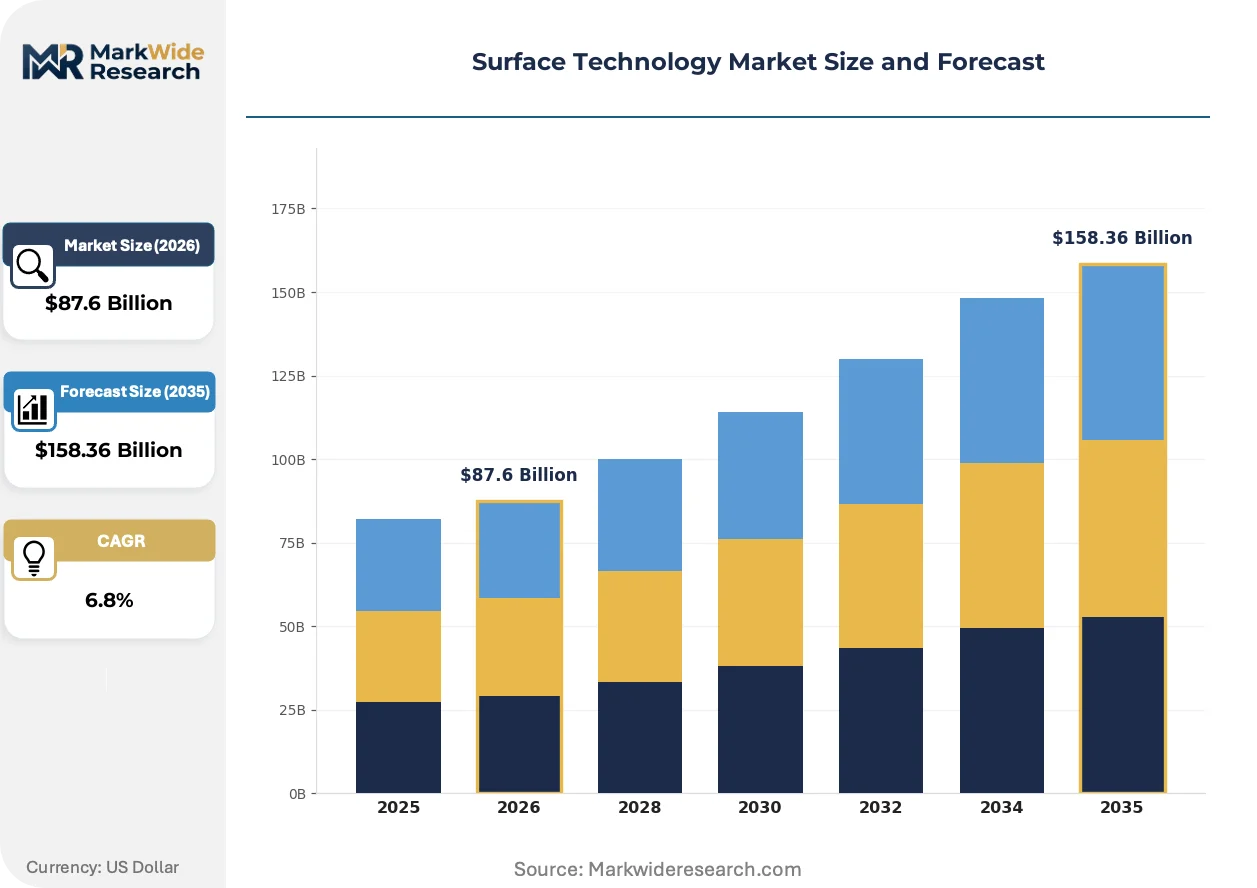
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Treatments, Films, Inks Material: Metals, Polymers, Composites, Ceramics Application: Aerospace, Automotive, Electronics, Medical Technology: Laser Processing, Plasma Coating, Electroplating, Vapor Deposition |
| Companies Covered | ASM Pacific Technology, Saint-Gobain, Bodycote plc, Nordson Corporation, Linde plc, Dürr AG, Aalberts Surface Technology, APS Materials Inc., OC Oerlikon Balzers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Technology Market Evolving Landscape
Process electrification and closed-loop chemistry recovery are compressing the environmental footprint of surface modification while tightening thickness precision tolerances. Equipment suppliers are embedding real-time spectroscopic monitoring to eliminate batch-to-batch variation.
Atomic layer deposition is miniaturizing interconnect metallization for sub-5nm logic nodes. Leading foundries in Taiwan and South Korea are qualifying ALD tungsten and ruthenium fill processes for backside power delivery networks. This precision shift is compressing sputtering equipment demand while expanding precursor chemical and chamber design specialization.
EPA effluent limitation guidelines for metal finishing operations are mandating zero liquid discharge configurations for new plating facilities in the Great Lakes manufacturing corridor. Shops are retrofitting vacuum evaporators and membrane filtration to recover nickel and copper salts. Job shops in Michigan and Ohio face capital decisions between compliance upgrades and facility relocation.
Automotive OEMs are unbundling coating specifications from component supply contracts, creating direct procurement relationships with surface technology specialists. Tier-1 stamped metal suppliers in Germany's automotive cluster now compete for specification authority against captive coating houses. This disintermediation concentrates technical accountability with OEM material engineering teams while fragmenting volume across qualified job-shop networks.
Surface Technology Market Segmentation
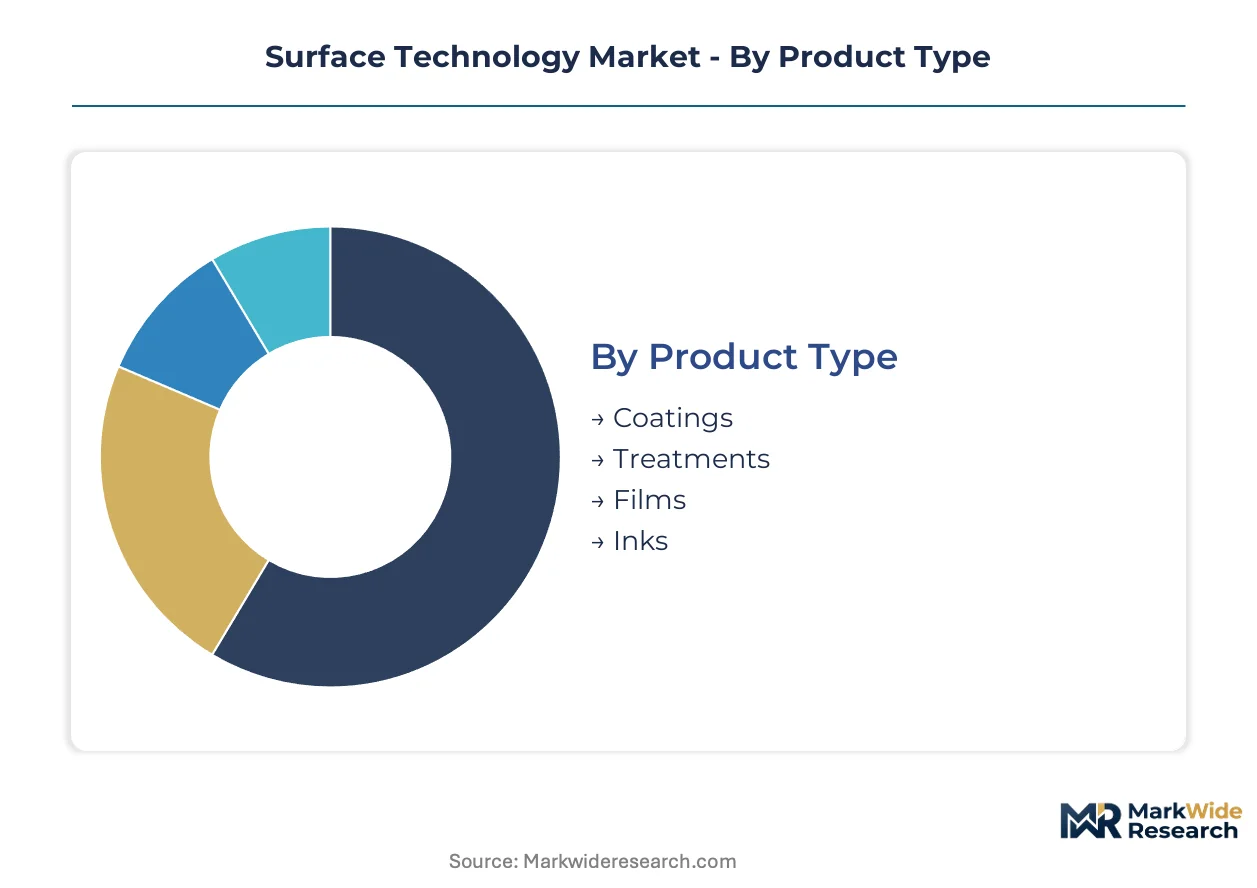
Surface technology procurement channels diverge sharply by segment maturity. Coatings and electroplating flow through established job-shop networks, while vapor deposition and laser processing concentrate in captive semiconductor and aerospace facilities. Understanding these channel dynamics reveals where specification authority and margin capture shift across the value chain.
Product Type:
Channel concentration varies by maintenance cycle intensity and specification complexity. Recurring industrial demand favors distributed service networks, while precision electronics applications lock into integrated manufacturing lines.
- Coatings:Thermal barrier, anti-corrosion, and wear-resistant layers dominate recurring maintenance spend in heavy industry. Demand concentrates in Germany's industrial corridor and US Great Lakes manufacturing regions, where EPA effluent guidelines now mandate zero liquid discharge configurations for new facilities.
- Films:Atomic-layer precision films for semiconductor interconnects achieve thickness control below 5nm. Taiwan and South Korea foundries are qualifying ALD tungsten and ruthenium processes for backside power delivery networks, pulling precursor chemistry and chamber design specialization.
- Treatments:Heat treatment and surface hardening services anchor captive networks in industrial clusters. Bodycote plc maintains position through distributed facility accreditation.
- Inks:Conductive and dielectric formulations for printed electronics and automotive sensors. Functional inkjet deposition is displacing screen printing for flexible circuit prototypes.
By volume, Coatings leads. By growth pace, Films is ahead.
Material:
Cost tier stratification separates commodity metal finishing from premium ceramic and composite applications. Price per square meter spans two orders of magnitude from standard zinc plating to medical-grade hydroxyapatite coatings.
- Metals:Nickel, chromium, and precious metal electrodeposits remain volume leaders despite REACH phase-out pressures. ECHA restrictions on hexavalent chromium and cadmium are forcing qualification of trivalent alternatives and thin-film ceramics.
- Ceramics:Thermal barrier coatings for turbine blades achieve bond strengths exceeding 70 MPa through plasma spray processes. Saint-Gobain leverages ceramics expertise for aerospace turbine applications.
- Polymers:Fluoropolymer and PVD polymer films for corrosion protection and release surfaces. EU F-Gas Regulation and national PFAS bans are redirecting R&D toward fluorine-free alternatives.
- Composites:Ceramic-polymer hybrid stacks for solid-state battery interfaces. Sulfide electrolyte compatibility demands novel coatings preventing lithium dendrite penetration.
By revenue scale, Metals dominates. By margin expansion, Ceramics is climbing the fastest.
Application:
Customer type fragmentation splits the market between specification-driven OEMs and price-sensitive maintenance operators. Aerospace and medical concentrate margin in certified supplier relationships, while automotive maintenance competes on throughput.
- Aerospace:Thermal barrier coating reapplication cycles accelerate with global fleet operating hour recovery. MRO demand concentrates specification authority with engine OEM material engineering teams.
- Automotive:Electrification is rewiring surface specifications as OEMs abandon legacy corrosion standards. Tier-1 suppliers must recertify coating systems for aluminum battery housings and copper busbars.
- Electronics:Interconnect scaling below 7nm nodes displaces sputtering with atomic layer deposition. Precursor chemistry and chamber design specialization is expanding.
- Medical:Biocompatible ceramic films for implants concentrate margin where regulatory certification creates durable supplier lock-in. Hydroxyapatite and titanium nitride coatings command premium pricing.
By installed base, Automotive leads. By specification intensity, Medical is gaining share fastest.
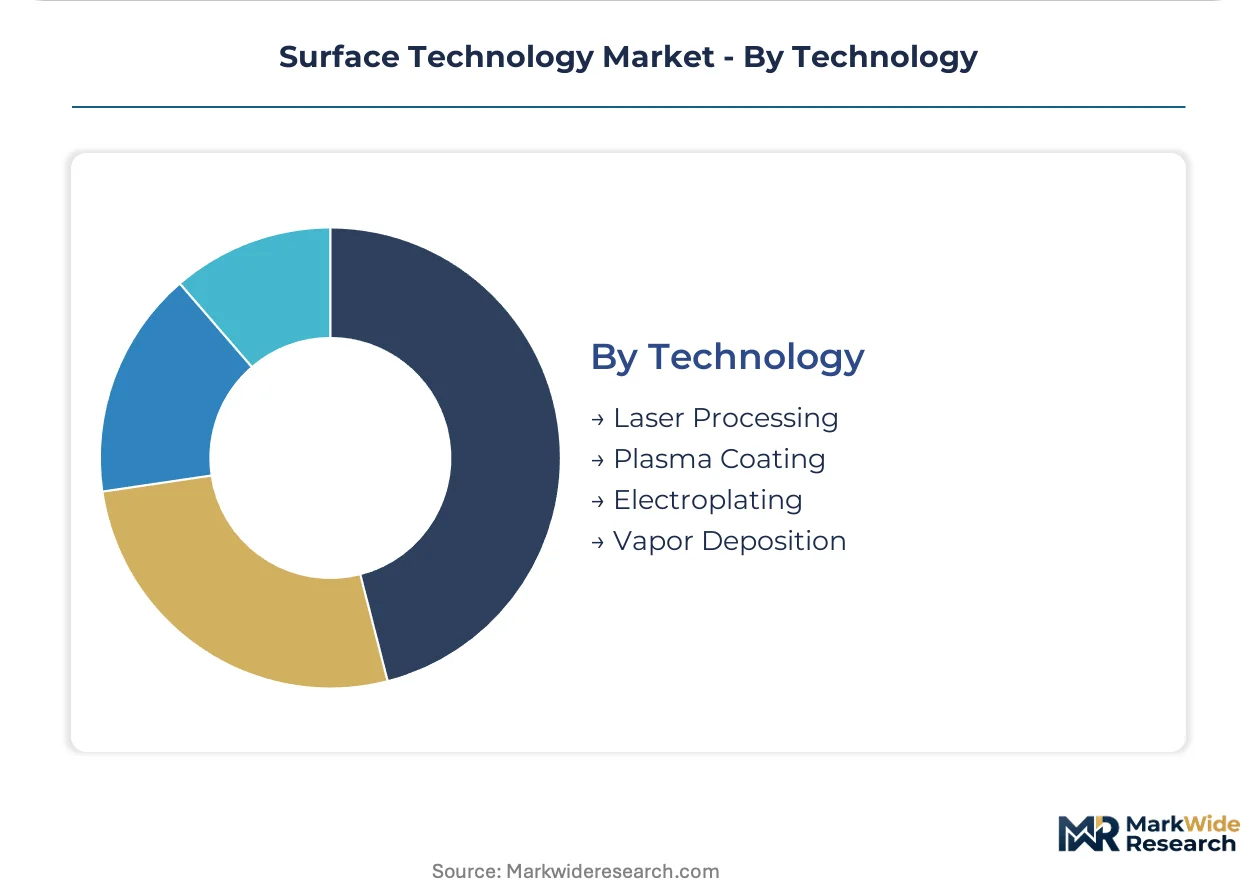
Technology:
Supply concentration in specialty gases and plasma physics expertise creates asymmetric capability distribution. High-enthalpy processes and vacuum systems require rare combinations of materials science and engineering training.
- Vapor Deposition:CVD and ALD processes achieve atomic-layer precision for semiconductor interconnects. High-purity silane and tungsten hexafluoride supply concentrates among three global producers.
- Plasma Coating:Atmospheric and vacuum plasma spray deposit thick ceramic layers for turbine protection. Physics expertise scarcity constrains operational capacity expansion.
- Electroplating:Conventional wet chemistry processes face regulatory compression from REACH and EPA effluent guidelines. Closed-loop operations recover nickel and copper salts.
- Laser Processing:Surface texturing and cladding for wear resistance and adhesion promotion. Fiber laser cost reductions are expanding job-shop adoption.
By process volume, Electroplating leads. By capability scarcity premium, Vapor Deposition shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma physics expertise and specialty gas supply concentrate in Germany, the United States, and East Asian manufacturing hubs. These centers anchor specification-grade coating services for aerospace turbines and semiconductor interconnects. Regulatory divergence across REACH, EPA, and China's GB standards fragments process chemistry investments.
United States
Aerospace MRO demand for thermal barrier coating reapplication accelerates as commercial fleet operating hours recover post-pandemic. EPA effluent limitation guidelines mandate zero liquid discharge configurations for new plating facilities in the Great Lakes manufacturing corridor. Shops in Michigan and Ohio retrofit vacuum evaporators to recover nickel and copper salts.
Germany
Automotive OEMs unbundle coating specifications from component supply contracts, concentrating technical accountability with material engineering teams. REACH restrictions on hexavalent chromium and cadmium force qualification of trivalent alternatives. The industrial corridor around Stuttgart and Munich hosts captive heat-treatment networks serving Tier-1 stamped metal suppliers.
China
Semiconductor foundries qualify atomic layer deposition processes for sub-7nm copper barrier-seed layers. MEE enforces wastewater discharge limits favoring closed-loop electroplating operations over open-bath configurations. The Yangtze River Delta concentrates vapor deposition equipment demand from logic and memory fabs.
South Korea
Leading foundries qualify ALD tungsten and ruthenium fill processes for backside power delivery networks. The country's national semiconductor regulator coordinates precursor chemistry import approvals with domestic chamber design specialization. Seoul Capital Area facilities pull high-purity silane and tungsten hexafluoride supply.
India
PLI scheme incentives for specialty steel and automotive component manufacturing create first-mover advantage for coating service providers. BIS certification requirements for industrial surface treatments tighten specification windows. Tamil Nadu and Gujarat industrial corridors attract captive facility investments from precision coating specialists.
Surface Technology Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the surface technology value chain. Ceramic specialists and precision equipment manufacturers command specification premiums in aerospace and electronics applications, while job-shop networks compete on throughput in automotive maintenance. Three archetypes dominate: materials science innovators with captive R&D, distributed service networks with multi-site accreditation, and equipment suppliers embedding process control software. M&A activity concentrates in heat-treatment network consolidation, while strategic partnerships link precursor chemistry suppliers to deposition equipment OEMs.
Among diversified materials specialists, Saint-Gobain and Linde plc exemplify technology leadership through ceramics expertise and industrial gas supply integration respectively. Bodycote plc occupies a position within the distributed service archetype, anchoring captive heat-treatment networks through facility accreditation scale. ASM Pacific Technology represents the precision equipment tier, sitting within semiconductor capital equipment supply chains. These three players illustrate how capability scarcity in plasma physics and vacuum engineering creates defensive positioning against commodity competition.
| Leading Market Players |
|---|
| ASM Pacific Technology |
| Saint-Gobain |
| Bodycote plc |
| Nordson Corporation |
| Linde plc |
| Dürr AG |
| Aalberts Surface Technology |
| APS Materials Inc. |
| OC Oerlikon Balzers |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German precision coating clusters shapes both supply concentration and price floors for specification-grade thermal barrier services. REACH compliance costs and captive heat-treatment investments create structural barriers that protect incumbent margins while compressing job-shop pricing power in commoditized electroplating segments.
Pricing Analysis
EPA effluent limitation guidelines dictate the pricing tier structure across US metal finishing operations. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-accredited aerospace specialists from automotive maintenance job shops and commodity zinc platers. Cost compression in standard-tier electroplating intensifies because precious metal volatility in palladium and rhodium baths squeezes contract margins. Automotive OEM procurement teams show highest price sensitivity, while medical device manufacturers accept premium pricing for biocompatible ceramic certification.
Supply Chain Analysis
Germany and the United States anchor specification-grade coating services for aerospace turbines and precision heat treatment. High-purity silane and tungsten hexafluoride for CVD processes draw from a concentrated base of three global producers. Single-source vulnerability in specialty gas supply threatens deposition facility operations. Distribution runs through captive networks for semiconductor and aerospace applications, while job-shop networks handle recurring industrial maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface technology sits in early-cycle expansion as automotive electrification forces recertification of coating systems for aluminum battery housings and copper busbars. This specification churn creates windows for qualified suppliers to capture displaced volume from legacy corrosion standards.
For Market Incumbents: Consolidate multi-site accreditation scale to defend against emerging coating specialists targeting Nadcap aerospace demand. Add captive capacity in Tamil Nadu and Gujarat industrial corridors before PLI scheme incentives attract regional competitors. Vertical integration into precursor chemistry supply hedges specialty gas concentration risk.
For New Entrants and Emerging Players: Lead with fluorine-free pretreatment systems as EU F-Gas Regulation and national PFAS bans redirect R&D budgets toward zirconium-based conversion coatings. Target India's industrial corridors where BIS certification requirements tighten specification windows for first movers. Position through direct OEM procurement relationships as automotive manufacturers unbundle coating specifications from Tier-1 contracts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials science innovators with captive plasma physics expertise and distributed service networks with synchronized multi-site quality accreditation. Long-term viability hinges on exposure to semiconductor interconnect scaling and solid-state battery interface development. Watch ALD equipment qualification timelines at Taiwan and South Korea foundries as inflection indicators for precursor chemistry demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Pretreatment Development | EU F-Gas Regulation redirects R&D budgets toward zirconium-based conversion coatings and silane adhesion promoters. |
| Captive Facility Expansion in India | PLI scheme incentives for specialty steel manufacturing create first-mover advantage in Tamil Nadu and Gujarat corridors. |
| Specialty Gas Supply Integration | Backward integration into silane and tungsten hexafluoride supply hedges concentration risk among three global producers. |
| Multi-Site Nadcap Accreditation | Synchronized quality audits across distributed networks stretch competitor bandwidth while locking aerospace specification authority. |
| Solid-State Battery Interface R&D | Ceramic-polymer hybrid coatings for sulfide electrolyte compatibility address unsolved lithium dendrite penetration challenges. |
Research Methodology
A standing panel of coating house operations directors, OEM material engineering leads, aerospace MRO procurement managers, and semiconductor fab process engineers provided ongoing calibration across primary fieldwork and secondary validation. Bottom-up demand modeling drew from EPA effluent filings, ECHA restriction updates, SEC 10-K disclosures from listed service providers, and customs data on precursor chemical trade flows. Top-down market sizing triangulated against industrial production indices and capital equipment shipment records.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated product type, material grade tier, end-use application, and technology process. CAGRs derived from slope analysis of annualized growth trajectories. Forecast inputs included semiconductor node transition timelines, turbine blade refurbishment cycle frequencies, and automotive electrification penetration curves.
Forecasts assume regulatory continuity in EPA effluent guidelines, REACH restriction schedules, and China's MEE wastewater discharge limits; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in precursor chemistry supply availability, foundry equipment qualification announcements, and aerospace fleet operating hour recovery patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Hornbeam Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
India Collagen Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Global PU Films Market