
 Melamine Foam Market | 2026-2036
Melamine Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Melamine Foam Market Outlook
China is narrowing its historical supply gap with new melamine resin capacity coming online in Shandong and Henan provinces. BASF SE leverages its integrated precursor chemistry to sustain cost advantages across European acoustic foam grades. Dow Inc. anchors North American supply through proprietary resin formulation know-how. SINOYQX competes aggressively on standard foam block exports from its Sichuan manufacturing base.
Melamine foam is a thermosetting polymer synthesized from melamine-formaldehyde resin, cured into an open-cell structure with densities typically ranging from 8 to 12 kg per cubic meter and exceptional thermal stability up to 240 degrees Celsius. Its primary industrial purpose centers on high-performance sound absorption, thermal insulation, and abrasive-free cleaning where conventional materials degrade or fail. Acoustic foam commands the dominant margin pool in automotive and architectural applications, while coated foam variants are expanding fastest as OEMs specify multi-functional surfaces combining fire resistance with hydrophobic barriers. Standard foam remains the volume backbone across consumer cleaning and basic insulation end uses, though price compression limits profitability at commodity grades.
REACH registration requirements administered by ECHA constrain formaldehyde residual levels in foam destined for European consumer goods and healthcare segments. China's SAMR enforces GB standards on melamine resin content in food-contact cleaning applications, directly shaping export eligibility for domestic producers. The US EPA and OSHA jointly influence workplace exposure limits during foam fabrication, affecting domestic manufacturing economics. Stakeholders must monitor regulatory divergence between these jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Automotive OEMs in Germany, Japan, and the US are consolidating NVH foam specifications around lighter-weight open-cell structures, compressing legacy polyurethane substitution timelines and forcing resin suppliers to recalibrate formulation chemistry.
Growth Catalysts
- REACH formaldehyde residual limits:ECHA's tightening thresholds for consumer goods and healthcare segments are filtering out marginal European producers, concentrating volume among qualified resin compounders.
- Electric vehicle platform expansion:Battery enclosure thermal management and cabin acoustic dampening are absorbing premium melamine foam grades as OEMs eliminate engine masking noise.
- Shandong-Henan capacity corridor:China's domestic resin supply expansion is reducing import dependency and enabling cost-competitive export positioning into Southeast Asian fabrication hubs.
Market Restraints
- Formaldehyde input cost volatility:Methanol-to-formaldehyde pricing swings directly compress melamine resin margins, exposing non-integrated foam producers to margin erosion.
- German automotive supply corridor concentration:Tier-1 acoustic module assembly clusters around Stuttgart and Wolfsburg create geographic demand risk if OEM platform delays occur.
- Polyimide aerogel substitution:Thin-film thermal barrier alternatives are capturing aerospace and premium EV battery applications where space constraints outweigh cost sensitivity.
Strategic Opportunities
- India's BIS certification pathway:Underpenetrated automotive and rail insulation markets await qualified foam suppliers as domestic manufacturing scales under PLI-linked incentives.
- GB standard food-contact cleaning expansion:SAMR's evolving domestic standards for melamine resin content in kitchen applications create export qualification arbitrage for compliant Chinese producers.
- Hydrophobic coating convergence:Fluoropolymer surface treatment integration with open-cell substrates is opening marine and outdoor architectural specifications previously closed to unprotected foam.
Industry Challenges
- Resin formulation chemist scarcity:Specialized expertise in melamine-formaldehyde condensation kinetics is concentrating at incumbent suppliers, constraining new entrant R&D velocity.
- Multi-jurisdiction qualification timelines:Parallel REACH, GB standard, and US EPA workplace exposure certifications stretch product launch cycles and tie up technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melamine Foam Market |
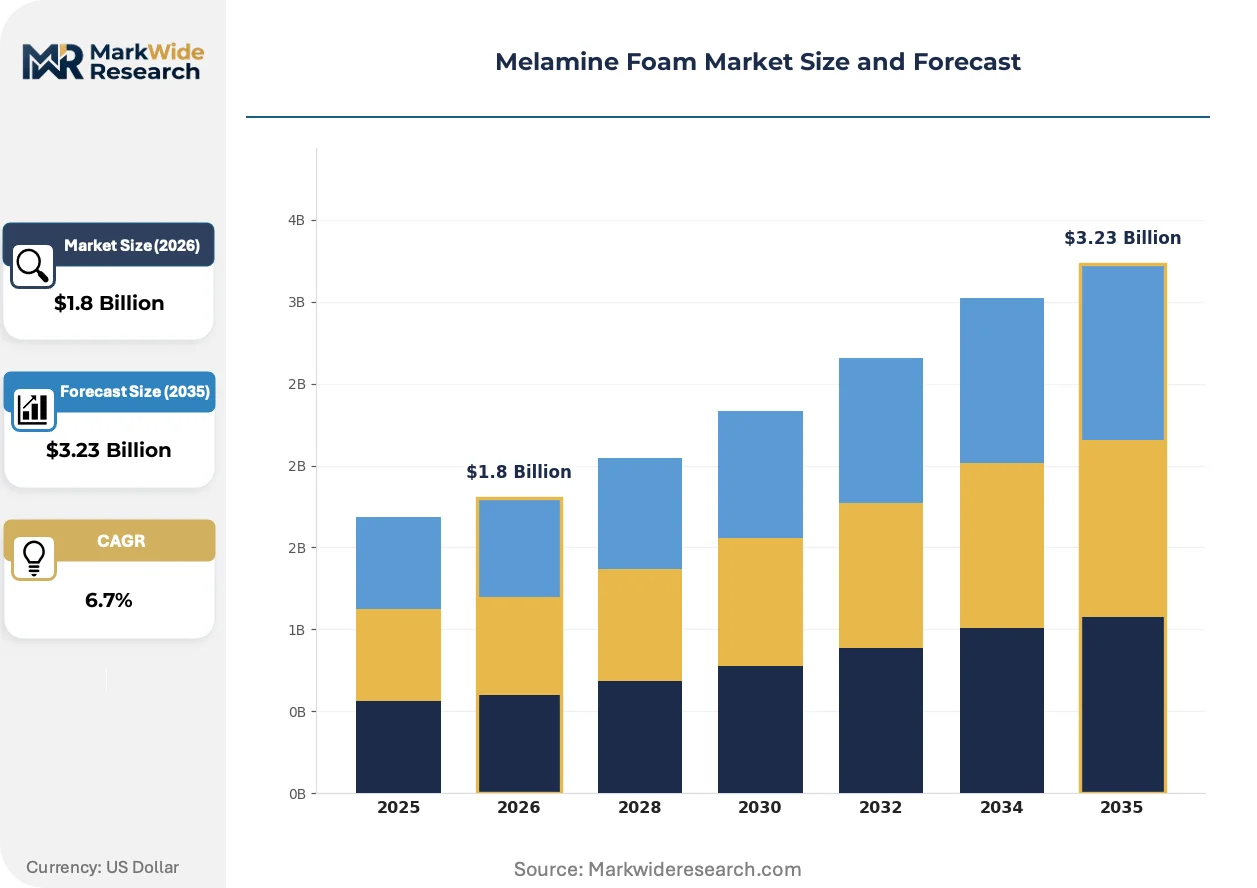
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Foam, Acoustic Foam, Mattress Foam, Coated Foam End User: Automotive, Construction, Healthcare, Consumer Goods Application: Soundproofing, Insulation, Cleaning, Packaging Form: Blocks, Sheets, Rolls, Custom Shapes |
| Companies Covered | Puyang Green Foam, Dow Inc., BASF SE, Armacell International, SABIC, Recticel, Huntsman Corporation, CMS Danskin Acoustics, SINOYQX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melamine Foam Market Strategic Shifts
Specification convergence across automotive, aerospace, and building insulation is compressing the gap between commodity and performance-grade foam, rewarding suppliers with integrated resin-to-block capabilities.
Hybrid melamine-phenolic resin systems are collapsing the thermal performance gap between standard foam and mineral wool in commercial HVAC duct lining. Building contractors in Germany and the Netherlands are specifying these composites for passive house certification projects. The technology is collapsing legacy mineral fiber market share in mid-rise residential mechanical enclosures where installation labor savings outweigh material premiums.
REACH authorization requirements for formaldehyde-based substances are forcing reformulation investments across European foam destined for consumer goods. ECHA's 2023-2024 dossier updates have extended compliance timelines for certain derivatives but tightened residual limits in finished articles. Healthcare and infant product segments are responding by sourcing pre-certified foam blocks from integrated resin producers with in-house analytical capabilities.
Buyer consolidation among automotive Tier-1 suppliers is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Acoustic module integrators in Germany and Michigan are centralizing foam procurement through platform-level agreements, displacing regional spot purchasing. This pattern is most visible in EV platform launches where single-source foam specifications span multiple vehicle programs and geographies.
Melamine Foam Market Segmentation
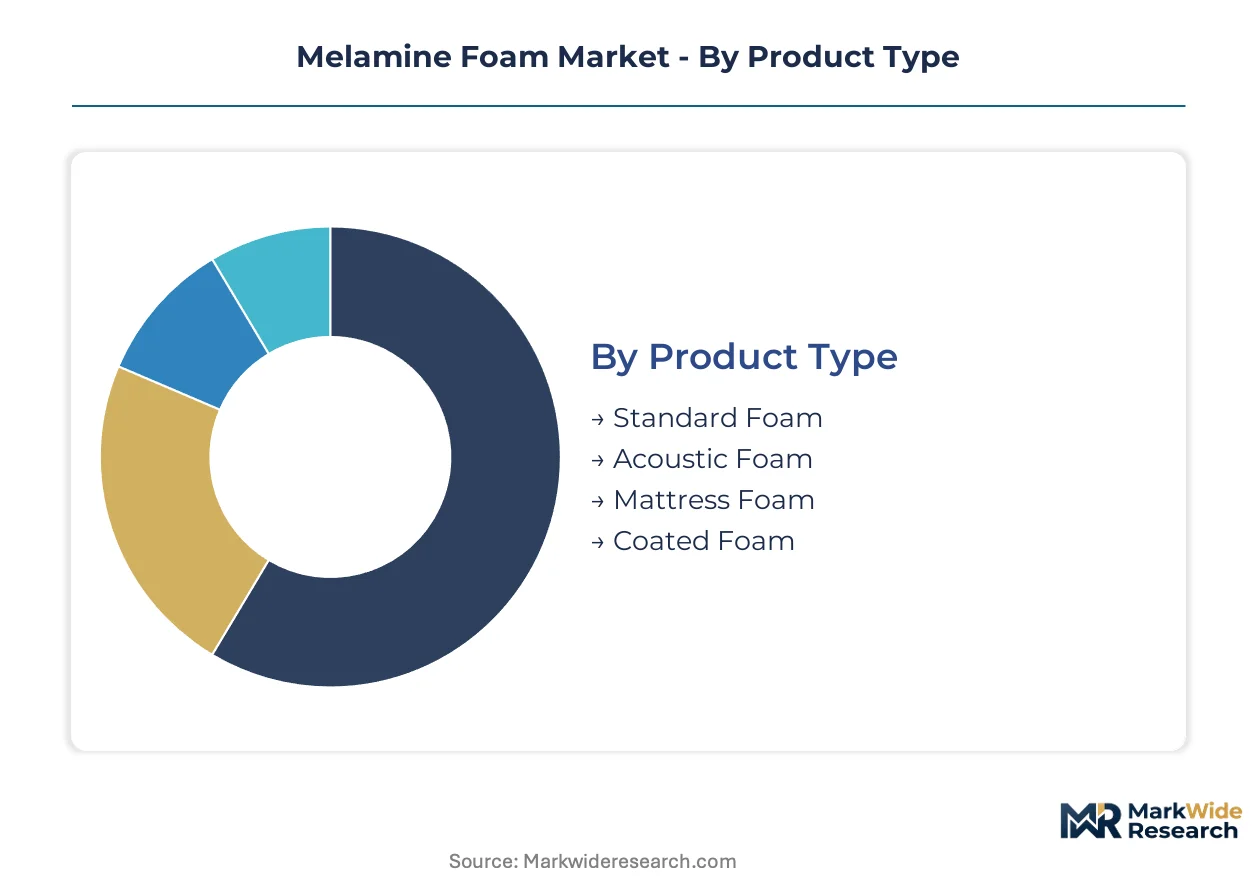
Melamine foam exhibits pronounced specification divergence across product grades, with resin purity and cell structure density determining end-use eligibility. Segmentation discipline separates commodity volume plays from certified performance tiers where formulation chemistry commands measurable price premiums.
Product Type:
Mature acoustic and coated variants anchor margin pools while standard foam occupies the volume-intensive cleaning and basic insulation sectors.
- Standard Foam:Open-cell melamine-formaldehyde resin cured to 8-12 kg/m³ density without surface modification or acoustic optimization. Bulk procurement by consumer cleaning brands and basic HVAC contractors in China and Southeast Asia concentrates demand, though price compression limits supplier profitability at commodity specifications.
- Acoustic Foam:Engineered cell structures with tuned tortuosity for sound absorption coefficients exceeding 0.90 across 500-4000 Hz frequency ranges. German automotive OEMs specify these grades for electric vehicle cabin NVH management as engine masking noise disappears, compressing legacy polyurethane substitution timelines.
- Mattress Foam:Modified resin systems with enhanced compression set resistance and fire-retardant certification for bedding applications. Healthcare and hospitality procurement in Europe and North America drives qualification requirements.
- Coated Foam:Fluoropolymer or silicone surface treatments imparting hydrophobicity, UV stability, or antimicrobial properties to base open-cell substrates. Marine decking and outdoor architectural specifications previously closed to unprotected foam are expanding fastest.
Standard foam retains volume leadership; coated foam holds the steepest expansion curve.
End User:
Cost tier stratification separates specification-heavy automotive and healthcare buyers from price-sensitive construction and consumer segments.
- Automotive:Tier-1 acoustic module integrators in Germany, Japan, and the United States consolidate procurement around platform-level agreements. Battery enclosure thermal management and cabin dampening absorb premium grades as EV architectures proliferate.
- Construction:Commercial HVAC duct lining and passive house certification projects in Germany and the Netherlands specify hybrid melamine-phenolic composites. Installation labor savings versus mineral wool drive adoption in mid-rise residential mechanical enclosures.
- Healthcare:Infant products and medical device cushioning require REACH-certified foam blocks with documented formaldehyde residual compliance. ECHA registration constraints filter supply to integrated resin producers with in-house analytical capabilities.
- Consumer Goods:Kitchen cleaning sponges and abrasive-free scrubbing applications dominate volume. SAMR GB standards on melamine resin content in food-contact applications directly shape Chinese export eligibility.
Automotive commands the premium tier; consumer goods generates the highest shipment volumes.
Application:
Customer type concentration varies sharply, with industrial buyers dominating insulation and soundproofing while retail channels anchor cleaning.
- Soundproofing:Architectural studios, automotive cabins, and rail interiors specify tuned acoustic grades. German OEM platform convergence around single-source foam specifications spans multiple vehicle programs.
- Insulation:Thermal barriers for commercial HVAC, industrial equipment, and EV battery enclosures. Hybrid resin systems are collapsing legacy mineral wool market share in certified building projects.
- Cleaning:Abrasive-free surface scrubbing for electronics, cookware, and transportation interiors. SAMR food-contact standards and REACH residual limits bifurcate export-qualified from domestic-only Chinese supply.
- Packaging:Protective cushioning for precision electronics and temperature-sensitive pharmaceuticals. Niche volume relative to other applications.
Soundproofing captures the specification premium; cleaning remains the volume workhorse.
Form:
Supply concentration in block manufacturing enables downstream fabrication economics, while custom shaping commands project-specific premiums.
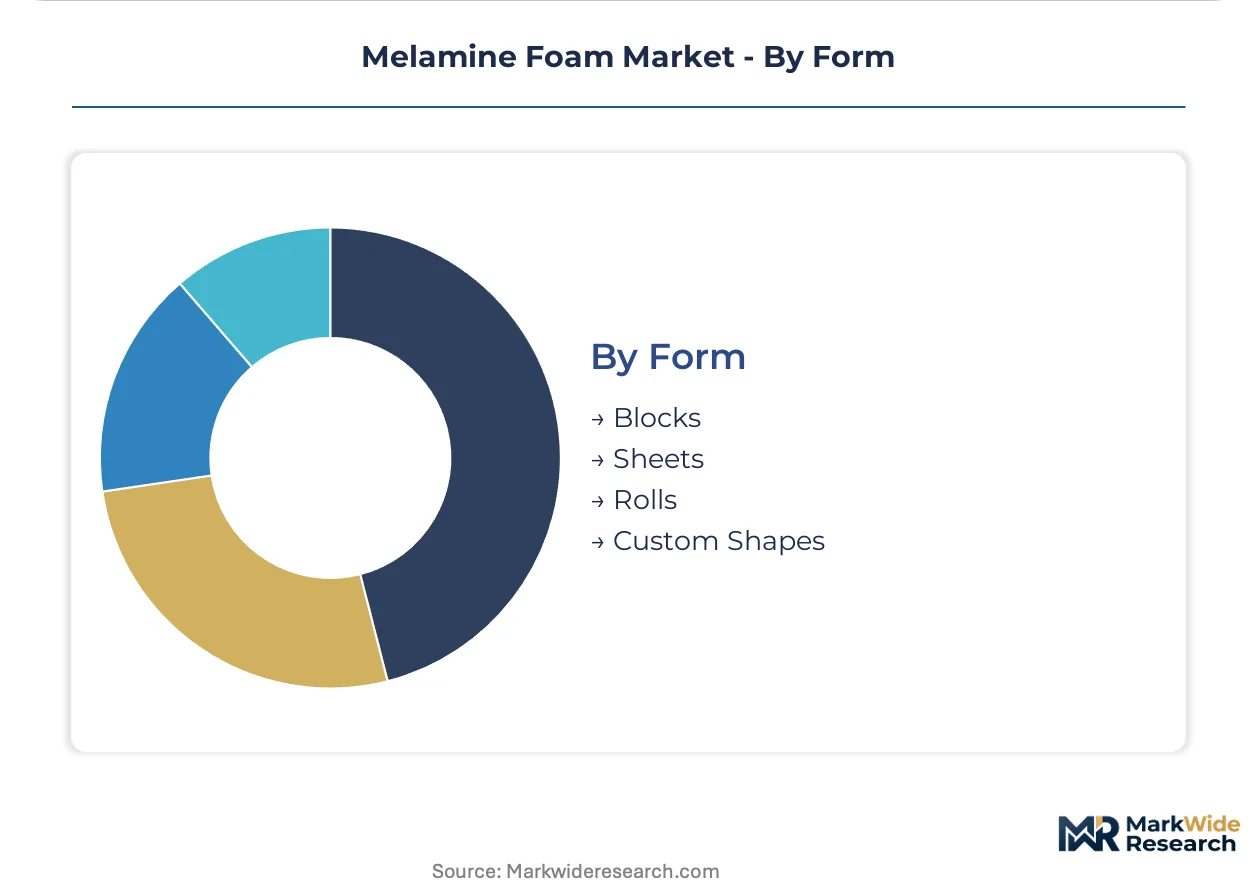
- Blocks:Standardized rectangular billets for secondary cutting and lamination. SINOYQX and Chinese producers compete aggressively on export block supply to Southeast Asian fabrication hubs.
- Sheets:Calibrated thickness panels for acoustic lining and insulation batts. German and Dutch building contractors specify these for passive house mechanical enclosures.
- Rolls:Continuous lengths for industrial wrapping and large-surface HVAC applications. Logistics efficiency favors regional conversion near installation sites.
- Custom Shapes:CNC-machined or die-cut components for automotive modules, medical devices, and aerospace interiors. Qualification timelines stretch product launch cycles across multi-jurisdiction certifications.
Blocks dominate upstream resin economics; custom shapes extract the highest per-kilogram value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH formaldehyde residual thresholds anchor European demand qualification, filtering supply toward integrated resin producers while China's SAMR GB standards reshape export eligibility for kitchen and healthcare applications.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify premium acoustic grades for electric vehicle cabin NVH management as engine masking noise disappears. KBA vehicle type approval requirements cascade into Tier-1 acoustic module specifications, tightening foam qualification protocols. The Baden-Württemberg supply corridor concentrates resin compounding and CNC fabrication capacity for platform-level procurement agreements.
China
Shandong and Henan provinces are bringing new melamine resin capacity online, reducing import dependency and enabling cost-competitive export positioning. SAMR enforces evolving GB standards on melamine resin content in food-contact cleaning applications, directly shaping export eligibility for domestic producers. The Yangtze River Delta fabrication hubs process standard foam blocks for Southeast Asian consumer goods markets.
United States
EPA and OSHA jointly influence workplace exposure limits during foam fabrication, affecting domestic manufacturing economics for acoustic and insulation grades. Electric vehicle battery enclosure thermal management specifications are absorbing premium foam volumes as OEMs eliminate legacy polyurethane alternatives. Michigan-based Tier-1 suppliers centralize procurement through platform-level agreements spanning multiple vehicle programs.
India
BIS certification pathways for automotive and rail insulation markets await qualified foam suppliers as domestic manufacturing scales under PLI-linked incentives. The country's national chemical regulator is aligning food-contact material standards with export market requirements. Maharashtra and Gujarat industrial corridors are emerging as conversion hubs for imported resin blocks.
Japan
METI energy efficiency standards for commercial buildings are specifying hybrid melamine-phenolic composites in HVAC retrofit projects. JIS fire-resistance certification requirements filter supply toward pre-qualified resin producers with documented formaldehyde residual compliance. The Kansai region maintains specialized fabrication capacity for precision electronics packaging applications.
Melamine Foam Market Competitive Environment
Capability concentration sits with integrated resin-to-foam producers; scale advantage sits with high-volume block exporters serving downstream fabrication hubs. The market structures around three tiers: multinational chemical conglomerates with captive precursor supply, regional specialists with certified formulation expertise, and commodity block producers competing on export logistics. Consolidation pressure is accelerating as automotive OEMs reduce qualified supplier lists, while backward integration into melamine resin production represents the dominant defensive maneuver.
Among integrated chemical conglomerates, BASF SE and Dow Inc. exemplify the capability tier through their control of precursor chemistry and European acoustic foam qualification. SINOYQX occupies a position within the scale-driven export segment, leveraging Sichuan-based manufacturing to supply standard foam blocks into Southeast Asian fabrication networks. These three anchors illustrate the bifurcation between specification-heavy automotive supply and commodity consumer goods volume.
| Leading Market Players |
|---|
| Puyang Green Foam |
| Dow Inc. |
| BASF SE |
| Armacell International |
| SABIC |
| Recticel |
| Huntsman Corporation |
| CMS Danskin Acoustics |
| SINOYQX |
| Others |
Value Chain & Pricing Dynamics
Formaldehyde residual compliance thresholds under REACH authorization requirements determine both pricing tier spreads and supply chain shape across European acoustic foam procurement. ECHA's tightening dossier updates filter supply toward integrated resin producers with in-house analytical capabilities, compressing margin pools at commodity grades while amplifying premiums for certified blocks.
Pricing Analysis
German acoustic module specifications command 40-60% premiums over Southeast Asian standard block exports, reflecting KBA vehicle type approval cascades into Tier-1 procurement protocols. Pricing stratifies across REACH-certified premium grades, industrial acoustic tiers, and commodity cleaning block levels, with certification-grade differentiation and volume scale as primary spread drivers. Price erosion runs through standard foam exports from Shandong-Henan corridor producers as resin capacity expansion outpaces qualification velocity. Consumer cleaning brands exhibit highest price sensitivity; German automotive OEMs demonstrate lowest sensitivity due to platform-level single-source specifications.
Supply Chain Analysis
Export control regimes on formaldehyde-based substance precursors constrain resin technology flows into non-integrated foam producers, reinforcing capability concentration. Supply concentrates in Germany for qualified acoustic grades, China for standard block manufacturing, and the United States for battery enclosure thermal management specifications. Raw material dependencies center on melamine crystal, formaldehyde from methanol oxidation, and condensation catalyst systems. Single-source vulnerability pervades European automotive supply corridors around Stuttgart and Wolfsburg. Distribution runs through platform-level agreements for automotive tiers and spot purchasing for consumer cleaning channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification divergence between REACH-certified automotive grades and commodity cleaning blocks fragments competitive space, creating niche opportunities as EV platform proliferation multiplies acoustic qualification pathways.
For Market Incumbents: Harden resin-to-foam integration through captive precursor supply in European supply corridors, defending against polyimide aerogel substitution in premium thermal barrier applications. Deepen analytical certification capabilities to capture healthcare and infant product procurement filtering toward documented formaldehyde residual compliance. Prioritize hybrid melamine-phenolic R&D to collapse mineral wool substitution timelines in passive house certification projects. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification pathway for automotive and rail insulation markets as PLI-linked incentives scale domestic manufacturing. Target hydrophobic coated foam specifications for marine decking and outdoor architectural applications previously closed to unprotected substrates. Lead with fluoropolymer surface treatment partnerships rather than commodity block exports to bypass SINOYQX scale advantages. For Investors and Strategic Acquirers: Regional specialists with certified formulation expertise and documented ECHA registration represent the most defensible acquisition profile for mid-cycle positioning. Long-term viability hinges on backward integration into melamine resin production or forward integration into CNC fabrication capacity adjacent to German OEM clusters. Watch for ECHA dossier updates on formaldehyde derivative authorization timelines as inflection signals for consolidation pressure acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melamine Resin | Captures margin compression from methanol-to-formaldehyde volatility while securing REACH qualification pathways. |
| Hybrid Resin System Development | Collapses mineral wool market share in German passive house certification through melamine-phenolic composites. |
| Fluoropolymer Coating Convergence | Opens marine decking specifications previously closed to unprotected foam via hydrophobic surface treatments. |
| BIS Certification Investment | Positions supply for India's PLI-linked automotive and rail insulation manufacturing scale-up. |
| Platform-Level Procurement Agreements | Locks multi-program EV acoustic specifications spanning German, Japanese, and US OEM architectures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, ACC and Cefic industry reports, SEC 10-K chemical segment disclosures, and ECHA registration dossiers. Primary interviews engaged resin formulation chemists, Tier-1 acoustic module procurement managers, HVAC contractor specification leads, and SAMR regulatory compliance officers. Bottom-up volume triangulation across resin capacity, foam block production, and end-use consumption patterns validates against top-down market sizing from trade flow analysis and OEM platform content assumptions.
Forecast inputs incorporate grade tier segmentation across standard, acoustic, mattress, and coated foam variants; end-use industry splits spanning automotive, construction, healthcare, and consumer goods; and regional production hub clustering around German automotive corridors, Shandong-Henan resin capacity, and Yangtze River Delta fabrication networks. CAGRs derive from elasticity modeling against EV platform penetration rates, REACH compliance cost pass-through coefficients, and substitution dynamics versus polyurethane and mineral wool alternatives.
Sensitivities concentrate around ECHA formaldehyde residual threshold revisions, methanol pricing volatility transmission to resin economics, and polyimide aerogel cost-down curves in aerospace and premium EV battery applications. Forecasts embed assumptions on qualification timeline durations and OEM platform standardization velocity. Material shifts in REACH authorization scope or German automotive production schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Elastic Films Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Light Diffusion Materials Market