
 Butter and Margarine Market | 2026-2036
Butter and Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Butter and Margarine Market Outlook
Asset-light leasing models for cold-chain distribution infrastructure are reshaping competitive entry barriers in emerging markets. Upfield Holdings B.V. leverages its plant-based portfolio to anchor shelf-space negotiations across European retail banners. Bunge Limited sustains cost advantages through backward integration into oilseed crushing and refining. Richardson International Limited competes on grain-origination scale that feeds into its margarine oil inputs.
Butter and margarine comprise water-in-fat emulsions with butterfat content ranging from 80% in traditional butter to 10-90% in blended margarines, produced via churning or scraped-surface crystallization for texture control. Their primary commercial purpose centers on providing fat functionality for flavor delivery, mouthfeel, and shelf stability in prepared foods. Plant-based margarine leads volume growth as bakery and food-processing buyers reformulate for cost and shelf-life advantages, while salted butter dominates premium-margin pools in retail spreading applications. Block formats retain manufacturing-scale efficiency for industrial baking, whereas spreadable tubs capture household convenience premiums.
EFSA nutrition claims regulation, FDA trans-fat labeling requirements, and BIS food safety standards collectively constrain formulation choices and compel reformulation investments across production networks. REACH chemical registration and EU Green Deal sustainability disclosure rules further tighten sourcing transparency for palm and shea oil supply chains. Stakeholders must monitor evolving regulatory thresholds for saturated fat claims and carbon intensity metrics to align product portfolios with compliance timelines and buyer procurement criteria.
Market Dynamics
EFSA trans-fat thresholds and FDA saturated fat disclosure mandates are forcing simultaneous reformulation across legacy butter and plant-based margarine portfolios, compressing R&D timelines while opening premium positioning for clean-label alternatives.
Growth Catalysts
- Bakery chain procurement:Industrial baking operations in India and Vietnam are consolidating supplier relationships around spreadable tub formats with extended shelf stability, driving volume commitments for modified-fat emulsions.
- REACH sustainability disclosure:EU Green Deal supply chain transparency rules are accelerating certified sustainable palm and shea oil sourcing investments, creating compliance-driven demand for traceable ingredient packages.
- Scraped-surface crystallization:Advanced texture-control processing is enabling fat-structured products with butter-like mouthfeel at lower saturated fat content, unlocking reformulation contracts from health-positioned retail banners.
Market Restraints
- Vegetable oil price volatility:Soybean and palm oil input costs fluctuate with Malaysian ringgit-denominated futures and Indonesian export levy adjustments, squeezing margin predictability for bulk margarine manufacturers.
- EFSA nutrition claim restrictions:Tightened thresholds for saturated fat and cholesterol reduction claims limit marketing vocabulary for reformulated spreads, constraining premium pricing justification in European retail.
- Butterfat supply concentration:New Zealand and Australian dairy cooperative networks control over 60% of internationally traded anhydrous milk fat, creating procurement vulnerability for European butter blenders.
Strategic Opportunities
- Urban retail modernization in Indonesia:Cold-chain infrastructure expansion in Jakarta and Surabaya is enabling first-time chilled margarine distribution to modern trade outlets, opening household penetration in a cooking-oil dominant market.
- FSSAI trans-fat reduction mandate:India's phased elimination of industrially produced trans fats by 2025 is creating regulatory tailwind for interesterified fat technology adoption in domestic bakery and confectionery supply chains.
- Direct-to-foodservice platforms:Digital procurement channels are collapsing traditional distributor layers, allowing regional margarine processors to secure institutional baking contracts with transparent pricing and technical service bundling.
Industry Challenges
- Interesterification process engineering:Specialized enzymatic and chemical interesterification expertise remains concentrated among a limited pool of lipid technology specialists, constraining rapid scale-up for trans-fat-free reformulation projects.
- Dual certification complexity:Simultaneous RSPO sustainable palm and ISO 22000 food safety audits impose overlapping documentation and facility validation requirements, extending new product qualification timelines by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butter and Margarine Market |
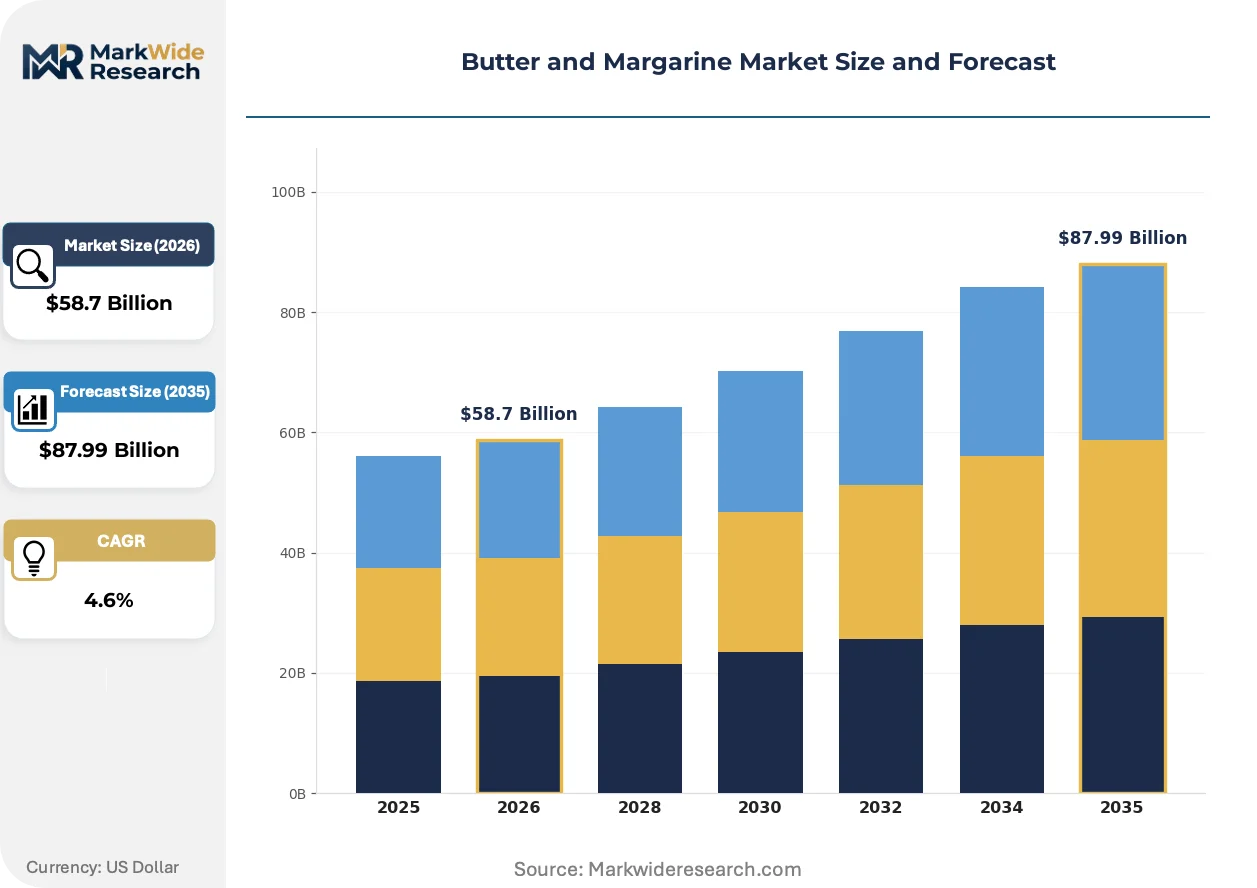
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsalted Butter, Salted Butter, Plant-Based Margarine, Dairy Margarine Application: Baking, Spreading, Cooking, Food Processing Form: Block, Spreadable, Liquid, Stick Packaging Type: Tub, Wrapper, Carton, Pouch |
| Companies Covered | Upfield Holdings B.V., Vandemoortele NV, Bunge Limited, Yildiz Holding A.S., Richardson International Limited, Wilmar International Limited, Associated British Foods PLC, Puratos Group, Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butter and Margarine Market Strategic Shifts
Reformulation priorities are converging on texture-engineered, clean-label alternatives that satisfy both regulatory fat-profile constraints and sensory expectations previously delivered by traditional butterfat.
Enzymatic interesterification of tropical oils is collapsing the functional gap between conventional margarine and butter in laminated pastry applications. Artisan bakery chains in France and artisanal croissant producers in Quebec are adopting these structured fats at accelerated procurement cycles. The technology is collapsing premium pricing power for imported European butter in industrial food manufacturing segments.
EFSA's 2023 updated guidance on nutrition claims for saturated fat reduction has tightened evidentiary requirements for spreadable fat products. Reformulated margarines must now demonstrate measurable metabolic benefit in controlled studies to carry approved health claims. Premium-positioned European retail SKUs are responding with front-of-pack labeling that emphasizes process transparency rather than explicit health assertions.
Bakery procurement departments are consolidating supplier panels around full-service fat system providers who bundle technical formulation support with volume contracts. Traditional commodity margarine distributors are losing shelf access as industrial buyers prioritize R&D partnership depth over price competition. This concentration is most visible in German and Polish baking cooperatives where technical service integration now outweighs spot-market purchasing.
Butter and Margarine Market Segmentation
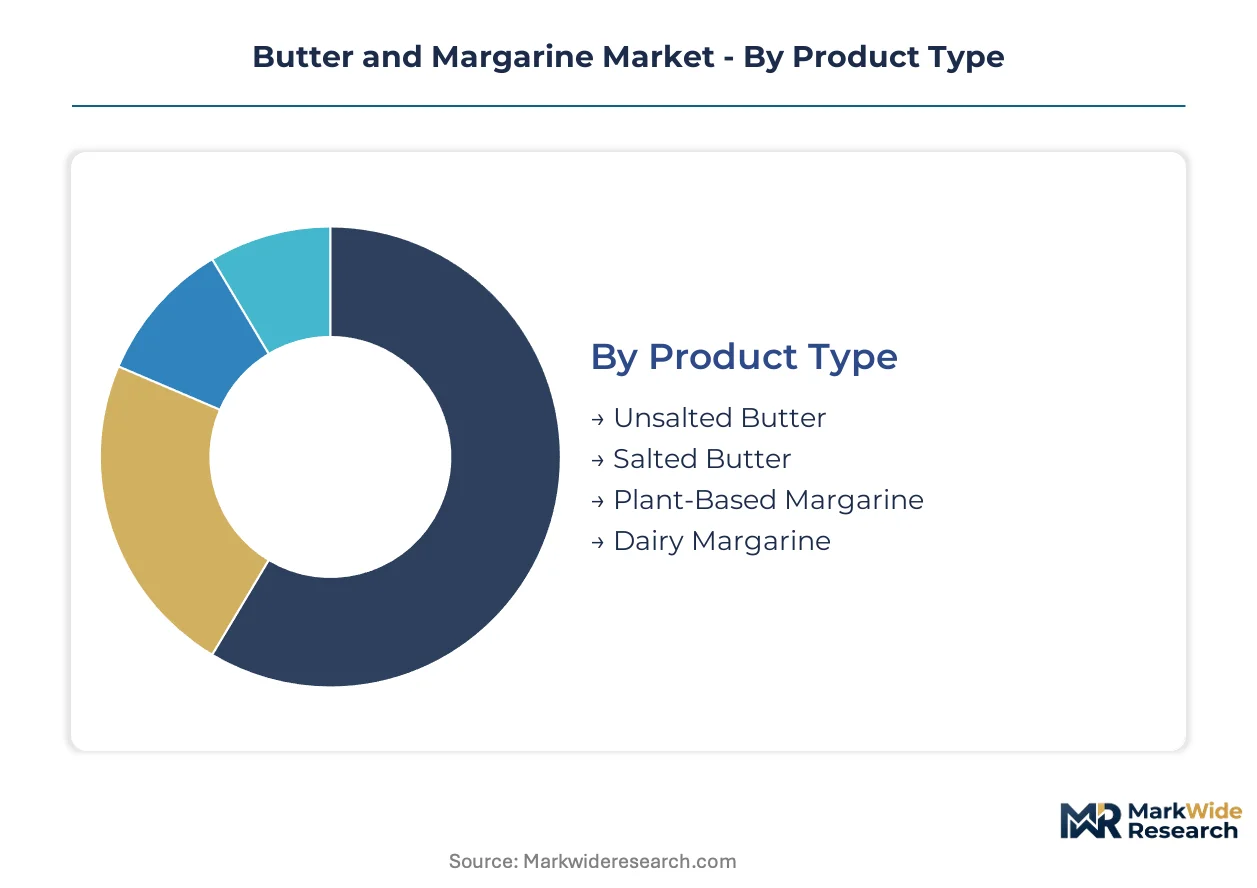
Butter and margarine procurement patterns diverge sharply across product formats, end-use applications, and packaging configurations. Manufacturers configure production assets and cold-chain investments around these segment boundaries to capture margin pools in industrial baking versus retail spreading channels.
Product Type:
Cost tier stratification separates commodity bulk formats from premium-positioned specialty fats in procurement negotiations.
- Plant-Based Margarine:Formulated from interesterified palm, shea, and sunflower oil blends with 10-90% fat content flexibility. Bakery chains in India and Vietnam are consolidating supplier panels around these spreadable formats for extended shelf stability and trans-fat compliance under FSSAI mandates.
- Salted Butter:Traditional churned cream product with 80% butterfat minimum and 1.5-2% salt content for flavor and preservation. European retail banners command premium shelf placement for these SKUs, though EFSA saturated fat claim restrictions constrain health-positioned marketing vocabulary.
- Unsalted Butter:Controlled sodium profile enables precise formulation control for artisan bakeries and confectionery manufacturers requiring predictable fat functionality.
- Dairy Margarine:Hybrid emulsion combining anhydrous milk fat with vegetable oils, targeting butter-like mouthfeel at intermediate price points for foodservice spreading applications.
Salted butter commands the established base. The steepest expansion runs through plant-based margarine.
Application:
Volume concentration tracks the divergence between industrial-scale manufacturing and household consumption occasions.
- Baking:Laminated pastry and industrial bread production demand fat systems with precise plasticity ranges and oxidative stability. German and Polish baking cooperatives are consolidating procurement around full-service providers bundling technical formulation support with volume contracts.
- Spreading:Retail household consumption prioritizes convenience and sensory immediacy. Cold-chain infrastructure expansion in Jakarta and Surabaya is enabling first-time chilled margarine distribution to modern trade outlets in Indonesia's cooking-oil dominant market.
- Cooking:High-heat stability requirements favor clarified butter and specialized margarine formulations for sautéing and frying applications in foodservice channels.
- Food Processing:Extended shelf-life specifications drive interesterified fat adoption for confectionery and prepared meal applications requiring consistent texture across temperature cycles.
Baking commands the established base. The steepest expansion runs through spreading applications.
Form:
Customer type segmentation separates manufacturing efficiency priorities from household convenience premiums.
- Block:Rectangular bulk format optimized for industrial slicing and portion control in high-throughput bakery operations. Block formats retain manufacturing-scale efficiency for institutional procurement with standardized fat incorporation protocols.
- Spreadable:Tub-packaged emulsion with modified crystal structure for immediate spreadability at refrigeration temperatures. Scraped-surface crystallization technology is enabling butter-like mouthfeel at reduced saturated fat content for health-positioned retail banners.
- Liquid:Pumpable oil blend for automated dispensing in industrial food manufacturing and commercial frying operations.
- Stick:Quarter-pound wrapped format balancing portion control with traditional measurement conventions in North American household baking.
Block commands the established base. Spreadable formats are gaining share fastest.
Packaging Type:
Supply concentration patterns reflect cold-chain infrastructure maturity and retail format modernization trajectories.
- Tub:Wide-mouth plastic container with resealable lid dominating retail spreadable segments. Tub packaging captures household convenience premiums while enabling product differentiation through color-coding and label claims.
- Wrapper:Foil or parchment paper enclosure for butter sticks and bakery blocks, minimizing material cost in commodity bulk channels.
- Carton:Paperboard secondary packaging for multi-unit retail presentation and brand billboard visibility in supermarket dairy cases.
- Pouch:Flexible film format for liquid and semi-liquid products in foodservice dispensing systems and industrial bulk delivery.
Wrapper commands the established base. The steepest expansion runs through tub packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major producing and consuming regions. New Zealand and Australia dominate butterfat exports through cooperative networks, while India and Southeast Asia drive import dependency for foodservice and industrial baking expansion.
United States
Domestic butter production from Midwest dairy cooperatives supplies foodservice chains and retail private-label programs. FDA trans-fat labeling requirements and saturated fat disclosure mandates compress formulation timelines for reformulated spreads. Chicago and Minneapolis-St. Paul anchor industrial procurement concentration for bakery and confectionery manufacturing.
Germany
EFSA nutrition claim restrictions constrain premium pricing justification for reformulated margarines in European retail. REACH sustainability disclosure rules and EU Green Deal supply chain transparency requirements accelerate certified sustainable palm oil sourcing investments. Bavaria and North Rhine-Westphalia host baking cooperatives consolidating supplier panels around full-service fat system providers.
India
FSSAI trans-fat reduction mandates create regulatory tailwind for interesterified fat technology adoption in domestic bakery supply chains. Urban retail modernization accelerates cold-chain infrastructure expansion in Mumbai, Delhi-NCR, and Bangalore. Modern trade outlets in these metros enable first-time chilled margarine distribution beyond traditional cooking-oil dominant markets.
Indonesia
Cold-chain infrastructure expansion in Jakarta and Surabaya unlocks household penetration for spreadable tub formats in a historically cooking-oil dominant market. BIS food safety standards and import regulations shape formulation compliance for multinational entrants. Java-based food processing clusters drive institutional procurement of modified-fat emulsions for bakery and confectionery applications.
Brazil
Domestic soybean crushing capacity supports cost-competitive vegetable oil inputs for bulk margarine manufacturing. ANVISA food safety regulations align with international standards for trans-fat labeling and nutritional claims. São Paulo and Rio Grande do Sul concentrate industrial baking operations consolidating around spreadable formats with extended shelf stability.
Butter and Margarine Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on oilseed crushing and tropical oil origination. The vendor base stratifies between multinational portfolio holders with backward integration into oilseed processing and regional formulators competing on technical service bundling. Three archetypes dominate: grain-origination scale players, plant-based portfolio specialists, and full-service fat system providers integrating formulation support with volume contracts. Competitive moves concentrate on M&A for tropical oil supply security and capacity expansion in enzymatic interesterification technology.
Among the integrated oilseed processors, Bunge Limited exemplifies backward integration advantages through captive crushing and refining assets. Upfield Holdings B.V. occupies a position anchoring shelf-space negotiations through plant-based portfolio breadth. Richardson International Limited represents grain-origination scale that feeds into margarine oil input supply chains.
| Leading Market Players |
|---|
| Upfield Holdings B.V. |
| Vandemoortele NV |
| Bunge Limited |
| Yildiz Holding A.S. |
| Richardson International Limited |
| Wilmar International Limited |
| Associated British Foods PLC |
| Puratos Group |
| Conagra Brands, Inc. |
| Others |
Value Chain & Pricing Dynamics
Vegetable oil price volatility determines both margin compression across bulk margarine tiers and the geographic concentration of crushing assets. Malaysian ringgit-denominated palm oil futures and Indonesian export levy adjustments feed directly into formulation cost spreads, compressing pricing power for non-integrated processors while rewarding backward-integrated oilseed networks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the butter and margarine market. Price differentiation rests on certification grade (RSPO sustainable palm, ISO 22000 food safety) and volume scale, with bakery cooperatives commanding lowest unit costs through consolidated procurement panels. Cost compression in economy bulk margarine is intensifying because soybean and palm oil input costs fluctuate with currency and levy volatility. Foodservice distributors exhibit highest price sensitivity due to thin operating margins, while European retail banners accept premium positioning for clean-label reformulations with butter-like mouthfeel.
Supply Chain Analysis
Contract-manufacturing concentration for enzymatic interesterification capacity sits with a limited pool of lipid technology specialists in Germany, the Netherlands, and Singapore. Raw material dependencies draw from Malaysian and Indonesian palm oil networks, New Zealand and Australian anhydrous milk fat cooperatives, and Ukrainian sunflower oil corridors. Single-source vulnerability concentrates in butterfat supply, where Oceania dairy cooperatives control over 60% of internationally traded volumes. Distribution runs through cold-chain infrastructure layers that remain underdeveloped in Southeast Asian urban markets, creating last-mile bottlenecks for chilled spreadable formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling represents the fastest-expanding recurring-revenue layer, outpacing commodity fat sales as bakery procurement departments prioritize R&D partnership depth over spot-market purchasing.
For Market Incumbents: Harden shelf-space negotiations through plant-based portfolio breadth that anchors European retail banner access. Deepen backward integration into oilseed crushing and refining to offset vegetable oil price volatility. Invest in enzymatic interesterification capacity additions in Southeast Asia to capture FSSAI trans-fat compliance demand from Indian bakery chains.
For New Entrants and Emerging Players: Cold-chain infrastructure gaps in Jakarta and Surabaya represent the most penetrable entry point for first-time chilled margarine distribution in Indonesia's cooking-oil dominant market. Direct-to-foodservice digital procurement channels in Vietnam and Poland offer collapsed distributor layers with transparent pricing. Lead with technical formulation support bundled with volume contracts to displace traditional commodity margarine distributors.
For Investors and Strategic Acquirers: India's phased elimination of industrially produced trans fats by 2025 reshapes the acquisition landscape toward interesterified fat technology specialists. Long-term viability centers on compliance-driven reformulation capability across emerging market regulatory trajectories. Target acquisition candidates with dual RSPO and ISO 22000 certification infrastructure. Monitor FSSAI enforcement intensity and EFSA saturated fat claim threshold adjustments as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Expansion | Enables trans-fat-free reformulation for FSSAI compliance in Indian bakery supply chains. |
| RSPO Sustainable Palm Certification Investment | Unlocks EU Green Deal procurement criteria for European retail banner shelf access. |
| Cold-Chain Infrastructure Partnership | Supports first-time chilled margarine distribution in Jakarta and Surabaya modern trade. |
| Direct-to-Foodservice Digital Platform Launch | Collapses distributor layers for transparent pricing in Vietnamese industrial baking procurement. |
| Technical Service Integration | Bundles formulation support with volume contracts to displace commodity distributors in German cooperatives. |
Study Parameters
Cross-validation between primary interviews with lipid technology specialists, bakery procurement directors, and foodservice distribution operators anchors the qualitative findings against secondary validation from FSSAI regulatory filings, EFSA nutrition claim guidance documents, and Malaysian Palm Oil Board trade statistics. Bottom-up volume modeling triangulates with top-down value assessments across product format, application, and packaging segmentation dimensions.
Calibration against historical price series for palm oil futures and anhydrous milk fat spot markets informs the analytical framework across the projection horizon. Segmentation modeling incorporates product type stratification, end-use application divergence, form factor preferences, and packaging configuration requirements. CAGRs derive from regression analysis of volume commitments and pricing elasticity patterns, with input sensitivity to vegetable oil cost volatility and regulatory compliance timeline shifts.
Macroeconomic conditions sit as an overlay; deviation in emerging market currency stability, dairy cooperative export pricing power, or Southeast Asian cold-chain investment flows would shift the trajectory. Forecasts reflect documented assumptions regarding FSSAI enforcement pace and EFSA claim threshold evolution. Quarterly review of Malaysian ringgit-denominated futures, Indonesian export levy adjustments, and RSPO certification uptake rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Sheep Milk Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Dairy Spreads Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Ghee Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Goat Milk Products Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Condensed Whey Market
Dairy Products
Organic Milk Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Malted Milk Powder Market