
 Colombia Dairy Market | 2026-2036
Colombia Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Dairy Market Intelligence
Food service buyers are unwinding share as household consumers deepen at-home dairy consumption across Colombian cities. Colanta leverages its cooperative federation model to sustain shelf presence in Andean departments. Alquería anchors Bogotá supply through backward integration into raw milk collection networks. Alpina Productos Alimenticios differentiates via fermented product specialization that commands loyalty in urban households.
Colombia dairy encompasses fluid milk, fermented products, and fat derivatives processed through pasteurization, ultra-high temperature treatment, or enzymatic coagulation, with protein content and somatic cell counts serving as critical quality benchmarks for industrial buyers and retail compliance. The product type dimension shows milk occupying volume leadership while yogurt captures margin expansion through probiotic positioning and functional health claims. Distribution channel dynamics reveal supermarkets consolidating urban throughput even as wholesale networks dominate inter-municipal supply to smaller cities and food manufacturers.
INVIMA, Colombia's national food and drug surveillance institute, enforces sanitary registration and cold chain traceability mandates that shape plant-level investment and market access thresholds for domestic and imported products. The Ministry of Agriculture and Rural Development coordinates Fondo Nacional del Ganado programs that influence producer financing and herd modernization timelines. Stakeholders must monitor how impending sustainability disclosure requirements from Colombian regulators reshape packaging investment and carbon accounting across the dairy value chain.
Market Dynamics
INVIMA's cold chain traceability mandates are compressing plant-level investment timelines while Bogotá's metropolitan corridor concentrates premium demand, forcing processors to modernize infrastructure ahead of enforcement waves.
Growth Catalysts
- Fondo Nacional del Ganado financing:Colombia's Ministry of Agriculture and Rural Development channels herd modernization capital toward Andean dairy cooperatives, accelerating genetic improvement and milk yield per cow.
- Ultra-high temperature processing adoption:Extended shelf-life technology enables processors to penetrate Colombia's secondary cities beyond Bogotá without refrigerated distribution density.
- Functional health positioning:Probiotic yogurt claims capture urban household loyalty through INVIMA-registered nutritional assertions that command retail shelf placement.
Market Restraints
- Input cost volatility:Imported feed concentrate prices fluctuate with peso-dollar exchange rates, squeezing margin structures for Colombian dairy farmers dependent on external protein sources.
- Supply concentration risk:Raw milk collection networks cluster within 150 kilometers of Bogotá, leaving Caribbean and Pacific regions structurally underserved by industrial processors.
- Regulatory friction:INVIMA sanitary registration timelines for novel fermented products extend 18-24 months, delaying market entry for innovation-focused entrants.
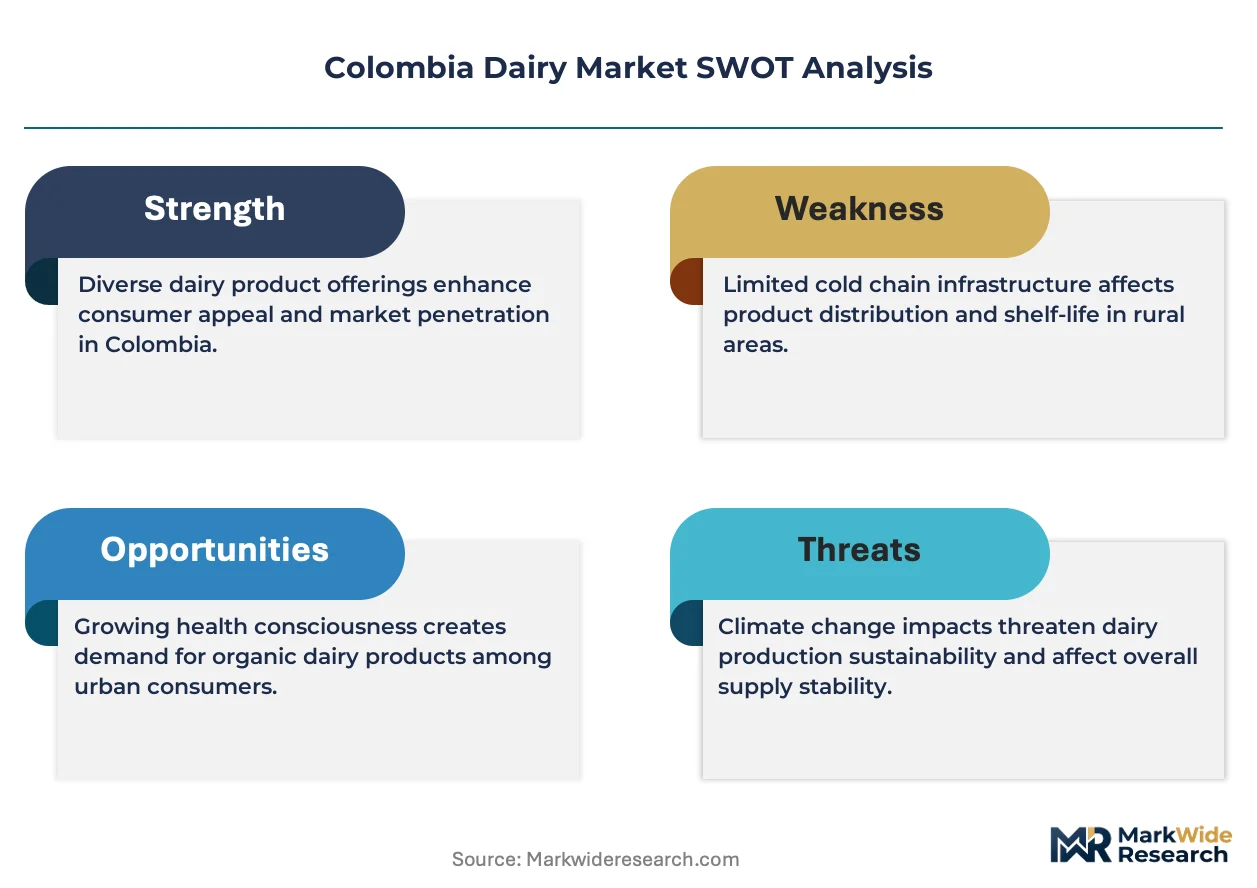
Strategic Opportunities
- Antioquia and Valle del Cauca penetration:Colombia's second and third metropolitan zones show underdeveloped cold chain infrastructure relative to per capita dairy consumption potential.
- E-commerce direct-to-home delivery:Urban households in Medellín and Cali demonstrate willingness to subscribe refrigerated dairy boxes, bypassing traditional wholesale intermediaries.
- Sustainability disclosure alignment:Impending Colombian carbon accounting requirements for packaged goods create first-mover advantage for processors with verified supply chain footprints.
Industry Challenges
- Certification timeline compression:INVIMA's evolving traceability standards require simultaneous HACCP recertification and digital record system overhauls at legacy processing plants.
- Cold chain reconfiguration friction:Inter-municipal distributors face capital requirements for GPS-tracked refrigerated fleets to meet pending national logistics mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Dairy Market |
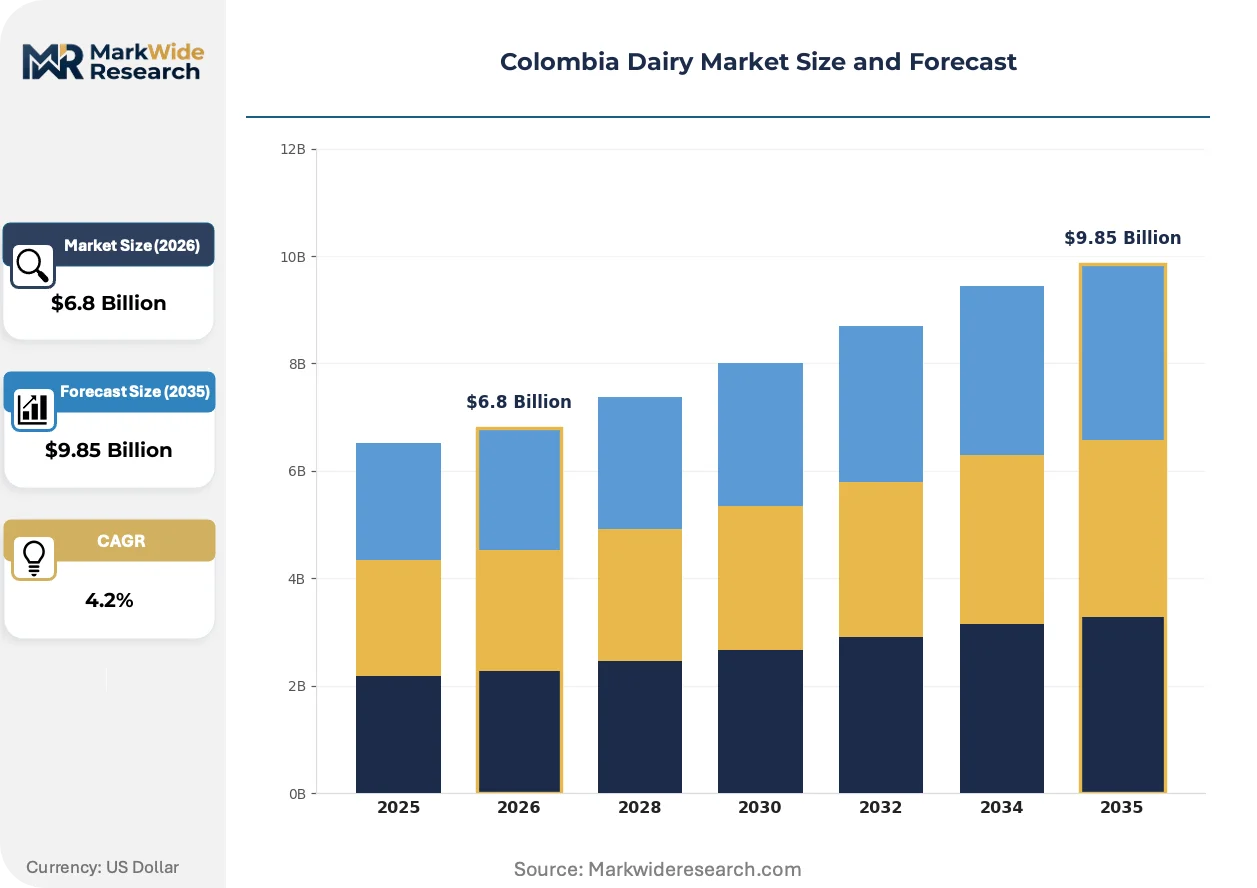
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Customer Type: Households, Food Service, Food Manufacturers, Exporters Quality Grade: Organic, Conventional, Premium, Standard |
| Companies Covered | Alpina Productos Alimenticios, Colanta, Lactalis Colombia, Auralac, Coolechera, Nestlé, Alquería, Inprolac, Danone, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Dairy Market Strategic Shifts & Innovations
Colombia's dairy sector is experiencing technology-driven processing efficiency gains alongside regulatory pressure for supply chain transparency and shifting household consumption patterns toward functional nutrition.
Extended shelf-life packaging is miniaturizing distribution economics for Colombian processors. UHT-treated milk in aseptic cartons enables shelf-stable logistics without continuous refrigeration, allowing Algarra and regional cooperatives to serve secondary cities like Bucaramanga and Pereira. This technology is miniaturizing the capital threshold for geographic expansion, compressing the historical advantage of vertically integrated cold chain operators.
INVIMA's phased implementation of digital sanitary registration platforms is accelerating compliance documentation requirements. Processors must now submit batch-level traceability data through centralized portals, raising IT infrastructure costs for smaller Andean cooperatives. Fermented product categories face the steepest adaptation curves due to live culture handling protocols.
Household buyers in Colombia's urban corridors are consolidating weekly dairy purchases through supermarket loyalty programs that bundle fluid milk with value-added derivatives. Traditional corner store channels in working-class Bogotá neighborhoods are losing volume share as price-sensitive consumers migrate to hard-discount formats with private-label fermented offerings. This channel rotation is most visible in Cundinamarca department's satellite municipalities.
Colombia Dairy Market Segmentation
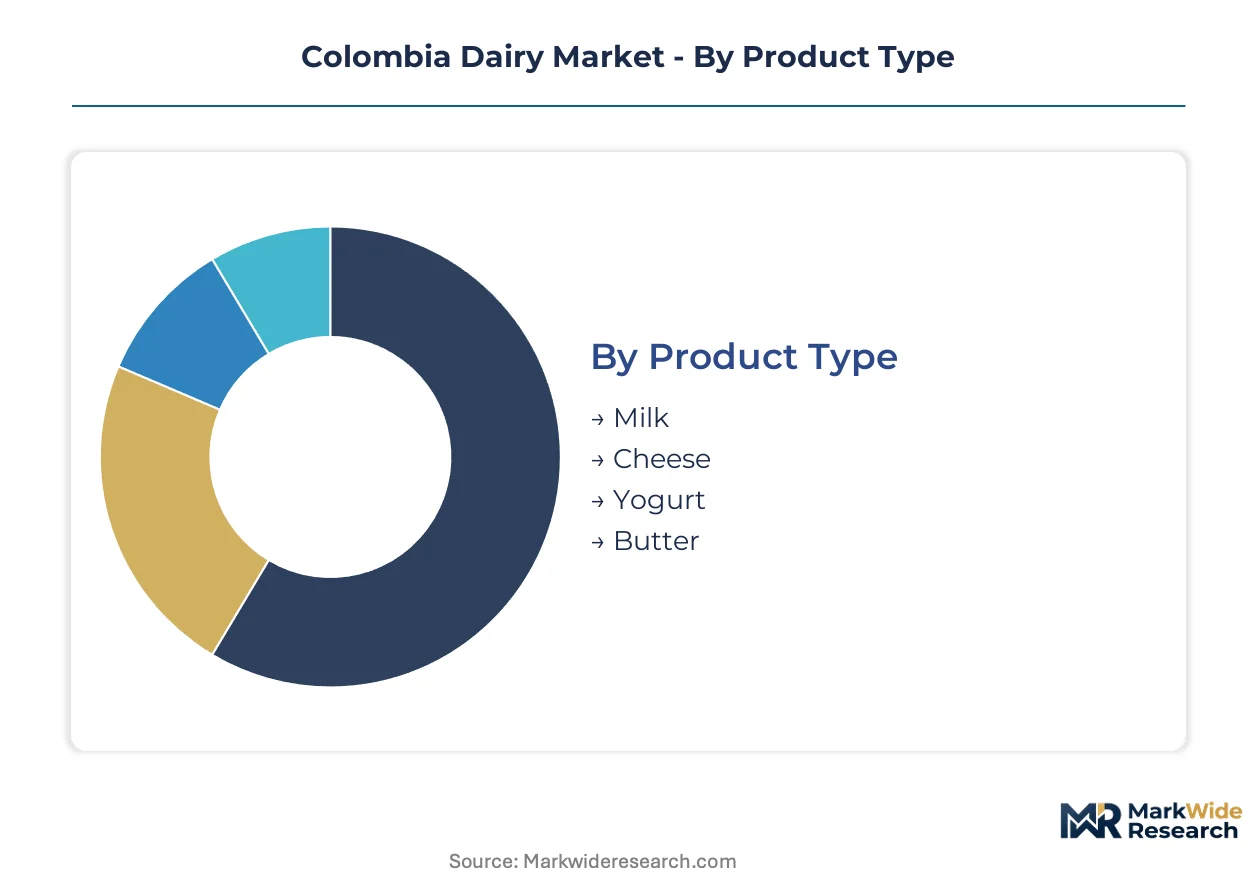
Colombia's dairy market stratification reveals how channel power, quality premiums, and end-use specifications create distinct competitive arenas. Understanding these segment boundaries enables processors to allocate capital across cold chain infrastructure, product development, and geographic expansion with precision.
Product Type:
Fluid milk commands the highest throughput through Bogotá's supermarket networks, while fermented derivatives generate disproportionate margin capture in urban households.
- Milk:Pasteurized and UHT-treated fluid products constitute the volume foundation, with protein content and somatic cell counts serving as procurement benchmarks for industrial buyers. Demand concentrates in Cundinamarca department's metropolitan corridor, where supermarket loyalty programs bundle fluid milk with complementary derivatives to lock in weekly purchase cycles.
- Yogurt:Fermented products with live cultures differentiate through INVIMA-registered probiotic health claims that command premium shelf placement. Urban households in Medellín and Cali demonstrate the steepest uptake of functional positioning, driving margin expansion ahead of fluid milk categories.
- Cheese:Fresh and aged varieties serve both household consumption and food service procurement, with regional cooperatives dominating fresh white cheese supply to Andean restaurant networks.
- Butter:Fat derivatives remain concentrated in baking and food manufacturing applications, with industrial buyers in Bogotá's processed goods corridor representing the primary offtake.
Milk dominates installed base. Yogurt is where expansion concentrates.
Distribution Channel:
Channel selection directly determines capital intensity, with refrigerated logistics requirements scaling from ambient wholesale through cold-chain-dependent supermarket and online formats.
- Supermarkets:Hard-discount and full-service formats in Bogotá, Medellín, and Cali consolidate urban throughput through private-label fermented offerings and loyalty-driven bundle pricing. These channels impose the strictest INVIMA cold chain compliance standards on supplier fleets.
- Convenience Stores:Traditional corner stores in working-class neighborhoods face volume erosion as price-sensitive consumers migrate to discounters, though they retain relevance for emergency fluid milk purchases in satellite municipalities.
- Online Retail:Direct-to-home refrigerated subscription boxes demonstrate traction among urban households willing to bypass wholesale intermediaries for scheduled delivery of probiotic and premium-grade products.
- Wholesale:Inter-municipal distributors supply secondary cities and food manufacturers, though GPS-tracked fleet mandates are compressing margins for legacy operators serving Bucaramanga and Pereira.
Wholesale networks dominate installed base. Online retail is climbing the fastest.
Customer Type:
End-use specifications diverge sharply between retail-facing households and industrial buyers, with procurement standards tightening fastest among export-oriented processors.
- Households:Urban consumers in Colombia's three metropolitan zones drive premium and functional product uptake, consolidating weekly purchases through supermarket loyalty programs that reward cross-category bundling.
- Food Service:Restaurant and hotel buyers in Bogotá's hospitality corridor procure fresh white cheese and UHT milk through specialized distributors, with quality consistency requirements exceeding retail-grade specifications.
- Food Manufacturers:Processed goods producers expand dairy procurement for bakery, confectionery, and ready-meal applications, demanding bulk supply contracts with certified protein content and extended shelf-life parameters.
- Exporters:Cross-border shipments face additional sanitary registration timelines and cold chain documentation requirements that favor processors with established INVIMA compliance infrastructure.
Households dominate installed base. Food manufacturers are gaining share fastest.
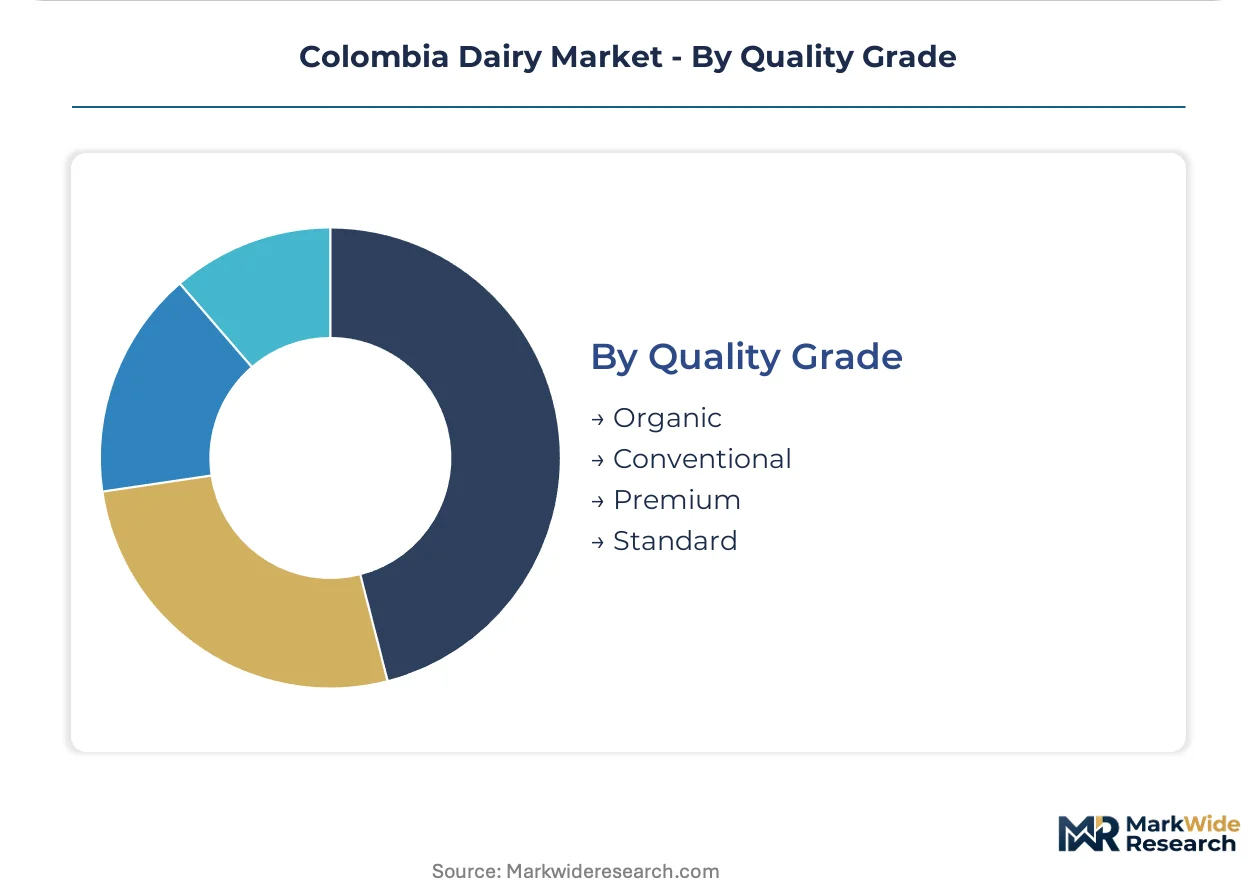
Quality Grade:
Quality tiering aligns with channel access and pricing power, with organic and premium grades commanding placement in supermarket premium aisles while standard grades flow through wholesale networks.
- Organic:Certified production with restricted antibiotic and feed additive protocols captures shelf space in Bogotá's upscale supermarket formats, though supply remains constrained by herd conversion timelines in Andean cooperatives.
- Premium:Enhanced protein content, specialized packaging, and functional health claims justify price positioning above conventional tiers, with urban households in Medellín demonstrating willingness to pay for perceived nutritional differentiation.
- Conventional:Standard pasteurization and UHT products serve volume demand through wholesale and discount channels, with INVIMA baseline compliance sufficient for market access.
- Standard:Entry-grade fluid milk competes primarily on price in hard-discount formats and traditional corner stores, with minimal differentiation beyond basic sanitary registration.
Conventional dominates installed base. Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bogotá-Santa Marta rail corridor and Caribbean port infrastructure anchor Colombia's dairy distribution architecture, enabling cold chain penetration into secondary markets beyond the Andean core.
Cundinamarca and Bogotá Metropolitan Area
Urban household consumption clusters drive premium fluid milk and probiotic yogurt uptake through supermarket loyalty programs. INVIMA's sanitary registration mandates shape processing plant investment timelines across the region. Bogotá's processed goods corridor concentrates food manufacturer demand for certified protein content and extended shelf-life dairy inputs.
Antioquia and Medellín
Colombia's second metropolitan zone shows underdeveloped cold chain infrastructure relative to per capita dairy consumption potential, creating whitespace for UHT-treated product penetration. The Ministry of Agriculture and Rural Development channels Fondo Nacional del Ganado financing toward herd modernization in surrounding Andean cooperatives. Medellín's urban households demonstrate willingness to subscribe refrigerated dairy boxes through direct-to-home delivery channels.
Valle del Cauca and Cali
Wholesale networks currently dominate inter-municipal supply to food service buyers and smaller retailers across the Pacific-facing region. INVIMA's pending GPS-tracked fleet mandates for refrigerated logistics are compressing distributor margin structures. Cali's hospitality corridor procures fresh white cheese through specialized distributors with quality specifications exceeding retail-grade benchmarks.
Santander and Bucaramanga
Aseptic carton UHT technology enables processors to serve this secondary city without continuous refrigerated distribution density. Regional cooperatives leverage extended shelf-life packaging to miniaturize capital thresholds for geographic expansion. Bucaramanga's supermarket networks are consolidating volume share as traditional corner stores lose price-sensitive consumers to hard-discount formats.
Risaralda and Pereira
Coffee belt municipalities present untapped demand for functional fermented products with INVIMA-registered health claims. Inter-municipal distributors face reconfiguration friction as national cold chain traceability standards tighten. Pereira's urban corridor is absorbing premium-grade dairy through modern retail formats that reward cross-category bundling with fluid milk.
Colombia Dairy Market Key Industry Players
Listed leaders compete with private specialists across cooperative federation structures and backward-integrated collection networks. The market exhibits tiered concentration with national-scale processors anchoring Bogotá supply while regional cooperatives defend Andean shelf presence. Two strategic archetypes dominate: vertically integrated processors with captive raw milk sourcing, and cooperative federations pooling member production for collective bargaining power. Competitive moves center on cold chain infrastructure modernization ahead of INVIMA enforcement waves, and portfolio diversification into probiotic-positioned fermented derivatives.
Among cooperative federation specialists, Colanta anchors Andean department presence through member-owned production pooling. Alquería occupies a position exemplifying backward-integrated supply chain control through raw milk collection network ownership. Alpina Productos Alimenticios represents the fermented product specialization archetype, with urban household loyalty built around live culture handling protocols and functional health positioning. These three players collectively illustrate the competitive tension between scale-driven national coverage and regional cooperative density.
| Leading Market Players |
|---|
| Alpina Productos Alimenticios |
| Colanta |
| Lactalis Colombia |
| Auralac |
| Coolechera |
| Nestlé |
| Alquería |
| Inprolac |
| Danone |
| Others |
Cost & Logistics Intelligence
INVIMA's sanitary registration and cold chain traceability mandates gate both supply qualification and price differentiation simultaneously, compressing margin structures for non-compliant operators while rewarding certified processors with premium shelf placement in Bogotá's supermarket networks. Input cost volatility in imported feed concentrates transmits directly through peso-dollar exchange rate movements, forcing pricing recalibration across conventional and premium tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between food manufacturers and industrial dairy suppliers, with protein content and somatic cell count benchmarks determining baseline pricing. Three-tier pricing separates premium-grade probiotic yogurts with INVIMA-registered health claims from standard UHT fluid products and economy-tier corner store milk. Cost compression in the standard tier is intensifying because hard-discount formats are consolidating price-sensitive consumers through private-label fermented offerings. Food manufacturers demonstrate the least price sensitivity due to stringent quality specifications, while traditional corner stores in working-class neighborhoods face the steepest margin erosion.
Supply Chain Analysis
Inventory lead times compress dramatically for UHT-treated products in aseptic packaging, enabling processors to bypass continuous refrigerated logistics and serve secondary cities with ambient distribution networks. Raw milk collection draws from Andean cooperatives clustered within 150 kilometers of Bogotá, with feed concentrate imports resting on dollar-denominated commodity markets. Single-source vulnerability concentrates in the Bogotá metropolitan corridor, where industrial processing capacity dominates national output. Distribution runs through GPS-tracked refrigerated fleets for supermarket compliance, while wholesale networks supply inter-municipal markets with pending traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates the Colombia dairy landscape as household consumption patterns bifurcate between premium functional positioning and hard-discount economy tiers, creating niches for specialized entrants between cooperative federation scale and national processor dominance.
For Market Incumbents: Consolidate backward integration into raw milk collection networks to defend against margin compression from imported feed cost volatility. Prioritize cold chain infrastructure modernization ahead of INVIMA enforcement waves, and lock in food manufacturer contracts through certified protein content guarantees that emerging cooperatives cannot match. For New Entrants and Emerging Players: Anchor in Antioquia and Valle del Cauca's underdeveloped cold chain infrastructure, where UHT technology enables penetration without refrigerated distribution density. Target Medellín's urban households with direct-to-home refrigerated subscription boxes for probiotic products, bypassing wholesale intermediaries through e-commerce platforms that established players have neglected. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermented product categories due to live culture handling protocols and extended INVIMA registration timelines. Over the projection horizon, vertically integrated processors with captive raw milk sourcing and established compliance infrastructure represent the most defensible acquisition archetype. The signal to watch is INVIMA's phased digital registration platform rollout, which will accelerate compliance cost divergence between legacy and modernized operations.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Modernization | INVIMA's GPS-tracked fleet mandates compress investment timelines for distributors serving secondary cities. |
| Backward Integration into Raw Milk Collection | Captive supply networks insulate processors from peso-dollar volatility in imported feed concentrate markets. |
| Probiotic Product Line Extension | INVIMA-registered health claims command premium shelf placement and urban household loyalty in Bogotá. |
| UHT Technology Adoption | Extended shelf-life packaging miniaturizes capital thresholds for geographic expansion beyond refrigerated corridors. |
| E-commerce Direct-to-Home Launch | Subscription refrigerated boxes bypass wholesale intermediaries in Medellín and Cali metropolitan zones. |
Research Approach
Cross-validation between primary interviews with dairy processing executives, cooperative federation managers, and supermarket category buyers anchors the qualitative findings against secondary validation from INVIMA regulatory filings, Ministry of Agriculture Fondo Nacional del Ganado program disclosures, and customs trade data on feed concentrate imports. Bottom-up triangulation across regional cooperative production volumes and top-down reconciliation with national consumption estimates ensures coverage consistency across the analysis window.
Sensitivity analysis frames the quantitative modeling, with volume and value outputs reflecting segmentation across product type, distribution channel, customer archetype, and quality grade dimensions. CAGRs derive from trend extrapolation anchored in documented herd modernization timelines and UHT adoption curves, with forecast inputs incorporating exchange rate volatility assumptions and INVIMA compliance cost trajectories.
Decision-makers should treat outputs as directional under stable regulatory enforcement and feed import cost assumptions; material deviation in peso-dollar parity or accelerated INVIMA digitization timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Milk Powder Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
North America Cheese Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Sour Cream Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Filled Cheese Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Blue Cheese Market
Dairy Products
Japan Casein Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Savory Dairy Products Market