
 Evaporated Milk Market | 2026-2036
Evaporated Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Evaporated Milk Market Intelligence
FDA dairy identity standards are expanding compliance burdens for new entrants while rewarding established operators with formulation expertise. Nestlé leverages its global dairy R&D network to navigate these standards across multiple jurisdictions. Arla Foods amba anchors its evaporated milk position through cooperative-owned supply chains in Northern Europe. Dana Dairy Group specializes in private-label production for Middle Eastern and African markets where shelf-stable dairy remains essential.
Evaporated milk is heat-treated concentrated cow's milk with approximately 60% of water removed, yielding a minimum 6.5% milk fat and 16.5% milk solids content that delivers extended shelf stability without refrigeration. Its primary commercial purpose centers on food manufacturing, institutional cooking, and household preparation where fresh milk logistics prove impractical. Unsweetened evaporated milk dominates institutional and industrial procurement due to formulation flexibility, while sweetened variants command premium positioning in retail dessert applications. Tetra Pack formats are displacing conventional cans in emerging-market distribution channels where material weight and opening convenience reshape consumer preference.
USDA dairy grading programs and FDA identity standards govern compositional benchmarks and labeling claims for evaporated milk distributed in American commerce, while EFSA and national EU dairy regulations enforce parallel requirements across European member states. Codex Alimentarius standards coordinate international trade specifications, reducing friction for exporters like Royal FrieslandCampina and Yotsuba Milk Products. Stakeholders must monitor evolving shelf-life extension technologies and shifting retail channel configurations to preserve margin structures as private-label competition intensifies.
Market Dynamics
Food manufacturers are reformulating toward shelf-stable dairy ingredients as cold-chain logistics costs escalate and supply security concerns intensify across processed food categories. This structural pivot concentrates procurement power among industrial buyers while squeezing margins for commodity-grade suppliers.
Growth Catalysts
- USDA Dairy Grading Programs:Federal quality benchmarks institutionalize evaporated milk in institutional foodservice contracts, locking in volume commitments from school nutrition programs and military procurement channels.
- Confectionery Processing:Traditional Mexican dessert recipes sustain per-capita consumption rates that exceed regional norms by substantial margins, anchoring import demand from Central American processors.
- Aseptic Tetra Pack Formats:Lightweight carton packaging reduces distribution costs and opening friction in emerging-market retail channels where conventional cans face consumer resistance.
Market Restraints
- Fresh Milk Substitution:Expanding cold-chain infrastructure in Southeast Asia and Sub-Saharan Africa enables fluid milk penetration into applications previously dependent on evaporated alternatives.
- Skim Milk Powder Price Volatility:Input cost swings for dairy solids concentrate squeeze formulation margins for private-label producers without backward integration into milk powder processing.
- FDA Identity Standard Compliance:Updated compositional requirements for milk fat and solids content create regulatory friction for exporters unfamiliar with US dairy labeling protocols.
Strategic Opportunities
- West African Urban Markets:Shelf-stable dairy remains essential in Nigerian and Ghanaian cities where refrigeration penetration lags income growth, creating white space for fortified evaporated milk positioning.
- Plant-Based Convergence:Hybrid formulations combining evaporated milk with oat or coconut extracts address lactose-intolerant demographics without full substitution.
- EU Green Deal Packaging Incentives:Carbon-border adjustments and extended producer responsibility schemes favor aseptic carton suppliers over metal can producers in European distribution.
Industry Challenges
- Dairy Technologist Shortage:Specialized expertise in concentrated milk heat-stabilization processes is concentrating among aging workforces in Northern European cooperative processing facilities.
- Legacy Canning Line Retrofit Costs:Converting existing metal packaging infrastructure to aseptic filling systems demands capital outlays that strain mid-tier private-label manufacturers.
- Cross-Border Certification Timelines:Codex Alimentarius harmonization gaps force redundant laboratory testing for exporters seeking simultaneous FDA and EFSA market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evaporated Milk Market |
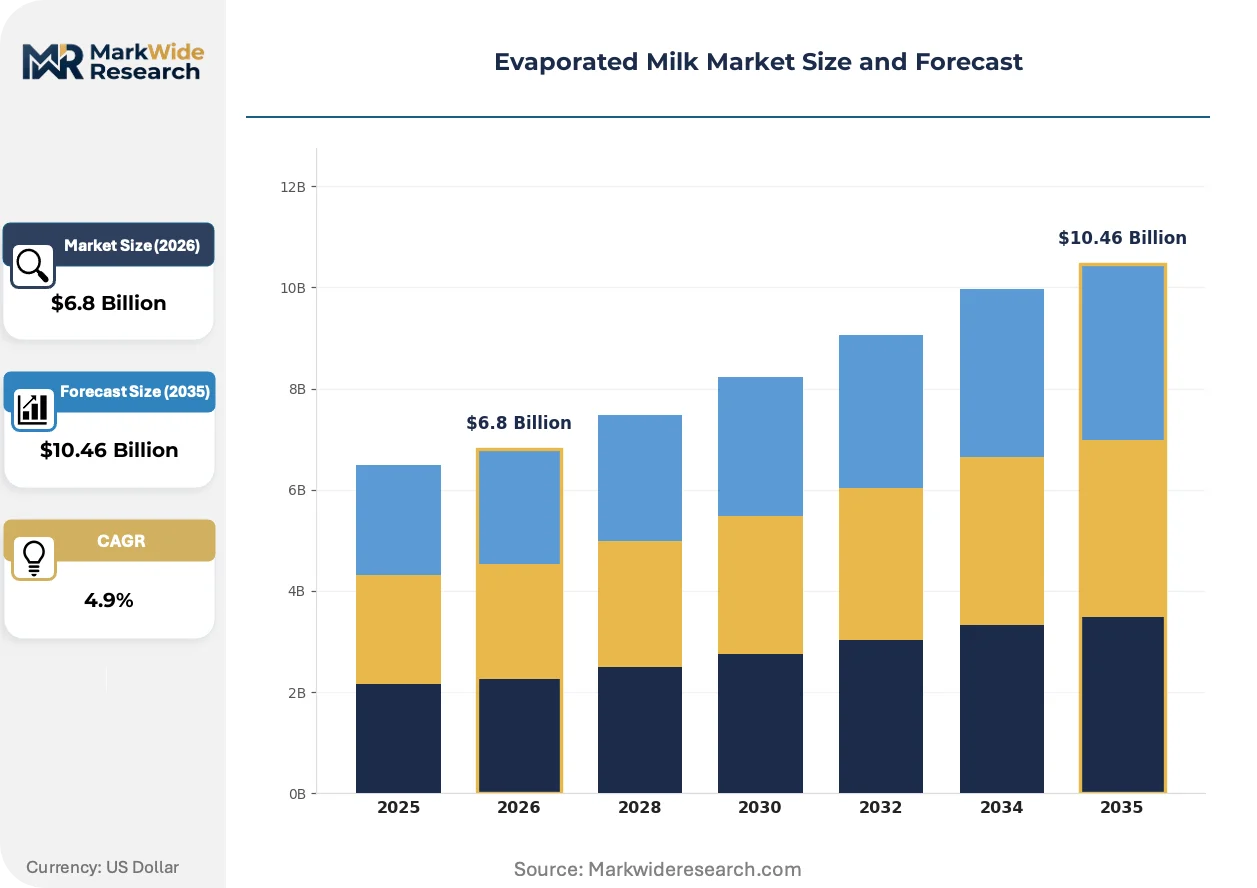
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened, Unsweetened, Flavored, Organic Packaging Type: Tetra Pack, Cans, Bottles, Pouches End User: Households, Food Service, Food Processing, Bakeries Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Fraser and Neave, Limited, Delta Food Industries FZC, Nestlé, Eagle Family Foods Group LLC, Alaska Milk Corporation, Arla Foods amba, Royal FrieslandCampina, Yotsuba Milk Products Co., Ltd., Dana Dairy Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evaporated Milk Market Strategic Shifts & Innovations
Processing technology and packaging format evolution are compressing cost structures while regulatory pressure on compositional claims intensifies scrutiny across export markets. These forces are reshaping competitive positioning toward formulation expertise and supply-chain control.
UHT sterilization coupled with membrane filtration is consolidating quality consistency in industrial-grade evaporated milk production. European dairy cooperatives are adopting these integrated systems to reduce thermal degradation while extending shelf stability. The technology is consolidating procurement decisions around suppliers with captive UHT capacity, marginalizing toll processors without in-house sterilization infrastructure.
EFSA's updated dairy labeling guidelines are tightening nutritional claim substantiation requirements across EU member states. Processors must now document protein quality scores and mineral bioavailability through controlled clinical studies rather than compositional analysis alone. Fortified evaporated milk positioned for pediatric nutrition applications faces the steepest compliance burden, with reformulation cycles extending eighteen to twenty-four months for major suppliers.
Industrial buyers are consolidating supplier relationships around full-service dairy ingredient portfolios rather than single-product procurement. Food manufacturers in Mexico and Central America now demand integrated supply contracts spanning evaporated milk, sweetened condensed milk, and specialized cream preparations. This pattern concentrates volume with processors possessing multi-product formulation capabilities, fragmenting procurement among pure-play evaporated milk specialists.
Evaporated Milk Market Segmentation
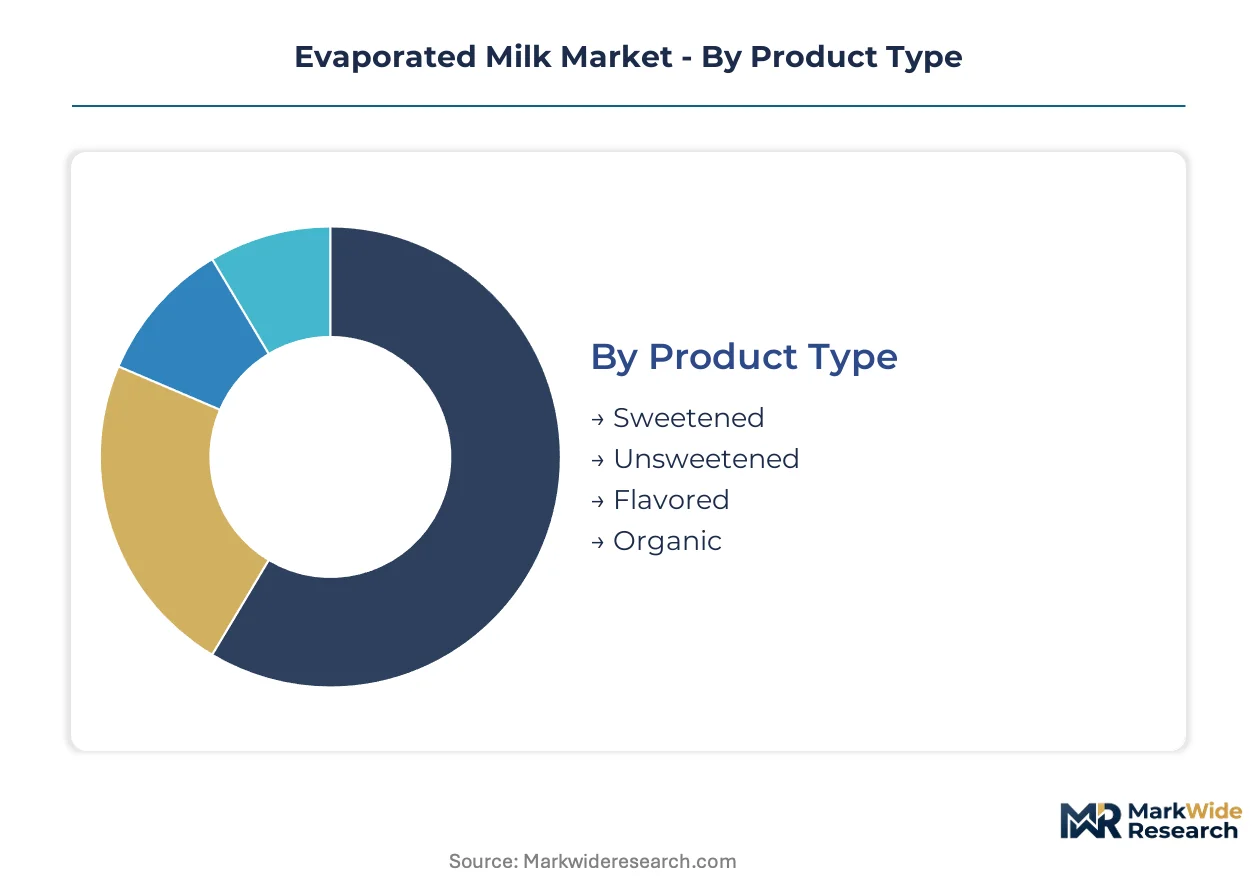
Segmentation in evaporated milk markets reveals how regulatory compliance burdens and packaging technology investments concentrate margin capture among specialized processors. Each dimension carries distinct certification requirements that reshape competitive positioning across procurement channels.
Product Type:
FDA identity standards impose compositional thresholds that vary sharply across sweetened and unsweetened variants, while organic positioning triggers USDA National Organic Program certification chains.
- Unsweetened:Heat-concentrated cow's milk with minimum 6.5% milk fat and 16.5% milk solids, delivering formulation flexibility for institutional foodservice contracts in Mexico and Central American industrial kitchens. Procurement from this segment dominates bulk purchasing agreements where processors demand neutral bases for customized dessert production.
- Sweetened:Sucrose-added variant with elevated viscosity and caramelized flavor profiles, commanding premium retail positioning in Latin American dessert applications. Demand concentrates in Mexican household consumption and traditional confectionery recipes where per-capita intake substantially exceeds regional benchmarks.
- Flavored:Vanilla and chocolate-infused formulations targeting pediatric nutrition and beverage applications, requiring additional flavor additive disclosures under FDA labeling protocols.
- Organic:Milk sourced from certified organic dairy operations with full traceability documentation, carrying USDA organic seal requirements and 20-40% price premiums over conventional equivalents.
Leading the category by volume: Unsweetened. Growing fastest: Organic.
Packaging Type:
Material selection determines distribution economics and shelf-life extension capabilities, with aseptic carton technology demanding capital commitments that fragment supplier tiers.
- Tetra Pack:Aseptic carton systems enabling 6-12 month ambient stability with 70% weight reduction versus metal alternatives, reshaping emerging-market retail penetration in Nigerian and Ghanaian urban centers where refrigeration access remains limited. EFSA packaging sustainability incentives favor this format in European distribution channels.
- Cans:Traditional tinplate containers with established recycling infrastructure, retaining cost advantages in bulk institutional procurement and military supply chains governed by USDA commodity specifications.
- Bottles:PET and glass formats targeting premium household segments with resealability convenience, common in Middle Eastern retail environments.
- Pouches:Flexible laminate structures with minimal material costs, gaining traction in price-sensitive West African markets through informal retail channels.
Volume leadership sits with cans. Steepest expansion trajectory belongs to Tetra Pack formats.
End User:
Procurement scale and specification rigor divide this dimension, with food processing buyers consolidating supplier relationships around full-service dairy portfolios.
- Food Processing:Industrial manufacturers of confectionery, bakery mixes, and prepared desserts purchasing evaporated milk as a functional ingredient for moisture retention and fat emulsification, with Mexican processors anchoring regional demand through traditional recipe requirements.
- Food Service:Institutional kitchens in schools, hospitals, and military facilities operating under USDA dairy grading program contracts that lock in volume commitments and quality benchmarks.
- Households:Retail consumers in Latin America and Southeast Asia selecting evaporated milk for home cooking where fresh milk cold-chain logistics prove unreliable.
- Bakeries:Artisan and commercial bread producers utilizing evaporated milk for enriched dough formulations, concentrated in Middle Eastern and North African markets.
Food Processing commands the largest procurement volumes. Food Service exhibits the most stable contract structures.
Distribution Channel:
Channel configuration determines margin capture and consumer access patterns, with modern trade expansion displacing traditional wholesale networks in urbanizing markets.
- Supermarkets:Organized retail chains in Mexico, Brazil, and South Africa carrying multiple product variants with promotional pricing cycles, requiring slotting fee investments that favor established suppliers with marketing budgets.
- Wholesale:Bulk distribution to food manufacturers and institutional buyers through dairy cooperatives and specialized ingredient distributors, common in Northern European supply chains anchored by Arla Foods amba and FrieslandCampina networks.
- Convenience Stores:Small-format urban retail in Latin American and Southeast Asian cities where evaporated milk serves as a staple pantry item with high purchase frequency.
- Online Retail:E-commerce platforms expanding in Middle Eastern and African markets with delivery logistics overcoming traditional distribution infrastructure gaps.
Wholesale channels move the greatest tonnage. Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's IMMEX maquiladora zones concentrate evaporated milk processing capacity near border logistics corridors serving confectionery exporters. Tax incentives under this program attract dairy multinationals seeking duty-advantaged access to US food manufacturing supply chains.
Mexico
Traditional dessert recipes sustain per-capita consumption rates substantially above regional benchmarks, anchoring demand from Central American processors. The country's national food safety regulator enforces NOM-092 standards for dairy identity and labeling compliance. Querétaro and Jalisco host concentrated evaporated milk production clusters supplying both domestic retail and export-oriented confectionery manufacturers.
United States
USDA dairy grading programs lock institutional volume commitments from school nutrition and military procurement channels. FDA updated identity standards tighten compositional requirements for milk fat and solids content claims. Midwest dairy cooperatives in Wisconsin and Minnesota maintain processing infrastructure serving bulk foodservice contracts.
Germany
EFSA dairy labeling guidelines drive reformulation investments among exporters seeking EU market access. The EU Green Deal packaging incentives favor aseptic carton suppliers over metal can producers in distribution networks. Bavarian dairy processing clusters leverage membrane filtration technology to reduce thermal degradation in concentrated milk production.
Nigeria
Urban refrigeration penetration lags behind income growth, preserving essential demand for shelf-stable dairy in Lagos and Abuja household markets. The country's national food and drug regulator enforces NAFDAC registration requirements for imported dairy products. Port Harcourt distribution hubs channel evaporated milk through informal retail networks reaching secondary cities.
Saudi Arabia
SFDA dairy import standards govern halal certification and compositional benchmarks for evaporated milk entering Gulf Cooperation Council markets. Vision 2030 food security initiatives incentivize localized dairy processing investments. Jeddah and Riyadh retail modernization programs expand organized trade penetration for Tetra Pack formats.
Evaporated Milk Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Market structure fragments between global dairy multinationals with captive R&D networks and regional private-label processors serving price-sensitive emerging markets. Three archetypes dominate: cooperative-owned European processors with backward integration into milk supply, Middle Eastern specialists in halal-certified shelf-stable dairy, and Asian conglomerates with diversified beverage and confectionery portfolios. Competitive moves concentrate on packaging format conversion and multi-product supply contract consolidation.
Among diversified food conglomerates, Nestlé occupies a position exemplifying global formulation expertise navigating FDA and EFSA standards simultaneously. Royal FrieslandCampina and Arla Foods amba represent the cooperative-owned archetype, anchoring European supply chains with member-farmer milk sourcing. Dana Dairy Group exemplifies private-label specialization for Middle Eastern and African markets where shelf-stable dairy remains essential infrastructure.
| Leading Market Players |
|---|
| Fraser and Neave, Limited |
| Delta Food Industries FZC |
| Nestlé |
| Eagle Family Foods Group LLC |
| Alaska Milk Corporation |
| Arla Foods amba |
| Royal FrieslandCampina |
| Yotsuba Milk Products Co., Ltd. |
| Dana Dairy Group |
| Others |
Cost & Logistics Intelligence
UHT sterilization and membrane filtration adoption simultaneously compresses production costs and consolidates procurement power among processors with captive sterilization infrastructure, fragmenting toll processors without in-house capacity and reshaping margin distribution across supplier tiers.
Pricing Analysis
Lead-time-driven pricing premiums reward processors with FDA and EFSA dual-certification readiness, while spot inventory discounts attract price-sensitive private-label buyers in West African informal channels. Three-tier pricing structure across premium certified, standard commercial, and economy private-label levels separates organic and fortified variants from commodity-grade bulk supply. Pricing pressure stems from skim milk powder input volatility squeezing formulation margins for non-integrated producers. Food processing buyers exhibit lowest price sensitivity due to recipe-locked specifications, while informal retail channels in Nigeria and Ghana demand maximum cost efficiency.
Supply Chain Analysis
Certification gating through FDA identity standards and EFSA dairy labeling guidelines fragments supplier access to premium procurement channels, concentrating volume with processors maintaining parallel compliance infrastructure. Milk supply concentrates in Northern European cooperative networks, Mexican border maquiladora zones, and Middle Eastern halal-certified operations. Raw material flows draw from fluid milk procurement, skim milk powder concentrate, and sucrose inputs for sweetened variants. Single-source vulnerability runs through concentrated membrane filtration equipment suppliers. Distribution feeds from dairy cooperative networks through wholesale ingredient channels and modern retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around formulation expertise and captive sterilization capacity, with FDA and EFSA compliance burdens forcing weaker toll processors toward exit or acquisition.
For Market Incumbents: Extend multi-product supply contracts spanning evaporated milk, sweetened condensed milk, and specialized cream preparations to lock in Mexican and Central American food manufacturers. Deepen backward integration into skim milk powder processing to buffer input cost volatility threatening private-label margins. Prioritize Tetra Pack format conversion in Nigerian and Ghanaian distribution to capture emerging-market retail modernization. For New Entrants and Emerging Players: Begin with fortified evaporated milk positioning in West African urban markets where refrigeration penetration lags income growth and shelf-stable dairy remains essential infrastructure. Target pediatric nutrition applications requiring extended reformulation cycles that deter established players from rapid competitive response. Pursue cooperative supply partnerships with Northern European dairy farmers to secure traceable organic milk sourcing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of mid-tier private-label processors by cooperative-owned European networks seeking geographic expansion. Long-term viability favors operators with integrated UHT capacity and multi-jurisdictional certification infrastructure. Watch for inflection when FDA enforcement actions against non-compliant imports accelerate market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Tetra Pack Format Conversion | Lightweight aseptic cartons reduce distribution costs in Nigerian and Ghanaian urban retail channels. |
| Backward Integration into Milk Powder | Captive skim milk powder production buffers margin compression from dairy solids price volatility. |
| Dual FDA-EFSA Certification Investment | Parallel compliance infrastructure unlocks premium procurement channels in US and European food manufacturing. |
| Fortified Product Line Extension | Pediatric nutrition positioning commands price premiums but requires eighteen-to-twenty-four-month reformulation cycles. |
| West African Distribution Partnership | Informal retail network access in Lagos and Abuja captures shelf-stable dairy demand amid refrigeration gaps. |
Research Approach
Multi-period observation of USDA dairy grading program contract volumes, FDA enforcement actions, and EFSA guideline implementation anchored the trend analysis, supplemented by interviews with dairy processing plant managers, food manufacturer procurement leads, Tetra Pack equipment specialists, and cooperative supply chain directors. Secondary validation drew from FDA dairy identity standard filings, EFSA scientific opinions, Codex Alimentarius trade specifications, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Input-output matrices mapped fluid milk supply, skim milk powder conversion rates, and packaging format adoption to derive segment-level volume and value trajectories across the projection horizon. Segmentation dimensions included product type, packaging technology, end-use application, and distribution channel configuration. CAGRs were synthesized from historical procurement pattern analysis and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporated membrane filtration adoption curves and cold-chain infrastructure development indices.
Underlying measurement precision varies by segment; USDA-graded institutional contracts carry tighter precision than informal West African retail estimates. Forecasts reflect assumptions regarding regulatory enforcement continuity and dairy input price stabilization. A model refresh is warranted upon material change in FDA identity standard enforcement intensity or accelerated cold-chain penetration in Sub-Saharan African markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Cheese Shreds Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
China Milk Protein Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Blue Cheese Market
Dairy Products
Colombia Dairy Market
Dairy Products
Milk Mineral Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
Europe Yogurt Market
Dairy Products
Dairy Carton Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Sheep Milk Market
Dairy Products
Europe Casein and Caseinates Market