
 Ultra High Temperature Sterilized Milk Market | 2026-2036
Ultra High Temperature Sterilized Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Temperature Sterilized Milk Market Insights
Food service procurement is consolidating as the fastest-growing end-use vertical for UHT sterilized milk, displacing traditional household bulk purchasing in emerging markets. Nestlé leverages its aseptic packaging partnerships to control channel access across Latin American and African markets. Lactalis anchors European production scale through backward integration into dairy farming cooperatives. Fonterra Co-operative Group Limited competes on powder-to-liquid flexibility, allowing seasonal milk supply smoothing.
Ultra high temperature sterilized milk undergoes heating at 135-150°C for 2-5 seconds, destroying spoilage microorganisms and enzymes while enabling ambient storage for 6-9 months unopened. Shelf-stable milk occupies the largest volume share as the default commodity format for humanitarian aid and institutional feeding programs. Flavored milk represents the fastest-growing product type as processors target younger demographics in Southeast Asian and Middle Eastern markets. Tetra Pak packaging dominates margin pools due to barrier-layer technology premiums and recycling infrastructure lock-in.
The EU Green Deal and REACH frameworks constrain sterilization energy intensity and packaging material composition, forcing plant retrofits and supplier audits. China's SAMR enforces GB 25190 standards for UHT milk protein and fat content, creating compliance barriers for imported product. FDA pasteurized milk ordinances in the United States limit UHT labeling claims, constraining market positioning against refrigerated alternatives. Stakeholders must monitor carbon border adjustment mechanisms and aseptic line automation costs as decisive variables for capacity planning.
Market Dynamics
EU Green Deal emissions mandates are forcing sterilization plant retrofits across European dairy processing, compressing operating margins while accelerating energy-efficient line investments. Food service procurement consolidation is displacing household bulk purchasing as the dominant volume driver in emerging markets.
Growth Catalysts
- Food service channel expansion:Extended supply chain requirements from quick-service restaurant operators are pulling ambient-stable dairy into institutional procurement frameworks.
- REACH packaging compliance:Barrier-layer material standards are locking processors into certified supplier relationships with recycling infrastructure providers.
- China cold-chain gaps:Urban inland distribution limitations make shelf-stable formats essential for reaching secondary and tertiary city markets.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings directly impact sterilization line economics, particularly for batch-process operators.
- Tetra Pak packaging concentration:Aseptic carton technology licensing creates dependency on single-source barrier-layer supply for mid-scale processors.
- FDA labeling friction:Pasteurized Milk Ordinance restrictions on UHT positioning against refrigerated alternatives constrain premium pricing in North American retail.
Strategic Opportunities
- Flavored milk penetration:Sweetened and functional variants targeting younger demographics remain underdeveloped in Middle Eastern and Southeast Asian convenience channels.
- EU carbon border adjustments:Emerging tariff mechanisms on embedded emissions create first-mover advantage for processors with verified low-carbon sterilization lines.
- Aseptic line automation:Robotics integration with existing filling equipment reduces labor dependency and contamination risk simultaneously.
Industry Challenges
- Retrofit capex intensity:Green Deal compliance requires simultaneous investment in heat recovery systems and renewable energy procurement contracts.
- GB 25190 certification timelines:China's protein and fat content verification protocols extend product registration cycles for imported UHT milk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Temperature Sterilized Milk Market |
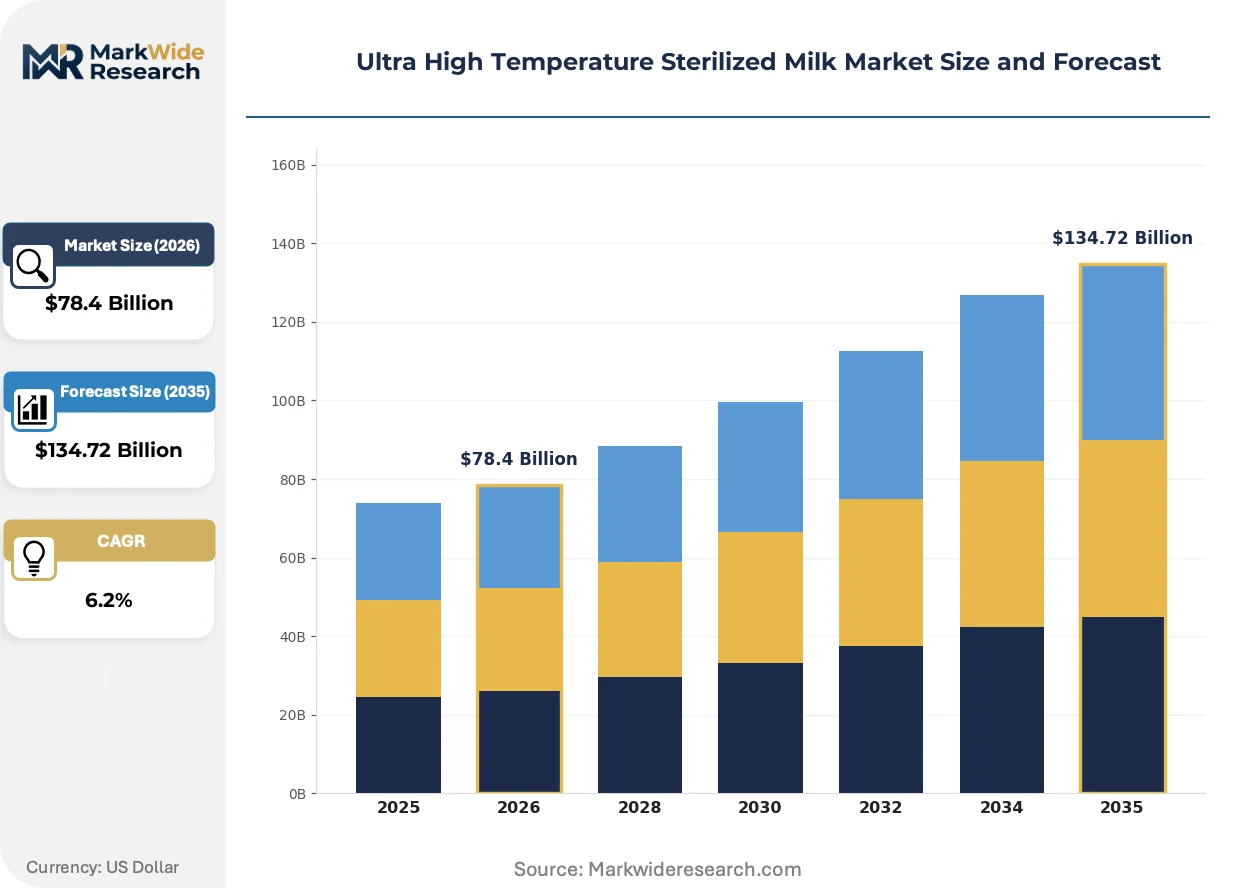
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shelf-Stable Milk, Flavored Milk, Whole Milk, Non-Fat Milk End User: Retail Outlets, Food Service, Households, Food Manufacturers Packaging Type: Aseptic Cartons, Bottles, Pouches, Tetra Pak Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Nestlé, Lactalis, Fonterra Co-operative Group Limited, Danone, Arla Foods amba, Royal FrieslandCampina, Yili Group, Saputo Inc., Dairy Farmers of America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Temperature Sterilized Milk Market Trends and Innovations
Aseptic packaging technology is converging with digital printing and connected supply chain tracking, creating new differentiation vectors beyond barrier performance. Regulatory carbon accounting and buyer procurement centralization are simultaneously reshaping competitive positioning.
Direct-heating sterilization systems are converging with heat recovery exchangers and renewable energy integration. European processors facing EU Green Deal benchmarks are retrofitting plants fastest, compressing payback period assumptions for energy-efficient equipment. This convergence is enabling smaller dairies to meet corporate carbon disclosure requirements without full line replacement.
REACH framework amendments on packaging material composition are forcing supplier audits and material substitution timelines. Industrial consequence includes accelerated testing cycles for alternative barrier layers and recycling stream compatibility. Flavored milk SKUs with complex multi-layer packaging face the steepest compliance cost escalation.
Food service operators are consolidating procurement through centralized category management, displacing fragmented distributor relationships. Quick-service chains and institutional feeders now specify aseptic format and shelf-life requirements directly. This pattern is most visible in Latin American urban markets where cold-chain reliability varies by neighborhood density.
Ultra High Temperature Sterilized Milk Market Segmentation
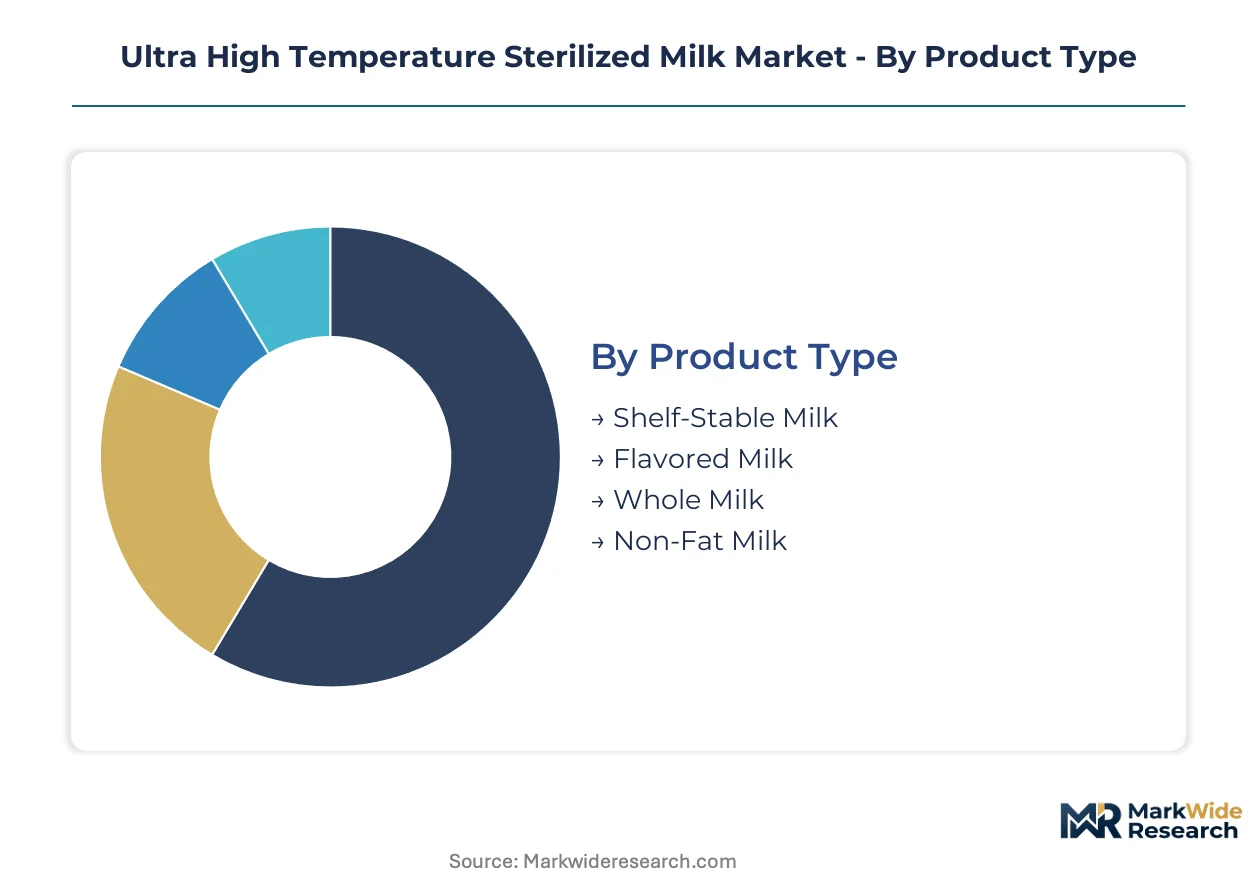
UHT sterilized milk segmentation reveals distinct compliance and channel access patterns across product formats and packaging technologies. Certification requirements from SAMR, FDA, and EU Green Deal frameworks create divergent margin structures by segment.
Product Type:
Shelf-stable and flavored variants carry divergent regulatory burdens — GB 25190 protein standards apply universally while flavored formulations face additional additive scrutiny under REACH and national food codes.
- Shelf-Stable Milk:Standard UHT format processed at 135-150°C for 2-5 seconds, destroying spoilage microorganisms for 6-9 month ambient storage. Demand concentrates in Chinese inland cities where cold-chain gaps make refrigerated distribution uneconomical for secondary markets.
- Flavored Milk:Sweetened and functional variants with cocoa, strawberry, or malt formulations targeting younger demographics. Southeast Asian convenience channels and Middle Eastern urban markets show steepest uptake as processors expand SKU portfolios beyond commodity white milk.
- Whole Milk:Full-fat UHT format with minimum 3.25% milk fat content, prevalent in European retail and institutional feeding programs.
- Non-Fat Milk:Skimmed UHT variant with less than 0.5% fat, preferred by health-conscious segments in North American and Japanese markets.
Shelf-stable milk sits at the top of the volume ranking, with flavored milk climbing the fastest.
End User:
Customer type determines packaging specification and procurement scale — food service operators now dictate aseptic format requirements directly while retail channels fragment by format.
- Retail Outlets:Supermarket and hypermarket channels moving multi-format UHT portfolios with private-label penetration highest in European markets.
- Food Service:Quick-service restaurant chains and institutional feeders consolidating procurement through centralized category management, specifying shelf-life and format requirements for extended supply chains across Latin American and African markets.
- Households:Traditional bulk purchasing segment being displaced by food service procurement in emerging markets, though remaining dominant in European and North American residential consumption.
- Food Manufacturers:Industrial buyers of UHT milk as ingredient input for bakery, confectionery, and processed dairy products, requiring tanker-load delivery and custom fat/protein specifications.
Food service sits at the top of the volume ranking, with food manufacturers climbing the fastest.
Packaging Type:
Barrier-layer technology and recycling infrastructure compatibility create tiered supplier dependency — Tetra Pak licensing concentration shapes competitive access for mid-scale processors.
- Aseptic Cartons:Multi-layer paperboard packaging with aluminum foil barrier, dominating European and North American retail due to established recycling streams and consumer familiarity.
- Bottles:HDPE and PET formats with oxygen-scavenging layers, prevalent in Brazilian and Mexican markets where bottle deposit schemes operate.
- Pouches:Flexible film packaging with metallized barrier layers, lowest unit cost format gaining share in Indian and Indonesian value-tier retail.
- Tetra Pak:Proprietary aseptic carton system with barrier-layer technology premiums and recycling infrastructure lock-in, controlling margin pools across premium retail segments.
Tetra Pak sits at the top of the volume ranking, with pouches climbing the fastest.
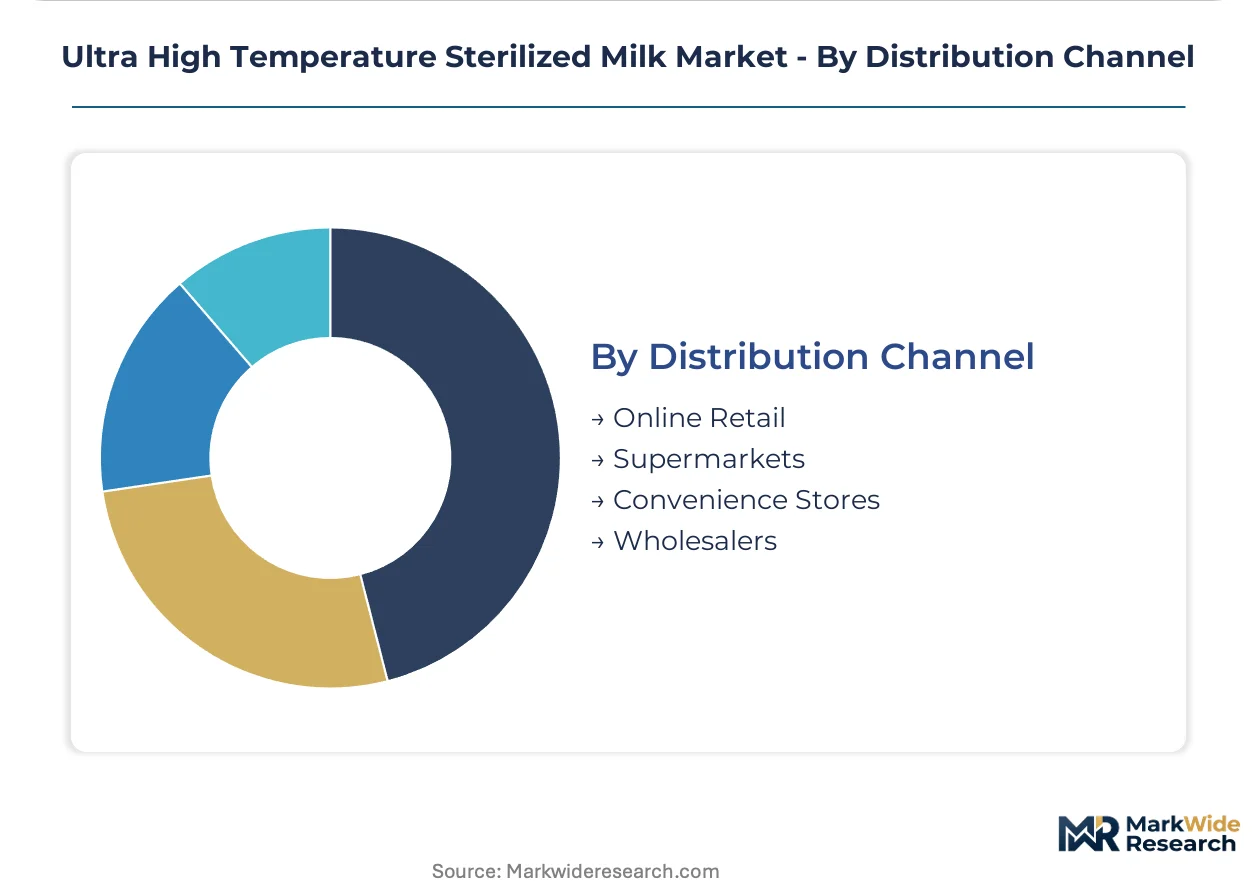
Distribution Channel:
Channel selection determines geographic reach and working capital intensity — online retail requires shortest shelf-life inventory turns while wholesalers absorb longest payment cycles.
- Online Retail:E-commerce platforms with direct-to-home delivery, expanding fastest in Chinese tier-1 cities where urban logistics density supports ambient-stable bulk purchasing.
- Supermarkets:Large-format retail with dedicated dairy aisles, remaining volume anchor in European and North American markets despite share erosion to convenience and online.
- Convenience Stores:Small-format urban retail with limited cold storage, critical channel for single-serve flavored milk in Southeast Asian and Middle Eastern markets.
- Wholesalers:Distributor networks serving independent retailers and food service, consolidating as food service operators bypass traditional tiers for direct processor relationships.
Supermarkets sit at the top of the volume ranking, with online retail climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping UHT sterilized milk production geography as processors relocate capacity to jurisdictions with lower carbon compliance costs and streamlined food safety certification timelines.
China
Urban cold-chain gaps in inland provinces drive shelf-stable dairy demand as essential distribution infrastructure. SAMR enforces GB 25190 protein and fat content standards that extend registration cycles for imported product. Secondary city clusters around Chengdu and Xi'an absorb volume as processors bypass refrigerated logistics limitations.
Germany
EU Green Deal emissions mandates compress operating margins while accelerating heat recovery system retrofits across dairy processing plants. ECHA REACH framework amendments constrain packaging material composition, forcing supplier audits and substitution timelines. Bavarian dairy cooperatives anchor European production scale through backward integration into farming operations.
United States
FDA Pasteurized Milk Ordinance restrictions on UHT labeling claims constrain premium positioning against refrigerated alternatives in retail channels. Natural gas price volatility directly impacts sterilization line economics for batch-process operators. Midwest dairy belt concentration around Wisconsin sustains ingredient supply for industrial food manufacturers.
Brazil
Quick-service restaurant chains consolidate procurement through centralized category management, pulling ambient-stable formats into institutional frameworks. ANVISA food safety protocols govern additive scrutiny for flavored milk variants targeting younger demographics. São Paulo metropolitan logistics density supports bottle deposit scheme operations for HDPE and PET formats.
Saudi Arabia
SFDA dairy import standards create compliance barriers for non-Gulf Cooperation Council processors seeking market access. Convenience channel expansion in Riyadh and Jeddah drives single-serve flavored milk uptake among younger consumer segments. Domestic dairy farming investments under Vision 2030 reduce import dependency for raw milk supply.
Ultra High Temperature Sterilized Milk Market Competitive Landscape
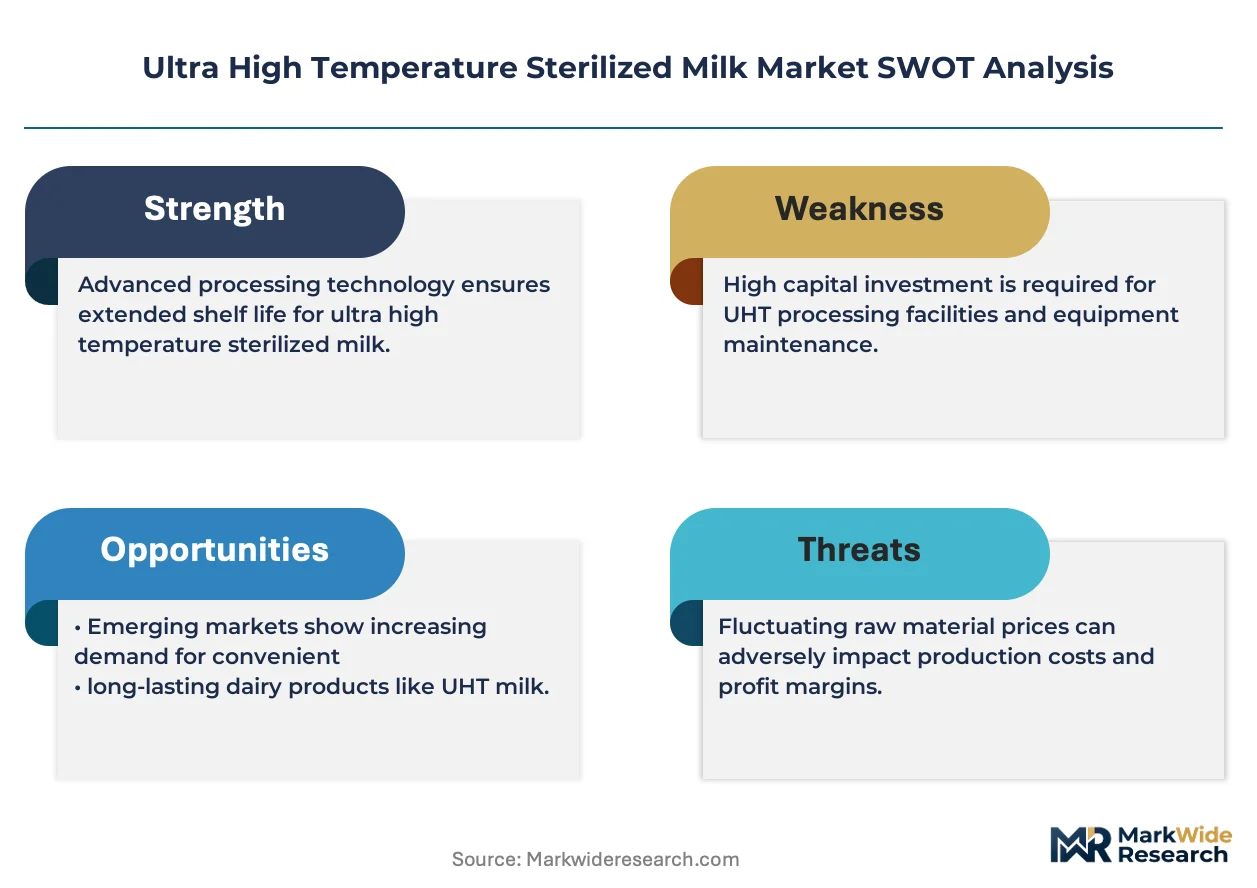
Branded specialists and contract manufacturers split share differently across segments, with Tetra Pak licensing concentration creating tiered supplier dependency for mid-scale processors. The vendor base clusters around three strategic archetypes: integrated dairy cooperatives with captive farming supply, multinational packaged food conglomerates with aseptic packaging partnerships, and regional dairy processors competing on powder-to-liquid flexibility. Dominant competitive moves include strategic partnerships for barrier-layer technology access and portfolio diversification into flavored and functional variants.
Among Swiss-based packaged food conglomerates, Nestlé occupies a position exemplifying aseptic packaging partnership control across Latin American and African markets. Lactalis, as a French dairy cooperative structure, represents the integrated production archetype through backward integration into European farming cooperatives. Fonterra Co-operative Group Limited, New Zealand-based, anchors the seasonal supply-smoothing segment through powder-to-liquid operational flexibility.
| Leading Market Players |
|---|
| Nestlé |
| Lactalis |
| Fonterra Co-operative Group Limited |
| Danone |
| Arla Foods amba |
| Royal FrieslandCampina |
| Yili Group |
| Saputo Inc. |
| Dairy Farmers of America Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap dairy processors in Southern Europe anchor pricing discipline through captive milk supply contracts, while their limited balance-sheet capacity constrains aggressive price competition against multinational conglomerates with deeper aseptic packaging partnerships. This ownership pattern concentrates supply bargaining power among cooperatives with backward integration into farming operations, compressing margins for processors dependent on spot-market raw milk procurement.
Pricing Analysis
Distributor margin layers absorb the steepest compression as food service operators consolidate procurement through direct processor relationships, bypassing traditional wholesale tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by aseptic packaging format and shelf-life certification, with Tetra Pak-licensed products commanding persistent premiums over pouch alternatives. Pricing pressure stems from natural gas cost volatility hitting batch-process sterilization economics, particularly for European operators facing EU Green Deal retrofit requirements. Food service buyers exhibit highest price sensitivity due to centralized category management and volume consolidation, while retail private-label penetration in European markets demonstrates lowest sensitivity through brand-loyalty insulation.
Supply Chain Analysis
GB 25190 certification timelines and REACH packaging compliance audits gate supplier qualification, extending onboarding cycles for alternative barrier-layer providers and locking processors into established Tetra Pak relationships. Raw milk supply concentrates in New Zealand, Germany, and France through cooperative structures and pastoral farming systems, while aseptic carton substrate production draws from Swedish and Finnish paperboard specialists. Aluminum foil barrier layers and oxygen-scavenging polymers constitute critical input dependencies with limited qualified suppliers. Single-source vulnerability in Tetra Pak licensing creates structural concentration risk for mid-scale processors seeking premium retail placement. Distribution runs through food service procurement consolidation and quick-service restaurant chain direct contracts, displacing fragmented wholesale networks in Latin American and African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UHT sterilized milk rests on heat recovery system deployment reducing sterilization energy intensity, while flavored milk premiumization shifts portfolio mix toward higher-margin SKUs targeting Southeast Asian convenience channels.
For Market Incumbents: Extend aseptic packaging partnership control through exclusive barrier-layer technology access agreements, locking out mid-scale competitors from premium retail placement. Deepen backward integration into dairy farming cooperatives in Bavaria and Normandy to secure raw milk supply stability against spot-price volatility. Counter emerging private-label threats through direct food service procurement relationships that bypass distributor margin layers. For New Entrants and Emerging Players: E-commerce direct-to-home platforms offer the lowest barrier entry route, leveraging Chinese tier-1 city logistics density to bypass established supermarket shelf-space competition. Target flavored milk penetration in Middle Eastern convenience channels where brand loyalty remains underdeveloped and GB 25190 compliance timelines have excluded smaller importers. Pursue pouch-format value-tier positioning in Indonesian and Indian retail to avoid Tetra Pak licensing concentration. For Investors and Strategic Acquirers: Packaged food conglomerates with existing aseptic packaging partnerships are the most active acquirer in this space, seeking regional dairy processors to fill geographic portfolio gaps. Long-term viability favors targets with verified low-carbon sterilization lines positioned for EU carbon border adjustment advantage. Watch for inflection in SAMR import registration velocity as signal for Chinese market access tightening or loosening.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery System Retrofit | EU Green Deal compliance compresses payback periods for energy-efficient sterilization equipment in German processing plants. |
| Flavored Milk SKU Expansion | Cocoa and malt variants target younger demographics in Saudi Arabian and Indonesian convenience channels with premium positioning. |
| Direct Food Service Procurement | Quick-service restaurant chain relationships in Brazil and Mexico displace fragmented distributor networks and capture volume consolidation. |
| Aseptic Line Automation | Robotics integration with existing filling equipment reduces labor dependency and contamination risk for European processors. |
| Pouch Format Market Entry | Flexible film packaging with metallized barriers gains share in Indian value-tier retail through lowest unit cost positioning. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade customs databases, and equipment vendor order books — were reconciled against primary interviews with dairy processing plant managers, food service procurement directors, and Tetra Pak licensing specialists. Secondary validation drew from EU ETS emissions disclosures, SAMR product registration records, and SEC filings of listed dairy conglomerates. Bottom-up volume modeling across sterilization line capacities and top-down macroeconomic triangulation anchored the analytical framework.
Data-stream reconciliation enabled segmentation modeling across product format, packaging technology, end-user channel, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from sterilization line investment cycles, food service procurement consolidation velocity, and cold-chain infrastructure development trajectories in target markets. Forecast inputs incorporated EU Green Deal retrofit timelines, REACH packaging amendment implementation schedules, and Chinese inland distribution logistics density projections.
The model assumes a particular technology adoption path; alternative pathways for direct-heating sterilization with integrated heat recovery would alter the outlook for European processor competitiveness. Forecasts reflect assumptions regarding SAMR import registration streamlining and natural gas price stabilization that could revise volume projections materially. A model refresh is warranted upon material change in EU carbon border adjustment mechanism implementation timing or FDA Pasteurized Milk Ordinance labeling revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Flavored Milk Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Smoked Cheese Market
Dairy Products
Organic Cheese Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
White Cheese Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Europe Cheese Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Global Milk Powder Market
Dairy Products
Cream Powder Market
Dairy Products
Low Fat Cheese Market