
 North America Spray Polyurethane Foam for Building and Construction Market | 2026-2036
North America Spray Polyurethane Foam for Building and Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spray Polyurethane Foam for Building and Construction Market Analysis
US chemical producers is consolidating spray polyurethane foam supply chains amid feedstock volatility and logistics cost pressures. Huntsman International LLC leverages its integrated polyols portfolio to sustain margin stability across the value chain. Owens Corning anchors its position through roofing-system bundling that extends SPF penetration in commercial envelopes. NCFI Polyurethanes specializes in regionally optimized formulations that compete effectively against national distributors in the Southeast.
Spray polyurethane foam for building and construction comprises a thermoset cellular plastic created by reacting isocyanate with polyol resin, typically achieving R-values of 6.0 to 7.0 per inch in closed-cell configurations. The material functions primarily as an air barrier, thermal insulator, and moisture manager in building envelopes. Closed cell formulations dominate margin pools due to their structural adhesion and vapor retarder properties in roofing and exterior applications. Residential end users represent the fastest-growing segment as energy code stringency and utility rebate programs expand across jurisdictions. Hybrid foam technologies occupy an emerging niche where contractors seek intermediate density-performance positioning without full closed-cell cost premiums.
The EPA's SNAP program and OSHA's isocyanate exposure standards shape product formulation and installer certification requirements across the United States. Canada's National Building Code and provincial energy efficiency regulations create parallel compliance pathways that manufacturers must navigate for cross-border market access. Stakeholders should monitor evolving state-level HFC phase-down schedules and embodied carbon disclosure mandates that will determine competitive positioning in public procurement channels.
Market Dynamics
EPA's Significant New Alternatives Policy program is compressing formulation cycles across the North American spray polyurethane foam sector as manufacturers race to commercialize next-generation blowing agents ahead of phasedown deadlines.
Growth Catalysts
- IRA Residential Energy Credits:The Inflation Reduction Act's tax incentives for home energy retrofits pull SPF into residential envelope upgrades across US jurisdictions with aggressive rebate stacking.
- Closed-cell density advantages:Structural adhesion and vapor retarder properties in roofing applications displace conventional board-stock insulation in commercial building envelopes.
- Sun Belt cooling loads:Texas, Florida, and Arizona building codes now recognize SPF's thermal performance value in cooling-dominated climates, accelerating specification rates.
Market Restraints
- Isocyanate feedstock volatility:MDI price swings tied to benzene and crude oil benchmarks compress contractor margins and bid competitiveness.
- OSHA exposure standard compliance:Respiratory protection and medical surveillance requirements for isocyanate handling add fixed operational costs to every installation crew.
- Hybrid foam substitution:Intermediate-density open-cell formulations capture price-sensitive residential segments where full closed-cell performance is not code-mandated.
Strategic Opportunities
- Canadian provincial stretch codes:British Columbia and Quebec energy efficiency regulations outpace federal baselines, creating premium formulation demand for cross-border suppliers.
- Embodied carbon procurement mandates:California and New York public building standards now require material disclosures, advantaging low-GWP SPF producers in government bids.
- Roofing-system bundling:Integrated membrane and SPF packages capture commercial re-roofing cycles where single-source accountability reduces project risk.
Industry Challenges
- Certified installer pipeline gaps:OSHA's isocyanate training requirements and manufacturer certification programs constrain crew expansion in high-demand markets.
- Legacy building stock integration:Moisture management conflicts between existing wall assemblies and high-performance SPF retrofits trigger liability concerns among risk-averse contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spray Polyurethane Foam for Building and Construction Market |
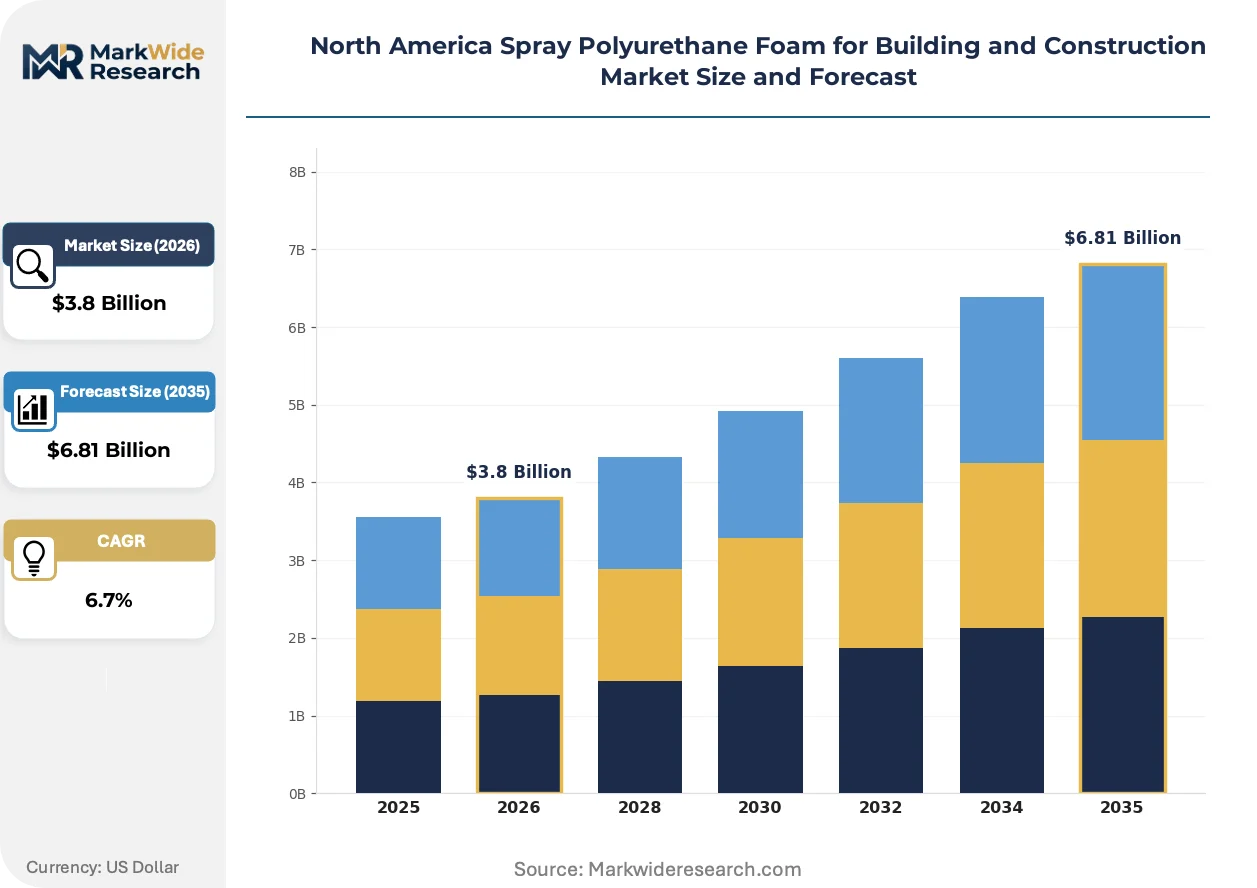
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cell, Closed Cell, Hybrid Foam, Coatings Application: Insulation, Roofing, Soundproofing, Sealing End User: Residential, Commercial, Industrial, Government Installation Method: Spray Application, Hand Application, Pre-Fabricated, Injection |
| Companies Covered | BASF SE, Huntsman International LLC, Owens Corning, Carlisle Companies Inc., Dow Chemical Company, Covestro AG, Johns Manville, NCFI Polyurethanes, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spray Polyurethane Foam for Building and Construction Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and procurement contracting models are simultaneously transforming how SPF manufacturers compete for specification in North American building envelopes.
Next-generation hydrofluoroolefin blowing agent systems are modularizing around core polyol platforms to accelerate EPA SNAP compliance timelines. Mid-size contractors in the US Southeast are adopting these drop-in formulations at the fastest pace to avoid stranded inventory. This modularization is compressing R&D amortization periods and forcing smaller blenders into toll-manufacturing arrangements with integrated resin suppliers.
Canada's National Building Code harmonization with provincial energy efficiency regulations is creating cross-border formulation complexity for US manufacturers. The 2025 code cycle introduces stricter thermal bridging requirements that favor continuous insulation approaches. Commercial envelope specifiers in Ontario and British Columbia are responding by consolidating supplier relationships with vendors holding dual US-Canadian certification.
Utility-managed residential retrofit programs are bundling SPF installation with whole-home energy audits and financing packages. Home performance contractors in Texas and Arizona are displacing traditional insulation bidding through this integrated channel. This convergence is most visible in municipal partnerships where utilities capture demand-side management credits and contractors secure pipeline visibility.
North America Spray Polyurethane Foam for Building and Construction Market Segmentation
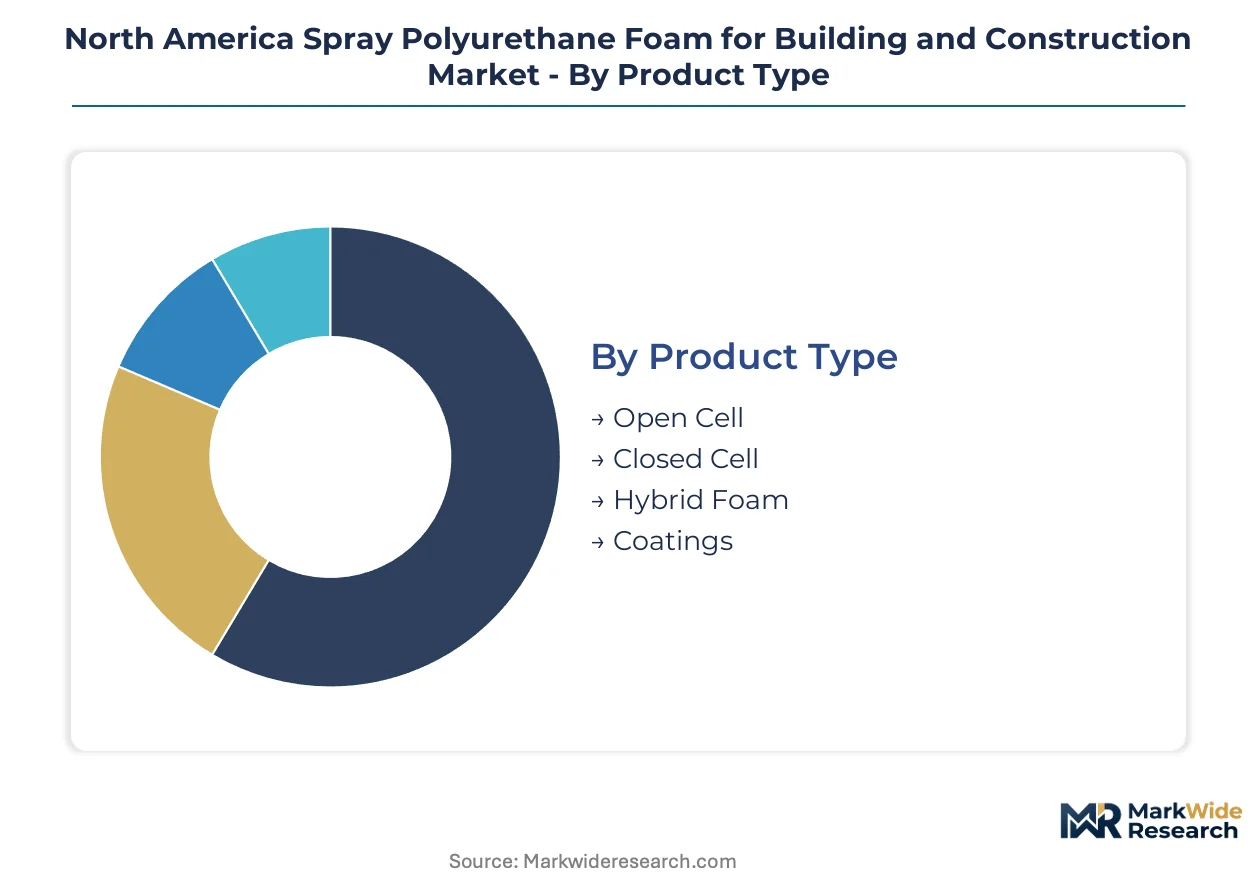
Spray polyurethane foam markets fragment across density-performance tiers, installation modalities, and end-user risk appetites. Each segmentation axis reveals distinct margin pools and specification pathways that manufacturers navigate through differentiated formulation strategies.
Product Type:
Open cell formulations function as standalone thermal layers in interior cavities, while closed cell and hybrid systems embed into composite envelope assemblies requiring structural adhesion or vapor control.
- Closed Cell:R-values of 6.0 to 7.0 per inch derive from hydrofluoroolefin-blown density matrices that simultaneously provide structural rigidity and Class II vapor retarder performance. Demand concentrates in Texas and Florida commercial roofing where cooling-dominated climates maximize thermal resistance value and code mandates continuous insulation approaches. The EPA's SNAP program accelerates formulation turnover as manufacturers phase out legacy HFC blowing agents ahead of regulatory deadlines.
- Open Cell:Lower-density water-blown chemistry achieves R-values near 3.5 per inch with superior acoustic attenuation characteristics. Residential retrofits across Arizona and Sun Belt states drive specification where cost-sensitive homeowners prioritize air sealing over structural adhesion in above-grade wall cavities. The material's permeability requires careful hygrothermal modeling in mixed-humidity zones.
- Hybrid Foam:Intermediate density positioning captures price-sensitive segments seeking performance between open and closed cell without full premium cost structures.
- Coatings:Protective elastomeric topcoats extend SPF system lifecycles in high-UV exposure roofing applications.
Closed cell leads volumes today; hybrid foam is gaining share fastest.
Application:
Margin concentration varies sharply between envelope positions, with roofing applications commanding premium pricing through system bundling while insulation fights commodity pressure.
- Roofing:Seamless monolithic membranes eliminate thermal bridging through direct-to-deck adhesion, displacing mechanically attached board-stock in commercial re-roofing cycles. Texas and Florida building codes now explicitly recognize SPF roofing in wind uplift zones. Integrated membrane-SPF packages from Owens Corning and national distributors capture single-source accountability premiums.
- Insulation:Wall cavity and attic floor applications dominate unit volumes across residential new construction and retrofit channels. The Inflation Reduction Act's residential energy credits pull SPF into envelope upgrades through utility-managed rebate stacking programs. Air barrier continuity requirements in Canada's National Building Code harmonization favor continuous insulation approaches.
- Soundproofing:Open-cell acoustic treatments target multi-family residential and commercial interior partition specifications.
- Sealing:Perimeter and penetration sealing applications leverage SPF's expansion characteristics for air barrier continuity.
Insulation dominates unit economics; roofing delivers the steepest margin expansion.
End User:
Risk tolerance and procurement sophistication separate segments, with government buyers imposing embodied carbon disclosure requirements that filter supplier pools.
- Residential:Home performance contractors displace traditional insulation bidding through utility-integrated retrofit programs in Texas and Arizona. IRA tax incentives stack with municipal rebates to reduce homeowner capital barriers. OSHA isocyanate exposure standards constrain certified installer pipeline expansion in high-demand markets.
- Commercial:Envelope specifiers consolidate supplier relationships around vendors holding dual US-Canadian certification for cross-border project execution. Roofing-system bundling reduces project risk through single-source accountability.
- Industrial:Cold storage and process piping applications demand closed-cell vapor retarder performance in extreme temperature differential conditions.
- Government:California and New York public building standards require material disclosures, advantaging low-GWP producers in procurement channels.
Residential drives volume velocity; government procurement is expanding most quickly on regulatory tailwinds.
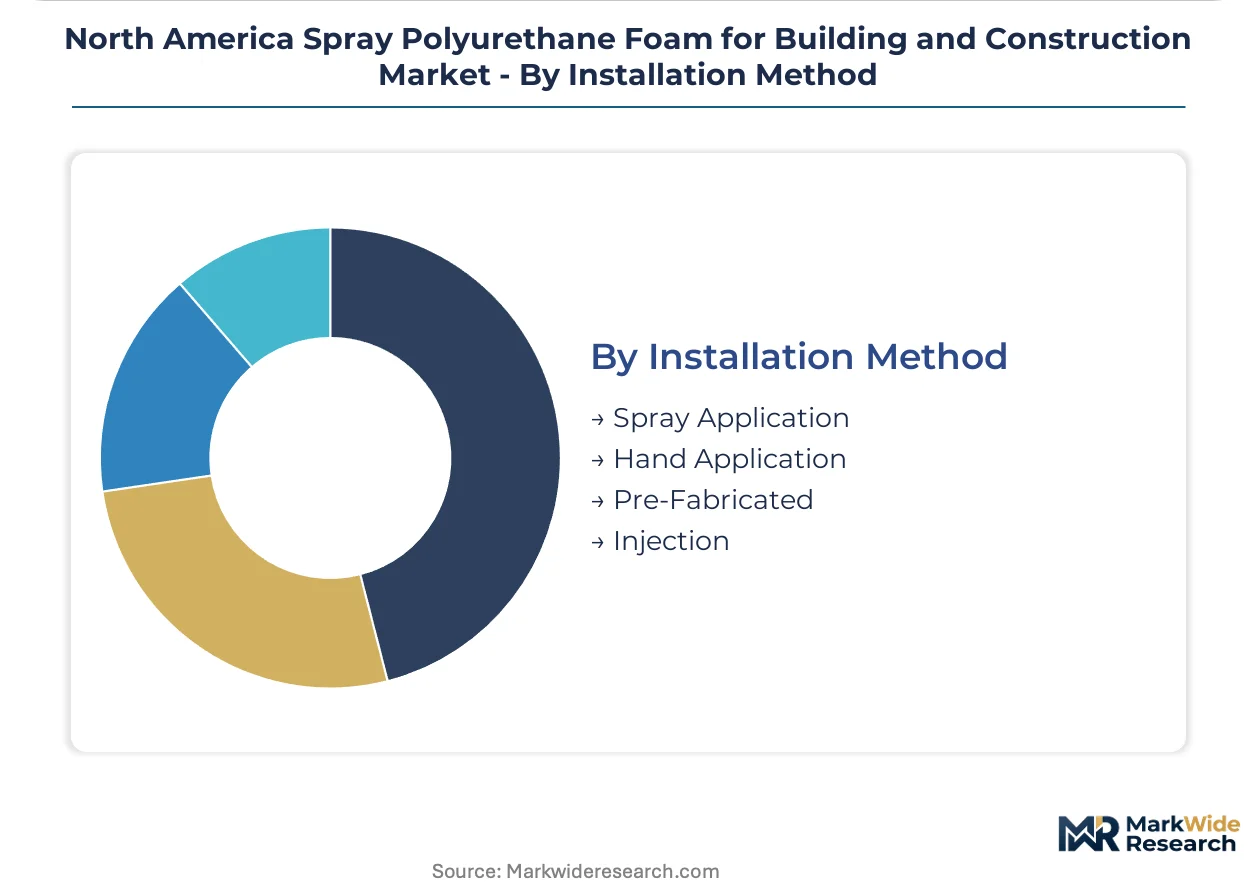
Installation Method:
Labor productivity and skill intensity determine contractor economics, with spray application requiring specialized equipment investment that fragments the installer base.
- Spray Application:High-pressure plural-component equipment delivers field-mixed isocyanate and polyol at temperatures optimizing reaction kinetics. Certified installer scarcity in high-growth Sun Belt markets constrains crew expansion despite demand pull. OSHA respiratory protection and medical surveillance requirements add fixed operational costs per installation team.
- Hand Application:Low-pressure portable systems enable detail work and small-area touch-ups in retrofit contexts.
- Pre-Fabricated:Factory-applied SPF laminates reduce field labor content and isocyanate exposure in controlled manufacturing environments.
- Injection:Cavity-fill applications target existing wall assemblies where tear-out costs prohibit open-spray approaches.
Spray application anchors current capacity; pre-fabricated methods are climbing the fastest as labor constraints bite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing SPF production footprints across North America as manufacturers weigh EPA SNAP compliance costs against provincial energy code premiums. Feedstock access and certified installer density now determine where formulation capacity clusters.
United States
Sun Belt cooling loads in Texas and Florida accelerate closed-cell specification for roofing envelopes. The EPA's SNAP program forces rapid HFC phase-down timelines that favor producers with integrated polyol supply chains. Houston and Dallas-Fort Worth anchor the largest installer certification pipelines, though OSHA respiratory protection requirements constrain crew expansion.
Canada
British Columbia and Quebec stretch codes outpace federal baselines, creating premium demand for continuous insulation approaches. Health Canada's alignment with National Building Code harmonization favors vendors holding dual US-Canadian certification. Toronto and Vancouver commercial envelope specifiers consolidate supplier relationships around cross-border project execution capabilities.
Mexico
Nearshoring of construction materials production gains traction as US contractors seek tariff-advantaged supply sources. Mexico's federal environmental standards lag EPA SNAP timelines, creating interim formulation flexibility for export-oriented producers. Monterrey and Mexico City industrial corridors attract toll-manufacturing arrangements from integrated resin suppliers.
Southeast US
Georgia and Florida residential retrofits exploit IRA tax incentive stacking through utility-managed rebate programs. State-level HFC phase-down schedules in North Carolina and South Carolina trail federal EPA deadlines, preserving legacy formulation windows. Atlanta anchors regional distribution hubs serving Gulf Coast cooling-dominated construction cycles.
Southwest US
Arizona and Nevada desert climates maximize SPF thermal performance value in cooling-intensive building envelopes. California's embodied carbon procurement mandates filter supplier pools for public sector bids, advantaging low-GWP producers. Phoenix and Las Vegas contractor networks specialize in roofing-system bundling that reduces commercial re-roofing project risk.
North America Spray Polyurethane Foam for Building and Construction Market Vendor Landscape
US producers anchor the integrated tier; Canadian and Mexican specialists hold regional formulation niches. Market structure tilts toward consolidation as feedstock volatility and logistics cost pressures squeeze independent blenders. Three archetypes dominate: integrated chemical conglomerates with captive polyol supply, roofing-system bundlers extending SPF penetration, and regionally optimized formulation specialists. Competitive moves center on toll-manufacturing arrangements and cross-border certification investments.
Within the integrated chemical tier, BASF SE and Dow Chemical Company exemplify scale-driven positions anchored by backward control over resin supply chains. Huntsman International LLC occupies a distinct archetype as a polyol-integrated operator sustaining margin stability across value chain positions. Among building materials specialists, Owens Corning and Johns Manville represent roofing-system bundlers capturing single-source accountability premiums in commercial envelopes. NCFI Polyurethanes sits within the regional optimization tier, competing effectively against national distributors through Southeast-focused formulation strategies.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman International LLC |
| Owens Corning |
| Carlisle Companies Inc. |
| Dow Chemical Company |
| Covestro AG |
| Johns Manville |
| NCFI Polyurethanes |
| PPG Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Benzene price benchmarks cascade through MDI and polyol resin costs to stratify SPF pricing across premium certified, standard commercial, and economy retrofit tiers. Contractor bid competitiveness tightens when feedstock volatility compresses margins in the middle tier.
Pricing Analysis
Distributor margin layers separate closed-cell roofing formulations from open-cell residential insulation through certification-grade price differentiation. EPA SNAP-compliant HFO-blown systems command premium positioning against legacy HFC inventories in distributor warehouses. Pricing pressure stems from MDI cost compression in the standard commercial tier as Huntsman and Dow anchor contract structures. Residential retrofit buyers exhibit highest price sensitivity, while government procurement with embodied carbon mandates shows lowest elasticity.
Supply Chain Analysis
Isocyanate supply rests on US Gulf Coast petrochemical complexes and European MDI producers with limited North American captive capacity. Polyol feedstocks draw from propylene oxide derivatives and recycled content streams. Raw material dependencies center on benzene, toluene, and specialty amine catalysts. Tariff exposure on imported resin creates vulnerability for toll-manufacturing blenders without backward integration. Distribution runs through regional distributor networks serving certified installer crews in Sun Belt metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as California and New York embodied carbon procurement mandates shift demand toward low-GWP premium formulations.
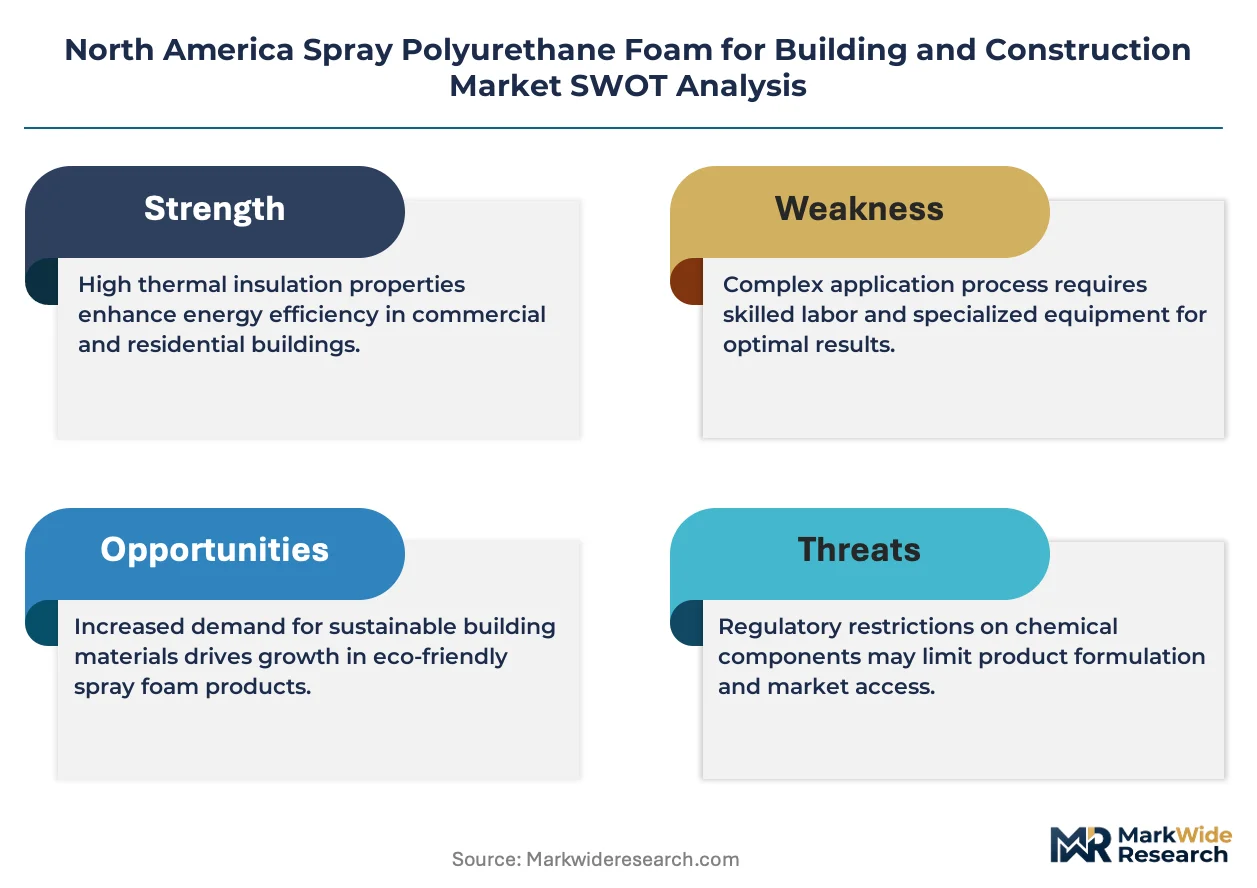
For Market Incumbents: Extend roofing-system bundling into Canadian provincial stretch code markets to capture cross-border certification premiums. Deepen captive polyol supply through Gulf Coast capacity additions. Hybrid foam substitution and certified installer pipeline gaps represent the primary threats to defend against. For New Entrants and Emerging Players: The price-point gap between premium HFO-compliant systems and economy open-cell retrofits creates entry space for mid-tier formulation specialists. Target utility-managed residential retrofit channels in Texas and Arizona where IRA incentive stacking reduces homeowner capital barriers. Pursue toll-manufacturing arrangements with integrated resin suppliers to bypass feedstock volatility exposure. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation specialists holding dual US-Canadian certification and Sun Belt installer network density. Long-term viability favors producers with backward integration into polyol supply and modular HFO platform chemistry. Watch EPA state-level HFC phase-down acceleration as the signal for competitive repositioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Huntsman and Dow sustain margin stability through captive resin production across value chain positions. |
| Dual US-Canadian Certification Investment | Ontario and British Columbia specifiers consolidate supplier relationships around cross-border project execution capabilities. |
| Utility-Managed Retrofit Channel Partnership | Texas and Arizona contractors displace traditional insulation bidding through integrated audit-financing-installation packages. |
| Modular HFO Formulation Platform Development | Mid-size Southeast blenders adopt drop-in chemistries to accelerate EPA SNAP compliance and avoid stranded inventory. |
| Roofing-System Bundling Expansion | Owens Corning captures single-source accountability premiums in commercial re-roofing cycles. |
Methodological Framework
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combined with secondary validation. Interviews incorporated SPF plant managers, procurement leads at commercial envelope contractors, distribution channel partners, and technical R&D directors at integrated resin suppliers. Secondary sources included EPA SNAP program filings, customs and trade data from the US Census Bureau, Canadian National Building Code harmonization documents, and SEC 10-K disclosures from building materials specialists. Bottom-up volume modeling triangulated against top-down market sizing across density-performance tiers.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled included product type tier, application envelope position, end-user risk profile, and installation method labor intensity. CAGRs derived from regression analysis against housing starts, commercial construction put-in-place, and energy code adoption curves. Industry-specific forecast inputs incorporated EPA HFC phase-down schedules and IRA residential credit utilization rates.
Caveats apply where EPA SNAP timeline acceleration or OSHA isocyanate standard enforcement could materially shift the outlook. Forecasts reflect assumptions around feedstock cost normalization and certified installer pipeline expansion. A small set of named triggers—state-level HFC regulations, embodied carbon mandate expansion, and MDI supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Blended Cement Market
Building Materials
Refractory Cement Market
Building Materials
United Kingdom White Cement Market
Building Materials
Geocells Market
Building Materials
United States Architectural Coatings Market
Building Materials
Timber Frames Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Ireland Cement Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Cellular Concrete Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Composite Rebar Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Plaster Accelerator Market