
 Ultra Large Scale Ics Market | 2026-2036
Ultra Large Scale Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Large Scale Ics Market Analytics
Subscription-based access to software-defined chip features is hardening as a recurring revenue layer for ULSI vendors. Nvidia Corporation leverages its CUDA ecosystem to lock in data center customers through recurring licensing. Intel Corporation anchors its foundry strategy on advanced packaging services that extend beyond silicon sales. TSMC dominates leading-edge wafer production by sustaining capital intensity that competitors struggle to match.
Ultra Large Scale Integration refers to semiconductor devices containing millions of transistors on a single die, typically fabricated at process nodes of 7nm or below using extreme ultraviolet lithography. These circuits serve as the computational backbone for applications requiring massive parallel processing, from generative AI inference to autonomous vehicle perception systems. ASIC designs capture premium margins in hyperscaler data centers where custom silicon optimizes power efficiency for specific workloads. FPGA architectures retain strategic value in telecommunications infrastructure where field reprogrammability reduces hardware refresh cycles. CMOS technology maintains volume leadership across consumer electronics and automotive systems despite emerging interest in GaN for power management applications.
The US CHIPS Act directs Department of Commerce funding toward domestic advanced logic fabrication, conditioning subsidy eligibility on restrictions in China capacity expansion. The EU AI Act imposes conformity assessment requirements on high-risk AI systems, creating compliance-driven demand for traceable, auditable chip supply chains under ECHA REACH substance regulations. South Korea's K-Semiconductor Belt clusters tax incentives with infrastructure buildout to capture next-generation memory-logic integration. Stakeholders must weigh geopolitical alignment against cost efficiency as fabrication geography fragments across competing industrial policy regimes.
Market Dynamics
Advanced node fabrication capacity is concentrating around extreme ultraviolet lithography clusters in Taiwan, South Korea, and the United States, creating geographic supply asymmetry that hyperscalers must navigate through multi-sourcing strategies and strategic inventory positioning.
Growth Catalysts
- Generative AI training clusters:Hyperscaler data centers in the United States are expanding procurement of high-bandwidth memory-integrated logic dies for large language model workloads.
- EU AI Act compliance infrastructure:Conformity assessment mandates for high-risk AI systems are generating demand for auditable chip provenance and supply chain traceability under ECHA REACH substance tracking.
- CHIPS Act subsidy conditioning:Department of Commerce funding eligibility tied to domestic fabrication expansion is redirecting capital expenditure toward Arizona, Ohio, and Texas facility buildouts.
Market Restraints
- EUV scanner availability:ASML's annual production capacity for high-NA lithography systems caps leading-edge wafer starts regardless of capital availability.
- Neon gas supply concentration:Ukrainian and Russian purification facilities historically supplied over half of semiconductor-grade neon, creating input fragility since 2022.
- Export control friction:US Bureau of Industry and Security licensing requirements for advanced logic and manufacturing equipment are fragmenting equipment resale markets and service access.
Strategic Opportunities
- India's semiconductor incentive corridor:Gujarat and Tamil Nadu are attracting assembly, test, and packaging investments through the PLI scheme and state-level infrastructure commitments.
- Chiplets and 3D packaging convergence:Universal Chiplet Interconnect Express standards are enabling heterogeneous integration that decouples memory, logic, and I/O process optimization.
- Automotive functional safety certification:ISO 26262 ASIL-D compliance requirements for autonomous perception systems are creating premium pricing tiers for fault-tolerant ULSI designs.
Industry Challenges
- EUV photoresist chemist scarcity:The specialized polymer formulation expertise required for sub-3nm patterning is concentrated among fewer than five hundred researchers globally.
- Co-packaged optical I/O integration:Silicon photonics assembly yield rates remain below merchantable thresholds for volume data center deployment, delaying productization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Large Scale Ics Market |
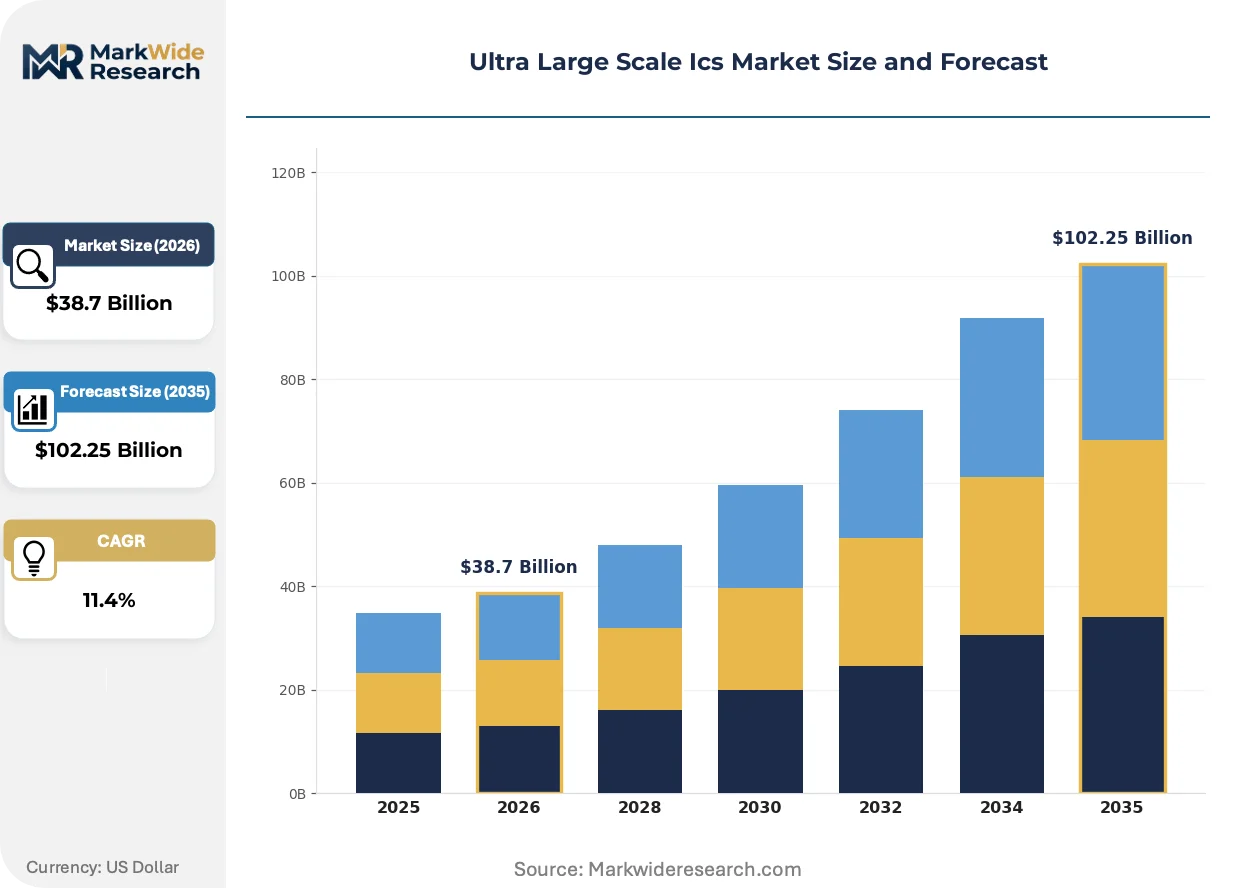
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontroller, FPGA, ASIC, DSP Technology: CMOS, BiCMOS, GaN, SiGe End User: Automotive, Consumer Electronics, Telecommunications, Aerospace Application: IoT Devices, Data Centers, Smart Appliances, Automotive Systems |
| Companies Covered | Nvidia Corporation, Advanced Micro Devices, Intel Corporation, Samsung Electronics, NXP Semiconductors, Microchip Technology, TSMC, Broadcom, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Large Scale Ics Market Evolving Landscape
Compute architecture is fragmenting from monolithic system-on-chip designs toward disaggregated chiplets, forcing ecosystem players to coordinate across previously siloed IP, packaging, and substrate domains.
Chiplet-based design methodologies are decentralizing the traditional system-on-chip value chain by separating CPU, GPU, memory, and I/O dies into independently optimized process nodes. Hyperscalers including Microsoft and Amazon Web Services are adopting this approach for custom AI accelerators to compress development cycles and yield risk. The structural consequence is decentralizing process technology leadership from pure-play foundries toward packaging-centric integrators capable of heterogeneous assembly.
The EU AI Act's high-risk system classification is mandating conformity assessment documentation that traces semiconductor provenance through fabrication, test, and integration stages. Industrial consequence includes mandatory third-party audit requirements for AI training and inference hardware deployed in medical, transportation, and critical infrastructure applications. Automotive and healthcare OEMs in Germany and France are responding by qualifying foundry partners against ISO 21434 cybersecurity and ISO 26262 functional safety standards before volume procurement.
Hyperscaler procurement is consolidating around long-term capacity reservation contracts that displace spot-market wafer purchases. Cloud service providers are negotiating multi-year, multi-billion-dollar prepayments to secure fixed allocation from TSMC and Samsung Foundry, displacing fabless semiconductor companies in queue priority. This pattern is most visible in the United States, where Google, Meta, and Microsoft account for an expanding share of leading-edge node output commitments.
Ultra Large Scale Ics Market Segmentation
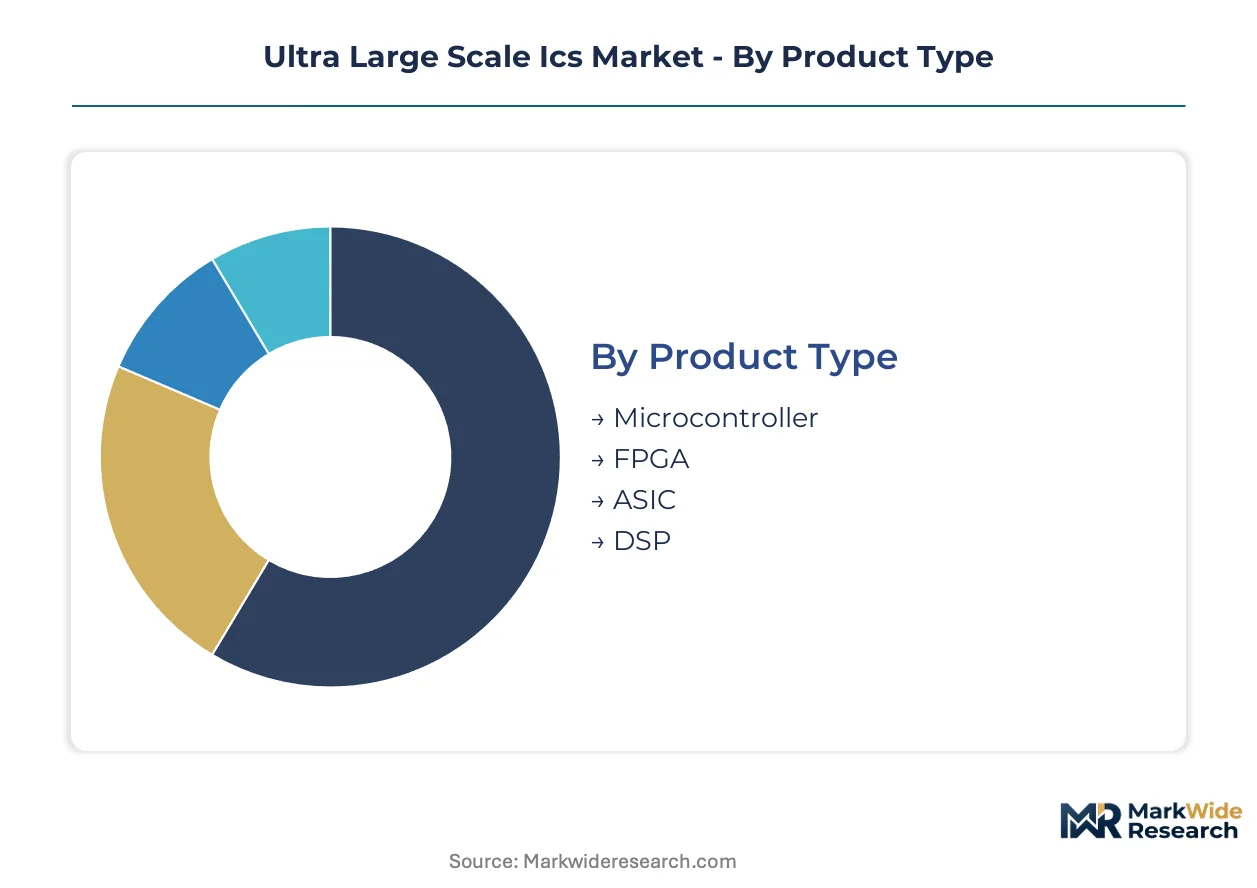
ULSI market segmentation reveals how fabrication economics and end-use requirements fragment demand across process nodes, packaging architectures, and reliability tiers. Buyers sort into distinct procurement patterns based on thermal constraints, volume scale, and regulatory exposure.
Product Type:
ASIC buyers prioritize power efficiency and die area optimization; FPGA purchasers value field reprogrammability and time-to-market compression.
- ASIC:Custom silicon designs manufactured for specific workloads capture premium pricing in hyperscaler data centers where power-per-compute metrics dominate procurement. Google and Amazon Web Services deploy these for AI training acceleration in Oregon and Iowa facilities. Volume sits with ASIC; growth tilts toward FPGA.
- FPGA:Field-programmable gate arrays enable post-deployment logic reconfiguration, reducing hardware refresh cycles in 5G base station deployments across South Korea and Germany. Xilinx and Intel supply these for telecommunications infrastructure where standards evolution outpaces silicon development cycles.
- Microcontroller:Embedded control processors integrate memory and peripherals for automotive body electronics and industrial automation systems.
- DSP:Digital signal processors execute mathematical operations for audio processing, radar systems, and software-defined radio applications.
ASIC volumes dominate wafer starts; FPGA expansion accelerates with telecommunications infrastructure buildouts.
Technology:
Process selection hinges on power-frequency tradeoffs, with CMOS maintaining cost leadership and compound semiconductors penetrating RF and power management niches.
- CMOS:Complementary metal-oxide-semiconductor fabrication at 7nm and below enables the transistor density required for generative AI inference engines. TSMC's N3E process in Hsinchu supplies Nvidia and Apple with logic dies for data center and consumer applications.
- GaN:Gallium nitride power devices switch at higher frequencies than silicon, shrinking magnetics in electric vehicle onboard chargers and server power supplies. Navitas and Infineon supply these for 800V automotive architectures and hyperscaler rack power distribution.
- BiCMOS:Bipolar-CMOS integration combines high-speed analog with dense digital logic for mixed-signal automotive radar and precision sensor interfaces.
- SiGe:Silicon-germanium heterojunction bipolar transistors deliver millimeter-wave performance for automotive radar and satellite communications at lower cost than III-V alternatives.
CMOS absorbs the majority of capital expenditure; GaN climbs fastest as automotive electrification and data center power density requirements intensify.
End User:
Sector-specific reliability certifications and operating temperature ranges create distinct procurement specifications that filter available supplier pools.
- Automotive:Grade 0 (-40°C to 150°C) qualification requirements and ISO 26262 functional safety mandates restrict supplier eligibility for autonomous perception and powertrain control systems. Bosch and Continental source these from Infineon and NXP fabs in Dresden and Austin.
- Telecommunications:Carrier-grade reliability specifications and NEBS compliance drive selection of extended-temperature FPGAs and network processors for 5G core infrastructure. Ericsson and Nokia deploy these in baseband units across European and North American networks.
- Consumer Electronics:Cost-optimized mobile SoCs and wearables processors prioritize die size reduction and packaging miniaturization for smartphone and tablet manufacturers.
- Aerospace:Radiation-hardened and high-reliability components meet DO-254 and MIL-STD-883 requirements for satellite and avionics applications with decade-long operational lifespans.
Automotive commands the steepest expansion trajectory; consumer electronics maintains the largest unit volumes.
Application:
Deployment environment determines packaging form factor, thermal management approach, and supply chain security requirements.
- Data Centers:Co-packaged optics and high-bandwidth memory integration dominate AI training accelerator designs for cloud service provider deployments. Microsoft and Meta reserve leading-edge capacity from TSMC Arizona for these workloads.
- Automotive Systems:Functional safety partitioning and redundant compute architectures for SAE Level 4 autonomy require fault-tolerant multi-core processors with lockstep execution. Mobileye and Waymo qualify these against ASIL-D standards.
- IoT Devices:Ultra-low-power sub-threshold designs extend battery life for industrial sensors and smart home endpoints with intermittent connectivity requirements.
- Smart Appliances:Motor control and connectivity integration in washing machines and HVAC systems demand cost-optimized microcontrollers with integrated wireless stacks.
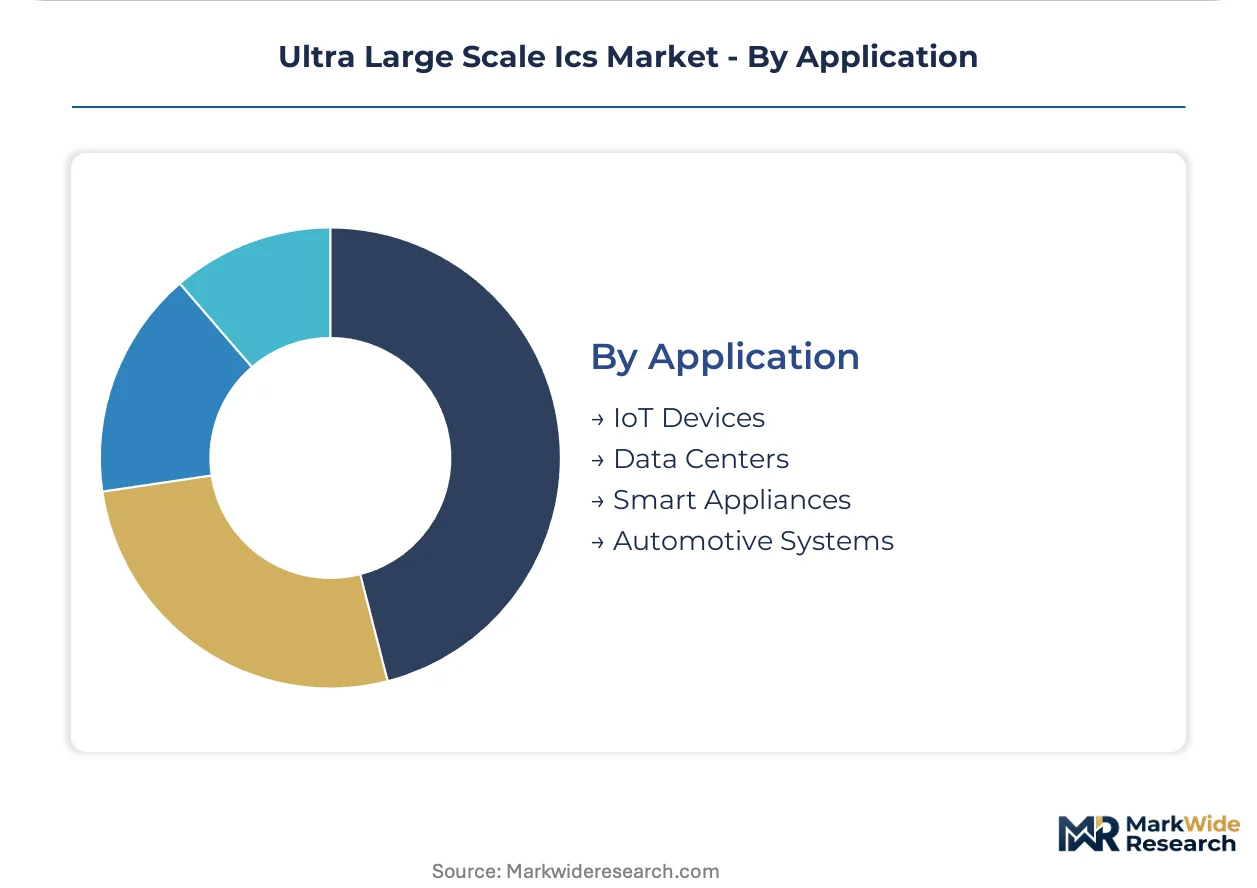
Data center procurement concentrates revenue; automotive systems gain share fastest with electrification and autonomy roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's most advanced logic fabrication, with TSMC's EUV clusters supplying Nvidia and Apple from Taiwan's northwest coast. Foundry capacity reservation contracts from hyperscalers are redrawing procurement geography across competing industrial policy regimes.
United States
Google, Meta, and Microsoft negotiate multi-year prepayments for leading-edge allocation at TSMC Arizona and Intel facilities in Ohio. The CHIPS Act conditions Department of Commerce subsidies on domestic fabrication expansion, redirecting capital toward Phoenix, Austin, and Columbus corridors.
South Korea
Samsung Foundry and SK Hynix integrate high-bandwidth memory with logic dies for AI training accelerators. The K-Semiconductor Belt clusters tax incentives with infrastructure buildout in Yongin and Pyeongtaek to capture next-generation memory-logic integration.
Germany
Bosch and Continental source Grade 0 automotive silicon from Infineon Dresden under ISO 26262 ASIL-D mandates. The EU AI Act's conformity assessment requirements are forcing traceable supply chain documentation for autonomous perception systems.
Japan
Tokyo Electron and Shin-Etsu Chemical supply EUV photoresists and silicon substrates from Kyoto and Utsunomiya clusters. METI subsidies target 2nm domestic pilot lines in Kagoshima to reduce import dependence for advanced logic.
India
Gujarat and Tamil Nadu attract assembly, test, and packaging investments through the PLI scheme and state-level infrastructure commitments. ISRO and defense procurement are creating captive demand for radiation-hardened designs at Bangalore design centers.
Ultra Large Scale Ics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where foundry economics determine entry barriers. The vendor base separates into three strategic archetypes: pure-play foundries owning EUV clusters, integrated device manufacturers with captive fabrication, and fabless designers relying on external capacity. Competitive moves concentrate on long-term capacity reservation contracts and heterogeneous packaging integration.
Among pure-play foundries, TSMC occupies the leading-edge position while Samsung Electronics exemplifies the memory-logic integrator archetype. Intel Corporation represents the integrated device manufacturer model attempting foundry service expansion. These three anchors demonstrate how capital intensity and ecosystem lock-in determine competitive positioning.
| Leading Market Players |
|---|
| Nvidia Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Samsung Electronics |
| NXP Semiconductors |
| Microchip Technology |
| TSMC |
| Broadcom |
| Qualcomm |
| Others |
Value Network & Pricing Analysis
Hyperscaler long-term capacity reservation contracts at TSMC and Samsung Foundry are compressing spot-market availability and forcing fabless designers toward premium prepayment structures that widen pricing spreads between anchored and unanchored buyers.
Pricing Analysis
Cost-down pressure on leading-edge wafers accelerates because hyperscalers negotiate multi-billion-dollar prepayments that displace legacy fabless customers in queue priority. Three-tier pricing structure across premium ASIC, mid-range FPGA, and economy microcontroller levels reflects certification grade and volume scale differentials. Automotive Grade 0 silicon under ISO 26262 ASIL-D mandates commands the least price sensitivity; consumer electronics SoCs face the most. Margin tightening in standard-node CMOS traces to foundry overcapacity in trailing-edge facilities.
Supply Chain Analysis
Regional distribution centers in Hsinchu, Yongin, and Phoenix operate hub-and-spoke patterns for EUV-exposed wafers and advanced packaging substrates. Supply concentrates in Taiwan, South Korea, and the United States for leading-edge logic; neon gas purification historically drew from Ukrainian and Russian facilities. Single-source vulnerability sits with ASML's annual high-NA lithography system output. Distribution runs through direct foundry-to-OEM channels for hyperscalers, with merchant distributors serving mid-tier fabless houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity assessment mandates erect a compliance moat that favors incumbent foundries with established audit trails and traceable supply chain documentation.
For Market Incumbents: Cement queue priority at EUV clusters through multi-year prepayment structures that lock in hyperscaler allocation. Defend against emerging packaging-centric integrators by deepening in-house 3D assembly capabilities in Arizona and Ohio. ISO 21434 cybersecurity certification investment represents the critical lever for automotive qualification expansion. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for audit-specialist service providers and traceability software vendors serving Tier 2 automotive suppliers. India's PLI scheme for assembly, test, and packaging offers the most penetrable geography for capital-light entry. A foundry partnership model with Gujarat-based packaging houses provides the essential go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors heterogeneous packaging integrators with Universal Chiplet Interconnect Express assembly expertise. Long-term viability hinges on 5-10 year capacity reservation visibility at leading-edge nodes. Watch hyperscaler capex guidance revisions as the inflection signal for foundry utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | TSMC Arizona and Intel Ohio facilities capture hyperscaler AI accelerator demand through CoWoS and EMIB integration. |
| EUV Cluster Geographic Diversification | Samsung Pyeongtaek and TSMC Kumamoto reduce concentration risk for Japanese automotive suppliers under METI subsidy programs. |
| Chiplet Standards Adoption | UCIe consortium membership enables AMD and Intel to source memory and I/O dies from independent process nodes. |
| Automotive Safety Certification Investment | Infineon Dresden and NXP Austin secure ASIL-D qualification for autonomous perception systems under EU AI Act traceability rules. |
| Neon Gas Supply Restructuring | Air Liquide and Linde expand non-Russian purification capacity to address Ukrainian supply fragility since 2022. |
Research Methodology
Independent corroboration across foundry operations executives, hyperscaler silicon procurement officers, and automotive Tier 1 supply chain directors underwrites the qualitative findings. Primary interviews with packaging engineering leads, EUV photoresist formulators, and regulatory compliance specialists at ECHA and FDA were cross-referenced against SEC 10-K filings, hyperscaler capex disclosures, and customs trade data. Bottom-up wafer start estimates and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical foundry utilization rates and capital expenditure cycles established the forecast baseline. The model segments by process node tier, packaging architecture, end-use certification grade, and geographic production cluster. CAGRs derive from regression against equipment installation timelines and node transition schedules. High-bandwidth memory attach rates and co-packaged optics yield assumptions feed the projection framework.
The model assumes a particular technology adoption path; alternative pathways for gate-all-around transistors at 2nm would alter the outlook. Forecasts reflect documented assumptions regarding EUV scanner delivery schedules, CHIPS Act subsidy disbursement timing, and export control licensing patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market