
 Touch Controller IC Market | 2026-2036
Touch Controller IC Market Size, Share, and Industry Trends Forecast 2026-2036
Touch Controller IC Market Outlook
Taiwan's semiconductor foundry expansion is narrowing the supply gap for advanced touch controller wafers. Texas Instruments Inc. leverages its analog portfolio to dominate industrial-grade controller segments. Synaptics Inc. sustains R&D intensity in automotive multi-touch architectures. FocalTech Systems Co. Ltd. anchors smartphone supply chains through geographic proximity to Shenzhen manufacturing corridors.
A touch controller IC is a mixed-signal integrated circuit that processes capacitive or resistive sensor arrays, converting analog touch inputs into digital coordinates with sampling rates typically exceeding 100 Hz for gesture recognition. These devices serve as the primary human-machine interface layer in displays, translating physical contact into system commands for processors. Capacitive controllers lead unit shipments due to smartphone and tablet saturation, while multi-touch technology captures expanding margin pools as automotive dashboards adopt pinch-to-zoom interfaces. Optical sensing remains a niche but grows in kiosks and public terminals where durability requirements exceed capacitive limits.
FCC certification mandates in the United States govern electromagnetic emissions from touch-enabled devices, while EU RoHS and REACH frameworks restrict hazardous substances in controller packaging and substrate materials. China's GB standards and MIIT regulations enforce electromagnetic compatibility thresholds for domestic electronics deployment. Stakeholders must monitor how automotive ISO 26262 functional-safety requirements migrate into touch controller validation protocols as human-machine interfaces assume critical vehicle control functions.
Market Dynamics
Automotive ISO 26262 functional-safety requirements are migrating into touch controller validation protocols as human-machine interfaces assume critical vehicle control functions, forcing suppliers to redesign architectures for fault tolerance and redundancy.
Growth Catalysts
- EU RoHS Compliance:Lead-free packaging transitions are accelerating across East Asian foundries as suppliers retool substrate materials to meet hazardous substance restrictions for European electronics exports.
- Samsung and LG Supply Chains:South Korea's display cluster concentrates procurement of advanced capacitive controllers for foldable smartphone and OLED panel production.
- Pinch-to-Zoom Interfaces:Automotive dashboards are adopting multi-touch architectures for navigation and climate control, expanding margin pools beyond consumer electronics.
Market Restraints
- Wafer Supply Concentration:Taiwan's semiconductor foundries control advanced touch controller substrate output, creating geographic single-point vulnerability for global procurement.
- Optical Sensing Substitution:Kiosks and public terminals are deploying infrared and camera-based alternatives where durability requirements exceed capacitive limits in high-abuse environments.
- FCC Certification Friction:United States electromagnetic emissions testing adds 8-14 weeks to product launch timelines for non-domestic suppliers.
Strategic Opportunities
- India BIS Standards:Domestic electronics deployment mandates under Compulsory Registration Order are creating localized demand for certified touch controller suppliers.
- Under-Display Integration:Foldable and rollable display form factors require new multi-layer controller architectures that merge fingerprint sensing with touch input.
- Direct Shenzhen Sourcing:Geographic proximity to manufacturing corridors is enabling controller vendors to bypass traditional distribution layers and contract directly with ODMs.
Industry Challenges
- Mixed-Signal Design Talent:Scarcity of engineers proficient in both analog sensor front-end and digital signal processing is constraining R&D velocity at mid-tier suppliers.
- Legacy Vehicle Integration:Automotive Tier 1 suppliers face complexity bridging ISO 26262-compliant touch interfaces with 10-15 year-old CAN bus architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch Controller IC Market |
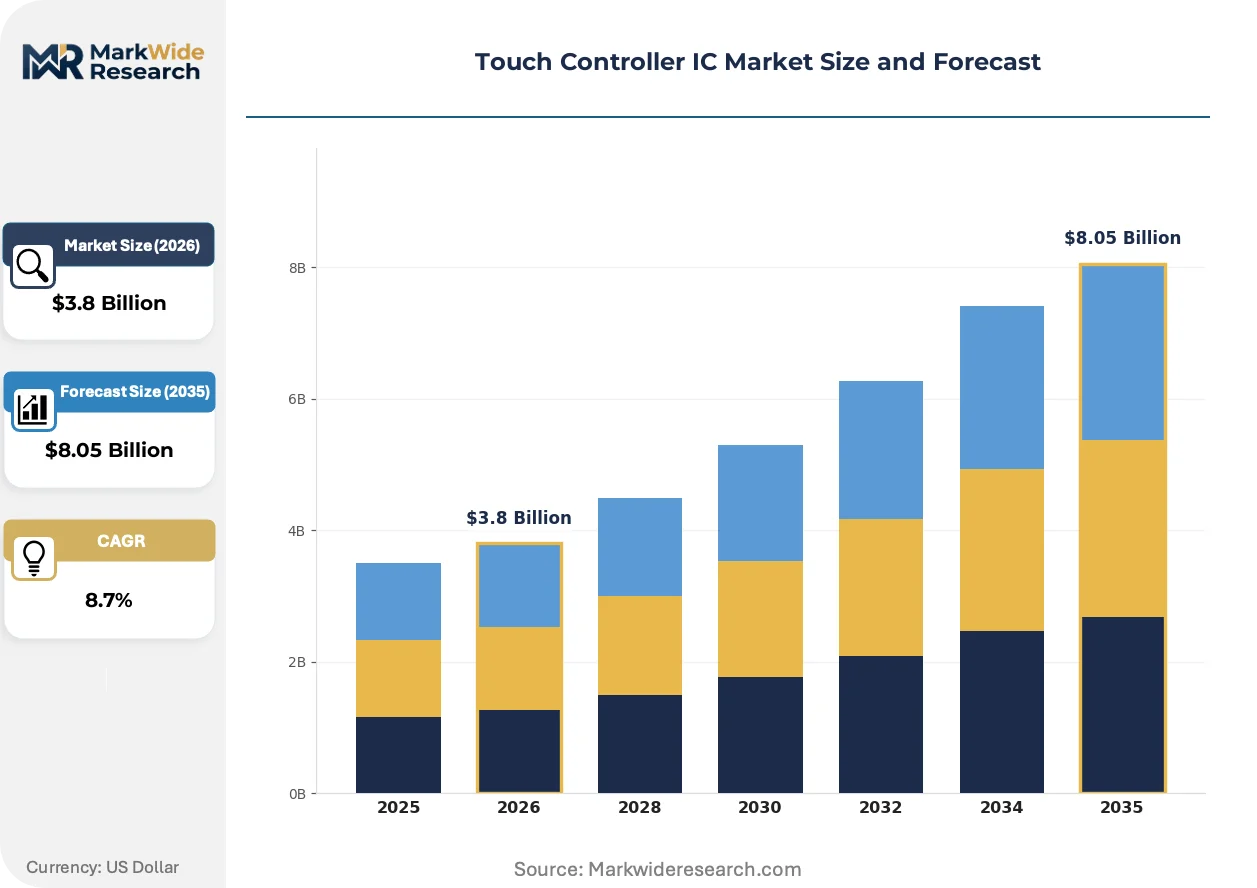
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Optical, Infrared Technology: Single-Touch, Multi-Touch, Gestural, Proximity End User: Consumer Electronics, Automotive, Industrial, Healthcare Application: Smartphones, Tablets, Laptops, Kiosks |
| Companies Covered | NXP Semiconductors N.V., FocalTech Systems Co. Ltd., Synaptics Inc., ROHM Semiconductors, STMicroelectronics, Texas Instruments Inc., Microchip Technology Inc., Melfas Inc., Analog Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch Controller IC Market Strategic Shifts
Touch controller architectures are bifurcating between ultra-low-power mobile designs and safety-critical automotive platforms, with sampling rate specifications diverging sharply across end-use verticals.
In-cell touch integration is digitizing display stack economics by embedding controller logic directly on TFT backplanes, eliminating discrete ICs and flex cables. Panel makers in South Korea and Taiwan are adopting this for premium smartphone lines. The technology is digitizing procurement patterns as display vendors capture value previously held by semiconductor suppliers.
China's MIIT electromagnetic compatibility thresholds are tightening test specifications for domestic electronics deployment, forcing foreign controller suppliers to establish local certification laboratories. The regulations are compressing product launch windows for non-compliant vendors. Automotive and industrial segments face the steepest compliance ramps.
Automotive OEMs are consolidating touch controller sourcing under single-supplier agreements for platform-level human-machine interface consistency, displacing the multi-vendor qualification models common in consumer electronics. Tier 1 integrators in Germany and Japan are driving this concentration. The shift is most visible in electric vehicle programs where touchscreen-centric cockpits dominate interior design.
Touch Controller IC Market Segmentation
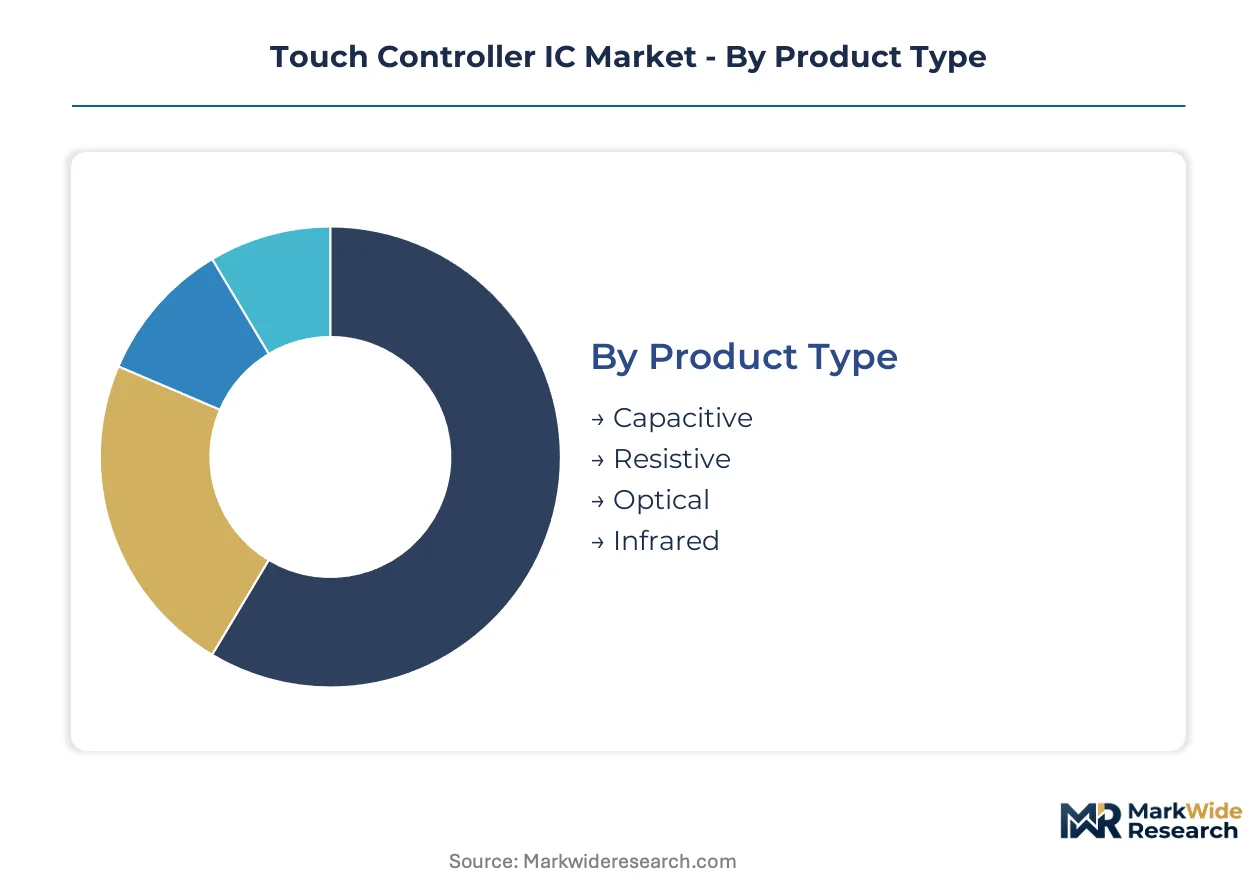
Touch controller IC architectures diverge sharply across end-use requirements, with sampling rates, power budgets, and safety certifications creating distinct procurement silos. Manufacturers configure product portfolios around these discontinuities rather than pursuing universal controller designs.
Product Type:
Cost tier differentiation separates premium capacitive solutions from legacy resistive alternatives and emerging optical architectures.
- Capacitive:These mixed-signal devices process projected or surface capacitance arrays with sub-millimeter positional accuracy. Samsung and LG procurement in South Korea concentrates demand for advanced controllers supporting OLED and foldable display stacks. EU RoHS lead-free packaging mandates are accelerating substrate material transitions among East Asian foundry suppliers.
- Resistive:Pressure-sensitive membrane stacks dominate industrial and legacy medical equipment where cost sensitivity exceeds gesture complexity requirements. Demand concentrates in China's Shenzhen manufacturing corridors for ruggedized handheld terminals and factory floor interfaces.
- Optical:Camera-based sensing architectures serve kiosks and public access terminals where surface durability requirements exceed capacitive limits.
- Infrared:IR grid systems deploy in outdoor digital signage and transportation ticketing interfaces exposed to environmental abuse.
Capacitive holds installed capacity. Optical is rotating up the share rankings.
Technology:
Application complexity tiers separate basic single-point detection from automotive-grade multi-touch architectures with functional-safety redundancy.
- Multi-Touch:Simultaneous contact point tracking enables pinch-to-zoom navigation and chorded gesture inputs. Automotive dashboards in Germany and Japan are adopting these interfaces for climate and infotainment control, expanding margin pools beyond consumer electronics saturation. ISO 26262 fault-tolerance requirements are forcing controller redesigns for redundancy and diagnostic coverage.
- Single-Touch:Binary contact detection suffices for elevator panels, industrial push-button replacements, and basic appliance interfaces. China's MIIT electromagnetic compatibility thresholds are tightening certification windows for these commodity controllers.
- Gestural:Three-dimensional motion tracking without surface contact supports hygiene-critical healthcare and food processing environments.
- Proximity:Near-field capacitive detection enables wake-on-approach power management in battery-constrained wearable devices.
Multi-Touch commands premium pricing. Gestural is climbing the fastest as post-pandemic hygiene protocols persist.
End User:
Customer type determines certification burden, with automotive and healthcare verticals imposing validation protocols that exclude consumer-grade suppliers.
- Automotive:Touch controllers in this segment must satisfy ISO 26262 ASIL ratings for human-machine interfaces controlling safety-critical vehicle functions. Tier 1 integrators in Germany and Japan are consolidating sourcing under single-supplier platform agreements, displacing multi-vendor qualification models common in consumer electronics. Electric vehicle programs with touchscreen-centric cockpits drive this concentration.
- Consumer Electronics:Smartphones and tablets saturate this segment with 100+ Hz sampling rate requirements for fluid gesture recognition. Taiwan's semiconductor foundries control advanced wafer supply, creating geographic single-point vulnerability.
- Industrial:Extended temperature ranges and electromagnetic immunity distinguish controllers for factory automation and process control.
- Healthcare:FDA and equivalent national regulators enforce biocompatibility and disinfection tolerance for clinical touch surfaces.
Consumer Electronics holds volume concentration. Automotive is gaining share fastest on safety-critical content expansion.
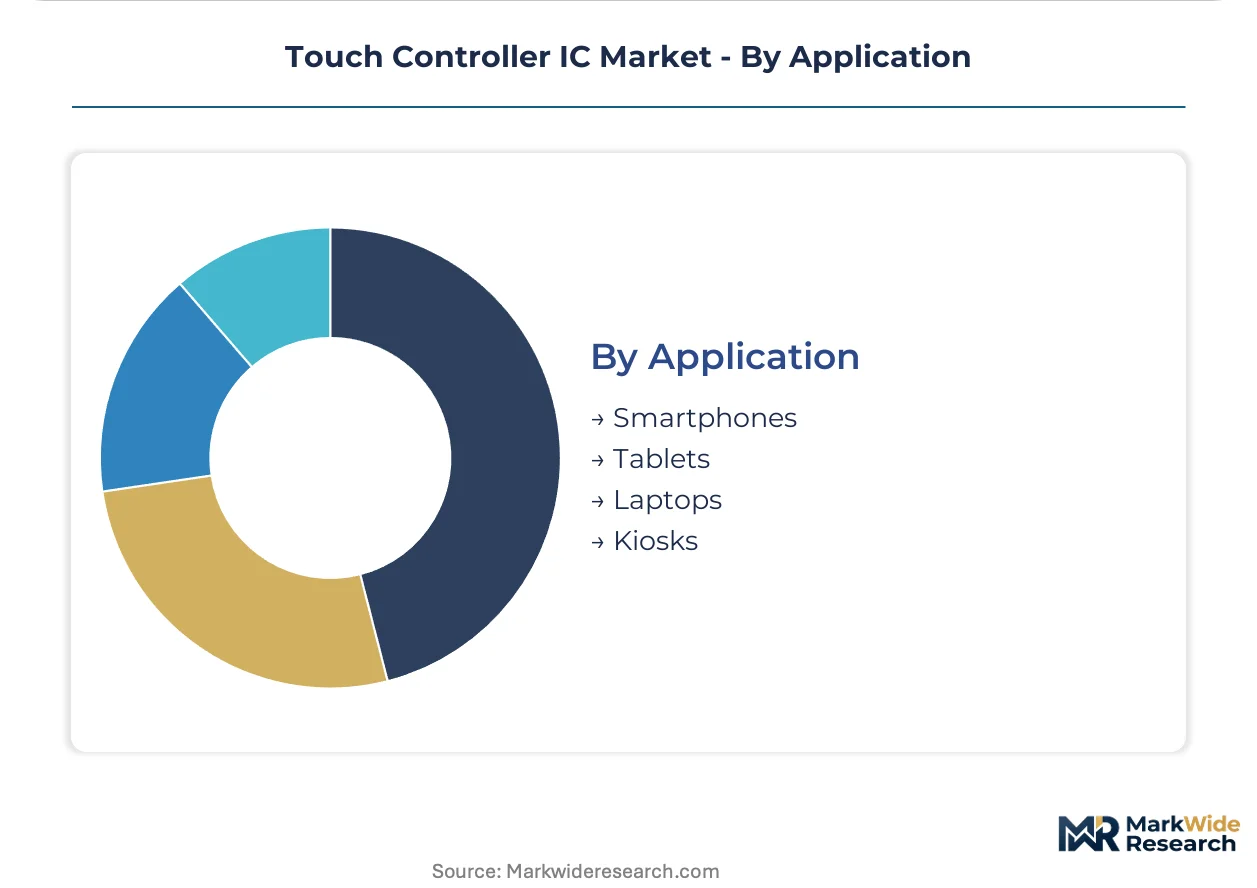
Application:
Volume scale separates billion-unit smartphone deployments from specialized kiosk and laptop configurations with divergent form factor constraints.
- Smartphones:In-cell touch integration embeds controller logic directly on TFT backplanes, eliminating discrete ICs and flex cables. South Korean and Taiwanese panel makers are capturing value previously held by semiconductor suppliers through this vertical integration. Foldable form factors require new multi-layer architectures merging fingerprint sensing with touch input.
- Kiosks:Public access terminals in airports, retail, and transit deploy optical and infrared alternatives where capacitive durability proves inadequate. India's BIS Compulsory Registration Order is creating localized demand for certified suppliers in this infrastructure-heavy segment.
- Tablets:Larger active areas strain signal-to-noise ratios and drive active pen integration requirements.
- Laptops:Precision touchpad specifications from Microsoft and platform vendors constrain controller selection for Windows-compatible systems.
Smartphones dominates unit economics. Kiosks is rotating up the share rankings on public infrastructure digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT electromagnetic compatibility thresholds anchor procurement decisions across East Asian supply chains. FCC certification timelines constrain United States market entry for non-domestic suppliers. EU RoHS lead-free mandates are accelerating substrate material transitions among foundry operators.
United States
Automotive OEMs in Detroit and Silicon Valley are consolidating touch controller sourcing under single-supplier platform agreements for electric vehicle cockpits. FCC electromagnetic emissions testing adds 8-14 weeks to product launch timelines for overseas suppliers. Texas-based analog semiconductor clusters supply industrial-grade controllers for factory automation and process control applications.
South Korea
Samsung and LG display clusters concentrate procurement of advanced capacitive controllers for foldable smartphone and OLED panel production. MFDS medical device regulations enforce biocompatibility standards for clinical touch surfaces in Seoul's healthcare technology corridor. Gyeonggi Province foundries are retooling substrate materials to meet EU RoHS hazardous substance restrictions.
China
Shenzhen manufacturing corridors drive demand for resistive controllers in ruggedized handheld terminals and factory floor interfaces. MIIT electromagnetic compatibility thresholds are tightening test specifications for domestic electronics deployment, forcing foreign suppliers to establish local certification laboratories. Yangtze River Delta panel makers are adopting in-cell touch integration for premium smartphone lines.
Taiwan
Semiconductor foundries control advanced touch controller wafer output, creating geographic single-point vulnerability for global procurement. The country's national electronics regulator enforces electromagnetic compatibility thresholds aligned with international standards. Hsinchu Science Park clusters supply 100+ Hz sampling rate controllers for fluid gesture recognition in consumer devices.
Germany
Automotive Tier 1 integrators in Stuttgart and Munich are driving ISO 26262 functional-safety requirements into touch controller validation protocols. KBA vehicle certification mandates govern electromagnetic emissions from touch-enabled automotive systems. Bavarian industrial automation clusters procure extended temperature range controllers for factory floor deployment.
Touch Controller IC Market Competitive Environment
Broad-based diversified semiconductor suppliers and specialized touch controller architects split the market along capability lines. The vendor base organizes into three tiers: analog-centric portfolio players with industrial-grade certification depth, fabless designers focused on mobile multi-touch integration, and display-vertically-integrated panel makers capturing value through in-cell architectures. Competitive moves center on strategic partnerships for automotive qualification and geographic expansion into India BIS-certified supply chains.
Within the diversified analog tier, Texas Instruments Inc. and Analog Devices Inc. represent established positions in industrial and automotive segments where extended temperature ranges and electromagnetic immunity distinguish procurement decisions. Synaptics Inc. exemplifies the fabless specialization archetype, occupying a position in automotive multi-touch architectures where ISO 26262 fault-tolerance requirements force controller redesigns. FocalTech Systems Co. Ltd. anchors smartphone supply chain proximity through geographic positioning near Shenzhen manufacturing corridors, enabling direct ODM contracting that bypasses traditional distribution layers.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| FocalTech Systems Co. Ltd. |
| Synaptics Inc. |
| ROHM Semiconductors |
| STMicroelectronics |
| Texas Instruments Inc. |
| Microchip Technology Inc. |
| Melfas Inc. |
| Analog Devices Inc. |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry overcapacity in mature-node wafer production is compressing input costs for mid-tier touch controller suppliers while concentrating pricing power among advanced-node operators serving automotive ISO 26262 certification tiers. This utilization bifurcation is reshaping supplier behavior, with cost-pass-through mechanisms diverging sharply across consumer and safety-critical segments.
Pricing Analysis
East Asian procurement premiums for automotive-grade controllers exceed consumer electronics pricing by multiples reflecting certification burden and fault-tolerance redundancy. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-tier controllers separates ISO 26262 ASIL-rated devices from extended-temperature industrial variants and commodity smartphone ICs. Pricing pressure stems from in-cell touch integration by South Korean and Taiwanese panel makers, which eliminates discrete controller value capture in premium smartphone stacks. Automotive OEMs exhibit lowest price sensitivity due to platform-level sourcing consolidation, while Shenzhen ODMs driving consumer electronics procurement maximize volume leverage.
Supply Chain Analysis
Extended payment terms from automotive Tier 1 integrators in Germany and Japan are forcing fabless controller designers to access supply-chain finance facilities for wafer procurement liquidity. Taiwan, South Korea, and China anchor global touch controller substrate output, with Taiwan's foundries controlling advanced-node capacity for high-sampling-rate architectures. Silicon wafers, specialty packaging substrates, and analog front-end IP constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's Hsinchu Science Park cluster, where geographic disruption would cascade through automotive and consumer electronics procurement simultaneously. Distribution runs through authorized component distributors for industrial and automotive qualification, while direct Shenzhen contracting dominates high-volume smartphone supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity in mixed-signal design—combining analog sensor front-end expertise with digital signal processing capability—is constraining R&D velocity and creating acquisition premiums for teams with automotive functional-safety experience. This capability gap is reshaping competitive dynamics across all tiers.
For Market Incumbents: Pre-empt optical sensing substitution in kiosk and public terminal segments by acquiring infrared grid specialists before infrastructure digitization accelerates. Secure captive wafer allocation through foundry partnership investments in Taiwan and South Korea, insulating against geographic single-point vulnerability while automotive ISO 26262 content expansion commands premium positioning. For New Entrants and Emerging Players: India's BIS Compulsory Registration Order compliance gap represents the most penetrable entry point, as established suppliers lag in local certification laboratory establishment. Under-display controller architectures for foldable displays offer white-space opportunity before South Korean panel makers complete vertical integration. Pursue direct ODM contracting relationships in Shenzhen manufacturing corridors to bypass entrenched distribution layers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-qualified controller suppliers with platform-level single-source agreements, generating visibility through electric vehicle program lifecycles. Long-term viability favors acquisition targets combining ISO 26262 certification depth with in-cell touch integration partnerships. Monitor automotive OEM cockpit consolidation announcements as inflection indicators for supplier concentration trends.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional-Safety Certification Investment | ISO 26262 ASIL-rated controller architectures unlock single-source platform agreements with German and Japanese Tier 1 integrators. |
| Foundry Partnership for Advanced-Node Capacity | Taiwanese foundry alliances secure wafer allocation for 100+ Hz sampling rate controllers serving foldable display stacks. |
| In-Cell Touch Integration Development | Embedding controller logic on TFT backplanes captures value from discrete IC suppliers in South Korean and Taiwanese panel ecosystems. |
| India BIS Certification Laboratory Establishment | Local compliance infrastructure addresses Compulsory Registration Order mandates for kiosk and infrastructure deployment segments. |
| Optical Sensing Architecture Acquisition | Infrared grid capabilities counter capacitive durability limitations in airport, retail, and transit public access terminals. |
Study Parameters
Cross-validation between primary fieldwork with touch controller design engineers and secondary analysis of MIIT electromagnetic compatibility filings anchors the qualitative findings in documented regulatory pathways. Semiconductor device physicists, automotive HMI platform architects, Shenzhen ODM procurement directors, and foundry capacity planners provided operational perspectives. SEC 10-K semiconductor segment disclosures, Taiwan's national technology regulator electromagnetic compatibility databases, EU RoHS substance restriction enforcement records, and automotive OEM supplier qualification documents furnished secondary validation. Bottom-up unit shipment estimates from application-level bill-of-materials analysis triangulate against top-down semiconductor industry revenue assessments.
Calibration against historical capacity utilization patterns and foundry expansion announcements shapes the projection framework across the analysis window. Segmentation dimensions include controller technology tier, end-use vertical certification burden, and geographic regulatory cluster. CAGRs derive from regression analysis of shipment growth rates against display panel production forecasts and automotive touchscreen content trajectories. Foldable display adoption curves and electric vehicle HMI penetration serve as industry-specific demand drivers in the quantitative model.
Practitioners should monitor automotive OEM single-source consolidation announcements, Taiwan foundry utilization inflections, and India BIS enforcement ramp intensity for early signals of structural shift. Forecasts reflect assumptions regarding sustained automotive electrification, continued in-cell touch integration by panel makers, and stable electromagnetic compatibility regulatory frameworks. Macroeconomic contraction in consumer electronics, foundry geographic disruption, or accelerated optical sensing substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market