
 Compressed Natural Gas (CNG) Dispenser Market | 2026-2036
Compressed Natural Gas (CNG) Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Natural Gas (CNG) Dispenser Market Outlook
China's manufacturing corridor expansion is reshaping component sourcing for CNG dispenser assemblies. Tatsuno Corporation leverages its precision metering heritage to dominate high-flow dispensing systems for heavy-duty transport. Bennett Pump Company anchors North American aftermarket service networks through extensive distributor relationships. Kraus Global specializes in cold-climate dispensing solutions, sustaining operational reliability across Canadian prairie provinces.
A compressed natural gas dispenser is a pressure-rated fueling terminal engineered to meter and transfer natural gas compressed to 3,000–3,600 psi into vehicle storage cylinders, incorporating mass flow sensors, solenoid valves, and electronic control systems to ensure accurate custody transfer and safe operation. Fast fill dispenser configurations command premium positioning due to their integration with high-pressure cascade storage systems that enable rapid vehicle turnover comparable to liquid fueling. Fleet operators represent the fastest-growing end user segment as logistics companies convert medium- and heavy-duty truck operations to compressed natural gas to manage volatile diesel cost exposure.
The US Department of Transportation's NHTSA and EPA jointly enforce vehicle and fueling equipment safety standards that dictate dispenser design, pressure testing protocols, and emission compliance pathways for alternative fuel infrastructure. India's Petroleum and Natural Gas Regulatory Board mandates city gas distribution licensing that directly determines CNG station rollout density and dispenser procurement schedules across licensed geographical areas. Stakeholders must monitor evolving hydrogen blending regulations in natural gas grids, as pipeline gas composition shifts will require recalibration of flow measurement algorithms and material compatibility standards in next-generation dispensing equipment.
Market Dynamics
Fast-fill dispenser architectures are compressing refueling dwell times to diesel-comparable intervals, eliminating the historical throughput penalty that constrained fleet conversion economics. This technical leap is restructuring procurement criteria across municipal transit authorities and long-haul logistics operators.
Growth Catalysts
- India's City Gas Distribution Mandates:The Petroleum and Natural Gas Regulatory Board's geographical licensing regime is binding station rollout density to urban expansion plans. Fleet procurement schedules now synchronize with pipeline completion timelines.
- Heavy-Duty Transport Electrification Gaps:Battery energy density limitations in long-haul trucking are preserving CNG's cost advantage for 500+ kilometer routes. Regional freight corridors in Maharashtra and Gujarat are prioritizing CNG infrastructure over depot-charging networks.
- Mass Flow Metering Accuracy Gains:Coriolis sensor integration is reducing custody transfer disputes below 0.5% variance thresholds. Fuel retailers are retrofitting legacy volumetric systems to retain fleet contracts.
Market Restraints
- Cascade Storage Steel Cost Volatility:High-pressure vessel fabrication depends on chromium-molybdenum alloy plate pricing. Foundry capacity concentration in East Asia creates input cost transmission lags.
- Pipeline Compressor Station Bottlenecks:CNG dispenser throughput depends on upstream compression availability. Distribution network expansion in secondary Indian cities is outpacing mother station commissioning.
- Electric Truck Battery Chemistry Advances:Solid-state cell prototypes are threatening CNG's total cost of ownership advantage in medium-duty urban delivery. Fleet operators are delaying multi-year CNG commitments pending 2027-2028 battery roadmaps.
Strategic Opportunities
- Hydrogen Blending Infrastructure Pivot:Pipeline operators in Germany and the Netherlands are testing 20% hydrogen admixture. Next-generation dispensers capable of flow algorithm recalibration will capture retrofit demand.
- Remote Mining Site Deployment:Off-grid CNG compression skids are displacing diesel generators in Australian and Canadian extraction operations. Modular dispenser units with integrated storage are penetrating fly-in-fly-out workforce logistics.
- EU Alternative Fuels Infrastructure Regulation:AFIR mandates are binding member states to corridor-based refueling coverage. Tender specifications are favoring dual-fuel capable dispensing systems.
Industry Challenges
- High-Pressure Systems Certification Timelines:ASME BPVC and ISO 19880-1 conformity assessment cycles are extending 14-18 months. Manufacturers are pre-certifying component families to compress delivery windows.
- Legacy SCADA Integration Complexity:Fleet management platforms require real-time dispenser telemetry. Retrofitting 1990s-era station automation layers is consuming 30-40% of project engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Natural Gas (CNG) Dispenser Market |
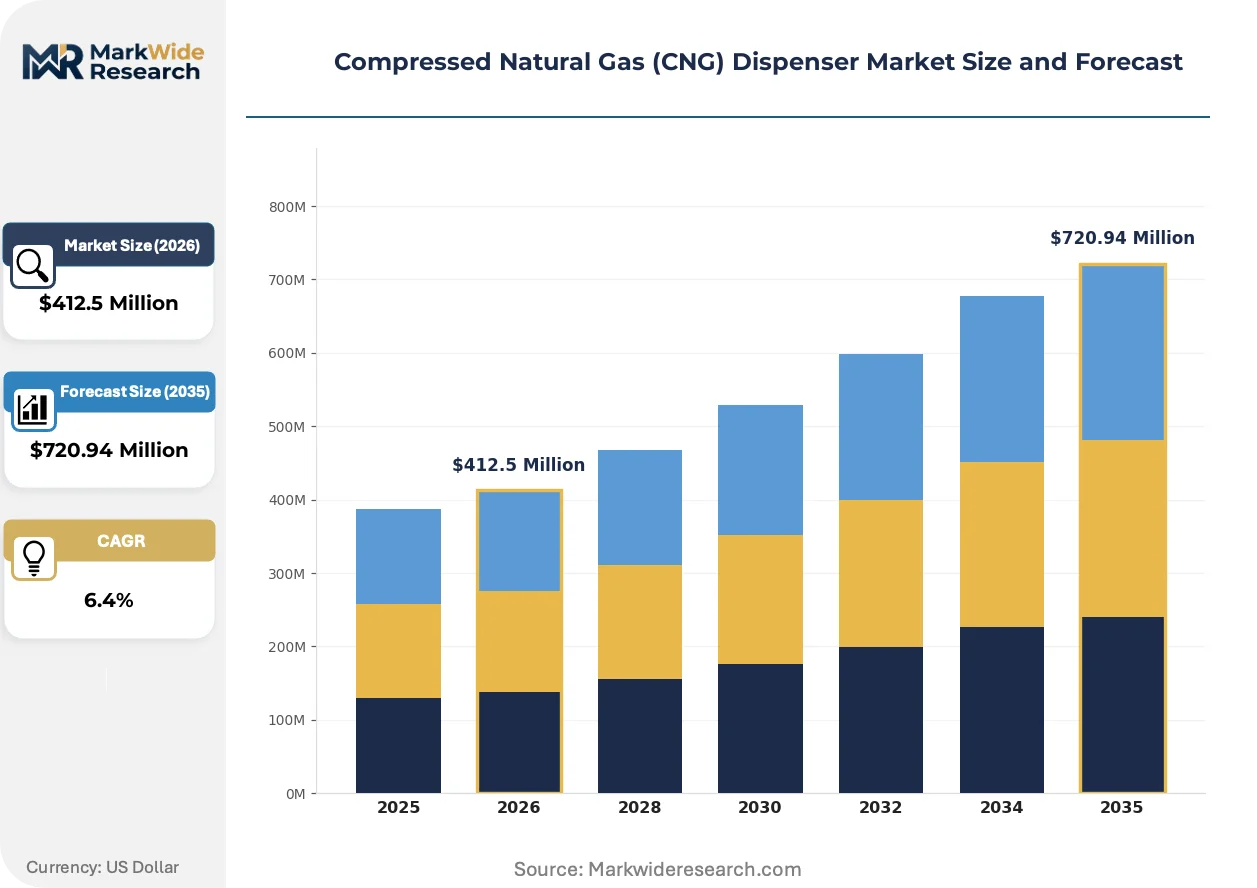
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispenser, Electric Dispenser, Dual Dispenser, Fast Fill Dispenser Installation Type: On-site Installation, Off-site Installation, Wall Mounted, Pole Mounted End User: Fleet Operators, Gas Stations, Municipalities, Industrial Users Technology: Rotary Vane, Diaphragm, Electronic Control, Pressure Regulation |
| Companies Covered | Gilbarco Veeder Root, Tatsuno Corporation, Scheidt & Bachmann, Kraus Global, Bennett Pump Company, Parker Hannifin, WEH GmbH, FTI International Group, Censtar Science & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Natural Gas (CNG) Dispenser Market Strategic Shifts
Dispenser architecture is converging with hydrogen-ready design specifications, compressing product development cycles and forcing material compatibility decisions years ahead of regulatory mandates. Component suppliers are re-engineering sealing systems and flow paths for dual-fuel certification.
Coriolis mass flow meters are replacing differential pressure sensors in custody transfer applications. European fuel retailers are mandating meter-type specifications in new station tenders. This metrology shift is rendering obsolete legacy volumetric calibration protocols that required temperature-pressure compensation algorithms.
The US Department of Transportation's NHTSA and EPA are tightening vehicle and fueling equipment safety testing protocols. Station operators must now document pressure-cycle fatigue testing for dispenser hose assemblies. Heavy-duty fleet segments in California and Texas are absorbing compliance costs through extended service contract pricing.
Fleet procurement teams are unbundling dispenser hardware from long-term maintenance agreements. Municipal transit authorities in India and Brazil are separating capital expenditure from operational service budgets. This contracting fragmentation is compressing equipment vendor margins while expanding third-party service provider addressable markets.
Compressed Natural Gas (CNG) Dispenser Market Segmentation
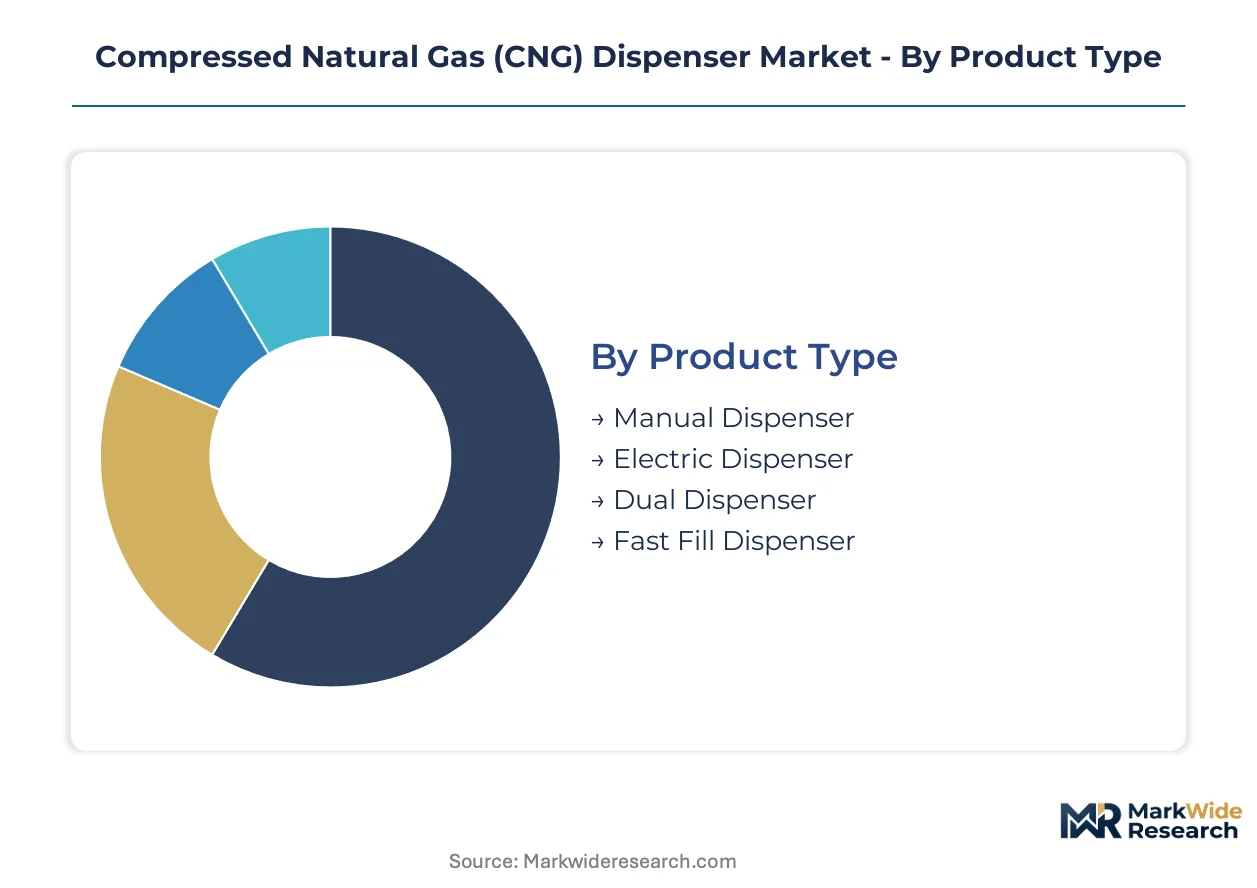
Segmentation in the CNG dispenser market reveals distinct service intensity profiles across installation configurations and end-user relationships. Fleet operators demand predictive maintenance contracts spanning compressor skids and dispensing terminals, while municipal procurement separates capital equipment from multi-year service agreements.
Product Type:
After-sales service intensity varies sharply across dispenser architectures, with high-flow systems requiring cascade storage integration support and electronic control modules demanding firmware update subscriptions.
- Fast Fill Dispenser:High-pressure dispensing terminals engineered for 3,000–3,600 psi transfer rates with integrated cascade storage synchronization. Demand concentrates among long-haul fleet operators in Maharashtra and Gujarat where diesel-comparable dwell times justify premium procurement. Service contracts typically bundle compressor maintenance with dispenser calibration.
- Electric Dispenser:Solenoid-actuated systems with programmable flow control and automated shutoff protocols. Municipal transit authorities in India favor these units for their SCADA integration capabilities and remote diagnostic accessibility.
- Manual Dispenser:Lever-operated mechanical systems with minimal electronic components; common in remote mining sites and off-grid industrial installations where technician availability is constrained.
- Dual Dispenser:Configurations supporting simultaneous vehicle fueling through parallel flow paths; deployed at high-throughput corridor stations along freight routes.
Fast fill dispenser configurations hold the largest share; momentum sits with electric dispenser architectures as fleet operators prioritize telemetry integration.
Installation Type:
Installation topology directly shapes procurement bundling, with on-site deployments absorbing civil engineering costs separately from equipment purchase while wall-mounted systems compress project timelines in dense urban environments.
- On-site Installation:Ground-mounted dispenser islands with integrated electrical and pneumatic infrastructure; standard for new station construction where footprint constraints are minimal.
- Wall Mounted:Space-constrained configurations attaching directly to station superstructures; prevalent in legacy fuel retail conversions where forecourt geometry limits island placement.
- Off-site Installation:Modular skid-mounted systems pre-assembled at manufacturing facilities; Australian and Canadian remote mining operations favor these for fly-in-fly-out deployment logistics.
- Pole Mounted:Elevated dispensing terminals minimizing ground-level footprint; emerging in dense Indian urban markets where Petroleum and Natural Gas Regulatory Board licensing restricts station size.
On-site installation dominates current procurement volumes; wall mounted configurations are climbing the fastest as urban station retrofits accelerate.
End User:
End-user category determines contract structure fragmentation, with fleet operators unbundling hardware from service agreements while gas stations pursue turnkey procurement with extended warranty coverage.
- Fleet Operators:Logistics companies and transit authorities managing captive vehicle populations; these buyers negotiate volume-based maintenance schedules and demand real-time fueling data integration with fleet management platforms.
- Gas Stations:Independent fuel retailers and oil marketing company franchises; procurement emphasizes rapid deployment and minimal operational training requirements for attendant staff.
- Municipalities:City transit departments and public works agencies; budget separation between capital and operating expenditures drives distinct RFP structures for equipment versus service provision.
- Industrial Users:Manufacturing facilities and extraction operations with captive CNG demand; these installations often integrate dispensing with on-site compression and prioritize uptime guarantees over unit economics.
Fleet operators command the steepest expansion trajectory; municipalities represent the most fragmented procurement landscape with divergent technical specifications across jurisdictions.
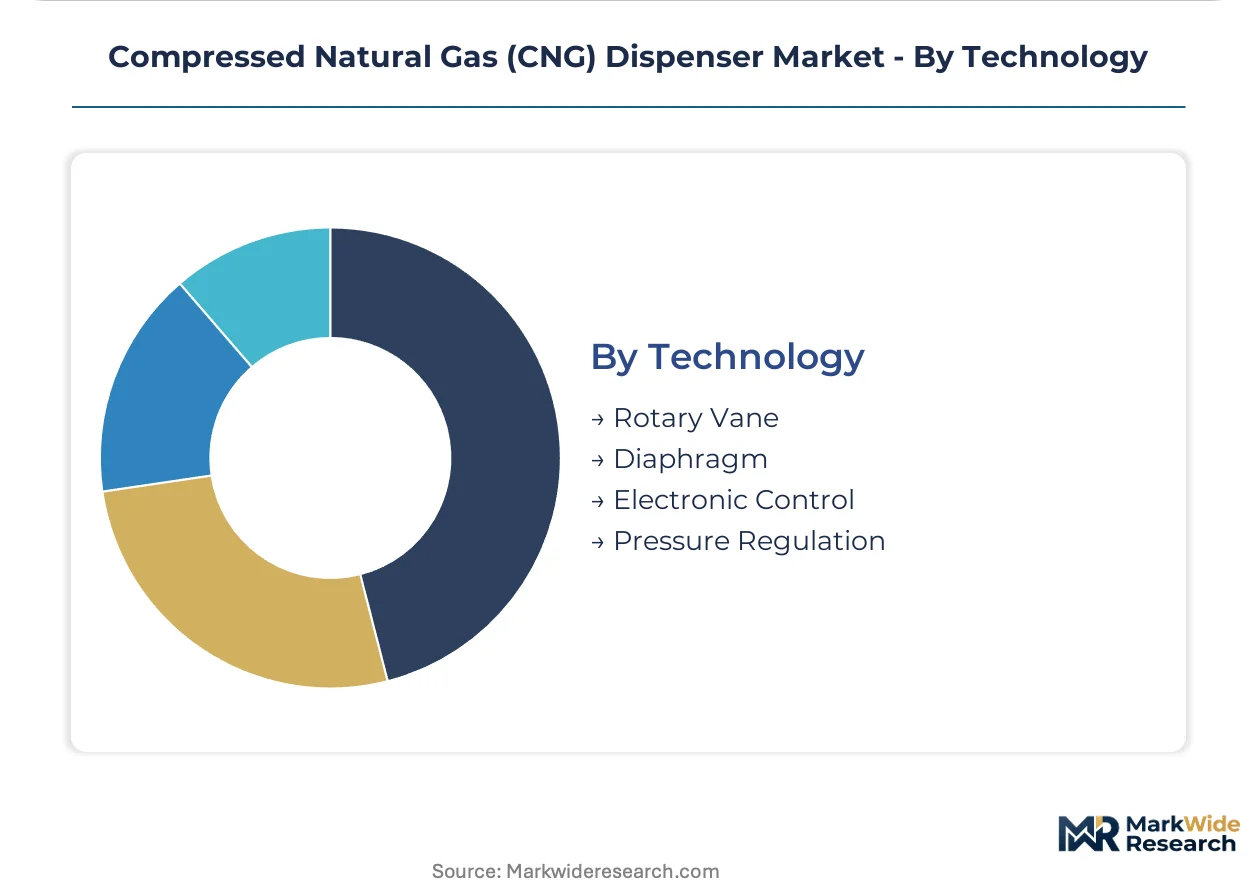
Technology:
Technology selection governs metrology accuracy and regulatory compliance pathways, with electronic control systems enabling Coriolis mass flow integration while mechanical alternatives persist in cost-sensitive deployments.
- Electronic Control:Microprocessor-governed dispensing with automated pressure sequencing and transaction logging; European fuel retailers mandate this technology in new station tenders to support custody transfer accuracy below 0.5% variance thresholds.
- Pressure Regulation:Multi-stage pressure reduction systems managing cascade storage depletion curves; critical for fast-fill applications where vehicle cylinder filling rates must optimize without thermal excursion.
- Rotary Vane:Positive displacement mechanical compression technology; limited to legacy installations and low-throughput applications where electronic system costs are prohibitive.
- Diaphragm:Sealed compression chambers eliminating lubricant contamination; deployed in food-grade and pharmaceutical logistics where gas purity specifications are stringent.
Electronic control systems hold the largest share; pressure regulation modules are gaining share fastest as cascade storage integration becomes standard for fleet-oriented installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for high-pressure dispensing systems clusters in East Asian foundries and North American precision manufacturing corridors. Pipeline network completion schedules in emerging economies are synchronizing procurement waves with regulatory licensing milestones.
United States
Long-haul freight operators along the Texas-California corridor are absorbing NHTSA-mandated pressure-cycle testing costs through extended service contracts. The EPA's emission compliance pathways for alternative fuel infrastructure are dictating dispenser design specifications for California Air Resources Board jurisdictions. Heavy-duty fleet conversion programs in the Permian Basin are prioritizing fast-fill architectures over depot-charging networks for 500-plus kilometer routes.
India
Maharashtra and Gujarat state transit authorities are expanding CNG refueling infrastructure under Petroleum and Natural Gas Regulatory Board city gas distribution mandates. The licensing regime binds station rollout density to urban expansion plans in secondary cities. Fleet procurement schedules in Mumbai and Ahmedabad now synchronize with compressed natural gas pipeline completion timelines.
Germany
Pipeline operators are testing 20 percent hydrogen admixture in natural gas grids, requiring recalibration of flow measurement algorithms in next-generation dispensing equipment. The EU Alternative Fuels Infrastructure Regulation binds member states to corridor-based refueling coverage specifications. Tender specifications in Bavaria and North Rhine-Westphalia are favoring dual-fuel capable dispensing systems.
China
Manufacturing corridor expansion in the Yangtze River Delta is reshaping component sourcing for CNG dispenser assemblies. MIIT industrial standards are governing pressure-rated vessel fabrication protocols for domestic and export markets. Precision metering heritage in Jiangsu and Zhejiang provinces is concentrating high-flow dispensing system production for heavy-duty transport applications.
Canada
Cold-climate dispensing solutions are sustaining operational reliability across Alberta and Saskatchewan prairie provinces where thermal excursion management is critical. Provincial regulators are aligning with CSA Group standards for high-pressure fueling equipment certification. Remote mining operations in the Athabasca oil sands are deploying modular skid-mounted systems with integrated compression for fly-in-fly-out workforce logistics.
Compressed Natural Gas (CNG) Dispenser Market Competitive Environment
Precision-metering specialists and integrated fueling-system conglomerates split the market across premium and volume-tier procurement channels. The vendor base organizes around three strategic archetypes: precision-component fabricators with metrology heritage, diversified industrial conglomerates with cross-fuel platform capabilities, and regional system integrators with localized service networks. Consolidation pressure is mounting through backward integration into high-pressure vessel fabrication and technology licensing agreements for hydrogen-ready design specifications.
Within the precision-metering tier, Tatsuno Corporation and WEH GmbH exemplify component-level specialization that anchors high-flow dispensing architectures. Bennett Pump Company and Kraus Global occupy positions in the integrated-systems segment, with the former representing North American aftermarket service network density and the latter exemplifying cold-climate operational reliability engineering. Gilbarco Veeder Root sits within the diversified conglomerate archetype, leveraging cross-platform fueling infrastructure capabilities spanning conventional and alternative fuel dispensers.
| Leading Market Players |
|---|
| Gilbarco Veeder Root |
| Tatsuno Corporation |
| Scheidt & Bachmann |
| Kraus Global |
| Bennett Pump Company |
| Parker Hannifin |
| WEH GmbH |
| FTI International Group |
| Censtar Science & Technology |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian high-pressure vessel foundries is compressing supplier pricing power and forcing tier-1 dispenser manufacturers toward captive fabrication investments. Utilization rates below 70 percent in Jiangsu and Zhejiang province steel-forging facilities are transmitting downstream through cascade storage cost curves, while procurement teams at Indian fleet operators exploit this softness to renegotiate long-term maintenance bundles.
Pricing Analysis
India's Petroleum and Natural Gas Regulatory Board city gas distribution mandates dictate the pricing tier structure across licensed geographical areas. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified fast-fill systems from CE-marked electric dispensers and unbundled manual configurations. Cost compression in standard-tier equipment is intensifying because chromium-molybdenum alloy plate volatility is squeezing foundry margins. Municipal transit authorities in Maharashtra exhibit highest price sensitivity due to capital-operating budget separation, while Permian Basin fleet operators absorb premium pricing for integrated telemetry.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta precision-machining clusters and North American pressure-vessel fabricators. Geographic supply concentration centers on China for electronic control modules, Germany for Coriolis mass flow sensors, and India for solenoid valve assemblies. Raw material dependencies draw from chromium-molybdenum alloy plate, high-grade aluminum castings, and semiconductor-grade pressure transducers. Single-source vulnerability in cascade storage steel creates structural risk. Distribution runs through OEM-direct channels for fleet operators and regional distributor networks for independent gas stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CNG dispenser market is approaching a platform-economics inflection where hydrogen-ready design specifications will determine vendor survival. Interoperability with blended hydrogen-natural gas grids is restructuring procurement criteria years ahead of regulatory mandates.
For Market Incumbents: Build certification moats around dual-fuel dispensing architectures capable of 20 percent hydrogen admixture flow algorithm recalibration. Secure backward integration into high-pressure vessel fabrication to defend against East Asian foundry volatility. Anchor aftermarket service density through predictive maintenance subscriptions that lock fleet operators into multi-year telemetry contracts. For New Entrants and Emerging Players: Remote mining operations in Canadian prairie provinces and Australian extraction corridors represent the most penetrable entry point for modular skid-mounted dispensing systems with integrated compression. Target fly-in-fly-out workforce logistics where technician availability constraints favor simplified mechanical architectures. Penetrate through equipment-as-a-service contracting that unbundles capital expenditure from operational budgets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-metering specialists with firmware update subscription models and long-term calibration service agreements. Five-to-ten year viability favors vendors with hydrogen-ready component families already submitted for ISO 19880-1 pre-certification. Watch for ASME BPVC conformity assessment cycle compression as the inflection signal indicating which manufacturers can deliver within 12-month windows.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Design Certification | ISO 19880-1 pre-certification compresses delivery windows for EU Alternative Fuels Infrastructure Regulation tenders. |
| Backward Integration into Vessel Fabrication | Captive chromium-molybdenum alloy plate sourcing insulates margin from East Asian foundry volatility. |
| Telemetry Platform Integration | Real-time dispenser SCADA connectivity secures fleet operator contracts against electrification delays. |
| Modular Skid-Mounted System Development | Pre-assembled off-site installations penetrate remote mining logistics in Athabasca and Pilbara regions. |
| Coriolis Mass Flow Retrofit Programs | Legacy volumetric system upgrades retain European fuel retailer contracts below 0.5 percent variance thresholds. |
Study Parameters
Initial hypotheses were tested against primary input from fleet procurement directors, station automation engineers, petroleum and natural gas regulatory board licensing officers, and high-pressure vessel fabrication plant managers and refined through secondary validation. Primary interviews combined with regulatory filing analysis from India's Petroleum and Natural Gas Regulatory Board, US Department of Transportation NHTSA safety protocols, EU Alternative Fuels Infrastructure Regulation documentation, and MIIT industrial standards from China. Bottom-up and top-down triangulation cross-checked dispenser unit economics against pipeline network completion schedules.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include dispenser architecture type, installation topology, end-user procurement structure, and regional regulatory cluster. CAGRs were derived through S-curve adoption modeling calibrated to city gas distribution licensing waves. Industry-specific forecast inputs incorporated mother station commissioning timelines and hydrogen blending test results from German and Dutch pipeline operators.
Practitioners should monitor solid-state battery chemistry roadmaps and hydrogen grid blending mandates for early signals of CNG demand displacement or infrastructure pivot requirements. Forecasts reflect assumptions about cascade storage steel cost stabilization and ASME certification timeline compression. Quarterly review of electric truck deployment data and EU member state AFIR corridor tender specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas Pooling Mechanism Market
Fuels
Coal Briquette Box Market
Fuels
Renewable Heating Fuels Market
Fuels
Coal Gasification Market
Fuels
Canada Bunker Fuel Market
Fuels
Gasoline Market
Fuels
Oil Dispensing Stations Market
Fuels
Emulsified Fuel Market
Fuels
Aviation Fuel Market
Fuels
Tire Derived Fuel Market
Fuels
Global Methane Hydrate Market
Fuels
LPG Gas Cylinder Market
Fuels
UAE Chemical Logistics Market
Fuels
Oil Dispenser Market
Fuels
United States Bunker Fuel Market
Fuels
High-Temperature Industrial Burner Market