
 Coal Briquette Box Market | 2026-2036
Coal Briquette Box Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Briquette Box Market Analytics
Commercial food vendors and street-side grill operators is rotating toward pre-packaged briquette boxes as their primary procurement format, displacing loose bulk purchases that dominated historically. Kingsford Products Company leverages its brand strength and retail shelf presence to anchor the North American channel. Gryfskand sp. z o.o. specializes in European-format compressed fuel packaging with moisture-resistant barrier specifications. Coal India Limited dominates domestic distribution through its captive logistics network, extending reach into tier-two Indian cities where commercial demand concentrates.
A coal briquette box is a rigid or semi-rigid container engineered to house compressed coal dust, charcoal fines, or blended fuel briquettes, typically incorporating moisture barriers, ventilation perforations, and stacking flanges to preserve calorific value during storage and transit. The box serves industrial boilers, commercial food preparation, and residential heating by enabling standardized unit dosing, reducing spillage, and simplifying inventory management for fuel distributors. Premium Box and Eco-Friendly Box categories are capturing margin pools as sustainability-conscious buyers in Western Europe and North America shift toward recycled-content and plastic-free packaging formats. Standard Box configurations in cardboard and composite materials still occupy the volume base across emerging Asian markets where unit economics favor minimal packaging cost.
India's BIS and CDSCO frameworks govern labeling integrity and combustible material handling standards for packaged fuel containers, while the EU REACH and F-Gas Regulation indirectly shape box material specifications through chemical restriction mandates on coatings and adhesives. China's SAMR enforces GB standards for transport packaging of solid fuels, requiring burst strength and stacking load certifications that box manufacturers must satisfy for market access. Stakeholders should monitor evolving extended producer responsibility frameworks in the EU and India, as these will determine whether biodegradable box investments generate compliance savings or stranded asset risk.
Market Dynamics
Commercial food vendors across India's northern industrial belt are abandoning loose bulk fuel purchases for standardized boxed briquette sets, compressing procurement cycles and forcing packaging suppliers to retool for smaller unit volumes with moisture-resistant specifications.
Growth Catalysts
- BIS Certification Mandates:India's tightening quality standards for packaged fuel products are accelerating box construction upgrades and labeling investments across domestic manufacturers.
- Residential Grilling Expansion:Backyard barbecue enthusiasts in North America are expanding purchases of boxed briquette sets, creating pull-through demand for retail-format packaging.
- Moisture-Resistant Barrier Technology:Advanced composite materials with ventilation perforations are preserving calorific value during monsoon-season storage, reducing spoilage losses for commercial vendors.
Market Restraints
- Raw Material Cost Volatility:Kraft paper and corrugated board input prices fluctuate with pulp commodity cycles, squeezing margin pools for cardboard box producers.
- Supply Concentration Risk:Captive logistics networks controlled by state-owned coal distributors limit third-party packaging suppliers' access to tier-two Indian cities.
- Substitution Threat:LPG cylinder penetration among street-side food vendors in urban India is displacing coal briquette demand in commercial cooking applications.
Strategic Opportunities
- Eco-Friendly Format Expansion:Recycled-content and plastic-free packaging specifications are capturing sustainability-conscious buyers in Western Europe.
- CDSCO Labeling Alignment:India's combustible material handling standards create first-mover advantage for box manufacturers investing in compliant barrier coatings.
- E-Commerce Channel Development:Direct-to-consumer fulfillment of boxed briquette sets is opening last-mile distribution partnerships with appliance retailers.
Industry Challenges
- Certification Timeline Compression:BIS testing protocols for burst strength and stacking load certifications require extended validation periods that delay product launches.
- Legacy Equipment Retrofit Costs:Small-scale box manufacturers face capital intensity in upgrading die-cutting and perforation machinery to meet moisture-barrier specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Briquette Box Market |
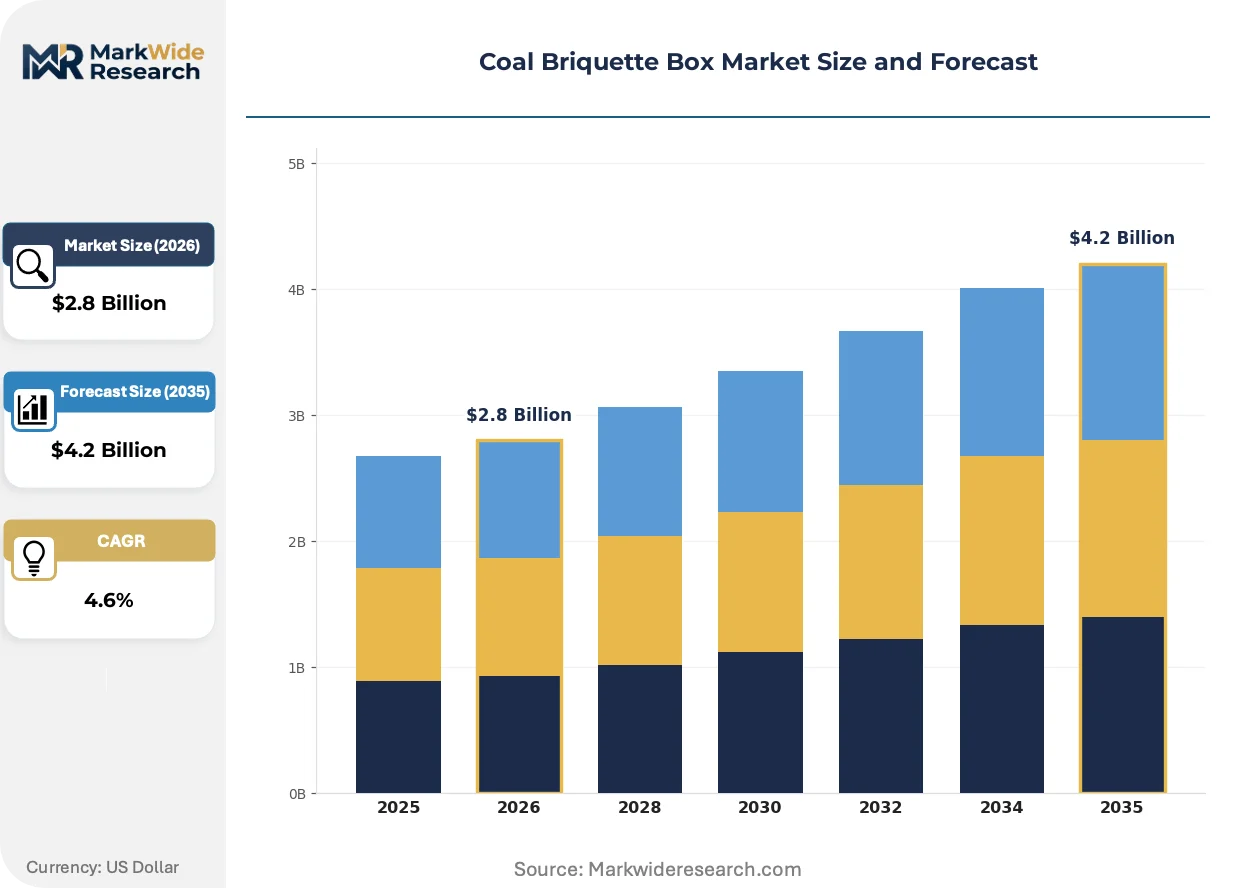
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Box, Premium Box, Eco-Friendly Box, Biodegradable Box Material: Cardboard, Plastic, Metal, Composite Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores End User: Household, Commercial, Industrial, Agricultural |
| Companies Covered | Coal India Limited, Peabody Energy Corporation, Arch Resources, Inc., China Shenhua Energy Company Limited, Kingsford Products Company, Royal Oak Enterprises, LLC, Duraflame Inc., Gryfskand sp. z o.o., Timber Charcoal Company Co. LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Briquette Box Market Evolving Landscape
Material science advances and regulatory pressure on combustible packaging are converging to reshape box construction, barrier performance, and end-of-life disposal protocols across fuel distribution channels.
Plant-based barrier coatings derived from cellulose nanofibrils are fragmenting the traditional polyethylene-laminated box segment by delivering comparable moisture resistance without fossil-derived films. European-format compressed fuel packaging specialists are piloting these coatings for grill briquette applications. The technology is fragmenting supplier tiers as early adopters capture sustainability premiums while conventional laminate producers face stranded asset exposure under REACH chemical restriction mandates.
EU REACH and the F-Gas Regulation are restricting perfluorinated coatings and certain adhesive chemistries in packaging materials, forcing reformulation of barrier layers used in fuel boxes. Industrial consequence includes accelerated R&D spending on bio-based alternatives and qualification delays for imported boxes. Western European markets are most affected, with distributors now requiring full material disclosure documentation from Indian and Chinese suppliers to secure customs clearance.
Street-side food vendors are consolidating procurement through wholesale cash-and-carry formats rather than traditional loose-bulk purchases from coal depots. This behavioral pivot disrupts long-standing supply relationships with unbranded fuel traders and elevates standardized boxed products with consistent burn characteristics. The shift concentrates most visibly around Delhi and Kanpur, where commercial briquette consumption is rotating toward pre-packaged inventory managed through distributor-led van sales operations.
Coal Briquette Box Market Segmentation
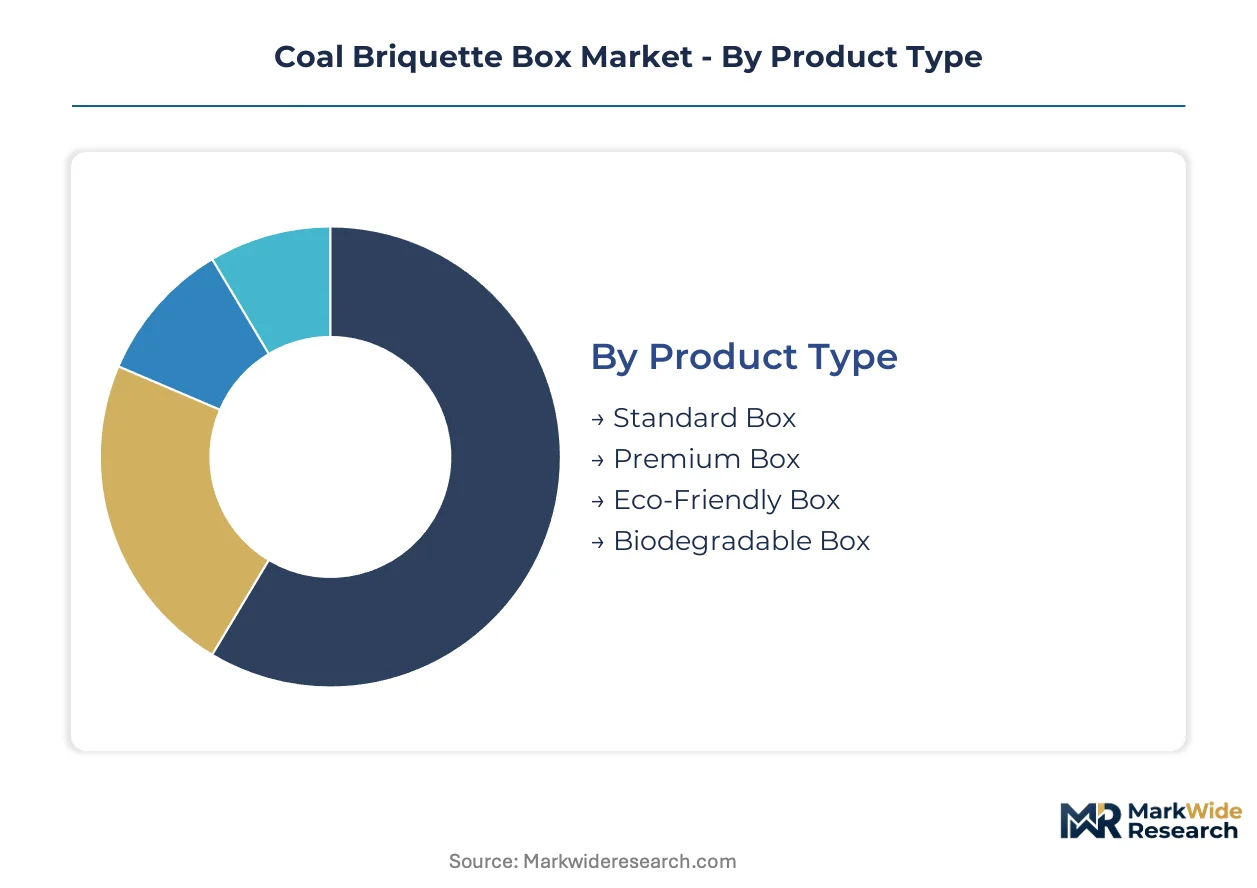
Segmentation in the coal briquette box market reflects divergent compliance burdens and performance specifications across user categories. Regulatory fragmentation between India's BIS mandates and EU REACH restrictions forces manufacturers to maintain parallel product lines with distinct material certifications and labeling protocols.
Product Type:
BIS certification tiers and EU chemical restriction thresholds create divergent cost structures across box grades, with premium specifications commanding qualification premiums in regulated channels.
- Standard Box:Basic cardboard or composite construction without specialized barrier coatings. Delhi and Kanpur street vendors rotate procurement toward this grade for cost-sensitive commercial cooking applications where moisture exposure remains manageable.
- Premium Box:Reinforced corrugated board with polyethylene-laminated moisture barriers and ventilation perforations calibrated for calorific value preservation. North American residential grillers pull this format through retail channels requiring extended shelf stability.
- Eco-Friendly Box:Recycled-content construction with plastic-free barrier specifications.
- Biodegradable Box:Plant-based coatings and compostable substrates aligned with extended producer responsibility frameworks.
Standard Box handles the majority of throughput; Premium Box is the fastest mover on share.
Material:
Raw material selection traces directly to end-use durability requirements and monsoon-season storage conditions in South Asian distribution networks.
- Cardboard:Kraft paper and corrugated board substrates dominate volume production. Indian manufacturers face margin compression from pulp commodity cycles while serving price-sensitive commercial vendors across the northern industrial belt.
- Plastic:Rigid polymer containers with sealed closures serve industrial boiler applications requiring extended outdoor storage.
- Metal:Tinplate and aluminum formats for premium gift-set packaging and institutional procurement.
- Composite:Multi-layer constructions combining cellulose substrates with bio-based barrier coatings.
Cardboard absorbs the highest shipment volumes; Composite materials are climbing the fastest as REACH-compliant alternatives displace conventional laminates.
Distribution Channel:
Channel selection determines packaging format specifications, with retail-facing channels demanding shelf-ready graphics and wholesale routes prioritizing stackability and cube efficiency.
- Online Retail:Direct-to-consumer fulfillment requires crush-resistant construction for last-mile handling. E-commerce partnerships with appliance retailers are opening new demand corridors for boxed briquette sets in residential segments.
- Supermarkets:Retail-format packaging with branded graphics and standard case counts for shelf replenishment cycles.
- Wholesale:Bulk pallet configurations serving cash-and-carry consolidation by commercial food vendors.
- Specialty Stores:Premium and eco-friendly assortments for sustainability-conscious buyers.
Wholesale channels move the largest aggregate tonnage; Online Retail is expanding most quickly as fulfillment infrastructure penetrates tier-two cities.
End User:
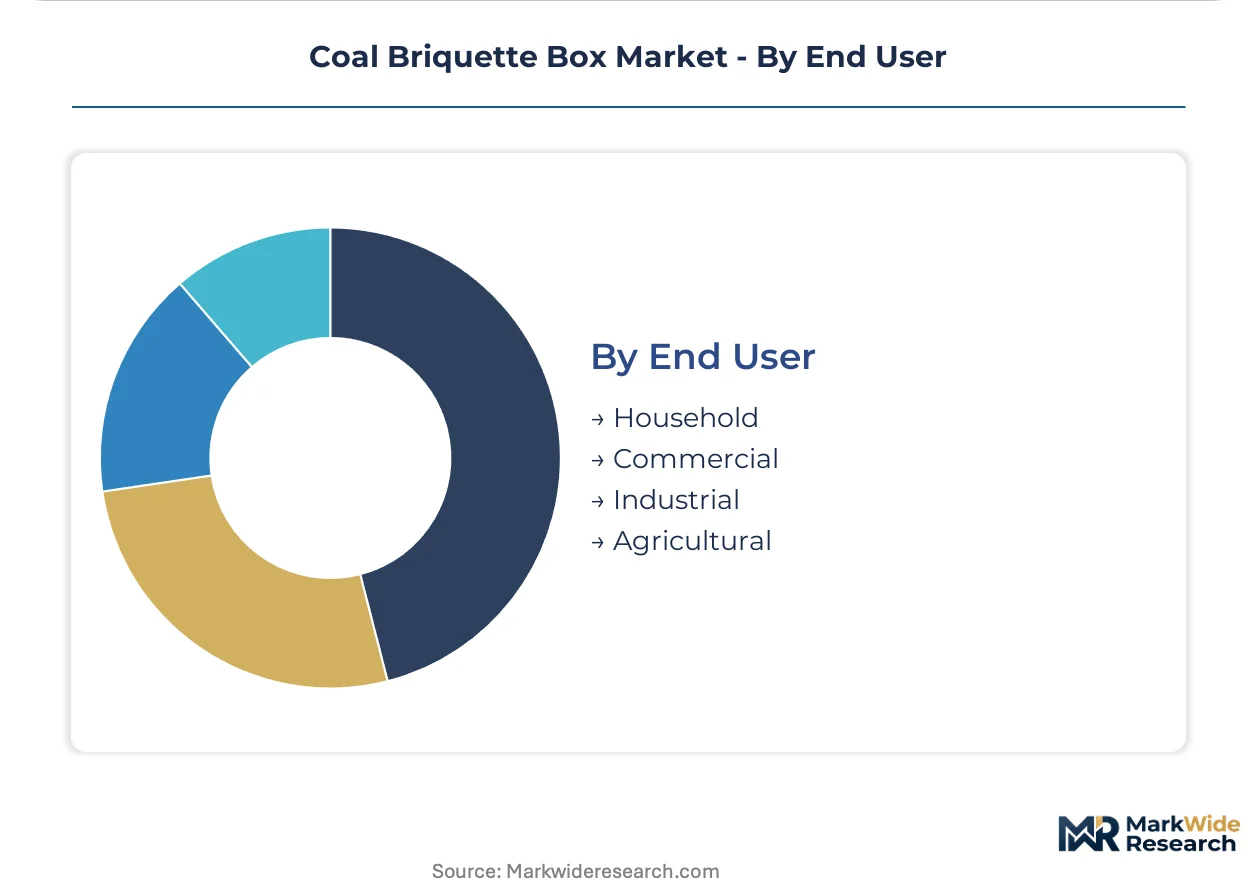
User category dictates performance specifications ranging from residential convenience to industrial combustion efficiency and agricultural drying applications.
- Household:Backyard barbecue enthusiasts in North America drive retail-format demand with preferences for consistent burn characteristics and convenient storage footprints.
- Commercial:Street-side food vendors across India's northern belt are consolidating procurement through standardized boxed sets, displacing loose bulk purchases from traditional coal depots.
- Industrial:Boiler operators and process heat users requiring high calorific value retention through extended storage cycles.
- Agricultural:Crop drying and greenhouse heating applications with seasonal demand concentration.
Commercial users generate the highest shipment volumes; Household segments are gaining share fastest as residential grilling culture expands in Western markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports packaged coal briquettes through its northern industrial corridor into Bangladesh and Nepal, while Chinese manufacturers supply moisture-resistant box formats across Southeast Asian retail channels.
India
Street-side food vendors in Delhi and Kanpur are consolidating procurement through standardized boxed sets, displacing loose bulk purchases from traditional coal depots. BIS certification mandates for packaged fuel products are accelerating box construction upgrades and labeling investments across domestic manufacturers. The northern industrial belt around Delhi anchors commercial demand concentration, with distributor-led van sales operations penetrating tier-two cities.
United States
Backyard barbecue enthusiasts are expanding purchases of boxed briquette sets through retail channels, creating pull-through demand for shelf-stable packaging formats. EPA regulations on combustible material storage influence warehouse handling standards for fuel distributors. The Southeast and Midwest regions concentrate residential grilling culture, with e-commerce fulfillment partnerships opening last-mile distribution corridors.
China
SAMR-enforced GB standards for transport packaging of solid fuels require burst strength and stacking load certifications that box manufacturers must satisfy for domestic market access. Industrial boiler operators in the Yangtze River Delta specify high-calorific-value retention through extended storage cycles. Pearl River Delta manufacturing clusters produce composite box formats with bio-based barrier coatings for export markets.
Germany
EU REACH and the F-Gas Regulation are restricting perfluorinated coatings and certain adhesive chemistries in packaging materials, forcing reformulation of barrier layers. Sustainability-conscious buyers in Western Europe are shifting toward recycled-content and plastic-free packaging formats. The Ruhr industrial region and Bavarian manufacturing corridors concentrate demand for premium grill briquette applications with full material disclosure documentation.
Poland
Commercial food preparation and residential heating applications sustain demand for standardized unit dosing formats that reduce spillage and simplify inventory management. ECHA chemical restriction mandates shape box material specifications through coating and adhesive limitations. Silesian industrial zones and Warsaw metropolitan distribution hubs channel boxed briquette products into Central European retail and wholesale networks.
Coal Briquette Box Market Competitive Landscape
Player mix skews toward state-affiliated resource conglomerates and specialized packaging fabricators with captive fuel distribution networks. Tier-one positions concentrate around integrated coal producers with in-house box manufacturing capabilities. Three strategic archetypes dominate: state-owned mining enterprises with logistics control, regional packaging specialists with barrier technology expertise, and branded consumer goods companies with retail shelf presence. Competitive moves center on certification pre-qualification for BIS and REACH compliance, plus e-commerce channel partnerships for direct-to-consumer fulfillment.
Within the state-affiliated tier, Coal India Limited anchors domestic Indian distribution through its captive logistics network, exemplifying vertical control over fuel sourcing and last-mile box delivery. Kingsford Products Company occupies a position among branded consumer goods specialists, representing retail-format packaging expertise in North American residential segments. Gryfskand sp. z o.o. sits within the European barrier technology specialist archetype, reflecting moisture-resistant specification capabilities for compressed fuel applications.
| Leading Market Players |
|---|
| Coal India Limited |
| Peabody Energy Corporation |
| Arch Resources, Inc. |
| China Shenhua Energy Company Limited |
| Kingsford Products Company |
| Royal Oak Enterprises, LLC |
| Duraflame Inc. |
| Gryfskand sp. z o.o. |
| Timber Charcoal Company Co. LLC |
| Others |
Value Network & Pricing Analysis
Plant-based barrier coatings substituting polyethylene-laminated constructions are redrawing procurement geography toward Pearl River Delta manufacturing clusters while compressing margin pools for incumbent laminate producers facing REACH chemical restriction mandates.
Pricing Analysis
Current-generation polyethylene-laminated boxes command qualification premiums against prior-generation uncoated cardboard and next-generation cellulose nanofibril alternatives. Three-tier pricing structure across premium BIS-certified, standard moisture-resistant, and economy uncoated grades stratifies by certification level and brand presence. Pricing pressure stems from pulp commodity cycle volatility squeezing cardboard producers serving price-sensitive Delhi street vendors. Commercial food vendors exhibit highest price sensitivity; North American residential grillers show lowest sensitivity due to brand loyalty.
Supply Chain Analysis
Inbound logistics costs through Nhava Sheva and Chennai port congestion are elevating landed costs for European-format moisture-resistant packaging imported into India. Supply concentrates in China, India, and Poland, with raw material dependencies spanning kraft pulp, bio-based coatings, and corrugated board substrates. Single-source vulnerability runs through state-owned coal distributors controlling captive last-mile networks. Distribution runs through distributor-led van sales operations penetrating tier-two cities alongside wholesale cash-and-carry consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory divergence between BIS certification tiers and EU REACH chemical restrictions creates parallel product line niches for specialized manufacturers.
For Market Incumbents: Compound certification pre-qualification advantages by accelerating BIS burst strength validation investments ahead of timeline compression risks. Secure backward integration into cellulose nanofibril coating supply chains to offset stranded asset exposure from REACH perfluorinated restrictions. Channel control through e-commerce fulfillment partnerships with appliance retailers anchors residential segment access against emerging direct-to-consumer entrants. For New Entrants and Emerging Players: Last-mile logistics gaps in tier-two Indian cities where Coal India's captive networks under-serve commercial vendors present white-space entry points. Target biodegradable box formats aligned with extended producer responsibility frameworks in Western Europe where sustainability premiums persist. Pursue CDSCO labeling alignment as first-mover positioning in India's combustible material handling standards. For Investors and Strategic Acquirers: Capital is best deployed toward barrier technology specialists with REACH-compliant bio-based coating capabilities and established European retail channel relationships. Long-term viability over a multi-year horizon hinges on regulatory arbitrage between tightening chemical restrictions and certification-driven procurement consolidation. Watch BIS testing protocol expansion as inflection signal for domestic Indian manufacturing capacity requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Coatings | REACH compliance secures European market access against laminate substitution. |
| BIS Certification Pre-Qualification | Accelerated validation timelines capture Delhi-Kanpur commercial vendor consolidation. |
| E-Commerce Fulfillment Partnership | Direct-to-consumer channels penetrate North American residential grilling segments. |
| Capacity Expansion in Pearl River Delta | SAMR GB standard compliance anchors Southeast Asian export manufacturing. |
| Long-Term Supply Agreement with Pulp Producers | Raw material cost hedging stabilizes margins against commodity cycle volatility. |
Research Methodology
A standing panel of packaging procurement managers at commercial food vendors, corrugated board plant engineers, BIS certification auditors, and retail category buyers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade records, BIS notification databases, SEC filings from integrated coal producers, and pulp commodity price indices. Bottom-up shipment data triangulated against top-down fuel consumption estimates from national energy agencies.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type tier, material substrate, distribution channel format, and end-use category. CAGRs derived from regression analysis of historical shipment trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated monsoon-season storage loss rates and regulatory compliance timeline assumptions.
Forecasts assume regulatory continuity in India's BIS framework and EU REACH chemical restriction regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Charcoal Briquette Market
Fuels
Asia-Pacific Coal Market
Fuels
India Retail Fuel Market
Fuels
Europe Firewood Market
Fuels
South Korea LNG Bunkering Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Global Fuel Ethanol Market
Fuels
Methane Market
Fuels
Industrial Fuel Filter Market
Fuels
Wood Pellet Market
Fuels
Diesel As Fuel Market
Fuels
Gas to Liquid (GTL) Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Iso-Octane Market
Fuels
Pyrolysis Gas Market