
 Compounding Chemotherapy Market | 2026-2036
Compounding Chemotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Compounding Chemotherapy Market Analysis
Modular dose bundling is rebalancing how hospital pharmacies procure chemotherapy preparations, shifting from bulk vial purchasing to patient-specific unit doses. Grifols, S.A. leverages its plasma-derived expertise to anchor European compounding capacity for cytotoxic agents. Baxter International Inc. sustains North American hospital relationships through integrated infusion pump and premixed bag systems. Fresenius Kabi AG competes aggressively on manufacturing scale for generic oncology injectables used in compounded protocols.
Compounding chemotherapy encompasses the sterile preparation of customized cytotoxic drug formulations, including dose adjustment, dilution in biocompatible vehicles, and aseptic processing under ISO Class 5 conditions with HEPA filtration. These preparations serve patients requiring individualized dosing based on body surface area, renal function, or protocol-specific combinations unavailable in manufactured strengths. Intravenous formulations dominate current volume due to their centrality in hospital-administered regimens, while oral compounding exhibits faster structural growth as home-based cancer care expands. The therapy area segmentation reveals oncology applications commanding the deepest margin pools, whereas pain management compounding faces reimbursement compression in outpatient settings.
The US FDA enforces current Good Manufacturing Practice standards for outsourcing facilities under Section 503B of the FD&C Act, while USP <797> and <800> chapters mandate engineering controls and personnel competency for hazardous drug handling. The European Medicines Agency coordinates batch-release requirements for compounded oncology products across member states, creating divergent compliance obligations for multinational operators. Stakeholders must monitor evolving USP chapter revisions and EMA guidance on advanced therapy medicinal products to anticipate facility investment requirements and partnership restructuring.
Market Dynamics
USP <797> and USP <800> enforcement is compressing hospital in-house compounding capacity, redirecting volume toward specialized outsourcing facilities that can absorb capital-intensive compliance burdens.
Growth Catalysts
- Oncology Patient Volume:Rising cancer incidence across aging populations drives demand for patient-specific dosing that manufactured strengths cannot satisfy.
- 503B Outsourcing Facility Expansion:FDA registration pathways enable hospitals to access sterile compounding without assuming full cGMP infrastructure costs.
- Home Infusion Migration:Oral and subcutaneous chemotherapy protocols shift administration from infusion centers to residential settings, requiring specialized compounding for ambulatory delivery.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing concentrates among Chinese and Indian manufacturers, exposing formulators to geopolitical and quality disruption risks.
- Facility Capital Intensity:ISO Class 5 cleanrooms with HEPA filtration and hazardous drug containment systems require seven-figure investments that exclude smaller hospital pharmacies.
- Reimbursement Compression:Medicare Part B and commercial payers apply ASP-based pricing limits that squeeze margins on compounded oncology injectables.
Strategic Opportunities
- Oral Oncology Compounding:Home-based cancer care expansion creates white space for cytotoxic capsule and liquid formulation services beyond intravenous dominance.
- EMA Batch-Release Harmonization:Coordinated European standards reduce cross-border compliance friction for multi-country outsourcing networks.
- Pediatric Dose Customization:Body surface area and weight-based protocols for pediatric oncology patients require compounding capabilities that standardized manufacturing cannot address.
Industry Challenges
- Sterile Compounding Personnel Shortage:USP <797> competency requirements and hazardous drug handling certifications limit qualified pharmacy technician availability.
- Environmental Monitoring Burden:Continuous viable and non-viable particle monitoring in cleanroom suites demands dedicated quality infrastructure and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compounding Chemotherapy Market |
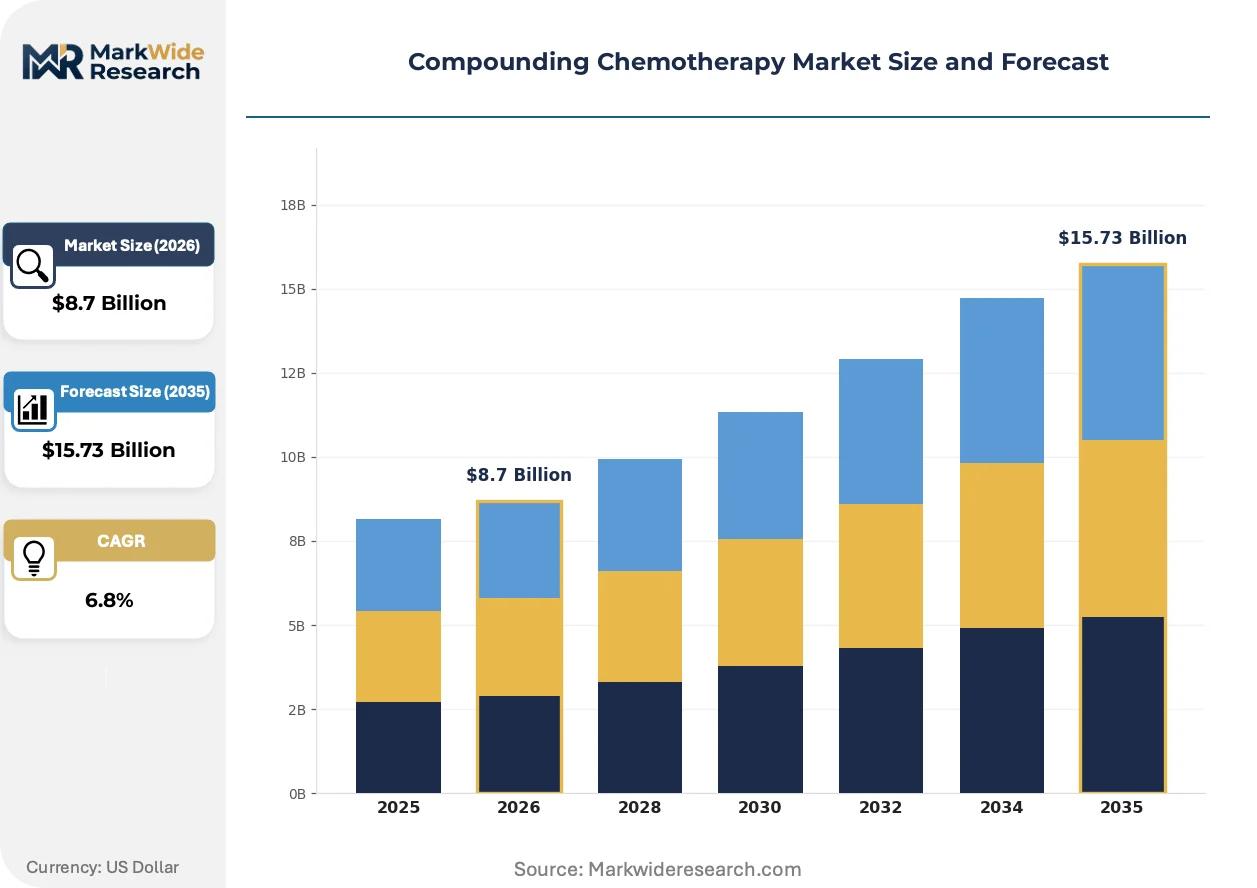
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Oral, Topical, Injectable Therapy Area: Cancer, Oncology, Hematology, Pain Management End User: Hospitals, Clinics, Pharmacies, Home Care Delivery Mode: Syringe, Infusion Pump, Tablets, Capsules |
| Companies Covered | Grifols, S.A., Fagron NV, Baxter International Inc., QuVa Pharma, Inc., PharMEDium, B. Braun Melsungen AG, ICU Medical, Inc., Nephron Pharmaceuticals Corporation, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compounding Chemotherapy Market Emerging Trajectories
Closed-system transfer devices and robotic compounding technologies are reconfiguring sterile preparation workflows, reducing occupational exposure while tightening dose accuracy tolerances.
Robotic compounding systems are automating aseptic manipulation of cytotoxic vials in hospital and outsourced settings. Large academic medical centers and 503B facilities deploy these systems to reduce technician handling time and contamination risk. The technology is automating workforce allocation away from manual sterile preparation toward supervisory and verification roles.
EMA guidance on advanced therapy medicinal products is extending quality standards from traditional small-molecule oncology drugs to cell and gene therapy compounding. Manufacturers must adapt batch-release documentation and stability testing protocols. European hospital pharmacies and contract manufacturers face the steepest compliance curve as ATMP volume accelerates.
Hospital pharmacy directors are consolidating supplier relationships around full-service outsourcing partners capable of dose bundling and just-in-time delivery. Multi-hospital systems negotiate enterprise agreements replacing fragmented local contracts. The United States exhibits the most pronounced consolidation as cancer center networks standardize across dozens of affiliated infusion sites.
Compounding Chemotherapy Market Segmentation
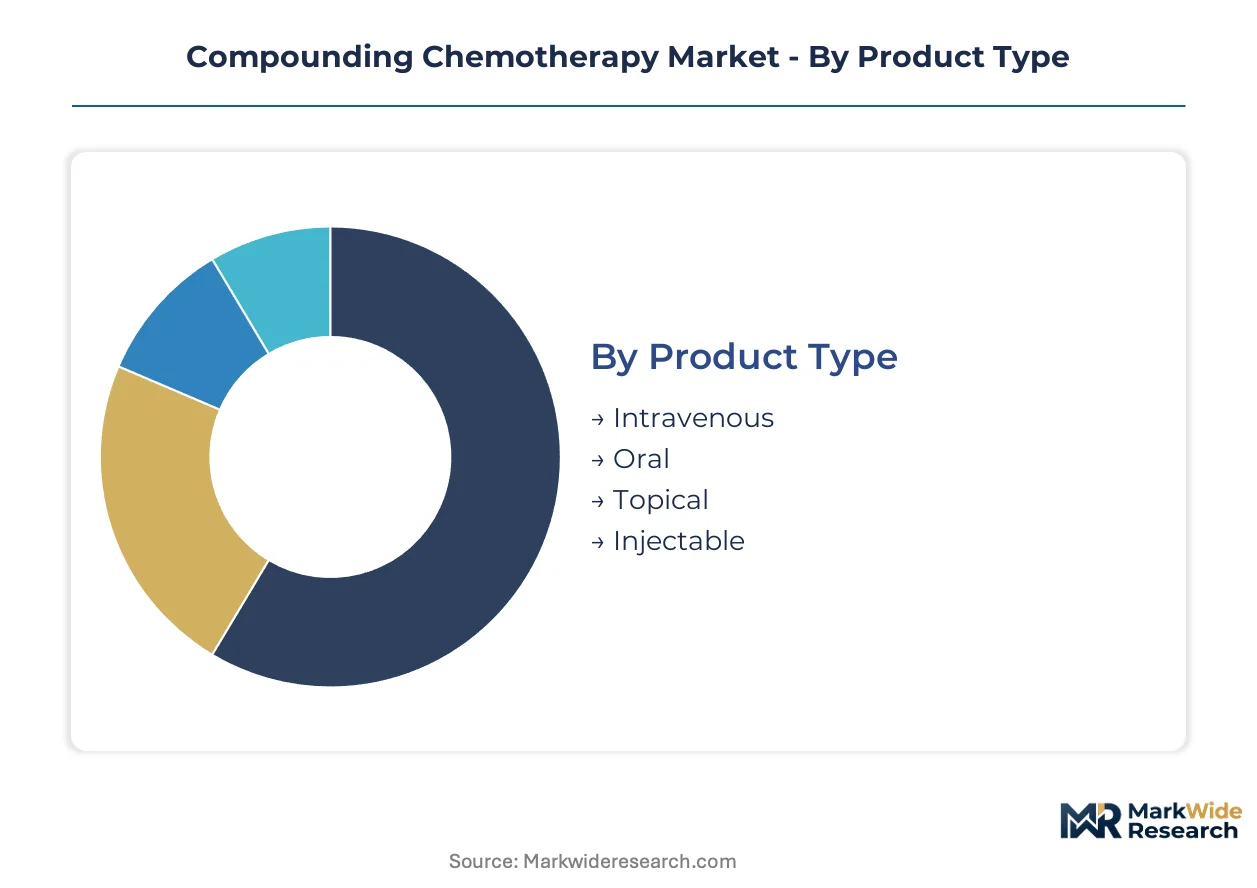
Compounding chemotherapy segmentation reveals how formulation complexity, administration setting, and regulatory burden concentrate margin across distinct service tiers. Supply chain configuration for each segment determines whether facilities absorb compliance costs internally or outsource to specialized 503B providers.
Product Type:
Sterile preparation requirements and API sourcing economics concentrate manufacturing investment differently across administration routes.
- Intravenous:Large-volume sterile preparations requiring aseptic dilution in biocompatible vehicles dominate hospital procurement. United States cancer center networks drive volume for outsourced IV compounding as USP <797> enforcement tightens.
- Oral:Cytotoxic capsules and liquid formulations bypass infusion center infrastructure. Home-based cancer protocols in Germany and France expand demand for patient-specific oral dosing that manufactured strengths cannot supply.
- Injectable:Subcutaneous and intramuscular preparations serve ambulatory delivery models. Japanese hospital pharmacies invest in robotic compounding systems to handle injectable volume with reduced technician exposure.
- Topical:Limited application for cutaneous lymphoma and palliative care. Compounding pharmacies in Australia address niche demand through specialized hazardous drug handling protocols.
Today's leader: Intravenous. Tomorrow's challenger: Oral.
Therapy Area:
Reimbursement density and protocol standardization separate high-investment oncology segments from commoditized pain management services.
- Oncology:Cytotoxic drug combinations require patient-specific dosing based on body surface area and renal function. United States Medicare Part B reimbursement sustains margin pools for sterile oncology compounding despite ASP-based pricing pressure.
- Cancer:Protocol-driven regimens concentrate demand among academic medical centers and specialized infusion networks. South Korean hospital systems expand in-house capacity to secure supply chain continuity for high-volume cancer therapies.
- Hematology:Bone marrow transplant conditioning regimens demand precise dose adjustment. EMA batch-release requirements create compliance friction for cross-border hematology compounding in Europe.
- Pain Management:Outpatient reimbursement compression limits capital investment. Canadian compounding pharmacies face margin erosion as provincial formularies restrict compounded analgesic coverage.
Oncology commands capital deployment. Hematology shows steepest expansion trajectory as transplant volume rises.
End User:
Facility scale and regulatory sophistication determine whether end users internalize compounding or outsource to specialized partners.
- Hospitals:Academic medical centers deploy robotic compounding systems to reduce technician handling time. United States hospital oncology departments balance in-house capacity against 503B outsourcing partnerships.
- Home Care:Ambulatory infusion and oral protocols shift administration from clinical settings to residential environments. French home care networks require specialized compounding for cytotoxic delivery outside hospital infrastructure.
- Clinics:Community oncology practices lack capital for ISO Class 5 cleanrooms. Italian clinic networks consolidate procurement through regional compounding hubs to achieve compliance scale.
- Pharmacies:Retail and specialty pharmacies face USP <800> hazardous drug containment requirements. United Kingdom independent pharmacies exit cytotoxic compounding as MHRA enforcement intensifies.
Hospitals anchor current volume. Home care gains share fastest as administration migrates residential.
Delivery Mode:
Device integration and packaging complexity separate premium dose-bundling services from commodity sterile preparation.
- Infusion Pump:Premixed bag systems integrate with smart pump libraries to reduce dosing errors. Baxter International sustains North American hospital relationships through combined device and compounding service agreements.
- Syringe:Patient-specific unit doses enable just-in-time delivery for infusion center workflows. German hospital pharmacies adopt closed-system transfer devices to reduce occupational exposure during syringe preparation.
- Capsules:Oral cytotoxic dosing requires specialized containment during encapsulation. Swiss compounding facilities invest in isolator technology for high-potency capsule production.
- Tablets:Limited application due to manufacturing scale advantages of commercial oncology tablets. Australian compounding pharmacies address niche pediatric dose customization beyond manufactured strengths.
Infusion pump integration locks in hospital contracts. Syringe dose bundling climbs fastest as modular procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The compounding chemotherapy industry traces its modern scale to post-war pharmaceutical manufacturing clusters in the United States and Western Europe, where sterile processing expertise first concentrated around academic medical centers and plasma fractionation facilities.
United States
FDA 503B outsourcing facility registrations and cancer center network expansion drive sterile compounding volume. USP <797> and <800> enforcement tightens engineering controls for hazardous drug handling. The Texas Medical Center in Houston anchors the nation's largest concentration of outsourced oncology compounding capacity.
Germany
Home-based cancer care protocols and oral cytotoxic formulation demand reshape compounding service requirements. The country's national pharmaceutical regulator enforces batch-release standards for sterile oncology preparations under EMA coordination. The Rhine-Ruhr metropolitan region hosts specialized facilities serving cross-border hospital networks.
Japan
Aging demographics and rising cancer incidence expand patient-specific dosing needs beyond manufactured strengths. PMDA guidance on aseptic processing governs robotic compounding system deployment in hospital pharmacies. The Kanto region around Tokyo concentrates investment in automated sterile preparation infrastructure.
France
Ambulatory infusion and residential chemotherapy administration shift compounding demand outside hospital walls. ANSM oversight of hazardous drug containment shapes facility investment in cytotoxic handling capabilities. The Île-de-France region surrounding Paris coordinates multi-site compounding networks for home care delivery.
Switzerland
High-potency capsule production and isolator technology investment serve precision oncology dosing requirements. Swissmedic standards for sterile compounding align with EMA frameworks while maintaining distinct national enforcement. The Basel area leverages pharmaceutical manufacturing heritage to anchor specialized cytotoxic formulation capacity.
Compounding Chemotherapy Market Vendor Landscape
Premium-margin players sit above commodity-margin players across compliance sophistication and delivery integration dimensions. The vendor base organizes into three tiers: full-service outsourcing networks with 503B registration, regional hospital-affiliated compounding operations, and specialized oral formulation specialists. Consolidation pressure intensifies as multi-hospital systems negotiate enterprise agreements replacing fragmented local contracts. Capacity expansion and robotic automation deployment represent the dominant competitive moves reshaping facility economics.
Among European plasma-derived therapy specialists, Grifols, S.A. exemplifies the vertically integrated archetype extending fractionation expertise into cytotoxic compounding capacity. Baxter International Inc. occupies a position at the device-integration end of the spectrum, where premixed bag systems and infusion pump libraries lock in hospital procurement relationships. Fresenius Kabi AG represents the manufacturing-scale archetype competing on generic oncology injectable volume for compounded protocols. These three entities anchor distinct strategic positions without exhaustively mapping competitive space.
| Leading Market Players |
|---|
| Grifols, S.A. |
| Fagron NV |
| Baxter International Inc. |
| QuVa Pharma, Inc. |
| PharMEDium |
| B. Braun Melsungen AG |
| ICU Medical, Inc. |
| Nephron Pharmaceuticals Corporation |
| Fresenius Kabi AG |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation around dose-bundling contracts is forcing compounders to absorb ISO Class 5 cleanroom capital costs while Medicare Part B ASP limits squeeze reimbursement headroom.
Pricing Analysis
Three-tier pricing structure across premium 503B-certified, standard hospital-affiliated, and economy regional compounding tiers separates compliance-grade providers from commodity operators. Price differentiation hinges on USP <797> certification tier and robotic automation scale, with academic medical centers least sensitive and community oncology clinics most vulnerable to cost compression. ASP-based Medicare reimbursement is tightening margins on sterile oncology injectables, pressuring mid-tier facilities toward consolidation or exit.
Supply Chain Analysis
API sourcing rests on Chinese and Indian active pharmaceutical ingredient manufacturers, with cytotoxic chemical precursors drawing from German and Swiss specialty chemical houses. HEPA filtration systems and isolator technology feed from Japanese and German engineering suppliers. Single-source vulnerability concentrates in Chinese API intermediates for platinum-based agents. Distribution runs through 503B outsourcing networks and direct hospital contracts, with just-in-time dose bundling replacing bulk vial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where USP <800> hazardous drug containment mandates are elevating specifications toward premium-certified providers.
For Market Incumbents: Cement 503B registration advantages through robotic compounding system deployment and cross-regional dose-bundling networks. Lock in multi-hospital system enterprise agreements before EMA batch-release harmonization lowers European entry barriers for competitors. Absorb ISO Class 5 capital intensity to exclude smaller hospital pharmacies from in-house alternatives. For New Entrants and Emerging Players: Home care infusion networks represent the most penetrable channel partner type for oral cytotoxic compounding services beyond intravenous dominance. Target French and German ambulatory delivery markets where residential chemotherapy administration is shifting volume outside hospital walls. Lead with pediatric dose customization capabilities that standardized manufacturing cannot address. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale 503B facilities possessing robotic automation and multi-state licensing but lacking national scale. Five-to-ten year viability favors operators with backward integration into API sourcing or device-compounding service bundling. Watch FDA enforcement intensity against non-compliant hospital in-house operations as inflection indicator for outsourcing volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Compounding System Deployment | Fresenius Kabi and Baxter scale automation to reduce technician exposure and tighten dose accuracy tolerances. |
| 503B Registration Expansion | QuVa Pharma and PharMEDium secure FDA outsourcing facility status to capture hospital compliance-driven volume. |
| Oral Oncology Formulation Investment | Swiss and German facilities build isolator capacity for home-based cytotoxic capsule production. |
| Multi-Hospital Enterprise Agreements | Cancer center networks consolidate procurement across dozens of affiliated infusion sites in the United States. |
| EMA Batch-Release Harmonization | Cross-border European compounding networks reduce compliance friction for multi-country outsourcing operations. |
Methodological Framework
Direct dialogue with hospital pharmacy directors, 503B facility compliance officers, oncology procurement managers, and EMA regulatory specialists grounded qualitative insights. Secondary validation drew from FDA 503B registration databases, USP chapter revision notices, EMA guidance documents, and hospital GPO contract filings. Bottom-up facility capacity modeling and top-down cancer incidence projections were triangulated against reimbursement rate trajectories.
Segmentation outputs across intravenous, oral, injectable, and topical formulation routes were calibrated against therapy area oncology, hematology, and pain management demand patterns. End-user splits between hospitals, home care, clinics, and pharmacies incorporated USP <797> and <800> enforcement timelines. CAGRs were derived from patient volume growth, outsourcing penetration rates, and regulatory compliance cost absorption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA 503B enforcement intensity, API supply geopolitics, and Medicare Part B reimbursement rulemaking. Forecasts reflect documented assumptions on robotic automation adoption speed and EMA harmonization implementation. A small set of named triggers—USP <797> revision finalization, major API supply disruption, and pediatric oncology protocol expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Alkylating Agents Market