
 Famotidine Market | 2026-2036
Famotidine Market Size, Share, and Industry Trends Forecast 2026-2036
Famotidine Market Analysis
Multi-source API procurement is expanding across generic famotidine manufacturers as supply security concerns reshape pharmaceutical sourcing. Teva Pharmaceutical Industries Ltd. leverages its vertically integrated active pharmaceutical ingredient capabilities to sustain cost advantages in tablet production. Dr. Reddy's Laboratories Ltd. anchors its position through high-volume exports to regulated markets. Sun Pharmaceutical Industries Ltd. competes on manufacturing scale across oral suspension and injectable formats.
Famotidine is a histamine H2-receptor antagonist with the chemical formula C8H15N7O2S3, synthesized through multi-step organic reactions involving thiazole ring formation and guanidine substitution, primarily prescribed for gastric acid suppression in gastroesophageal reflux disease and peptic ulcer conditions. Tablet formulations dominate volume due to patient compliance and manufacturing efficiency, while injectable formats command premium positioning in acute hospital settings where oral administration is contraindicated. Retail pharmacies represent the most mature distribution channel with established reimbursement pathways, whereas online pharmacies exhibit the fastest structural expansion driven by direct-to-patient fulfillment models.
The FDA enforces bioequivalence standards under ANDA pathways that determine which generic famotidine products gain market access, while the EPA regulates pharmaceutical manufacturing discharge limits affecting API production site location decisions. The International Council for Harmonisation Q7 guidelines govern good manufacturing practice for active pharmaceutical ingredients, creating compliance thresholds that filter supplier participation. Stakeholders must monitor evolving pharmacovigilance requirements for H2-antagonist drug-drug interaction labeling as regulatory scrutiny intensifies across major prescribing markets.
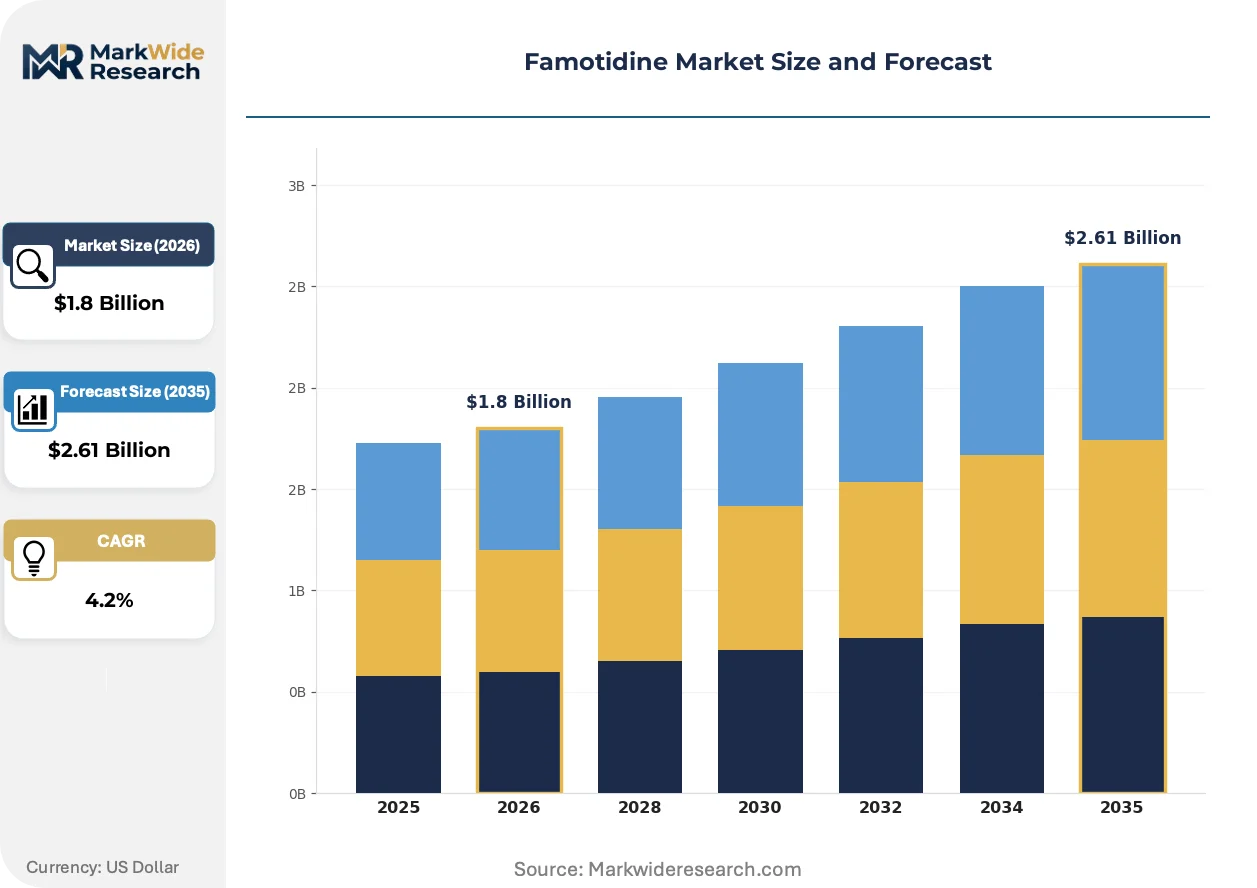
Market Dynamics
Hospital formulary committees now prioritize generic famotidine sourcing through consolidated procurement contracts, compressing supplier margins while elevating bioequivalence documentation requirements as the central competitive filter.
Growth Catalysts
- ANDA Bioequivalence Pathways:The FDA's abbreviated new drug application framework accelerates generic entry for tablet and injectable formats, expanding therapeutic access while maintaining quality thresholds.
- Acute Care Settings:Hospital emergency departments and intensive care units drive demand for parenteral famotidine where oral administration is contraindicated.
- Thiazole Synthesis Optimization:Process chemistry advances in guanidine substitution reactions reduce active pharmaceutical ingredient production costs.
Market Restraints
- API Supply Concentration:Bulk famotidine chemical production clusters in select Asian manufacturing zones, creating single-source vulnerability for finished dose formulators.
- Proton Pump Inhibitor Substitution:Omeprazole and esomeprazole formulations capture maintenance therapy prescriptions previously filled by H2-antagonists.
- EPA Discharge Limits:Pharmaceutical manufacturing effluent regulations constrain site selection for multi-step organic synthesis operations.
Strategic Opportunities
- Online Pharmacy Channels:Direct-to-patient fulfillment models bypass traditional wholesale distribution, capturing margin previously allocated to intermediaries.
- CDSCO Generic Approvals:India's streamlined abbreviated new drug application pathway enables export-ready production for regulated markets.
- Fixed-Dose Combinations:Co-formulation with antacids addresses breakthrough symptom management in gastroesophageal reflux disease.
Industry Challenges
- ICH Q7 Compliance Talent:Good manufacturing practice expertise for active pharmaceutical ingredient production remains scarce relative to formulation-scale operations.
- ANDA Response Timelines:Complete response letter cycles from the FDA extend generic product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Famotidine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Suspension, Injectables, Effervescent Granules End User: Hospitals, Clinics, Retail Pharmacies, Home Healthcare Application: Gastroesophageal Reflux Disease, Peptic Ulcer Disease, Zollinger-Ellison Syndrome, Heartburn Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Supermarkets |
| Companies Covered | Merck & Co., Astellas Pharma Inc., Teva Pharmaceutical Industries Ltd., Viatris, Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Upsher-Smith Laboratories, Xiuzheng Pharmaceutical, Fujian Tianquan Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Famotidine Market Emerging Trajectories
Continuous manufacturing technologies and real-time release testing are reshaping famotidine production economics, while regulatory convergence around bioequivalence standards accelerates cross-border generic substitution.
Continuous direct compression is consolidating solid dose manufacturing by integrating granulation, blending, and tableting into unified processing lines. Generic manufacturers in India and the United States adopt these systems to reduce batch-to-batch variability and facility footprint. The technology is consolidating competitive advantage around capital-intensive operators capable of validating real-time release protocols.
REACH authorization requirements for thiazole derivative intermediates are tightening environmental compliance obligations for European API sourcing operations. Chemical manufacturers must submit comprehensive safety dossiers for guanidine-containing compounds used in famotidine synthesis. German and Swiss production sites are responding by relocating final crystallization steps to jurisdictions with less stringent chemical substance registration frameworks.
Hospital procurement committees now mandate therapeutic interchange programs that automatically substitute prescribed H2-antagonists with lowest-cost equivalent products. This centralized purchasing behavior concentrates volume with suppliers offering the most favorable contracting terms. The United States exhibits the most advanced form of this shift, with group purchasing organizations capturing substantial inpatient famotidine volume.
Famotidine Market Segmentation
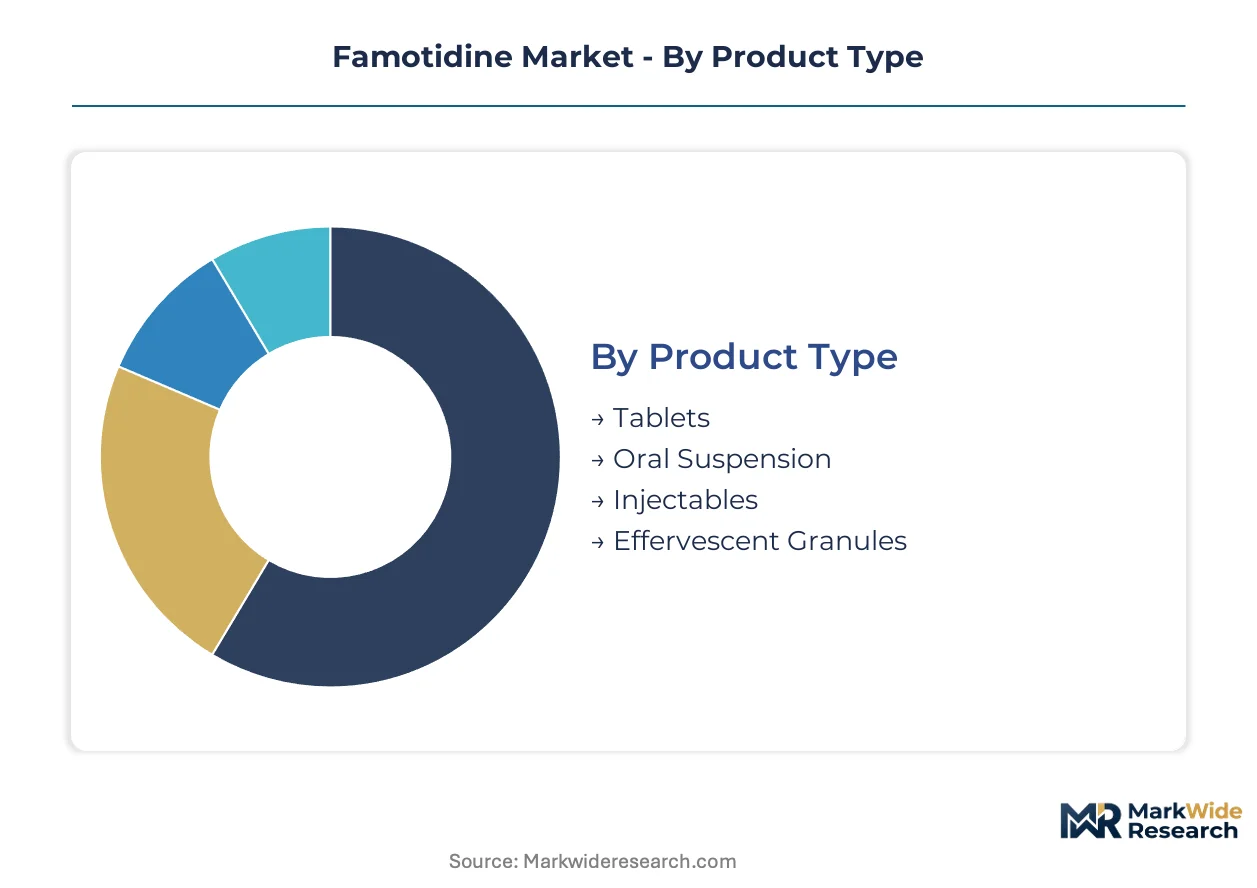
Famotidine formulation diversity reflects divergent patient acuity levels and administration constraints across care settings. Supply-side specialization concentrates manufacturing investment around high-volume solid dose formats while niche parenteral production requires dedicated sterile facilities.
Product Type:
API sourcing concentration in Asian manufacturing clusters shapes finished dose economics across all formulation categories.
- Tablets:Compressed solid dosage forms containing famotidine base or its salts in 20mg and 40mg strengths. Hospital procurement committees in the United States allocate the majority of formulary volume to immediate-release tablets for maintenance therapy of acid-related disorders.
- Injectables:Sterile solutions for intravenous or intramuscular administration in acute care environments. Demand concentrates in emergency departments and intensive care units where oral administration is contraindicated, with FDA bioequivalence requirements governing ANDA approvals for generic parenteral entrants.
- Oral Suspension:Liquid formulations enabling dose titration for pediatric and geriatric populations with swallowing difficulties.
- Effervescent Granules:Rapid-dissolution sachet formats targeting over-the-counter heartburn relief in retail pharmacy channels.
Tablets absorb the bulk of installed capacity; injectables are expanding most quickly.
End User:
Cost tier differentiation separates institutional purchasers operating under consolidated procurement contracts from fragmented retail dispensing.
- Hospitals:Acute care facilities purchasing through group purchasing organizations with mandatory therapeutic interchange programs. Teva Pharmaceutical Industries and Dr. Reddy's Laboratories compete for volume through long-term supply agreements with US hospital systems.
- Retail Pharmacies:Community and chain pharmacies dispensing outpatient prescriptions with established insurance reimbursement pathways. CVS Health and Walgreens Boots Alliance capture the majority of US famotidine prescription volume through centralized generic sourcing.
- Clinics:Outpatient medical offices with limited on-site dispensing capabilities.
- Home Healthcare:Long-term care and hospice settings requiring parenteral administration for patients unable to tolerate oral intake.
Hospitals command the largest absolute volume; home healthcare is climbing the fastest as aging populations shift care settings.
Application:
Volume distribution across indications tracks the prevalence gradient of acid-related gastrointestinal pathology.
- Gastroesophageal Reflux Disease:Chronic condition characterized by lower esophageal sphincter dysfunction causing recurrent acid exposure. Maintenance prescriptions in the United States dominate volume as proton pump inhibitor substitution pressures reshape first-line therapy selection.
- Peptic Ulcer Disease:Mucosal defects in stomach or duodenum requiring acid suppression for healing. Hospital admissions for bleeding ulcers in India and China sustain demand for parenteral famotidine where cost constraints limit PPI access.
- Zollinger-Ellison Syndrome:Rare gastrin-secreting tumor causing extreme acid hypersecretion requiring high-dose H2-antagonist therapy.
- Heartburn:Episodic symptomatic relief driving over-the-counter famotidine purchases through retail and online channels.
Gastroesophageal reflux disease absorbs the bulk of installed capacity; heartburn is gaining share fastest through direct-to-consumer channel expansion.
Distribution Channel:
Margin compression in traditional wholesale distribution is accelerating channel disintermediation.
- Direct Sales:Manufacturer-to-institution contracts bypassing wholesale intermediaries for hospital system procurement. Teva Pharmaceutical Industries leverages direct sales teams to secure multi-year agreements with US group purchasing organizations.
- Online Pharmacies:Direct-to-patient fulfillment platforms capturing margin previously allocated to brick-and-mortar intermediaries. Amazon Pharmacy and Capsule in the United States are expanding same-day famotidine delivery in metropolitan markets.
- Wholesalers:McKesson and AmerisourceBergen maintaining inventory aggregation for retail pharmacy networks.
- Supermarkets:Mass merchandisers with limited pharmacy operations stocking over-the-counter famotidine formats.
Wholesalers retain the largest volume share; online pharmacies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thiazole derivative intermediates for famotidine synthesis concentrate in Asian chemical manufacturing corridors, with finished dose formulation distributed across regulated markets in North America, Europe, and Asia-Pacific.
United States
Hospital group purchasing organizations consolidate famotidine procurement through mandatory therapeutic interchange programs, compressing supplier margins. The FDA's ANDA bioequivalence requirements filter generic market entry for tablet and injectable formats. New Jersey and Pennsylvania host sterile injectable manufacturing facilities serving acute care networks.
India
CDSCO streamlined abbreviated new drug approvals enable export-ready generic production for regulated markets. The country's PLI scheme for active pharmaceutical ingredients attracts backward integration investments from formulation specialists. Hyderabad and Ahmedabad anchor high-volume tablet and oral suspension manufacturing for North American and European export.
Germany
EMA centralized marketing authorization procedures govern famotidine distribution across EU member states. REACH authorization requirements for thiazole derivative intermediates tighten environmental compliance for API sourcing operations. Frankfurt and Ludwigshafen chemical clusters handle crystallization and purification steps for European formulation supply.
China
NMPA generic consistency evaluation requirements reshape domestic market access for famotidine manufacturers. Dual carbon goals constrain energy-intensive multi-step organic synthesis operations. Zhejiang and Jiangsu provinces concentrate thiazole ring formation and guanidine substitution production for global API export.
Japan
PMDA post-market surveillance requirements intensify pharmacovigilance obligations for H2-antagonist drug-drug interaction labeling. METI industrial policy supports continuous manufacturing technology adoption for solid dose production. Osaka and Tokyo pharmaceutical corridors specialize in high-purity injectable formulations for domestic hospital networks.
Famotidine Market Vendor Landscape
Global majors compete with regional champions across formulation scale and API sourcing integration. The vendor base stratifies into three tiers: vertically integrated pharmaceutical conglomerates with captive active pharmaceutical ingredient production, high-volume generic specialists serving export markets, and regional formulation houses targeting domestic procurement channels. Dominant competitive moves include backward integration into thiazole intermediate manufacturing and long-term supply agreements with hospital group purchasing organizations.
Among Israel-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. exemplifies the vertically integrated archetype through in-house production of active pharmaceutical ingredients. Indian generic specialists Dr. Reddy's Laboratories Ltd. and Sun Pharmaceutical Industries Ltd. occupy positions as high-volume exporters to regulated markets, with manufacturing scale across multiple dosage formats. These three anchors represent distinct strategic postures in a market where bioequivalence documentation and procurement contracting determine competitive outcomes.
| Leading Market Players |
|---|
| Merck & Co. |
| Astellas Pharma Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Viatris |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Upsher-Smith Laboratories |
| Xiuzheng Pharmaceutical |
| Fujian Tianquan Pharmaceutical |
| Others |
Supply Flow & Price Mechanics
Thiazole derivative intermediate pricing indices cascade through famotidine supply chains into three distinct procurement tiers. Hospital group purchasing organizations leverage consolidated volume to compress supplier margins on generic tablet and injectable formats, while retail channels absorb higher per-unit costs through fragmented dispensing economics.
Pricing Analysis
Service-bundling separates bioequivalence documentation packages from bare API supply contracts in hospital procurement. Three-tier pricing structure across premium certified, standard approved, and economy unbundled levels reflects FDA ANDA tier differentiation and ICH Q7 compliance depth. Cost compression in the economy tier intensifies because therapeutic interchange programs mandate lowest-cost substitution. Retail pharmacies exhibit highest price sensitivity due to reimbursement lag; hospital systems with multi-year supply agreements demonstrate lowest sensitivity.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Zhejiang and Jiangsu provinces constrains thiazole ring formation capacity expansion. Bulk famotidine API production clusters in China, India, and Germany, drawing from guanidine derivatives, thiazole intermediates, and crystallization solvents. Single-source vulnerability runs through concentrated Asian intermediate manufacturing. Distribution runs through direct manufacturer-to-hospital contracts and wholesale aggregation for retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The famotidine market functions as a vertical-integration race where API sourcing security determines competitive survival. Players pursue backward control over thiazole intermediate manufacturing to escape supply concentration risk.
For Market Incumbents: Cement formulary position through multi-year supply agreements with US group purchasing organizations. Secure captive thiazole intermediate production in India or China to offset API supply concentration vulnerability. Proton pump inhibitor substitution pressure demands defensive H2-antagonist portfolio expansion into fixed-dose combination formats.
For New Entrants and Emerging Players: Enter via CDSCO streamlined ANDA pathway for export-ready generic production targeting regulated European and North American markets. Online pharmacy direct-to-patient fulfillment represents the most penetrable channel, bypassing wholesale margin extraction. Lead with pediatric oral suspension formats where formulation complexity filters competition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Indian generic specialists with sterile injectable capabilities in Hyderabad or Ahmedabad manufacturing corridors. Long-term viability hinges on 5-10 year regulatory convergence around bioequivalence standards and continuous manufacturing technology adoption. Watch FDA complete response letter cycle duration as inflection indicator for generic launch timing compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiazole Intermediates | Captive supply of guanidine derivatives insulates Teva and Dr. Reddy's from Asian API concentration risk. |
| Continuous Manufacturing Technology Adoption | Real-time release protocols at Sun Pharmaceutical reduce batch variability and FDA inspection exposure. |
| Hospital GPO Long-Term Supply Agreements | Multi-year contracts with US group purchasing organizations lock out competitors through therapeutic interchange mandates. |
| CDSCO ANDA Export Pathway Utilization | Streamlined Indian regulatory approvals enable rapid entry into regulated North American and European markets. |
| Fixed-Dose Combination Development | Co-formulation with antacids addresses PPI substitution pressure in gastroesophageal reflux disease maintenance therapy. |
Methodological Framework
Document review covered FDA ANDA filings, EMA centralized marketing authorization procedures, CDSCO abbreviated new drug approval databases, and hospital formulary placement records, complemented by interviews with generic pharmaceutical manufacturing executives, regulatory affairs directors, hospital procurement managers, and API sourcing specialists. Secondary validation drew from EPA pharmaceutical discharge compliance reports, ICH Q7 guideline documentation, and trade flow data for thiazole derivative intermediates. Bottom-up volume modeling triangulated against top-down therapeutic class expenditure analysis.
Cross-referencing historical generic substitution patterns with expert panel input on bioequivalence standard evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include dosage form, end-user channel, application indication, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation adjusted for therapeutic interchange program penetration and online pharmacy channel expansion rates. Forecast inputs incorporated API production capacity utilization at key Asian manufacturing sites and FDA ANDA approval velocity trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA discharge limit tightening or NMPA generic consistency evaluation disruption. Projections reflect assumptions on therapeutic interchange program adoption speed and continuous manufacturing technology validation timelines. Supply chain concentration in select Asian chemical corridors and evolving pharmacovigilance labeling requirements for H2-antagonist drug interactions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Spain OTC Drugs Market