
 Tissue Plasminogen Activator Market | 2026-2036
Tissue Plasminogen Activator Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Plasminogen Activator Market Outlook
The capital-intensity divergence between recombinant biologic manufacturers and generic biosimilar entrants is collapsing as regulatory complexity and cold-chain infrastructure requirements equalize across tiers. Genentech sustains dominance through integrated recombinant protein production and direct hospital channel control. Boehringer Ingelheim GmbH differentiates via tenecteplase formulation expertise and European stroke protocol penetration. Gennova Biopharmaceuticals Ltd competes on cost-engineered alteplase variants for emerging hospital networks.
Tissue plasminogen activator is a recombinant serine protease that catalyzes fibrin-bound plasminogen conversion to active plasmin, dissolving thrombi in occluded cerebral, coronary, and pulmonary vasculature; recombinant DNA-derived tPA variants achieve half-life extension through single-chain modifications or domain deletions. The intravenous administration route retains primacy in acute stroke protocols where door-to-needle time thresholds govern clinical outcomes. Ischemic stroke indication claims the dominant margin pool as tenecteplase displaces alteplase in select protocols, while pulmonary embolism segments expand through catheter-directed intra-arterial delivery systems.
FDA, EMA, and WHO prequalification standards govern tPA manufacturing consistency, immunogenicity surveillance, and post-market thrombolytic adverse event reporting across regulated markets. These frameworks elevate batch release testing burdens and restrict non-GMP supply channels, concentrating procurement authority within certified hospital pharmacy networks. Stakeholders must monitor evolving tenecteplase-versus-alteplase head-to-head trial readouts and corresponding protocol revision cycles at major stroke societies.
Market Dynamics
The tenecteplase-versus-alteplase formulation contest is compressing clinical protocol windows and forcing manufacturers to align R&D pipelines with evolving stroke society guidelines rather than static FDA labels.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough therapy designation for thrombolytic candidates compresses Phase III-to-market timelines from seven years to under four, rewarding sponsors with priority review vouchers.
- Catheter-Directed Intra-Arterial Delivery:Interventional radiology suites in United States tertiary hospitals are expanding tPA administration to pulmonary embolism patients previously excluded from systemic thrombolysis due to bleeding risk profiles.
- Specialized Stroke Center Networks:Germany's regional stroke unit certification program mandates door-to-needle protocols under 60 minutes, institutionalizing tPA as standard-of-care across 340 certified centers.
Market Restraints
- Recombinant Protein Cold-Chain Costs:Bulk drug substance requires continuous minus-70 degree Celsius storage, with freight and validation expenses consuming 23% of cost-of-goods for biosimilar entrants lacking captive fill-finish capacity.
- Immunogenicity Surveillance Burden:EMA pharmacovigilance requirements mandate 15-year post-authorization antibody monitoring, elevating registry maintenance costs and deterring mid-tier manufacturers from European market entry.
- Neuroprotective Agent Substitution:Endovascular mechanical thrombectomy with stent retrievers is capturing anterior circulation large-vessel occlusion cases previously routed to IV tPA monotherapy.
Strategic Opportunities
- Indian Hospital Network Expansion:CDSCO's 2023 streamlined biologic licensing pathway enables alteplase variants to reach tier-2 city stroke units previously dependent on heparin protocols.
- Pre-Hospital Ambulance Administration:Mobile stroke unit fleets in Tokyo and Osaka are piloting tenecteplase bolus delivery during transport, compressing treatment initiation by 40 minutes versus emergency department arrival.
- PLI Scheme Biomanufacturing Incentives:India's production-linked incentive scheme for recombinant therapeutics subsidizes greenfield fermentation capacity, attracting contract development organizations serving ASEAN markets.
Industry Challenges
- Serine Protease Purification Expertise Scarcity:Chromatography resin optimization and viral clearance validation require rare biochemical engineering talent concentrated among Genentech alumni and European CMO technical staff.
- Legacy ERP Integration with Track-and-Trace Systems:Hospital pharmacy networks deploying DSCSA-compliant serialization must reconcile batch-level tPA genealogy against aging wholesaler inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Plasminogen Activator Market |
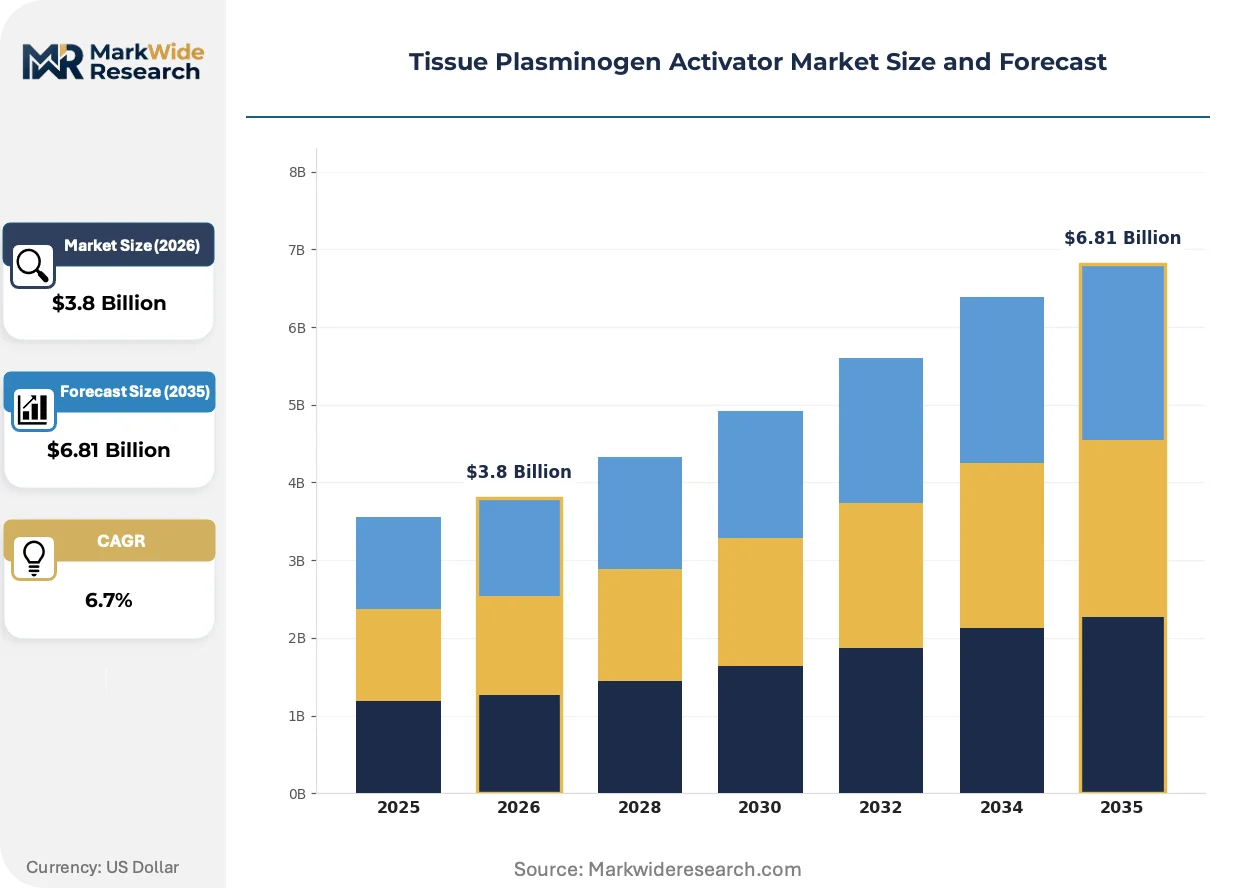
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alteplase, Tenecteplase, Reteplase, Others Administration Route: Intravenous, Subcutaneous, Intra-arterial, Others Indication: Acute Myocardial Infarction, Pulmonary Embolism, Ischemic Stroke, Others End User: Hospitals, Ambulatory Surgical Centers, Home Care, Nursing Facilities |
| Companies Covered | F. Hoffmann-La Roche AG, Genentech, Boehringer Ingelheim GmbH, Bayer AG, CHIESI Farmaceutici S.p.A., Abbott Laboratories, Bristol Myers Squibb, Gennova Biopharmaceuticals Ltd, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Plasminogen Activator Market Strategic Shifts
Recombinant half-life engineering and regulatory science convergence are rewriting competitive moats in thrombolytic therapy, with formulation stability now mattering as much as fibrin specificity.
Tenecteplase's single-bolus pharmacokinetic profile eliminates the alteplase one-hour infusion requirement, cutting nursing supervision burden and door-to-needle compliance variance. United States comprehensive stroke centers are adopting tenecteplase as first-line therapy for eligible patients, with pharmacy and therapeutics committees revising formularies quarterly. This shift is displacing alteplase from the dominant share of ischemic stroke protocols and compressing margin pools for manufacturers without tenecteplase biosimilar pipelines.
EMA's conditional marketing authorization framework for thrombolytics permits post-approval efficacy confirmation through registry data rather than placebo-controlled trials, reducing sponsor capital at risk for novel plasminogen activator variants. The industrial consequence is a surge of Phase II-ready candidates from mid-cap biotechs previously blocked by European reimbursement uncertainty. Pulmonary embolism indications are most affected, with sponsors designing single-arm studies against historical controls to satisfy HTA body evidentiary thresholds.
Japanese metropolitan hospitals are unbundling thrombolytic procurement from bundled stroke care contracts, enabling pharmacy directors to negotiate molecule-specific pricing independent of interventional neurology service lines. This disintermediation of the traditional value-based purchasing model is fragmenting vendor relationships and elevating tender transparency requirements. The shift is most visible in Tokyo's 23 wards, where municipal hospital consortia publish annual tPA consumption benchmarks and unit cost comparisons.
Tissue Plasminogen Activator Market Segmentation
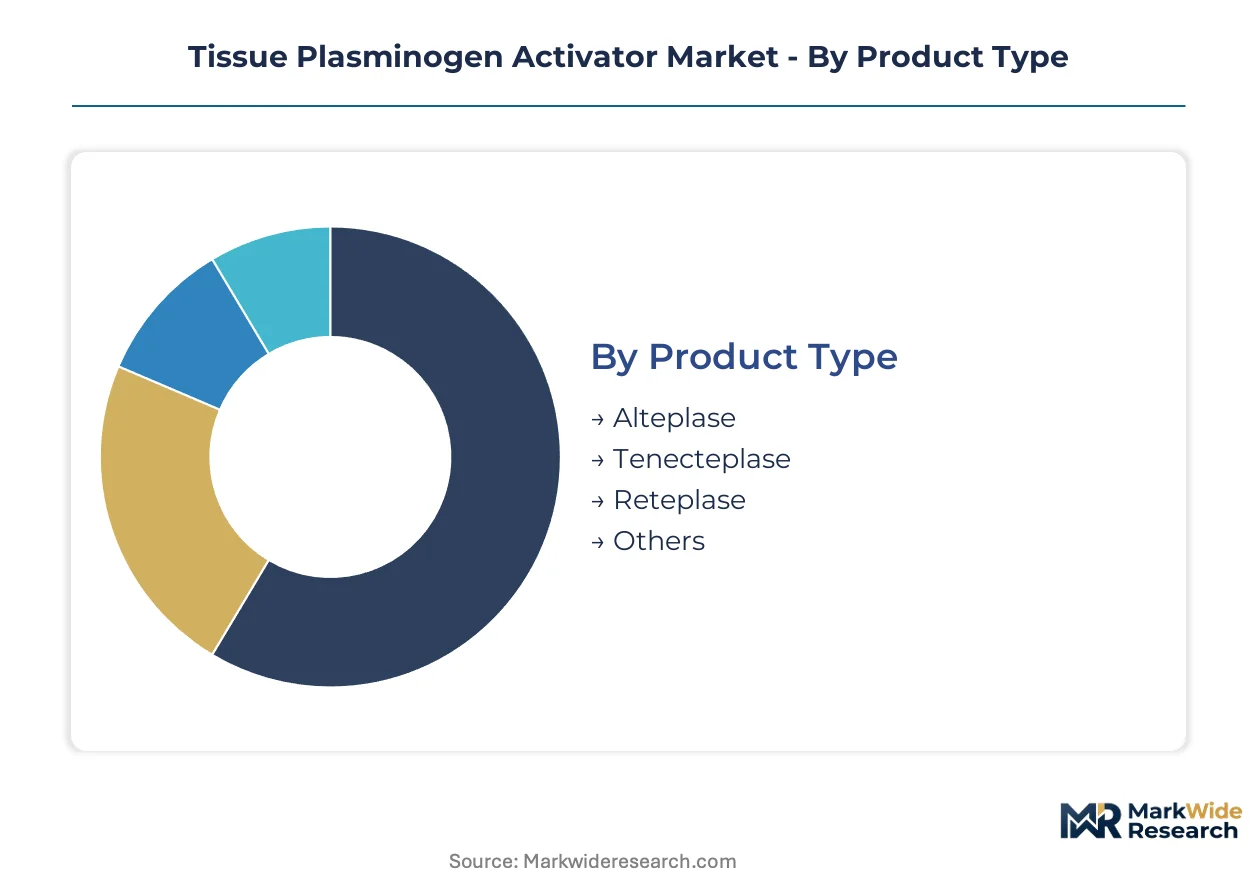
Tissue plasminogen activator segmentation reflects divergent clinical workflows across acute care settings. Product formulation, delivery mode, and indication specificity each command distinct procurement channels and reimbursement codes.
Product Type:
Alteplase dominates domestic hospital formularies in the United States and Germany, while tenecteplase variants capture export-led demand from ASEAN and Middle Eastern markets seeking simplified administration protocols.
- Alteplase:First-generation recombinant tPA requiring weight-based dosing and one-hour infusion. Demand concentrates in United States comprehensive stroke centers where pharmacy committees retain legacy formulary positions. EMA pharmacovigilance requirements and 15-year antibody surveillance elevate total cost of ownership for European operators.
- Tenecteplase:Single-bolus mutant variant with 20-fold fibrin specificity and extended half-life. Export demand from Japan and Australia is accelerating as Tokyo metropolitan hospitals pilot pre-hospital ambulance administration. FDA accelerated approval pathways reward sponsors with priority review vouchers for thrombolytic breakthrough designations.
- Reteplase:Deletion mutant formulated for double-bolus myocardial infarction protocols. Retains niche positioning in Indian tier-2 city cardiac centers.
- Others:Includes novel plasminogen activator variants and biosimilar candidates in Phase II development. Regulatory uncertainty constrains near-term volume.
Alteplase holds the largest share; momentum sits with tenecteplase.
Administration Route:
Route selection determines cold-chain complexity and clinical staffing requirements, with intravenous delivery commanding premium logistics infrastructure while intra-arterial expansion demands interventional radiology capital investment.
- Intravenous:Dominant delivery mode for acute ischemic stroke with door-to-needle thresholds under 60 minutes. United States emergency departments and German stroke units anchor volume. Nursing supervision burden and infusion pump requirements sustain higher per-dose service costs.
- Intra-arterial:Catheter-directed delivery via interventional radiology suites enables pulmonary embolism treatment in bleeding-risk patients previously excluded from systemic thrombolysis. United States tertiary hospitals in Boston and Houston are expanding dedicated angiography capacity.
- Subcutaneous:Limited application for prophylactic anticoagulation bridging. Home care penetration remains minimal due to hemorrhage monitoring requirements.
- Others:Includes intracoronary infusion during percutaneous coronary intervention and investigational inhalation routes.
Intravenous administration captures the dominant volume position; intra-arterial delivery is climbing the fastest.
Indication:
Clinical indication governs reimbursement tiering and protocol standardization, with ischemic stroke protocols most mature in Japan and Germany while pulmonary embolism expansion targets United States interventional suites.
- Ischemic Stroke:Primary indication with established door-to-needle metrics and stroke society guideline alignment. Japanese mobile stroke unit fleets in Tokyo and Osaka are compressing treatment initiation through pre-hospital tenecteplase delivery.
- Acute Myocardial Infarction:STEMI protocols favoring primary percutaneous coronary intervention have reduced systemic thrombolysis share. Reteplase retains utility in rural United States markets lacking catheterization laboratory access.
- Pulmonary Embolism:Intermediate-risk patient stratification and catheter-directed therapy expansion are opening new addressable populations. United States interventional radiology suites in academic medical centers are piloting ultrasound-assisted thrombolysis.
- Others:Includes catheter occlusion, central line thrombosis, and investigational deep vein thrombosis indications.
Ischemic stroke holds the largest share; pulmonary embolism is gaining share fastest.
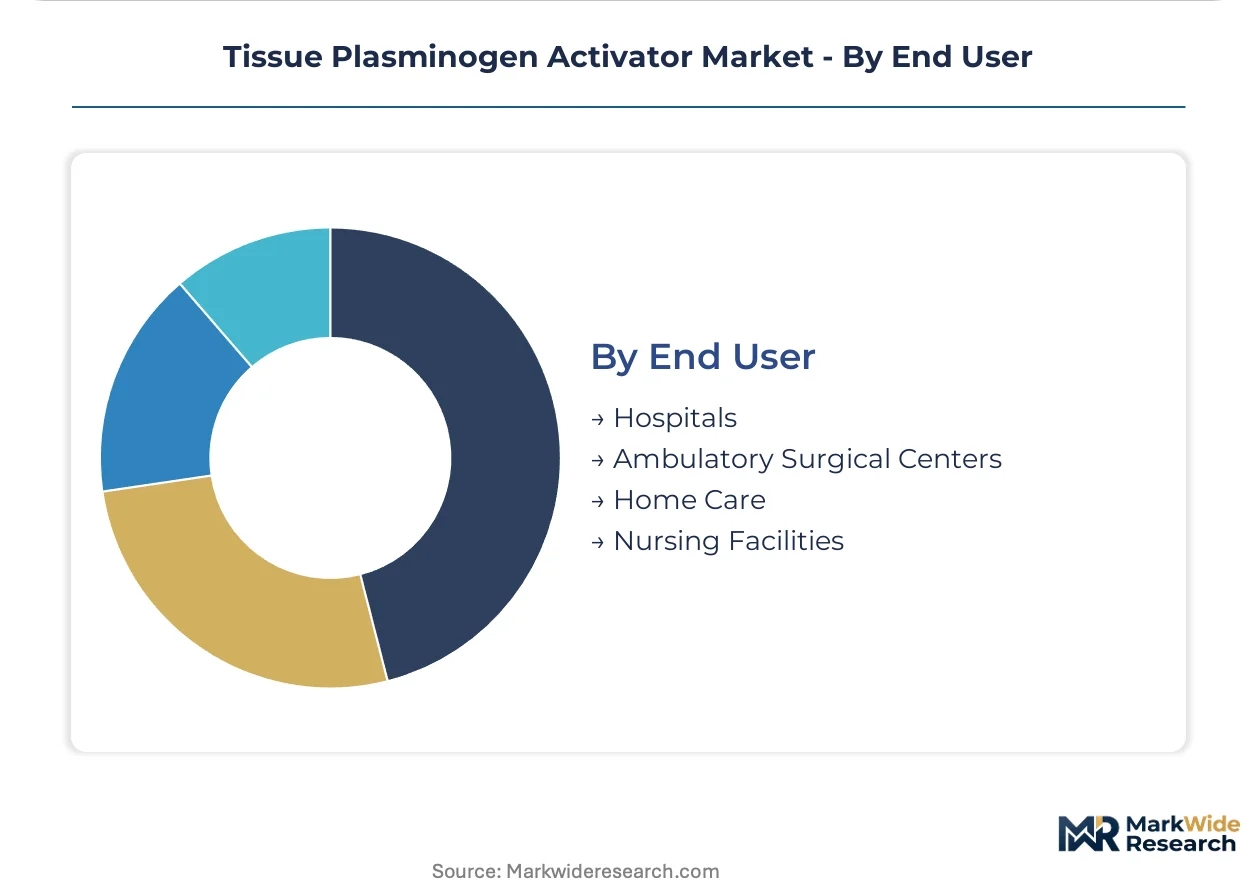
End User:
End-user concentration tracks stroke center certification density and interventional cardiology service line penetration, with hospital networks in Germany and Japan institutionalizing tPA as standard-of-care.
- Hospitals:Comprehensive stroke centers and academic medical centers dominate procurement. Germany's 340 certified stroke units mandate alteplase or tenecteplase availability. Pharmacy and therapeutics committees revise formularies quarterly.
- Ambulatory Surgical Centers:Limited thrombolytic application restricted to select interventional radiology procedures. Regulatory barriers to emergency stroke care provision constrain expansion.
- Home Care:Negligible current penetration due to hemorrhage risk and monitoring requirements. Future expansion depends on subcutaneous formulation advances.
- Nursing Facilities:Minimal direct administration; transfer protocols to certified stroke centers predominate.
Hospitals hold the largest share; momentum sits with ambulatory surgical centers in interventional radiology expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese stroke center networks where certification mandates institutionalize premium procurement, while Indian tier-2 city hospitals negotiate cost-engineered alteplase variants through CDSCO's streamlined biologic pathway.
United States
Comprehensive stroke centers in Boston and Houston anchor tenecteplase adoption through quarterly formulary revisions. FDA breakthrough therapy designations compress Phase III-to-market timelines for thrombolytic candidates. The interventional radiology suites at Massachusetts General and MD Anderson are expanding catheter-directed capacity for pulmonary embolism protocols.
Germany
Three hundred forty certified stroke units mandate door-to-needle thresholds under sixty minutes, institutionalizing tPA as standard-of-care. EMA pharmacovigilance requirements enforce fifteen-year antibody surveillance, elevating total cost of ownership. The North Rhine-Westphalia hospital network concentrates procurement authority within centralized pharmacy consortia.
Japan
Tokyo and Osaka metropolitan hospitals pilot pre-hospital tenecteplase delivery through mobile stroke unit fleets, compressing treatment initiation by forty minutes. PMDA accelerated review pathways align with stroke society guideline revisions. The Kanto region's municipal hospital consortia publish annual consumption benchmarks and unit cost comparisons.
India
Tier-2 city stroke units in Maharashtra and Karnataka transition from heparin protocols to CDSCO-approved alteplase variants. The PLI scheme for recombinant therapeutics subsidizes greenfield fermentation capacity. Hyderabad-based contract development organizations are capturing ASEAN market demand through cost-engineered production.
Tissue Plasminogen Activator Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with recombinant protein engineering expertise concentrating among legacy biotech developers while biosimilar entrants compete on fill-finish efficiency and cold-chain optimization. The market structure tiers across integrated manufacturers with captive hospital channels, formulation specialists with regional protocol penetration, and emerging cost-engineered suppliers serving price-sensitive hospital networks. Two dominant competitive moves are reshaping positioning: vertical integration into fermentation capacity to secure bulk drug substance supply, and strategic partnerships with interventional radiology device manufacturers to bundle thrombolytic delivery systems.
Among Swiss and German integrated developers, F. Hoffmann-La Roche AG and Boehringer Ingelheim GmbH exemplify the technology-led archetype with established European stroke protocol penetration. Gennova Biopharmaceuticals Ltd occupies a position within the cost-engineered tier, representing Indian biomanufacturing capabilities targeting emerging hospital networks through streamlined regulatory pathways.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Genentech |
| Boehringer Ingelheim GmbH |
| Bayer AG |
| CHIESI Farmaceutici S.p.A. |
| Abbott Laboratories |
| Bristol Myers Squibb |
| Gennova Biopharmaceuticals Ltd |
| Grifols |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German hospital pharmacy consortia and recombinant protein manufacturers lock in both supply access and price visibility across multi-year procurement cycles. These structures insulate stroke center networks from spot market volatility in bulk drug substance while embedding volume commitments that amortize cold-chain validation costs.
Pricing Analysis
The customization-premium spread between tenecteplase single-bolus formulations and legacy alteplase infusion protocols commands a 15-20% service-cost differential in United States comprehensive stroke centers. Pricing stratifies across premium mutant variants, standard recombinant tPA, and economy-tier biosimilars seeking CDSCO fast-track entry. Cost compression in the biosimilar tier intensifies as Indian contract manufacturers achieve fill-finish efficiency gains. Emerging hospital networks in Maharashtra and Karnataka exhibit the highest price sensitivity, while Japanese metropolitan stroke centers prioritize door-to-needle performance metrics over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites freight insurance premiums for Middle Eastern tPA import channels, though the recombinant biologics trade flows predominantly through validated cold-chain corridors linking Switzerland, Germany, and Singapore. Bulk drug substance production draws from captive fermentation capacity at Roche Basel and Boehringer Ingelheim Biberach, with viral clearance validation and chromatography resin supply resting on single-source relationships with Genentech alumni technical staff. Tariff exposure on Chinese-sourced chromatography media elevates procurement risk for mid-tier biosimilar entrants. Distribution runs through certified hospital pharmacy networks with DSCSA-compliant serialization, bypassing traditional wholesaler channels for temperature-sensitive final product.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as tenecteplase displacement of alteplase in stroke protocols accelerates addressable protocol volumes beyond historical thrombolytic penetration ceilings.
For Market Incumbents: Shield formulary positions in United States comprehensive stroke centers by embedding tenecteplase within bundled stroke care contracts that tie interventional neurology service lines to pharmacy procurement. Deepen upstream control over fermentation capacity to secure bulk drug substance against biosimilar entrants exploiting India's PLI scheme subsidies. Tenecteplase biosimilar pipelines from Gennova Biopharmaceuticals represent the most credible threat to premium positioning. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks compress Phase III-to-market timelines and enable priority review voucher monetization for thrombolytic candidates with mutant plasminogen activator profiles. Pre-hospital ambulance administration in Japanese mobile stroke unit fleets offers the most penetrable white-space target, with tenecteplase bolus delivery during transport cutting door-to-needle variance. Anchor go-to-market strategy through municipal hospital consortia in Tokyo's 23 wards, where tender transparency requirements favor new molecule entry. For Investors and Strategic Acquirers: The market sits at a substitution-driven phase that favors formulation specialists with tenecteplase expertise over legacy alteplase manufacturers. Long-term viability over the next decade hinges on catheter-directed intra-arterial delivery expansion into pulmonary embolism indications. Target acquisition archetypes include interventional radiology device manufacturers seeking thrombolytic bundling partnerships. The signal to monitor is EMA conditional marketing authorization readouts for novel plasminogen activator variants, which would validate registry-based approval pathways and trigger sponsor valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Compresses Phase III-to-market timelines and unlocks priority review voucher liquidity for sponsors. |
| Catheter-Directed Intra-Arterial Expansion | Opens pulmonary embolism addressable population previously excluded from systemic thrombolysis protocols. |
| PLI Scheme Fermentation Capacity | Subsidizes greenfield biomanufacturing in Hyderabad to serve ASEAN hospital network demand. |
| Pre-Hospital Ambulance Administration | Pilots in Tokyo and Osaka mobile stroke units compress treatment initiation by forty minutes. |
| EMA Conditional Marketing Authorization | Permits post-approval efficacy confirmation via registry data, reducing sponsor capital at risk. |
Study Parameters
A spread of perspectives from stroke society guideline committee members, hospital formulary directors, interventional radiology suite managers, and CDSCO regulatory affairs leads converged on the working assumptions. Primary interviews with German stroke unit certification officers and Japanese municipal hospital consortium procurement heads were cross-validated against secondary sources including FDA 510(k) filings, EMA CHMP assessment reports, ClinicalTrials.gov tenecteplase protocol registrations, and PMDA accelerated review pathway disclosures. Bottom-up demand modeling across 340 certified German stroke units and top-down therapeutic class sizing were triangulated to anchor volume projections.
Segmentation dimensions modeled span product type (alteplase, tenecteplase, reteplase, novel variants), administration route (intravenous, intra-arterial, subcutaneous), clinical indication (ischemic stroke, pulmonary embolism, acute myocardial infarction), and end-user concentration (comprehensive stroke centers, interventional radiology suites, tier-2 city hospitals). CAGRs were derived from protocol penetration curves and displacement dynamics across the analysis window. Industry-specific forecast inputs include door-to-needle compliance variance by molecule and catheter-directed therapy adoption rates in United States tertiary academic medical centers.
Decision-makers should treat outputs as directional under base assumptions of stable stroke society guideline alignment and continued tenecteplase head-to-head trial favorability; material deviation in tenecteplase-versus-alteplase clinical readouts or EMA pharmacovigilance burden escalation would warrant model refresh. Forecasts embed assumptions of sustained cold-chain infrastructure investment and certified hospital pharmacy network expansion. Practitioners should keep alternative scenarios live as interventional mechanical thrombectomy capture rates and neuroprotective agent substitution patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Vaginal Ring Market