
 Global Polio Vaccines Market | 2026-2036
Global Polio Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polio Vaccines Market Intelligence
The progressive replacement of live attenuated poliovirus with inactivated strains is shifting the manufacturing and cost structure for polio vaccines. Sanofi leverages its extensive experience in inactivated vaccine production to supply global markets. GSK plc competes through its portfolio of combination vaccines that include polio components. Serum Institute of India sustains its market position through high-volume manufacturing for public health programs.
Polio vaccines are biological preparations designed to induce immunity against the poliovirus. These formulations contain either live attenuated virus strains for oral administration or inactivated virus antigens for injection, both stimulating the production of protective antibodies. While Oral Poliovirus Vaccine (OPV) remains critical for outbreak response, the market is structurally moving toward Inactivated Poliovirus Vaccine (IPV) for routine immunization. The infant target population segment accounts for the vast majority of volume, driven by national childhood vaccination schedules.
The World Health Organization's prequalification program is essential for vaccine procurement by global health bodies like UNICEF. National regulators, including the US FDA and the European Medicines Agency, enforce stringent standards for vaccine licensure, ensuring safety and efficacy. Stakeholders must navigate the complex logistical and financial requirements of transitioning entire populations to IPV-containing schedules to achieve final eradication goals.
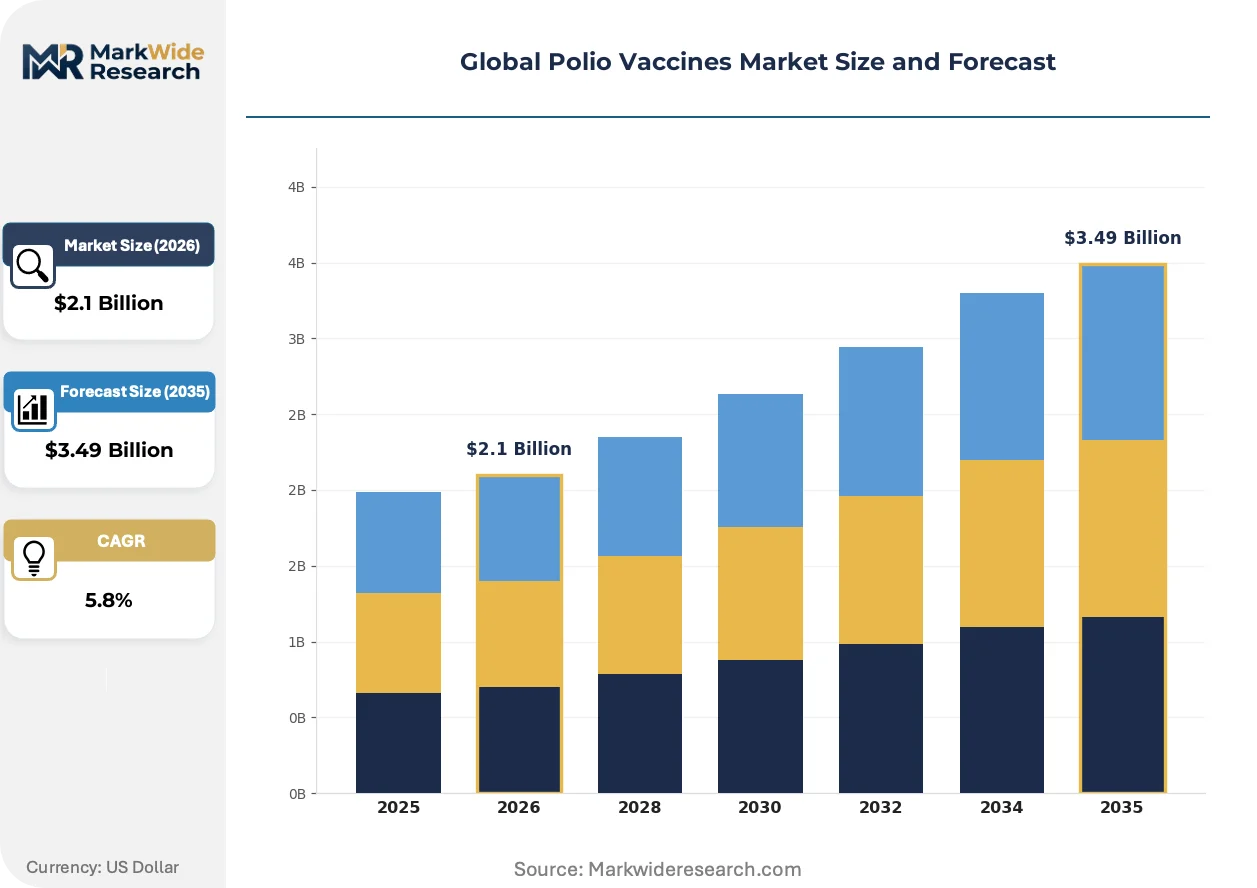
Market Dynamics
The global polio eradication endgame strategy, which mandates a phased withdrawal of oral poliovirus vaccine (OPV) and a synchronized switch to inactivated poliovirus vaccine (IPV), is the central force governing market structure, investment, and product development priorities.
Growth Catalysts
- Global Eradication Policy:The WHO's Global Polio Eradication Initiative (GPEI) strategic plan provides a clear roadmap and funding mechanism for countries to introduce at least one dose of IPV into routine immunization schedules, creating sustained, policy-driven demand.
- High-Volume Public Procurement:National immunization programs in countries with large annual birth cohorts, such as India, Nigeria, and Pakistan, represent the largest volume purchasers, procuring vaccines through tenders supported by global health organizations like Gavi.
- Combination Vaccine Development:The inclusion of IPV components in pentavalent and hexavalent vaccines simplifies logistics for healthcare providers and improves compliance with childhood vaccination schedules, driving uptake of IPV-containing products in middle-income countries.
Market Restraints
- Higher IPV Manufacturing Cost:The production of inactivated poliovirus vaccine is significantly more complex and expensive than that of oral poliovirus vaccine, placing a financial burden on the budgets of low-income countries and global health funders.
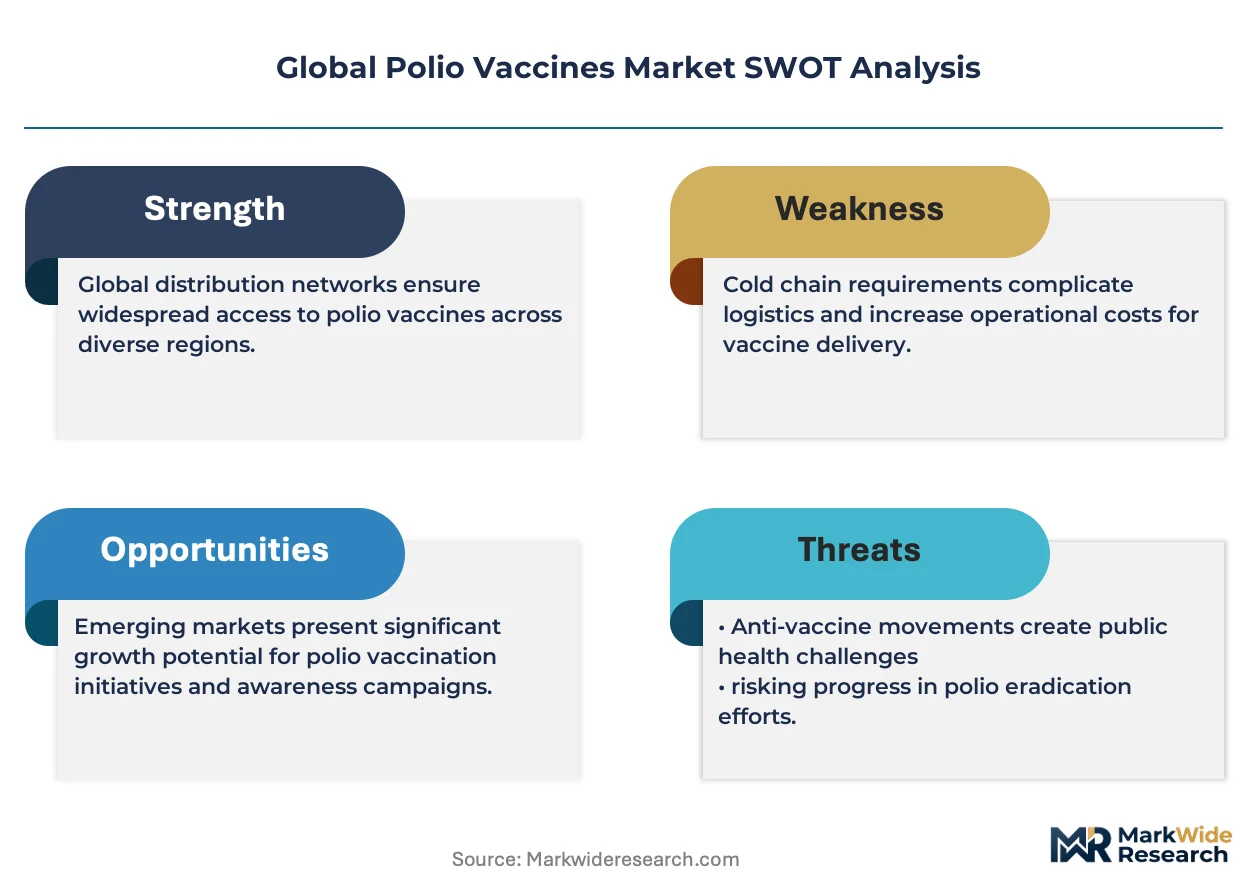
- Concentrated Production Base:Manufacturing capacity for WHO-prequalified IPV is concentrated among a small number of producers, creating risks of supply shortages or disruptions that could impact global immunization timelines and outbreak response capabilities.
- Cold Chain Requirements:Unlike the heat-stable OPV, IPV requires a stringent and unbroken cold chain for storage and transport, posing a significant logistical and infrastructural barrier in regions with limited public health resources.
Strategic Opportunities
- Novel Vaccine Formulations:The development and deployment of novel oral poliovirus vaccine type 2 (nOPV2), which is more genetically stable than its predecessor, presents a major opportunity to more effectively combat circulating vaccine-derived poliovirus outbreaks.
- Fractional Dosing Strategies:The adoption of fractional-dose IPV (fIPV) regimens, which use a smaller amount of vaccine administered intradermally, allows countries to stretch limited vaccine supplies and reduce per-dose costs, expanding access.
- IPV Introduction in New Geographies:There is significant opportunity in supporting the final cohort of countries in Africa and Asia to complete the full transition to IPV-containing routine immunization schedules as they phase out OPV entirely.
Industry Challenges
- Dual Vaccine Logistics:Managing parallel supply chains for both IPV for routine immunization and OPV for outbreak response activities creates significant complexity for national logistics and public health program managers during the transition phase.
- Capital-Intensive Facility Conversion:Shifting manufacturing from live attenuated to inactivated virus production requires substantial capital investment in new BSL-3 containment facilities and purification technologies, presenting a high barrier to entry for new producers.
- Vaccine Hesitancy:Overcoming misinformation and ensuring high levels of community acceptance and participation in vaccination campaigns remains a persistent operational challenge, particularly in conflict-affected regions or areas with low trust in public institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polio Vaccines Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated Poliovirus Vaccine, Oral Poliovirus Vaccine, Monovalent Vaccine, Bivalent Vaccine, Trivalent Vaccine Target Population: Infants, Toddlers, Adolescents, Adults, Travelers Application Setting: Immunization Centers, Community Health Programs, Pharmacies, Travel Clinics, Emergency Response Units Distribution Channel: Public Healthcare Systems, Private Clinics, Hospitals, Non-governmental Organizations, Mobile Health Units |
| Companies Covered | Sanofi, GSK plc, Serum Institute of India, Pfizer, Bharat Biotech, Beijing Tiantan Biological Products, Merck & Co., Bio Farma, Panacea Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polio Vaccines Market Strategic Shifts & Innovations
The industrial and scientific response to the final stages of polio eradication is reshaping the market. This involves balancing the need for routine immunization with IPV against the necessity for rapid, effective outbreak response using next-generation oral vaccines.
Combination vaccines that integrate multiple antigens, including IPV, into a single shot are a key product evolution. National immunization programs adopt these formulations to reduce the number of injections required for infants. This technology is expanding into routine pediatric schedules, simplifying logistics and improving compliance.
The World Health Organization's prequalification program serves as a critical gatekeeper for market access. This process ensures vaccines procured by agencies like UNICEF meet strict quality and efficacy standards. The PQ requirement is forcing new manufacturers to invest heavily in quality systems to supply global tenders.
A notable change is occurring in purchasing models for large-scale programs. Global health bodies are using multi-year supply agreements with volume guarantees to secure IPV supply and stabilize pricing. This model is most visible in procurement for national programs in sub-Saharan Africa and South Asia.
Global Polio Vaccines Market Segmentation
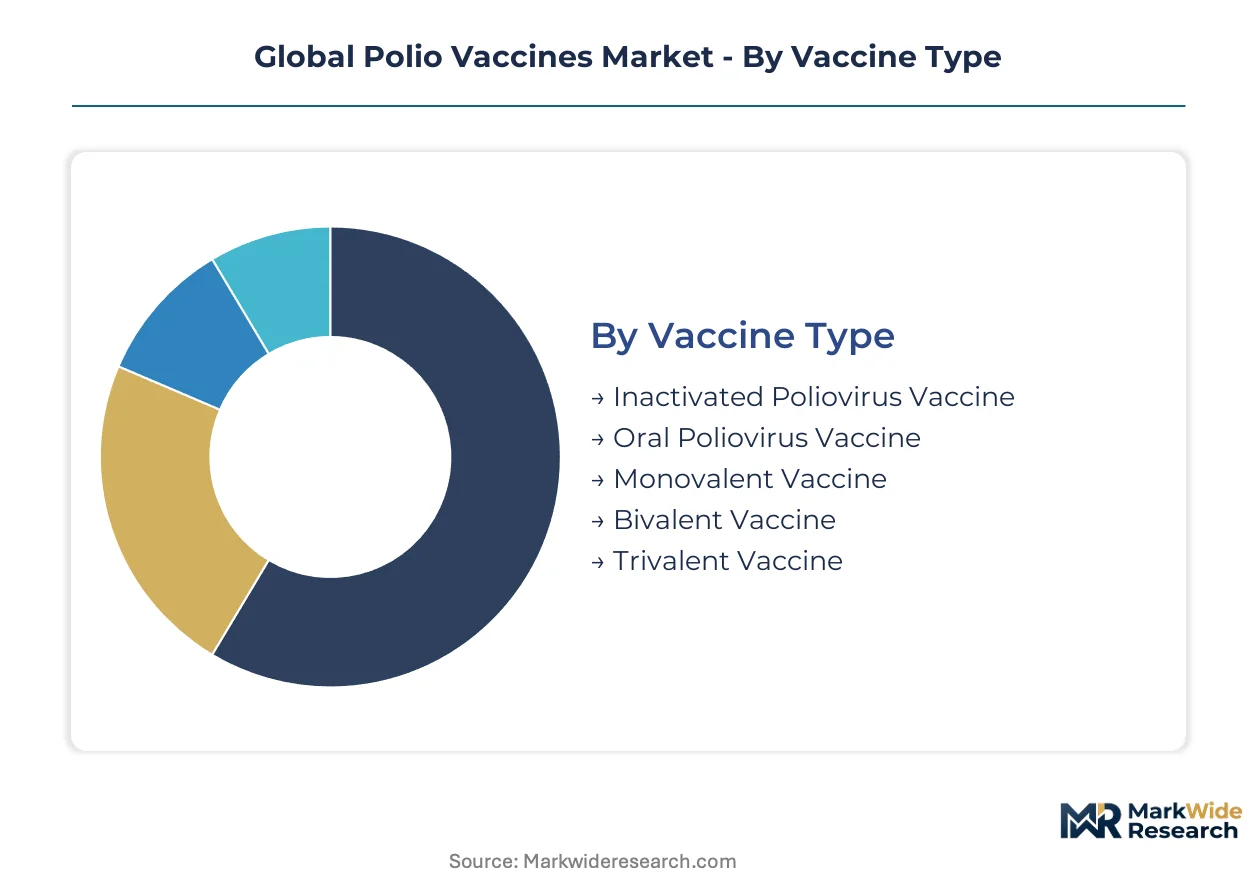
Segmentation within the global polio vaccines market illuminates the diverse product requirements and strategic priorities driving vaccine development and deployment. Understanding these distinct segments is crucial for stakeholders to align manufacturing capabilities with public health needs and global eradication targets.
Vaccine Type:
The market for polio vaccines differentiates based on viral strain and formulation technology. These distinctions influence administration routes, efficacy, and strategic deployment in eradication efforts.
- Inactivated Poliovirus Vaccine (IPV):This vaccine contains killed poliovirus, administered via injection, inducing humoral immunity. Demand grows as WHO policy transitions routine immunization programs away from live attenuated vaccines.
- Oral Poliovirus Vaccine (OPV):This vaccine comprises live attenuated poliovirus strains, given orally, generating both humoral and intestinal immunity. OPV remains crucial for rapid outbreak response due to ease of administration.
- Monovalent Vaccine:This vaccine targets a single poliovirus serotype, primarily used for targeted outbreak response against specific strains.
- Bivalent Vaccine:This vaccine protects against two poliovirus serotypes, types 1 and 3, widely used in routine immunization schedules.
- Trivalent Vaccine:This vaccine offers protection against all three poliovirus serotypes, though its use phases out for bivalent and IPV formulations.
Oral Poliovirus Vaccine leads on scale for outbreak response; Inactivated Poliovirus Vaccine leads on momentum for routine immunization.
Target Population:
Volume consumption for polio vaccines is shaped by target age groups, reflecting national immunization schedules and public health campaigns.
- Infants:This segment represents the primary recipients of polio vaccines globally, integrated into national childhood immunization programs. High birth cohorts in countries like India and Nigeria drive significant procurement.
- Toddlers:Children in this age group receive booster doses, reinforcing initial immunity acquired during infancy. Compliance with booster schedules is critical for sustained protection.
- Adolescents:Select populations or those in high-risk areas may receive polio booster doses during adolescence.
- Adults:Adults typically receive vaccination if unimmunized, traveling to endemic regions, or working in healthcare settings.
- Travelers:Individuals journeying to countries where poliovirus circulates require proof of vaccination or booster doses.
Infants dominate volume; travelers demonstrate consistent, albeit smaller, demand for specific protection.
Application Setting:
The application setting dictates operational logistics and patient access points for polio vaccine administration across healthcare infrastructures.
- Immunization Centers:These dedicated facilities serve as central hubs for routine childhood vaccination programs. They manage cold chain storage and administer doses to large patient volumes.
- Community Health Programs:These outreach initiatives deliver vaccines directly to underserved populations, particularly in rural or remote areas. These programs achieve high vaccination coverage.
- Pharmacies:In some countries, pharmacies administer vaccines, offering convenient access for adult boosters or travel-related immunizations.
- Travel Clinics:These specialized clinics provide pre-travel health consultations and vaccinations, including polio, for individuals visiting at-risk regions.
- Emergency Response Units:These units deploy rapidly during poliovirus outbreaks to conduct mass vaccination campaigns, often using oral poliovirus vaccines.
Largest patient throughput occurs within immunization centers; emergency response units focus on targeted outbreak interventions.
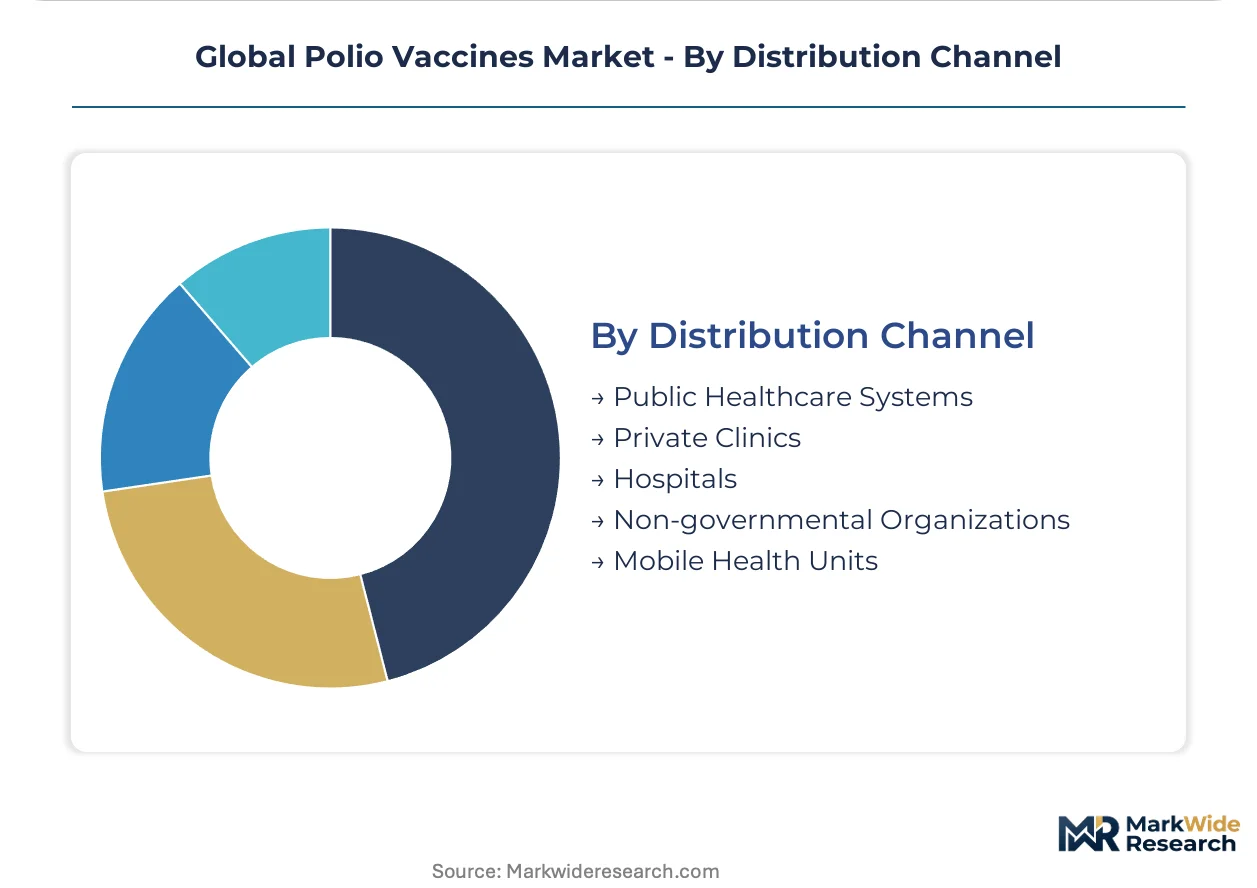
Distribution Channel:
Supply concentration within distribution channels determines how polio vaccines reach target populations, impacting accessibility and program efficiency.
- Public Healthcare Systems:Government-managed health networks are the primary channel for procuring and distributing polio vaccines for national immunization programs. This ensures widespread access.
- Private Clinics:These facilities cater to individuals seeking private healthcare, often providing IPV as part of comprehensive pediatric or adult vaccination schedules.
- Hospitals:Hospitals administer polio vaccines to newborns and patients requiring immunization during their stay.
- Non-governmental Organizations:Organizations like UNICEF and Gavi play crucial roles in funding, procuring, and distributing vaccines to countries with significant public health needs.
- Mobile Health Units:These flexible units extend vaccine delivery to remote communities, overcoming geographical barriers and improving coverage rates.
Government-led initiatives manage bulk distribution; non-governmental organizations provide critical supplemental access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune, India, functions as a significant hub for polio vaccine manufacturing and global supply. This region's influence extends across various national immunization programs. The global market for polio vaccines exhibits distinct regional dynamics. These dynamics are shaped by local disease burden and regulatory frameworks.
India
India's large annual birth cohort drives substantial demand for polio vaccines. The Central Drugs Standard Control Organization (CDSCO) oversees vaccine quality and distribution within the country. Pune, a major pharmaceutical cluster, hosts high-volume manufacturing facilities, contributing significantly to global public health initiatives.
Nigeria
Nigeria represents a critical demand center due to its high birth rates and ongoing polio eradication efforts. The National Primary Health Care Development Agency (NPHCDA) guides routine immunization schedules. Abuja serves as a key logistical hub for vaccine distribution, supporting national health programs and UNICEF-backed campaigns.
China
China maintains significant demand for polio vaccines, integrated into its routine childhood vaccination program. The National Medical Products Administration (NMPA) rigorously regulates vaccine licensure and domestic production. Beijing functions as a central point for vaccine R&D and policy formulation, with major manufacturers like Beijing Tiantan Biological Products.
Pakistan
Pakistan faces persistent challenges in polio eradication, necessitating continuous high-volume vaccine procurement. The Drug Regulatory Authority of Pakistan (DRAP) oversees vaccine imports and national immunization campaigns. Karachi, a major urban center, serves as a crucial point for mass vaccination drives and logistical coordination.
United States
The United States primarily utilizes inactivated poliovirus vaccine (IPV) for its routine childhood immunization schedule. The Food and Drug Administration (FDA) enforces stringent standards for vaccine safety and efficacy. The Boston/Cambridge biotech cluster is a hub for advanced vaccine research and development, including novel polio formulations.
Global Polio Vaccines Market Key Industry Players
Global majors compete with regional champions across manufacturing capacity and market access within the polio vaccines market. The industry structure shows concentration among a few large multinational pharmaceutical companies. Strategic archetypes include high-volume public health suppliers and specialized research-driven developers. Dominant competitive moves involve capacity expansion and strategic partnerships for global distribution.
Among multinational pharmaceutical companies, Sanofi and GSK plc exemplify established players with diverse vaccine portfolios. Sanofi leverages its extensive experience in inactivated vaccine production to supply global markets, often participating in large-scale tenders. GSK plc competes through its portfolio of combination vaccines, integrating polio components into broader pediatric immunization schedules. Serum Institute of India, a prominent manufacturer, occupies a position as a high-volume supplier for public health programs, particularly in developing nations, anchoring significant global supply.
| Leading Market Players |
|---|
| Sanofi |
| GSK plc |
| Serum Institute of India |
| Pfizer |
| Bharat Biotech |
| Beijing Tiantan Biological Products |
| Merck & Co. |
| Bio Farma |
| Panacea Biotec |
| Others |
Cost & Logistics Intelligence
National immunization programs represent a concentrated buyer archetype, influencing pricing models through large-scale, tender-based procurement. This dynamic shapes how manufacturers structure their offerings and manage production costs.
Pricing Analysis
Input-cost pass-through mechanisms are increasingly relevant as inactivated poliovirus vaccine (IPV) production costs exceed oral poliovirus vaccine (OPV). The dominant pricing model for public procurement is contract-based long-term offtake with volume guarantees. Price differentiation drivers include WHO prequalification status and the complexity of combination vaccine formulations. Pricing softness stems from the high-volume public procurement by global health organizations. Low-income countries and their funding bodies are highly price-sensitive, while private clinics catering to travelers exhibit lower sensitivity.
Supply Chain Analysis
National pharmaceutical regulators, through local content mandates, are reshaping sourcing strategies for polio vaccines. Geographic supply concentration centers on India, France, and the UK for high-volume manufacturing. Raw material dependencies include cell culture media, viral antigens, and specialized purification chemicals. A structural supply chain risk is the concentrated production base for WHO-prequalified IPV, creating potential single-source vulnerabilities. Vaccine distribution runs primarily through public healthcare systems, supplemented by non-governmental organizations in underserved regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the strategic transition to higher-value inactivated poliovirus vaccines and the adoption of cost-reducing fractional dosing regimens.
For Market Incumbents:Acquire specialized manufacturing capabilities for inactivated poliovirus vaccine (IPV) production to meet escalating global demand. Expand BSL-3 compliant facilities and invest in advanced purification technologies to mitigate concentrated production risks. Form strategic partnerships with logistics providers to strengthen cold chain distribution networks in challenging geographies. This defends against supply disruptions and ensures market access for IPV products.
For New Entrants and Emerging Players:Enter via niche product development, focusing on novel oral poliovirus vaccine type 2 (nOPV2) formulations for targeted outbreak response. The most penetrable segment for new players involves specialized solutions for specific poliovirus serotypes. A viable go-to-market angle involves collaborating with global health organizations for rapid deployment in emergency situations. This strategy leverages innovation where established players may have less flexibility.
For Investors and Strategic Acquirers:Global health organizations are the most active acquirers in this space, driven by eradication goals and sustained demand for IPV. The long-term viability of the market is anchored in routine immunization schedules for infants over the next decade. Acquisition target archetypes include manufacturers with WHO-prequalified IPV production facilities or robust combination vaccine pipelines. Expansion of IPV production capacity or new WHO prequalification approvals are key signals to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | New nOPV2 formulations offer more stable outbreak response capabilities. |
| Manufacturing Scale-Up | Expanding IPV production capacity meets rising routine immunization demand. |
| Licensing Agreement | Accelerates market entry for novel vaccine technologies in key regions. |
| Strategic Partnership | Secures distribution channels and market access in high-need countries. |
| Regulatory Approval Pathway | Achieving WHO prequalification unlocks global procurement opportunities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing market sizing and trend analysis. Primary insights came from public health officials, vaccine manufacturers, supply chain logistics managers, and national immunization program directors. Secondary validation drew from WHO reports, UNICEF procurement data, national health agency publications, and company financial filings. Bottom-up and top-down triangulation ensured data integrity.
The forecast framework anchored historical reference periods to project market growth over the projection horizon. Segmentation dimensions modeled included vaccine type, target population, application setting, distribution channel, and regional regulatory cluster. Compound annual growth rates were derived from historical growth patterns and projected policy shifts. Global eradication policy mandates and birth cohort demographics served as key forecast inputs.
Inputs from WHO policy documents and national immunization reports were available through the study window; gaps in real-time outbreak data and specific country-level procurement prices introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical stability and the absence of unexpected viral mutations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Critical Care Therapeutics Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Diuretic Drugs Market