
 Global Pneumococcal Vaccines Market | 2026-2036
Global Pneumococcal Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pneumococcal Vaccines Market Foresight
Biopharmaceutical manufacturing capacity in India and South Korea is hardening as regional governments prioritize vaccine sovereignty. Pfizer Inc. leverages its decades-long R&D intensity in conjugate chemistry to sustain premium positioning across OECD markets. Merck & Co., Inc. anchors its competitiveness through manufacturing scale at its West Point facility, while Serum Institute of India Pvt. Ltd. dominates volume economics by supplying UNICEF and Gavi at sub-dollar per-dose pricing.
Pneumococcal vaccines are sterile biological preparations containing purified capsular polysaccharides from Streptococcus pneumoniae, either conjugated to protein carriers or presented in unconjugated form, designed to induce protective antibodies against invasive pneumococcal disease. The manufacturing process requires fermentation, polysaccharide purification, protein conjugation, and extensive lot-release testing that stretches production timelines to 18-24 months. Pneumococcal conjugate vaccines command the largest revenue share due to superior immunogenicity in infants and WHO inclusion in routine immunization schedules. Recombinant technology represents the fastest-evolving segment as developers pursue next-generation serotype coverage without fermentation bottlenecks.
The FDA, EMA, and WHO prequalification program collectively shape market access through divergent stability requirements and post-marketing surveillance obligations. India's CDSCO and South Korea's MFDS are tightening local clinical trial mandates for imported vaccines, redirecting sponsor investment toward regional manufacturing footprints. Stakeholders must monitor serotype replacement patterns and regulatory convergence on conjugate-to-polysaccharide switching protocols as determinants of future portfolio composition.
Market Dynamics
Serotype replacement pressure and WHO prequalification acceleration are compressing traditional 18-24 month production cycles while forcing manufacturers to choose between premium OECD positioning and high-volume Gavi supply. This structural tension between speed, cost, and immunogenicity coverage defines current competitive moves.
Growth Catalysts
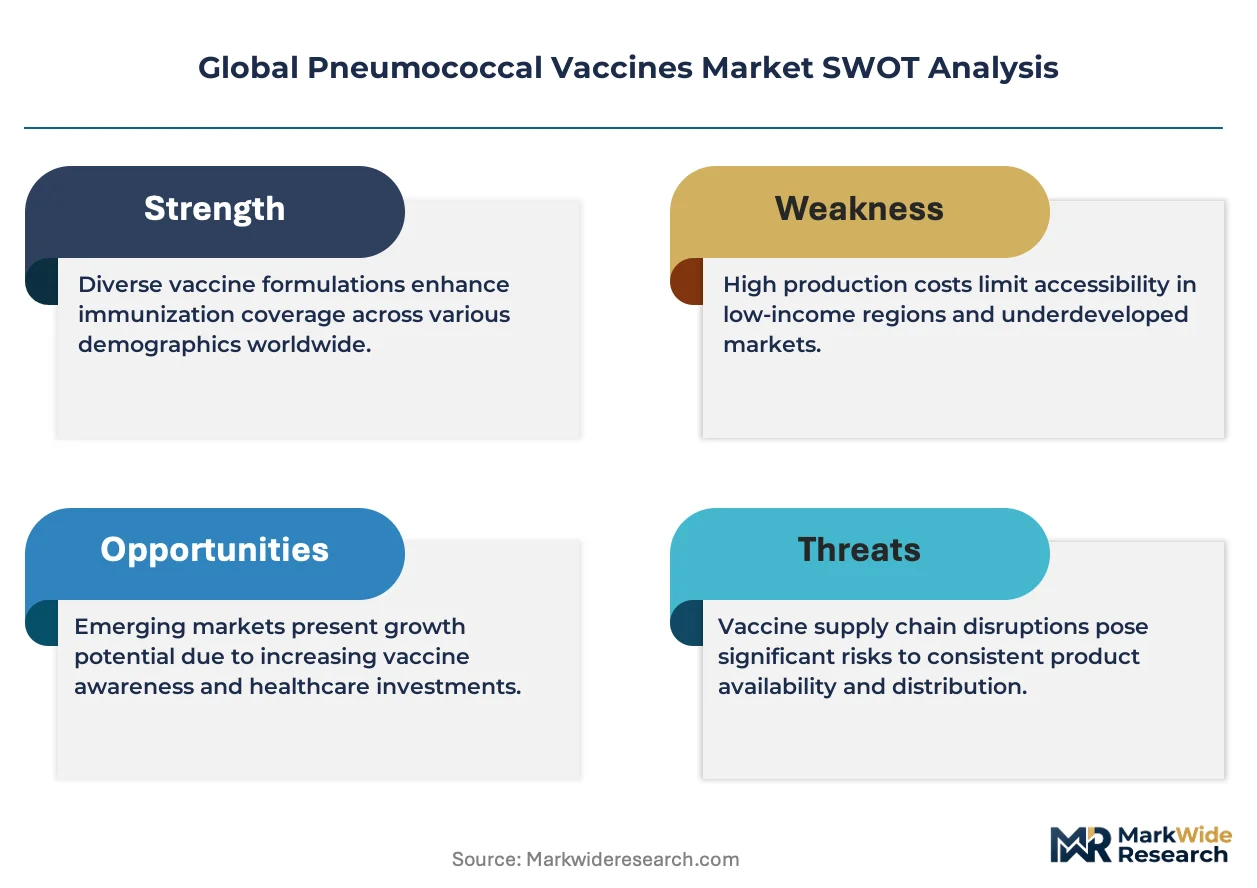
- WHO Prequalification Pathway:Accelerated review timelines for conjugate vaccines are unlocking procurement eligibility across 70+ low-income national immunization programs previously dependent on polysaccharide alternatives.
- India's Universal Immunization Programme:Government tenders for pneumococcal conjugate inclusion in routine pediatric schedules are generating sustained multi-year demand commitments at population scale.
- Recombinant Protein Synthesis:Cell-free expression systems are circumventing fermentation bottlenecks that constrain polysaccharide yield, shortening candidate-to-clinic timelines for expanded serotype coverage.
Market Restraints
- Fermentation Capacity Concentration:Bulk polysaccharide supply depends on a limited network of GMP-certified bioreactor facilities, with South Korean and Indian sites operating at 85%+ utilization.
- CRM197 Carrier Protein Scarcity:Corynebacterium diphtheriae-derived CRM197 supply is captive to three global fermentation sources, creating input cost volatility for conjugate manufacturers.
- EMA Stability Requirements:Divergent cold-chain validation protocols versus WHO prequalification standards force dual dossier preparation, extending regulatory timelines.
Strategic Opportunities
- Indonesia's National Expansion:Archipelago logistics challenges and rising per-capita health expenditure are creating demand for thermostable formulation partnerships outside traditional cold-chain dependence.
- Adult Indication Development:Immunocompromised patient populations and elderly pneumonia burden are opening reimbursement pathways for polysaccharide-conjugate sequential regimens in OECD markets.
- PLI Scheme Manufacturing:India's production-linked incentive framework for bulk biologics is attracting fermentation and conjugation capacity investments with 20% subsidy offset on capital expenditure.
Industry Challenges
- Conjugation Chemistry Expertise Gap:Scarcity of process development scientists capable of optimizing polysaccharide-protein linkage efficiency is extending tech transfer timelines for new serotype additions.
- Lot-Release Testing Backlogs:National control laboratories in target markets face 6-12 month queues for sterility and potency validation, delaying market entry despite manufacturing completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pneumococcal Vaccines Market |
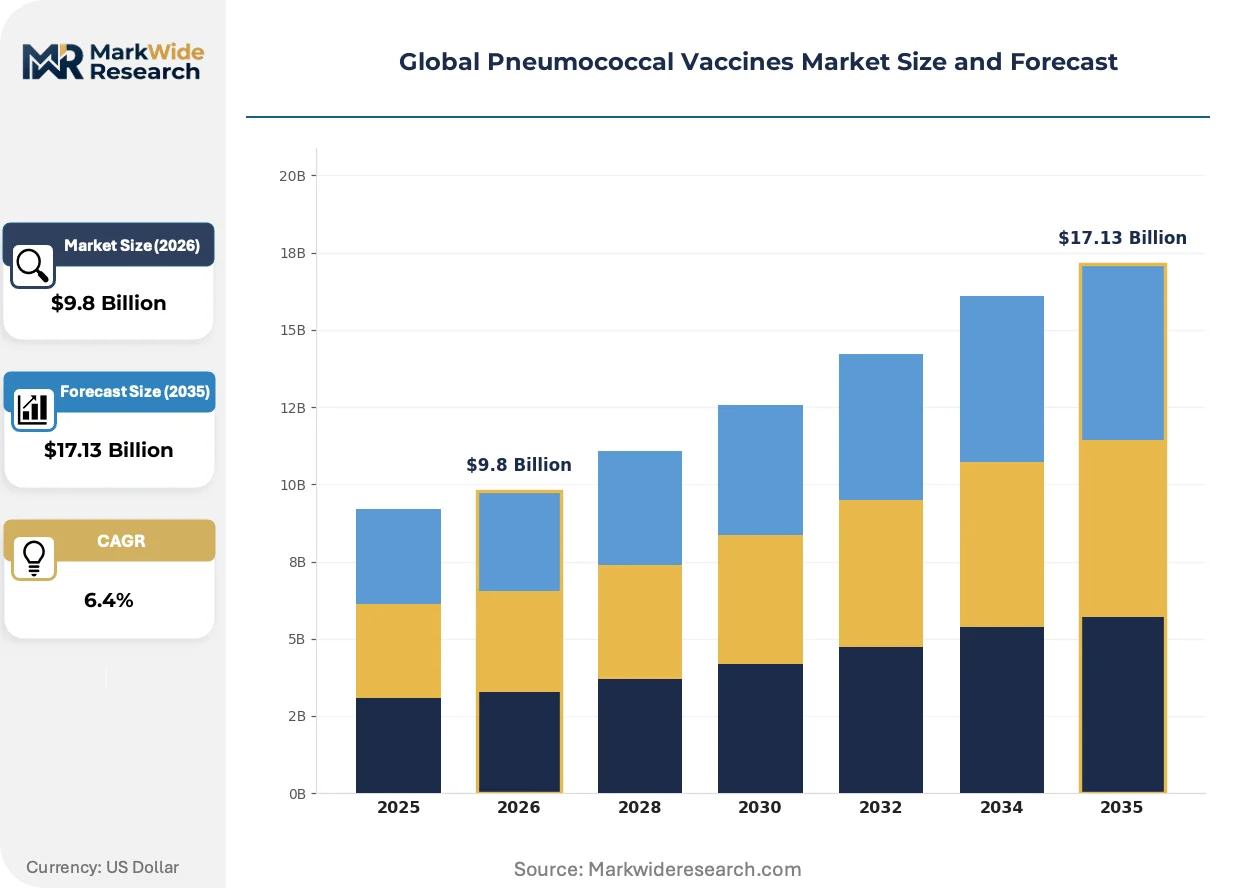
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumococcal Conjugate Vaccine, Pneumococcal Polysaccharide Vaccine, Combination Vaccine, Others Technology: Recombinant Technology, Inactivated Virus, Live Attenuated, Others End User: Hospitals, Clinics, Pharmacies, Public Health Organizations Distribution Channel: Direct Sales, Distributor Network, Online Pharmacies, Others |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Sanofi, Serum Institute of India Pvt. Ltd., CSL, Walvax Biotechnology Co., Ltd., Biological E. Limited, SK Bioscience Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pneumococcal Vaccines Market Shifts & Advancements
Recombinant manufacturing platforms and regulatory convergence initiatives are compressing the traditional conjugate vaccine development paradigm. These forces are redistributing competitive advantage from fermentation scale to protein engineering precision.
Protein-polysaccharide conjugation chemistry is rewriting the technical foundation of pneumococcal immunization. Developers are deploying site-specific enzymatic conjugation to replace random chemical cross-linking, improving batch-to-batch consistency. Pediatric immunization programs in Sub-Saharan Africa are piloting these next-generation candidates through WHO prequalification fast-track. This precision is compressing the cost gap between premium and access-tier supply.
EMA's revised stability guidelines for conjugate vaccines are mandating real-time release testing protocols that diverge from FDA accelerated stability models. European manufacturers must now maintain parallel validation datasets, increasing quality system overhead. Multinational sponsors are responding by regionalizing release testing at MFDS-inspected South Korean facilities to serve both EMA and Asia-Pacific markets from unified dossiers.
UNICEF's long-term supply agreements are consolidating procurement into 3-5 year tenders with price-volume escalation clauses, displacing annual spot purchasing. National programs in Gavi-eligible countries are accepting multi-serotype bundled contracts to secure supply continuity. This contracting evolution is most visible across West African nations where fragmented previous procurement eroded negotiating leverage.
Global Pneumococcal Vaccines Market Segmentation
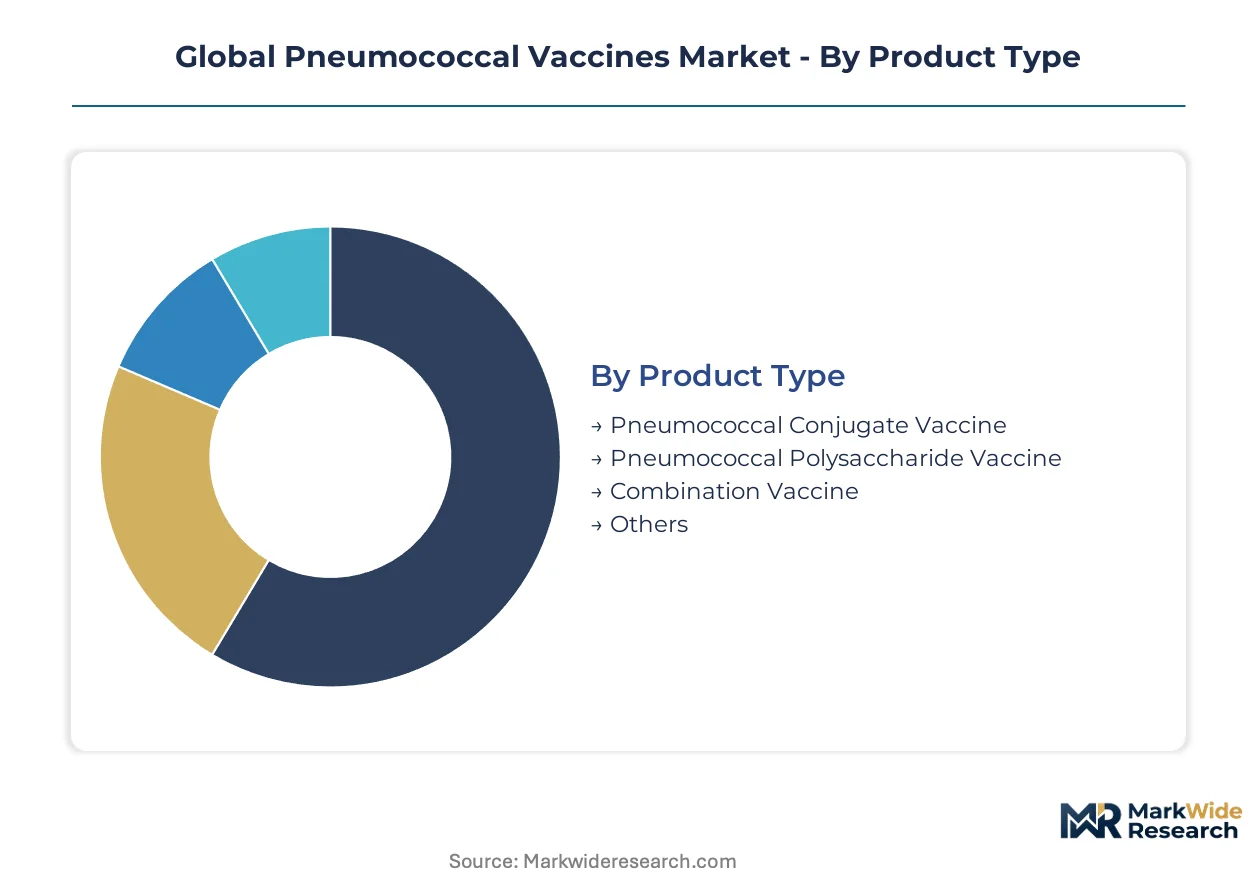
Pneumococcal vaccine procurement splits sharply between premium OECD markets demanding expanded serotype coverage and Gavi-eligible countries prioritizing cost minimization. Segmentation reveals how manufacturing complexity, regulatory pathway, and cold-chain infrastructure dictate competitive positioning across buyer tiers.
Product Type:
Cost tier separates routine pediatric immunization from adult catch-up campaigns and outbreak response stockpiles.
- Pneumococcal Conjugate Vaccine:Protein-polysaccharide conjugation chemistry elicits T-cell dependent immune responses essential for infant protection. India's Universal Immunization Programme and UNICEF tenders concentrate demand here, though CRM197 carrier protein scarcity constrains supply expansion.
- Pneumococcal Polysaccharide Vaccine:Unconjugated capsular polysaccharides trigger T-cell independent responses suitable for adults over 65. Elderly pneumonia burden in Japan and adult indication development in Germany sustain residual demand despite inferior infant immunogenicity.
- Combination Vaccine:Co-formulation with Hib or other antigens reduces injection burden in resource-limited settings.
- Others:Investigational mucosal delivery formats and nanoparticle carriers remain preclinical.
Volume sits with Pneumococcal Conjugate Vaccine; growth tilts toward Combination Vaccine as bundling economics improve.
Technology:
Manufacturing maturity determines which developers can bypass fermentation bottlenecks constraining polysaccharide yield.
- Recombinant Technology:Cell-free expression systems synthesize protein antigens without bacterial fermentation, compressing candidate-to-clinic timelines. South Korean biopharmaceutical manufacturing capacity is hardening around these platforms as MFDS fast-tracks novel construct reviews.
- Inactivated Virus:Not applicable to pneumococcal bacterial targets; placeholder category for platform flexibility.
- Live Attenuated:Experimental mucosal delivery vectors under early investigation.
- Others:Synthetic peptide and mRNA approaches remain exploratory.
Recombinant Technology captures the steepest expansion trajectory as developers pursue serotype coverage without polysaccharide purification constraints.
End User:
Cold-chain reliability and reimbursement infrastructure segment buyers by risk tolerance for temperature excursions.
- Public Health Organizations:Gavi and national immunization programs aggregate purchasing power across 70+ low-income countries. WHO prequalification pathway acceleration is unlocking procurement eligibility previously blocked by polysaccharide-only alternatives.
- Hospitals:Tertiary centers manage severe invasive pneumococcal disease cases and administer adult polysaccharide regimens.
- Clinics:Primary care settings handle routine pediatric conjugate administration in OECD markets.
- Pharmacies:Retail channels expanding into adult vaccination in US and UK markets.
Procurement volume concentrates with Public Health Organizations; margin expansion favors Hospitals as adult indication pricing decouples from pediatric tenders.
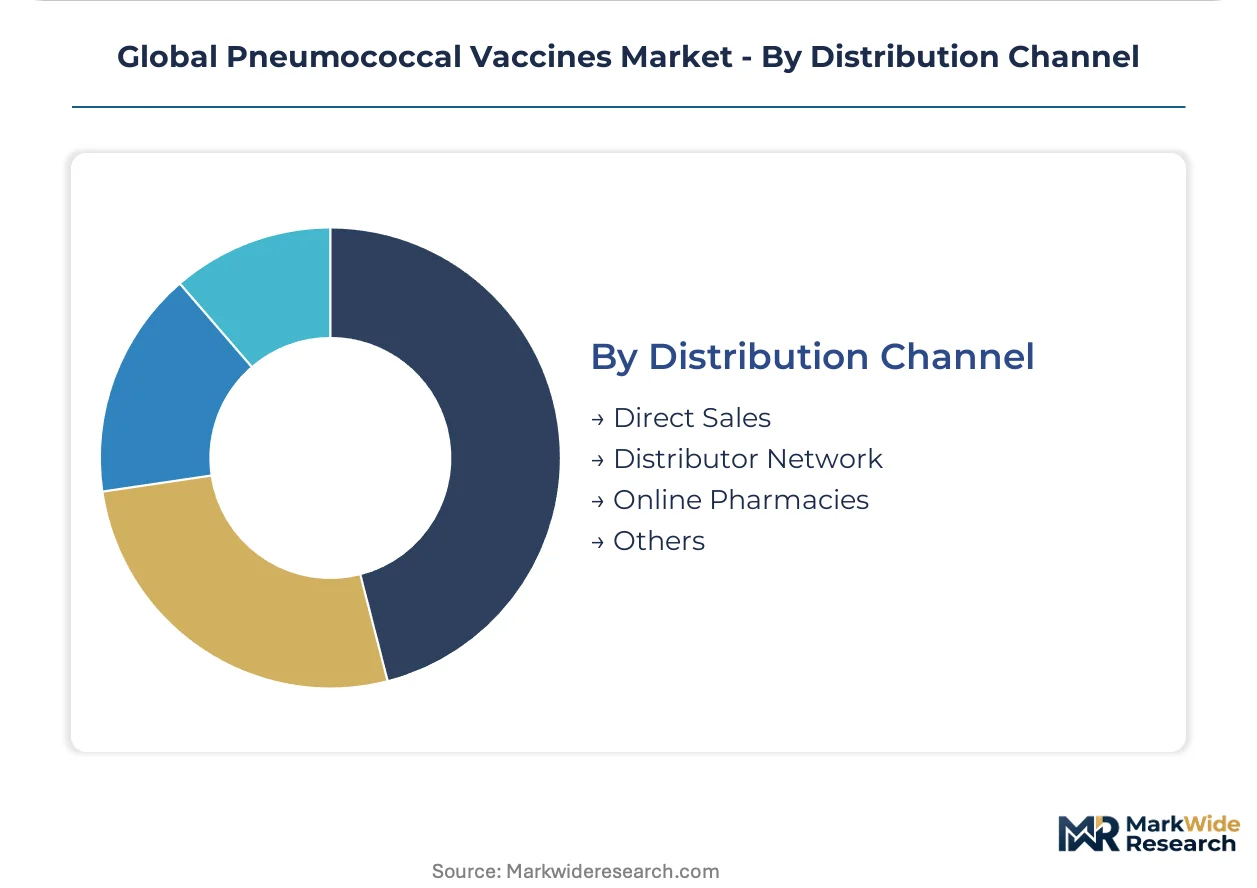
Distribution Channel:
Geographic fragmentation and regulatory dossier requirements determine whether manufacturers maintain direct relationships or cede margin to intermediaries.
- Direct Sales:Multinational sponsors negotiate multi-year tenders with UNICEF and Gavi, embedding price-volume escalation clauses that displace annual spot purchasing.
- Distributor Network:Regional wholesalers manage archipelago logistics challenges across Indonesia and Philippines where cold-chain integrity degrades over maritime transport.
- Online Pharmacies:Emerging channel for adult booster reminders in digitally mature markets.
- Others:Humanitarian stockpile mechanisms and emergency deployment protocols.
Direct Sales commands volume concentration; Distributor Network gains share fastest as regional manufacturing footprints expand under India's PLI scheme subsidies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CRM197 carrier protein fermentation anchors manufacturing gravity in South Korea and India, while polysaccharide purification capacity concentrates around Pune and Seoul. Demand fragmentation across income tiers splits procurement between premium OECD markets and Gavi-eligible tenders.
United States
FDA stability requirements for conjugate vaccines drive real-time release testing investments at West Point and Durham manufacturing clusters. The Biologics License Application pathway mandates extensive lot-release documentation that extends regulatory timelines. Massachusetts and North Carolina biopharmaceutical corridors concentrate conjugation chemistry expertise and adult indication development programs.
Germany
EMA revised stability guidelines force parallel validation datasets for European market entry, increasing quality system overhead for sponsors. The Paul-Ehrlich-Institut oversees batch release testing that creates 6-12 month queues for sterility validation. Marburg and Frankfurt Rhine-Main biopharma clusters host polysaccharide fermentation and conjugation capacity serving EMA and export markets.
India
CDSCO tightening of local clinical trial mandates redirects sponsor investment toward regional manufacturing footprints under the PLI scheme. Government tenders for Universal Immunization Programme inclusion generate multi-year demand commitments at population scale. Pune and Hyderabad vaccine manufacturing clusters scale affordable conjugate supply for UNICEF and Gavi procurement.
South Korea
MFDS fast-track reviews for novel recombinant constructs accelerate candidate-to-clinic timelines for expanded serotype coverage. The national regulator's convergence with EMA standards enables unified dossier preparation for European and Asia-Pacific markets. Songdo and Osong biopharma clusters harden cell-free expression system capacity around vaccine sovereignty priorities.
Indonesia
Archipelago logistics challenges and rising per-capita health expenditure create demand for thermostable formulation partnerships outside traditional cold-chain dependence. The national immunization program expansion targets pneumococcal conjugate inclusion despite maritime transport integrity degradation. Java-based distribution hubs and emerging eastern manufacturing zones attract regional capacity investments.
Global Pneumococcal Vaccines Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and pricing architecture. The vendor base stratifies between premium OECD-positioned developers and high-volume Gavi suppliers. Three archetypes dominate: fermentation-scale incumbents with conjugation chemistry depth, recombinant platform specialists circumventing polysaccharide bottlenecks, and emerging market champions capturing UNICEF tenders. Competitive moves concentrate on capacity expansion under India's PLI scheme and technology licensing for thermostable formulations.
Among fermentation-scale incumbents, Pfizer Inc. and Merck & Co., Inc. occupy positions defined by decades-long R&D intensity in conjugate chemistry. Serum Institute of India Pvt. Ltd. anchors the access-tier vector, exemplifying volume economics through sub-dollar per-dose pricing for multilateral procurement. These three represent the structural tension between premium positioning and high-volume supply that defines current competitive dynamics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| Serum Institute of India Pvt. Ltd. |
| CSL |
| Walvax Biotechnology Co., Ltd. |
| Biological E. Limited |
| SK Bioscience Co., Ltd. |
| Others |
Supply & Pricing Matrix
CRM197 carrier protein fermentation costs cascade through three distinct pricing tiers as Indian and South Korean bulk suppliers feed conjugate manufacturers serving UNICEF tenders, OECD premium markets, and emerging national immunization programs. The 18-24 month production cycle for polysaccharide purification and protein conjugation creates working capital intensity that separates volume-scaled access-tier suppliers from margin-defended premium-positioned developers.
Pricing Analysis
Warranty and lot-release documentation bundling separates premium OECD supply from stripped-down Gavi-eligible tenders, with EMA-mandated real-time release testing adding quality system overhead that price-sensitive public health buyers reject. Three-tier pricing structure across premium, standard, and economy levels reflects divergent cold-chain validation, serotype coverage breadth, and carrier protein sourcing. Pricing pressure stems from UNICEF's multi-year tender consolidation with price-volume escalation clauses. Public health organizations exhibit highest price sensitivity; immunocompromised adult indication segments in Germany and Japan show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content mandates and South Korea's vaccine sovereignty policies are reshaping sourcing patterns away from legacy US and European fermentation footprints. Bulk polysaccharide supply draws from GMP-certified bioreactor networks concentrated in India, South Korea, and the United States, with CRM197 carrier protein captive to three global fermentation sources. Single-source vulnerability for Corynebacterium diphtheriae-derived inputs creates input cost volatility. Distribution runs through direct multi-year tenders with UNICEF and Gavi, supplemented by regional wholesalers managing archipelago logistics across Indonesia and Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from WHO prequalification acceleration and CRM197 supply scarcity will force sub-scale conjugate developers into technology licensing or exit over the coming decade. Manufacturing scale and carrier protein security separate survivors from casualties.
For Market Incumbents: To counter recombinant platform specialists circumventing fermentation bottlenecks, Pfizer and Merck should deepen captive CRM197 supply through backward integration into Corynebacterium diphtheriae fermentation capacity. Merck's West Point facility expansion and Pfizer's conjugation chemistry R&D intensity must extend to site-specific enzymatic conjugation licensing to compress cost gaps with access-tier suppliers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in thermostable formulations opens white-space targeting Indonesia's archipelago logistics challenges and Sub-Saharan Africa's cold-chain reliability gaps. Serum Institute of India's sub-dollar per-dose UNICEF pricing sets a floor; entrants should pursue recombinant protein synthesis partnerships with South Korean MFDS-fast-tracked facilities. Go-to-market positioning through WHO prequalification fast-track unlocks Gavi procurement eligibility previously blocked by polysaccharide-only alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor recombinant platform specialists with cell-free expression system capacity in South Korea's Songdo and Osong clusters, where vaccine sovereignty policies guarantee offtake. Long-term viability across the analysis window hinges on serotype replacement pattern adaptability and regulatory convergence capture. Watch EMA-FDA stability guideline alignment as inflection signal for unified dossier economics.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands fermentation capacity at Pune and Hyderabad clusters to meet UNICEF multi-year tender commitments. |
| Regulatory Convergence Capture | Aligns MFDS-inspected South Korean release testing with EMA standards to serve European and Asia-Pacific markets from unified dossiers. |
| Technology Licensing | Transfers site-specific enzymatic conjugation expertise to compress batch-to-batch consistency costs for next-generation candidates. |
| Backward Integration | Secures captive CRM197 carrier protein supply from Corynebacterium diphtheriae fermentation to reduce input cost volatility. |
| Reimbursement Strategy | Opens adult indication pathways for polysaccharide-conjugate sequential regimens in OECD markets with elderly pneumonia burden. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and MFDS, UNICEF procurement officers, and hospital formulary directors. FDA Biologics License Application documentation, EMA stability guideline revisions, WHO prequalification pathway records, and Gavi tender disclosures provided secondary validation. Bottom-up demand modeling across pediatric and adult indication segments triangulated against top-down manufacturer capacity assessments.
Data-stream reconciliation merged serotype coverage expansion timelines, fermentation capacity utilization rates, and carrier protein supply constraints into a unified analytical framework across the analysis window. Segmentation dimensions included product type, technology platform, end-user category, and distribution channel, with regional regulatory cluster effects modeled separately. CAGRs derived from manufacturer shipment data, national immunization program procurement records, and multilateral supply agreement volumes, with recombinant technology adoption curves and WHO prequalification acceleration rates as industry-specific forecast inputs.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time national control laboratory lot-release queue data introduce uncertainty bands around market entry timing assumptions. Forecasts reflect documented assumptions regarding serotype replacement patterns, CRM197 supply continuity, and regulatory convergence trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Pregabalin Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market