
 Antiretroviral (ARV) Agents Market | 2026-2036
Antiretroviral (ARV) Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Antiretroviral (ARV) Agents Market Analytics
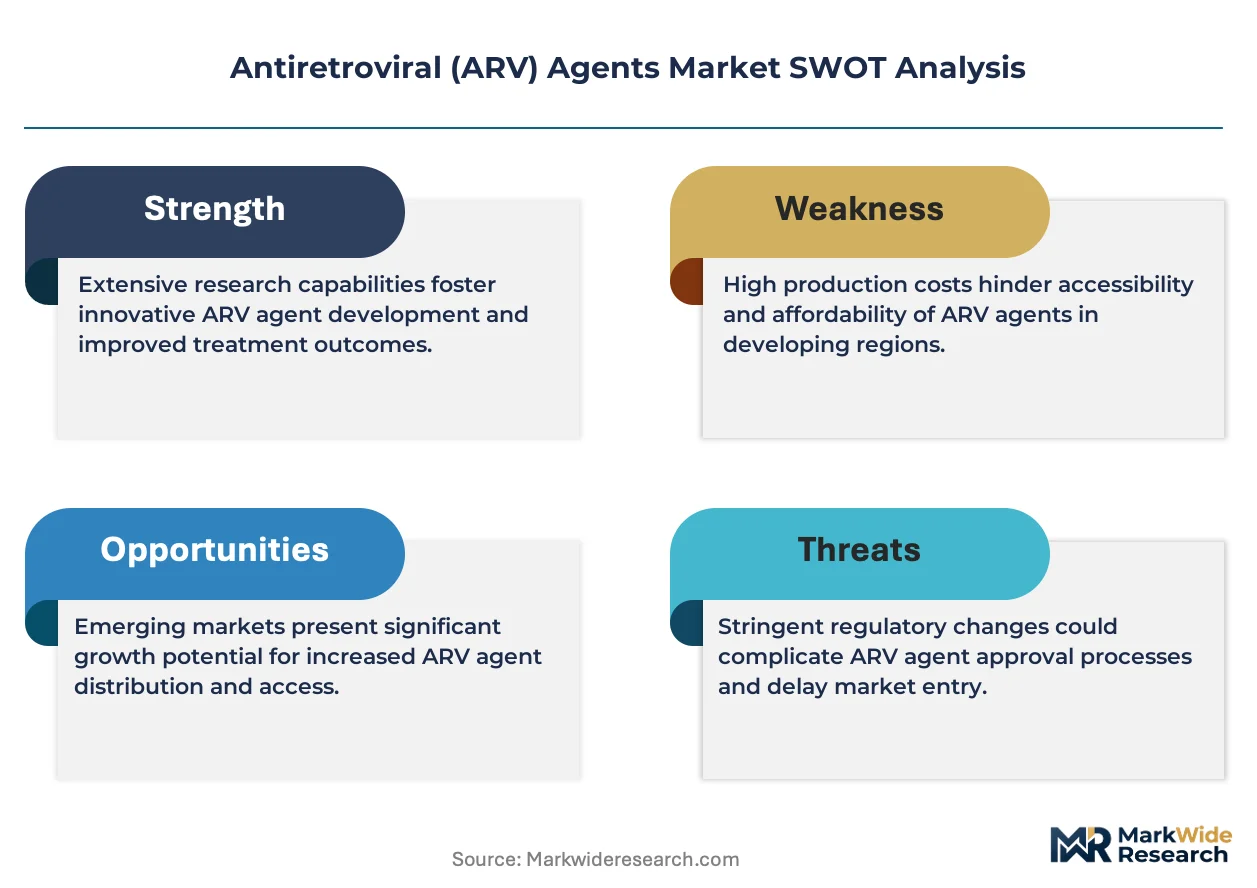
Multi-source API procurement is expanding as pharmaceutical manufacturers diversify away from single-source dependencies for efavirenz and tenofovir intermediates. Gilead Sciences leverages captive manufacturing in Ireland and India to secure supply continuity for its integrase inhibitor portfolio. ViiV Healthcare anchors its long-acting injectable strategy through specialized sterile formulation facilities in the United Kingdom. Cipla competes on cost-engineered oral fixed-dose combinations supplied to African national programs.
Antiretroviral agents are synthetic or semi-synthetic compounds that disrupt HIV replication through enzymatic inhibition, with modern formulations targeting reverse transcriptase, protease, or integrase at picomolar binding affinities. Their primary purpose is sustained viral suppression in infected patients and pre-exposure prophylaxis in high-risk populations. Integrase inhibitors command premium positioning due to superior resistance profiles and tolerability versus legacy nucleoside analogues. Injectable delivery modes represent the fastest-expanding category as cabotegravir and rilpivirine long-acting formulations shift patient adherence dynamics. Hospital end users retain dominant procurement volumes, though home care channels are capturing share through direct-to-patient distribution models.
FDA accelerated approval pathways and EMA conditional marketing authorizations shape development timelines for novel ARV entrants, while WHO prequalification standards govern access to low-income country tenders. The EPA regulates active pharmaceutical ingredient discharge from manufacturing facilities, raising compliance costs for API producers in India and China. Stakeholders must monitor patent cliff dynamics for blockbuster molecules and position manufacturing capacity for next-generation long-acting modalities.
Market Dynamics
Long-acting injectable formulations are compressing adherence-driven market structures by replacing daily oral regimens with monthly or quarterly administration cycles, fundamentally altering procurement volumes and distribution economics across hospital and outpatient channels.
Growth Catalysts
- PEPFAR funding continuity:Sustained bilateral financing under the US President's Emergency Plan for AIDS Relief underwrites national treatment programs across Sub-Saharan Africa, securing volume commitments for generic fixed-dose combinations.
- WHO prequalification acceleration:Streamlined quality-assessment pathways for generic manufacturers reduce time-to-tender for low-income country procurement, expanding supplier pools beyond originator firms.
- Integrase inhibitor superiority:Picomolar binding affinity and superior resistance profiles drive formulary preference over legacy nucleoside reverse transcriptase inhibitors in treatment-naive patient populations.
Market Restraints
- API supply concentration:Efavirenz and tenofovir intermediate production clusters in specific coastal manufacturing zones of India and China, creating single-source vulnerability for multi-product portfolios.
- Sterile formulation capacity scarcity:Long-acting injectable manufacturing requires specialized aseptic facilities with isolator technology, limiting qualified suppliers to a narrow base of contract manufacturers.
- Patent cliff compression:Expiring exclusivity on blockbuster integrase inhibitors triggers rapid price erosion in tender markets, compressing revenue per patient for originator portfolios.
Strategic Opportunities
- Sub-Saharan Africa home care expansion:Direct-to-patient distribution models for oral pre-exposure prophylaxis bypass hospital procurement bottlenecks in Kenya, Nigeria, and South Africa.
- FDA accelerated approval pathway exploitation:Breakthrough therapy designation for novel long-acting modalities compresses Phase III-to-launch timelines, enabling first-mover capture of adherence-sensitive patient segments.
- Dual prevention-contraception convergence:Cabotegravir long-acting formulations paired with hormonal contraceptive delivery systems target overlapping high-risk demographics in integrated sexual health programs.
Industry Challenges
- Sterile manufacturing talent scarcity:Qualified aseptic operators and formulation scientists command premium compensation in biologics-heavy labor markets, constraining capacity expansion timelines.
- Cold chain integrity maintenance:Long-acting injectable stability requirements mandate controlled-temperature distribution infrastructure that remains underdeveloped in last-mile rural networks.
- Regulatory divergence friction:Misalignment between FDA bioequivalence standards and WHO prequalification protocols forces redundant clinical studies for global generic filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiretroviral (ARV) Agents Market |
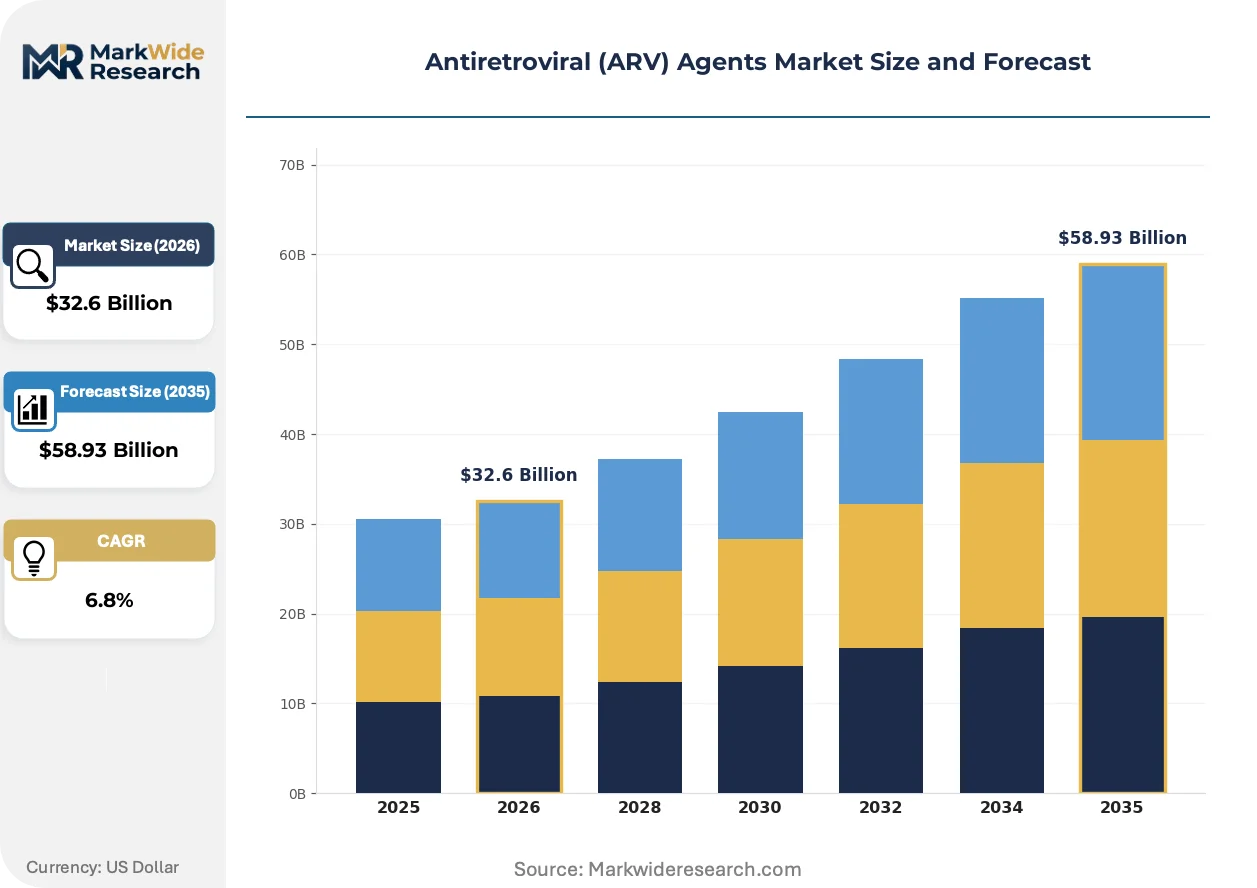
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: NRTIs, NNRTIs, PIs, Integrase Inhibitors Delivery Mode: Oral, Injectable, Implantable, Topical End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: HIV Treatment, Prophylaxis, Combination Therapy, Preventive Care |
| Companies Covered | Gilead Sciences, Inc., ViiV Healthcare, Merck & Co., Inc., AbbVie Inc., Johnson & Johnson, Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd., GlaxoSmithKline plc., Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiretroviral (ARV) Agents Market Evolving Landscape
Formulation science breakthroughs and regulatory pathway evolution are converging to displace decades-old oral daily regimens, while procurement behavior shifts reward suppliers capable of integrated manufacturing and direct distribution.
Long-acting injectable nanosuspension technology is overtaking conventional oral tablet dominance in patient adherence strategies. Hospital outpatient clinics and community health centers in high-burden regions are adopting cabotegravir-rilpivirine monthly or bi-monthly administration protocols at accelerating velocity. This modality is compressing pharmacy refill visit frequency and enabling resource reallocation toward prevention outreach rather than chronic disease management logistics.
EMA conditional marketing authorization frameworks are accelerating novel ARV entrants into European markets ahead of complete Phase III durability data. Manufacturers gain earlier revenue streams while committing to post-authorization efficacy studies, shifting competitive positioning toward regulatory strategy sophistication. Injectable integrase inhibitors receive disproportionate pathway utilization given their adherence advantages in hard-to-retain patient cohorts.
Patient preference for discreet administration options is redirecting procurement decisions away from observable daily pill consumption toward private injection scheduling. Home-based administration training programs and nurse-led community delivery models are displacing clinic-centric dispensing in South Africa and Kenya. This behavioral pivot rewards manufacturers with flexible distribution licensing and cold-chain partnerships over traditional wholesale-hospital contracting structures.
Antiretroviral (ARV) Agents Market Segmentation
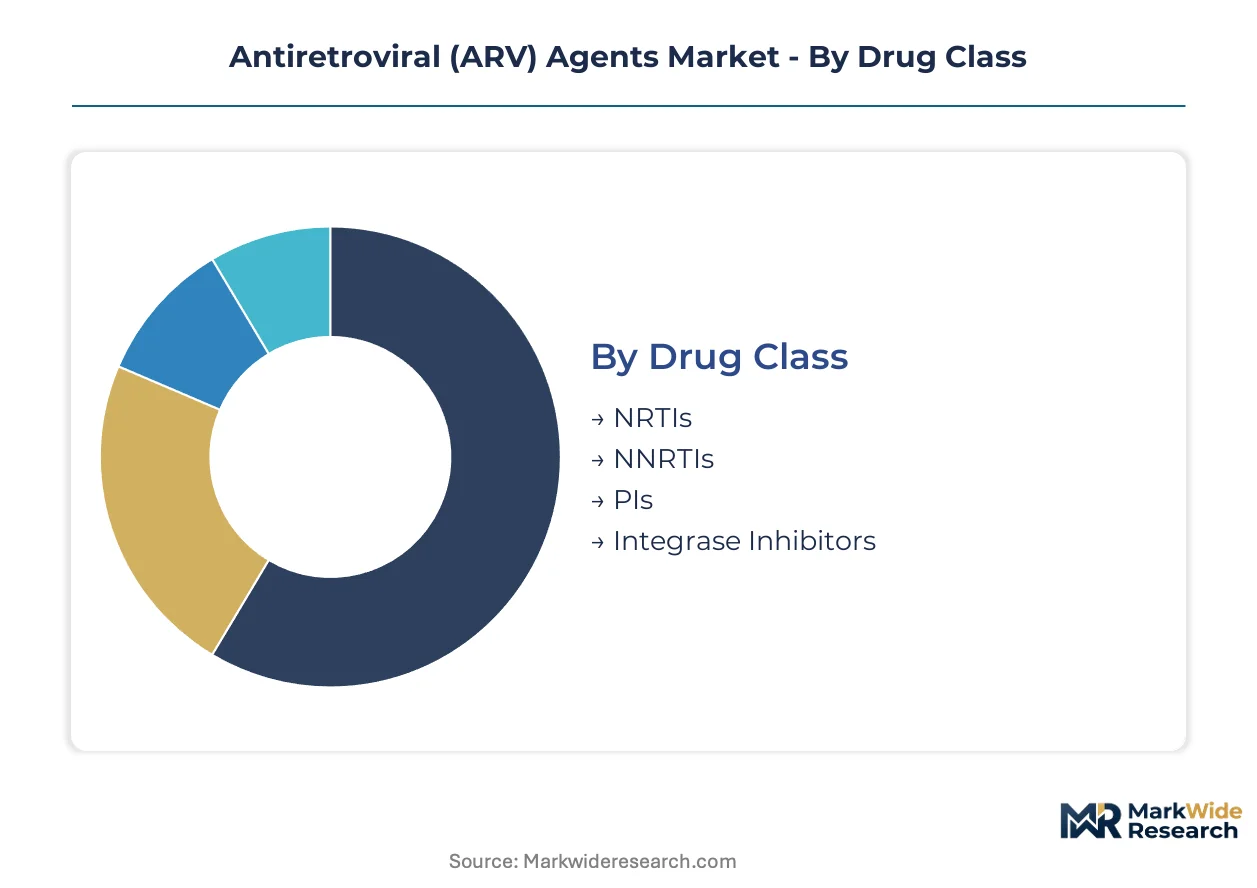
Antiretroviral market segmentation reveals how formulation innovation and care setting migration are redistributing value across drug classes and delivery modes. Understanding these divides exposes where procurement budgets concentrate and where next-generation products displace legacy regimens.
Drug Class:
Upgrade cycles from first-generation nucleoside analogues toward modern integrase inhibitors are compressing revenue pools for legacy agents while concentrating premium pricing on resistance-protected portfolios.
- NRTIs:Nucleoside reverse transcriptase inhibitors form the backbone of combination regimens through tenofovir and emtricitabine co-formulations. Demand concentrates in Sub-Saharan Africa national tenders where cost-engineered fixed-dose combinations dominate procurement volumes despite inferior resistance barriers.
- Integrase Inhibitors:These agents achieve picomolar binding affinity against HIV integrase enzyme with superior genetic barrier to resistance. Hospital formularies in the United States and Western Europe prioritize dolutegravir and bictegravir regimens for treatment-naive patients, driving premium positioning despite patent cliff pressures.
- NNRTIs:Non-nucleoside reverse transcriptase inhibitors including efavirenz and rilpivirine persist in generic-heavy markets.
- PIs:Protease inhibitors occupy niche salvage therapy roles after multi-class resistance emergence.
NRTIs sit at the top of the volume ranking, with Integrase Inhibitors climbing the fastest.
Delivery Mode:
Cost tier stratification separates mass-market oral tablets from premium-priced long-acting modalities requiring specialized manufacturing investment and cold-chain infrastructure.
- Oral:Daily fixed-dose combination tablets remain the dominant procurement category across PEPFAR-funded programs and emerging market tenders. Cipla and Mylan compete intensely on tenofovir-lamivudine-dolutegravir pricing for African national stockpiles.
- Injectable:Cabotegravir and rilpivirine nanosuspension formulations enable monthly or bi-monthly administration, capturing adherence-sensitive patient segments in United States and European outpatient clinics. ViiV Healthcare anchors supply through specialized sterile facilities in the United Kingdom.
- Implantable:Subdermal depot systems remain investigational with limited commercial penetration.
- Topical:Vaginal microbicide gels occupy prevention research pipelines without scaled procurement.
Oral formulations retain volume leadership, though Injectable modalities are expanding most quickly in adherence-driven segments.
End User:
Customer type fragmentation reflects divergent procurement authority between centralized hospital systems and emerging direct-to-patient distribution channels.
- Hospitals:Academic medical centers and public hospital networks in South Africa, Kenya, and Nigeria aggregate procurement through national tender mechanisms. These institutions administer complex first-line regimens and manage treatment-experienced patients with resistance profiles.
- Home Care:Nurse-led community delivery and patient self-administration training programs are capturing share in South African townships and Kenyan urban peripheries. Direct distribution bypasses hospital pharmacy bottlenecks for stable patients on suppressive therapy.
- Clinics:Primary health centers handle initiation and monitoring in high-burden districts.
- Pharmacies:Retail dispensing concentrates on private-pay segments and PrEP access in urban centers.
Hospitals command the largest procurement volumes, while Home Care channels are gaining share fastest through decentralized distribution licensing.
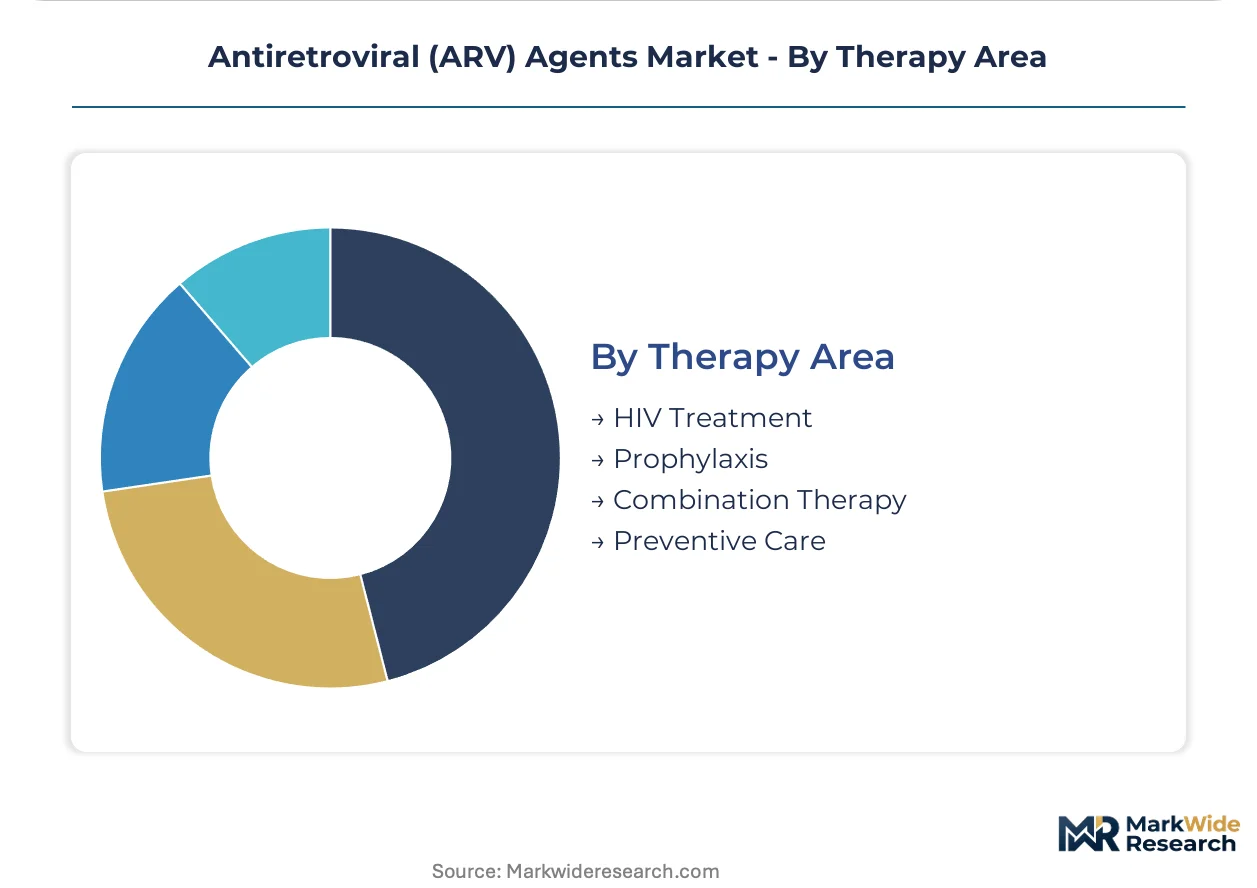
Therapy Area:
Application maturity varies sharply between established treatment paradigms and emerging preventive indications reshaping patient eligibility criteria.
- HIV Treatment:Lifelong suppressive therapy for seropositive patients consumes the majority of API volume through WHO-recommended first-line and second-line regimens. Sub-Saharan African national programs underwrite treatment for over two-thirds of global patient load.
- Prophylaxis:Pre-exposure prophylaxis with tenofovir-emtricitabine or long-acting cabotegravir targets seronegative high-risk populations in United States urban centers and Kenyan female cohorts. FDA breakthrough therapy designation accelerated injectable PrEP approval ahead of complete durability data.
- Combination Therapy:Multi-class regimens dominate clinical practice across all care settings.
- Preventive Care:Post-exposure prophylaxis and prevention of mother-to-child transmission occupy discrete procurement streams.
HIV Treatment anchors volume demand, with Prophylaxis applications showing the steepest expansion trajectory as indication breadth widens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune pharmaceutical corridor anchors global API supply for efavirenz and tenofovir intermediates, with formulation manufacturing gravitating toward sterile facilities in the United Kingdom and distribution networks concentrating in Sub-Saharan African treatment programs.
United States
FDA accelerated approval pathways compress development timelines for novel long-acting injectables, with hospital outpatient clinics in Baltimore and Boston adopting cabotegravir-rilpivirine protocols. Breakthrough therapy designations reward adherence-focused formulations. Research Triangle Park hosts clinical trial infrastructure for next-generation integrase inhibitors.
India
CDSCO oversight governs fixed-dose combination exports to PEPFAR-funded programs, with Hyderabad and Ahmedabad manufacturing zones supplying cost-engineered tenofovir-lamivudine-dolutegravir tablets. Generic prequalification timelines determine tender competitiveness. Active pharmaceutical ingredient clusters in coastal Gujarat face EPA-equivalent discharge compliance costs.
South Africa
National Department of Health tenders underwrite treatment for the continent's largest patient cohort, with Johannesburg and Cape Town hospital networks managing resistance-profiled patients. Nurse-led community delivery models bypass pharmacy bottlenecks in township peripheries. Cold chain infrastructure gaps constrain long-acting injectable rural penetration.
United Kingdom
MHRA alignment with EMA conditional marketing authorizations accelerates novel ARV market entry, with specialized sterile formulation facilities in Stevenage and Barnard Castle anchoring ViiV Healthcare's injectable strategy. NHS procurement prioritizes adherence-improving modalities. London research institutes drive nanosuspension formulation science.
Brazil
ANVISA registration requirements shape generic substitution policies, with São Paulo and Rio de Janeiro public hospital networks administering first-line integrase inhibitor regimens. Ministry of Health price negotiations compress originator margins. Domestic formulation capabilities in Osasco supply Latin American regional programs.
Antiretroviral (ARV) Agents Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory pathway sophistication, with originator firms commanding premium positioning in adherence-driven segments while generic specialists capture volume in tender-funded markets. Market structure tilts toward consolidated API supply and fragmented finished-dose competition. Three archetypes dominate: vertically integrated originators with captive manufacturing, multi-source generic aggregators, and sterile formulation specialists. Capacity expansion and strategic licensing partnerships constitute the primary competitive maneuvers.
Within the originator tier, Gilead Sciences and ViiV Healthcare exemplify vertical integration strategies, with the former leveraging Ireland and India manufacturing assets and the latter anchoring supply through United Kingdom sterile facilities. Cipla occupies a distinctive position as a cost-engineered generic supplier, representing the regional champion archetype that competes on PEPFAR tender pricing and WHO prequalification velocity.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| ViiV Healthcare |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd. |
| GlaxoSmithKline plc. |
| Cipla |
| Others |
Value Network & Pricing Analysis
API intermediate costs for efavirenz and tenofovir feed through from coastal Gujarat manufacturing clusters into tiered finished-dose pricing, with procurement officers at African national programs capturing economy-tier supply while hospital formularies in the United States absorb premium-tier integrase inhibitor markups.
Pricing Analysis
Input-cost pass-through from active pharmaceutical ingredient synthesis determines contract pricing for generic fixed-dose combinations, with tenofovir-lamivudine-dolutegravir tenders in Sub-Saharan Africa driven by volume-scale negotiations and WHO prequalification status as the primary differentiation factors. Pricing pressure intensifies in the integrase inhibitor segment as patent expirations on dolutegravir and bictegravir formulations accelerate generic substitution in tender markets. PEPFAR-funded procurement officers exhibit the highest price sensitivity, while United States hospital outpatient clinics purchasing long-acting injectable regimens demonstrate markedly lower elasticity due to adherence-outcome value attribution.
Supply Chain Analysis
Single-source vulnerability sits with efavirenz intermediate production concentrated in specific coastal zones of India and China, where environmental compliance costs and energy input pricing create cascading effects on global generic availability. The supply chain draws from specialized aseptic formulation facilities in the United Kingdom for long-acting injectable nanosuspensions, with cold-chain distribution dependencies creating last-mile constraints in rural Sub-Saharan African networks. Tariff exposure on API imports into Brazil and South Africa compounds sourcing risk for regional formulation manufacturers. Distribution runs through national tender mechanisms in high-burden countries, supplemented by direct-to-patient channels emerging in Kenyan and South African home care programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in long-acting injectable modalities where sterile manufacturing scarcity supports premium positioning, while cost-engineered oral generics compete on PEPFAR tender velocity and WHO prequalification throughput.
For Market Incumbents: Anticipate patent cliff compression on blockbuster integrase inhibitors by accelerating captive manufacturing investments in Ireland and India to secure API supply continuity ahead of generic substitution waves. Prioritize sterile formulation capacity additions in the United Kingdom to defend positioning in adherence-driven patient segments where hospital outpatient clinics reward injection-based regimens with formulary preference. For New Entrants and Emerging Players: Nanosuspension formulation technology offers a technology-first wedge into the long-acting injectable supply gap, with qualified aseptic contract manufacturing capacity scarce enough to support partnership-based market entry. Target Sub-Saharan African home care distribution licensing in Kenya and Nigeria, where nurse-led community delivery models bypass entrenched hospital procurement structures and reward flexible cold-chain partnerships over traditional wholesale contracting. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing talent scarcity constrains capacity expansion timelines for next-generation long-acting modalities. The analysis window favors acquisition targets with established WHO prequalification pathways and existing PEPFAR supplier relationships, as these assets compound defensive moats against originator portfolio erosion. Watch for FDA breakthrough therapy designations on novel integrase inhibitor formulations as inflection signals for adherence-sensitive segment capture.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses Phase III-to-launch timelines for cabotegravir-rilpivirine expansions. |
| Manufacturing Scale-Up | Sterile formulation capacity additions in the United Kingdom anchor ViiV Healthcare's injectable supply security. |
| Backward Integration | Gilead Sciences' captive API production in Ireland insulates integrase inhibitor margins from intermediate price volatility. |
| Licensing Agreement | Direct-to-patient distribution licenses in Kenya bypass hospital pharmacy bottlenecks for stable patients. |
| Pipeline Diversification | Dual prevention-contraception convergence targets overlapping high-risk demographics in integrated sexual health programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at originator and generic firms, hospital formulary directors in Baltimore and Boston, and procurement managers at African national health programs with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure analysis were triangulated to constrain estimate variance.
Segment-weighting approaches applied differential growth assumptions across drug class, delivery mode, and end-user dimensions, with integrase inhibitor adoption curves, long-acting injectable penetration rates, and home care channel migration modeled separately across regional regulatory clusters. CAGRs were derived from compounded annual patient volume and average revenue per patient trajectory analysis, incorporating tender pricing dynamics, patent expiry schedules, and PEPFAR funding continuity as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sterile manufacturing capacity expansion timelines, regulatory divergence between FDA bioequivalence standards and WHO prequalification protocols, and cold chain infrastructure development in last-mile rural networks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Acetaminophen Market