
 Thermal Spray Coating Market | 2026-2036
Thermal Spray Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Spray Coating Market Analysis
Defense contractors is collapsing as the fastest-expanding buyer archetype for thermal spray coating services, overtaking traditional power plant maintenance cycles. Oerlikon Metco dominates plasma spray system supply through captive powder production and equipment-integrated service models. Praxair Surface Technologies anchors North American aerospace coating demand with proprietary HVOF feedstock formulations. Bodycote extends its position through dense service center networks that compete on turnaround speed for industrial equipment refurbishment.
Thermal spray coating deposits molten or semi-molten particles onto substrates to build protective layers typically 50 micrometers to several millimeters thick, engineered for wear resistance, corrosion protection, and thermal barrier performance in extreme operating environments. Ceramic coatings, particularly yttria-stabilized zirconia, lead aerospace thermal barrier applications where operating temperatures exceed one thousand degrees Celsius. HVOF technology is displacing traditional flame spray in oil and gas component repair due to superior coating density and bond strength. Cold spray represents the fastest-growing technology segment, though from a smaller base, as manufacturers seek low-temperature deposition for temperature-sensitive substrates.
The EPA regulates particulate emissions from thermal spray operations under Clean Air Act provisions, while REACH restricts hexavalent chromium compounds historically used in certain bond coats. ISO 14918 certification for thermal spray personnel shapes workforce availability and service quality differentiation across coating shops. Stakeholders must monitor evolving powder feedstock qualification protocols and assess whether in-house spray capability or outsourced coating services better align with production scale and part complexity trajectories.
Market Dynamics
Defense contractors now drive coating demand faster than traditional power plant maintenance, while cold spray technology compresses deposition timelines for temperature-sensitive aerospace substrates. This demand rotation collides with tightening REACH and EPA emissions protocols that restrict hexavalent chromium bond coats.
Growth Catalysts
- Turbine blade thermal barriers:Aerospace OEMs specify yttria-stabilized zirconia coatings for engines operating above 1,000°C, extending component lifecycles in commercial aviation.
- REACH compliance deadlines:European manufacturers accelerate qualification of chromium-free bond coat alternatives ahead of substance restriction phase-outs.
- HVOF density advantages:Oil and gas operators replace flame spray with high-velocity oxy-fuel systems for superior coating adhesion in downhole component repair.
Market Restraints
- Feedstock powder concentration:Captive powder production by dominant equipment suppliers limits third-party feedstock pricing flexibility.
- ISO 14918 certification scarcity:Qualified thermal spray personnel shortages constrain coating shop capacity expansion and service quality consistency.
- Plasma spray capex intensity:Automated plasma systems require substantial capital outlay, favoring large-scale in-house operations over job shop entry.
Strategic Opportunities
- Additive repair convergence:Cold spray deposition hybridizes with directed energy deposition for near-net-shape component restoration in defense maintenance depots.
- Industrial refurbishment clusters:German equipment rebuild centers generate concentrated coating service demand from aging machine tool and printing press fleets.
- EPA Clean Air Act alignment:US coating shops investing in particulate capture systems qualify for accelerated permitting in non-attainment zones.
Industry Challenges
- Multi-standard compliance layering:Coating shops serving aerospace and medical device verticals simultaneously must maintain AS9100 and ISO 13485 quality systems.
- Substrate-powder matching complexity:Expanding alloy portfolios require extensive qualification matrices that extend new product introduction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Spray Coating Market |
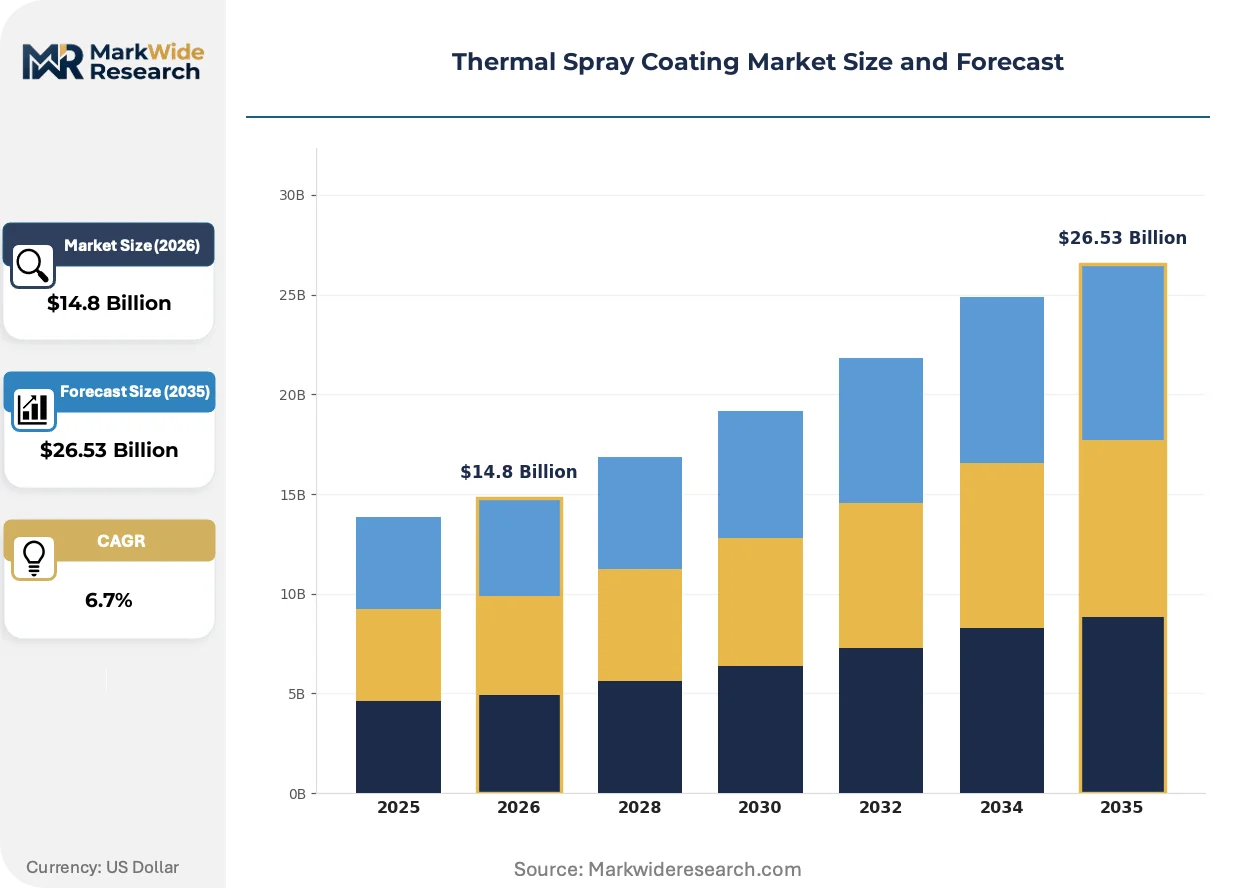
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Material: Ceramic, Metal, Polymer, Composite Application: Aerospace, Automotive, Industrial Equipment, Energy Technology: Plasma Spray, HVOF, Flame Spray, Cold Spray End User: Aerospace Manufacturers, Power Plants, Oil & Gas, Defense Contractors |
| Companies Covered | Oerlikon Metco, Praxair Surface Technologies, Bodycote, H.C. Starck, Surface Technology, ASB Industries, A&A Thermal Spray Coatings, Flame Spray Technologies, Metallisation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Spray Coating Market Emerging Trajectories
Cold spray equipment is miniaturizing deposition footprints while regulatory pressure on hexavalent chromium compounds accelerates bond coat reformulation. These forces compress traditional technology adoption curves and reshape supplier-customer technical relationships.
Portable cold spray systems are miniaturizing equipment form factors for field repair applications. Pipeline operators and shipyard maintenance crews deploy handheld units for on-site corrosion protection without substrate thermal damage. The technology is miniaturizing capital barriers and enabling decentralized coating service delivery previously confined to fixed facilities.
REACH authorization requirements for chromium trioxide in aerospace bond coats force feedstock suppliers toward trivalent chromium and cobalt-based alternatives. German coating shops face 2024 sunset dates for legacy hexavalent formulations. Aerospace OEMs in France and Germany accelerate alternative qualification programs to maintain European supply chain continuity.
Service-based contracting now dominates procurement for industrial equipment refurbishment. German machine rebuilders specify coating turnaround speed over unit price, compressing supplier selection to dense service center networks. This behavioral shift concentrates coating volumes with regional players capable of 48-hour part return cycles.
Thermal Spray Coating Market Segmentation
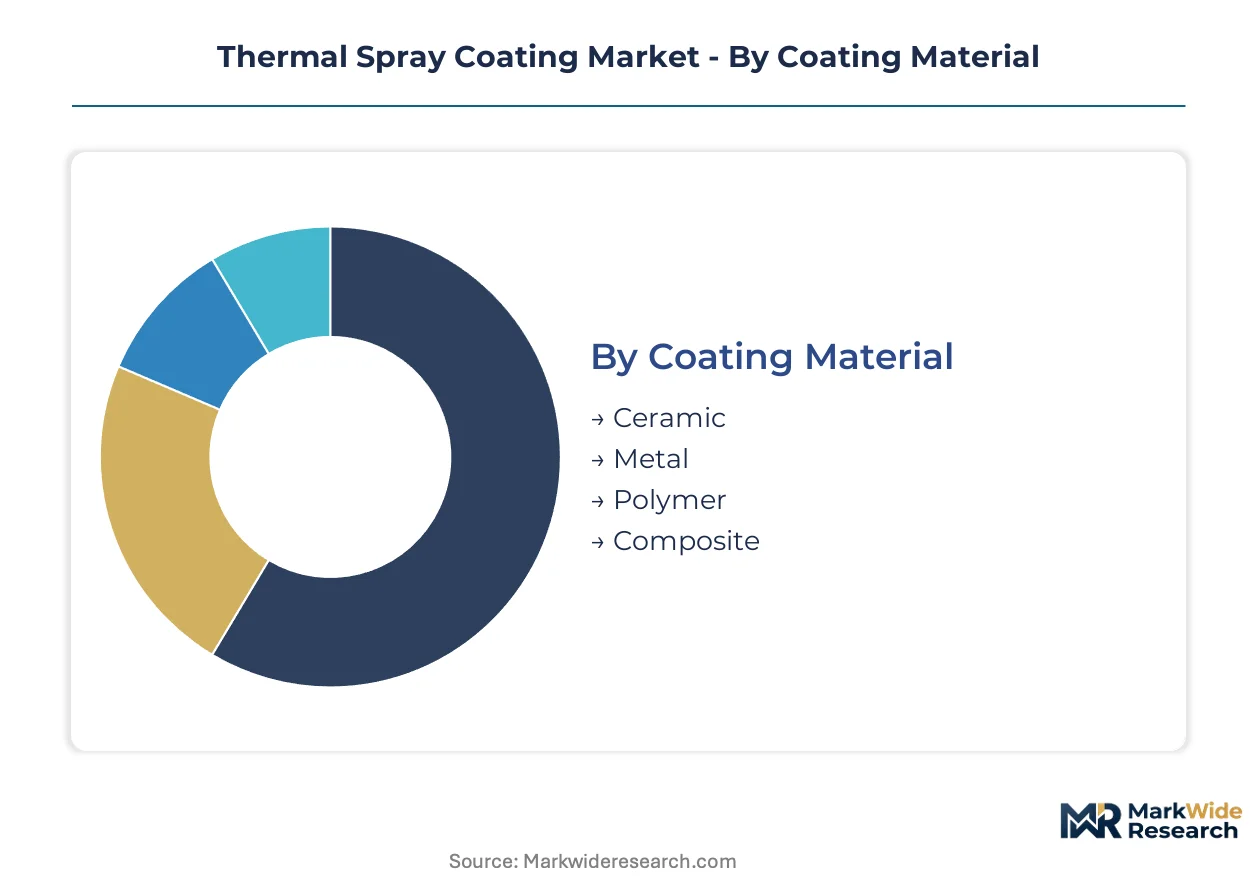
Thermal spray coating procurement channels diverge sharply by material chemistry and deposition technology. Aerospace OEMs route ceramic thermal barrier specifications through captive coating cells, while industrial refurbishment flows through dense third-party service networks.
Coating Material:
Material selection determines whether coatings flow through equipment-integrated supply channels or independent powder distributors.
- Ceramic:Yttria-stabilized zirconia formulations dominate turbine blade thermal barrier applications where operating temperatures exceed 1,000°C. German aerospace OEMs in Munich and Hamburg specify ceramic coatings through captive plasma spray cells to control feedstock qualification.
- Metal:Nickel-chromium and cobalt-based alloys provide wear resistance for oil and gas downhole components. US Gulf Coast operators source metal coatings through Praxair Surface Technologies' HVOF service centers to meet API specifications.
- Polymer:Polyamide and fluoropolymer powders deliver chemical resistance for pump housings and valve components.
- Composite:Ceramic-metal blends combine thermal insulation with structural toughness for hybrid aerospace applications.
By volume, Metal coatings lead. By growth pace, Ceramic is ahead.
Application:
End-use verticals stratify by part complexity and regulatory burden, with aerospace commanding premium pricing and industrial equipment driving service velocity.
- Aerospace:Engine hot-section components require AS9100-certified thermal barrier systems with full traceability. French and German OEMs concentrate specification authority in Toulouse, Hamburg, and Munich engineering centers.
- Automotive:Piston ring and cylinder bore coatings shift toward HVOF deposition for improved fuel efficiency.
- Industrial Equipment:Printing press and machine tool refurbishment in Germany's Ruhr region generates 48-hour turnaround demands that favor Bodycote's dense service center model.
- Energy:Gas turbine hot gas path components combine thermal protection with corrosion resistance for combined cycle plants.
Aerospace captures the highest margin per kilogram deposited. Industrial Equipment moves the largest coating mass annually.
Technology:
Capital intensity and substrate sensitivity partition technology adoption between in-house manufacturing and outsourced job shop execution.
- Plasma Spray:Automated systems deposit ceramic thermal barriers with precise thickness control for rotating engine components. Oerlikon Metco's integrated powder-equipment-service model dominates European aerospace supply chains.
- HVOF:High-velocity oxy-fuel systems achieve superior coating density for oil and gas component repair. US operators favor HVOF over flame spray for API-compliant downhole tool restoration.
- Flame Spray:Lower capital requirements sustain job shop entry for general industrial corrosion protection.
- Cold Spray:Solid-state deposition enables temperature-sensitive substrate repair without phase transformation. Portable systems expand field repair capability for pipeline and shipyard maintenance crews.
Plasma Spray retains the largest installed base. Cold Spray is climbing the fastest as defense contractors adopt additive repair protocols.
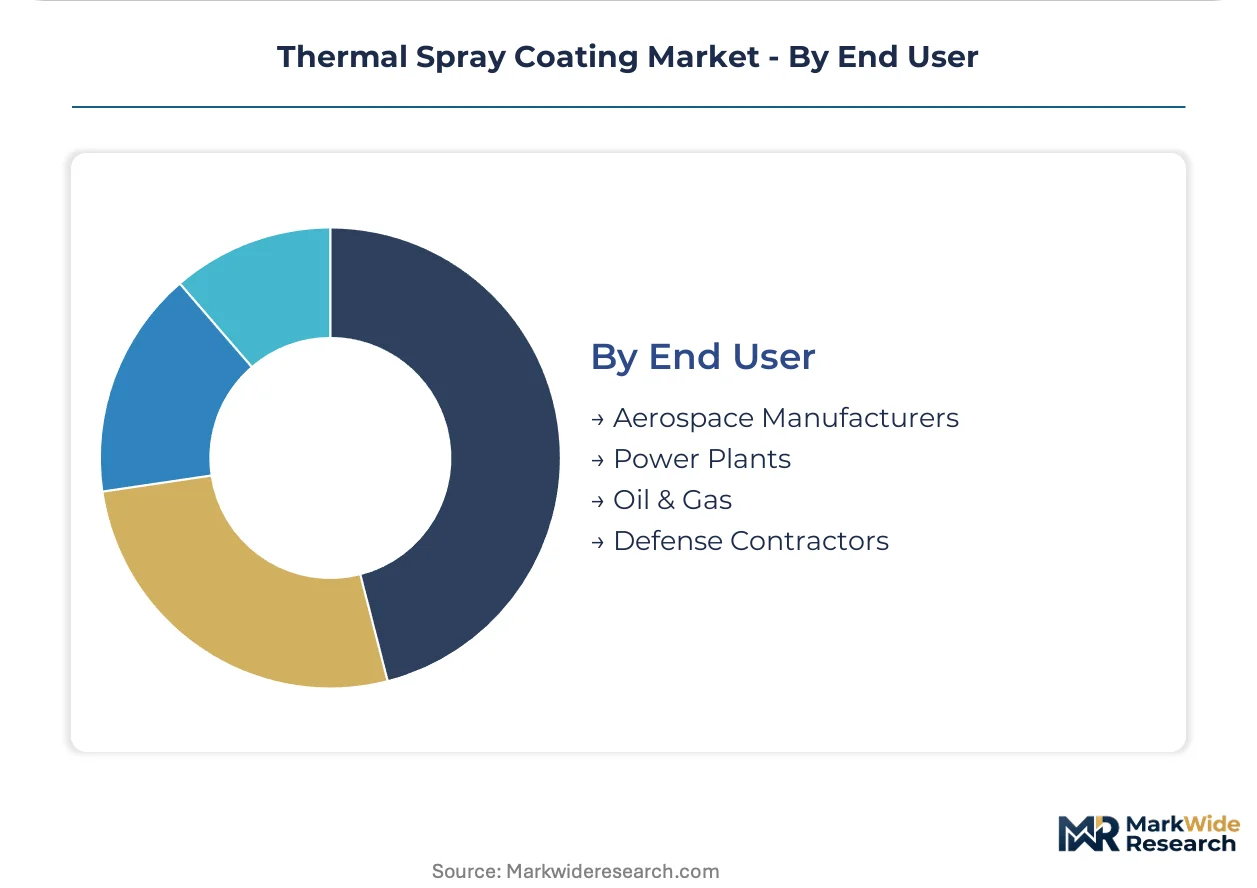
End User:
Customer archetypes diverge by procurement rhythm, with defense maintenance depots compressing qualification timelines and power plants extending maintenance cycles.
- Aerospace Manufacturers:Commercial aviation OEMs specify coating systems through long-term supply agreements with integrated powder-equipment vendors. Hamburg and Toulouse engineering centers drive European thermal barrier qualification.
- Power Plants:Combined cycle gas turbine operators schedule coating refurbishment during planned outages, favoring regional service providers with rapid mobilization capability.
- Oil & Gas:Downhole tool manufacturers and drilling contractors specify HVOF coatings for wear resistance in abrasive wellbore environments.
- Defense Contractors:Military aviation and naval maintenance depots accelerate cold spray adoption for component restoration without disassembly. US Navy shipyards and German defense maintenance facilities drive technology transition.
Defense Contractors are expanding most quickly. Aerospace Manufacturers maintain the largest committed coating volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German coating service exports flow to French and UK aerospace maintenance depots, while US Gulf Coast operators source HVOF systems through cross-border equipment supply chains.
United States
Defense maintenance depots in Virginia and California accelerate cold spray adoption for naval aviation component restoration. EPA Clean Air Act permitting requirements concentrate coating shop investments in Texas and Louisiana petrochemical corridors. Houston-area service centers process downhole tool refurbishment for Permian Basin operators under API specification protocols.
Germany
Ruhr region machine rebuilders generate concentrated demand for 48-hour turnaround coating services on aging printing press fleets. REACH authorization deadlines for chromium trioxide force Munich and Hamburg aerospace OEMs to qualify trivalent chromium bond coat alternatives. Bavarian coating shops face 2024 sunset dates for legacy hexavalent formulations in turbine blade applications.
France
Toulouse engineering centers specify ceramic thermal barrier systems for commercial aviation engine programs. ANSM oversight of aerospace material qualification shapes feedstock approval timelines for domestic coating suppliers. Lyon-area industrial equipment refurbishment clusters drive service-based contracting for corrosion-resistant metal coatings.
China
MIIT industrial equipment modernization programs expand coating adoption for machine tool remanufacturing in Yangtze River Delta manufacturing hubs. GB standards for thermal spray personnel certification constrain workforce scaling in Shanghai and Jiangsu province service centers. Local automotive OEMs specify HVOF piston ring coatings to meet fuel efficiency targets under dual carbon policy frameworks.
Japan
METI-sponsored additive manufacturing initiatives integrate cold spray deposition with directed energy deposition for aerospace component repair. JIS standards for thermal spray coating thickness control shape quality requirements in Nagoya-area turbine maintenance facilities. Osaka-based industrial equipment suppliers specify ceramic-metal composite coatings for hybrid thermal-structural applications in power generation equipment.
Thermal Spray Coating Market Vendor Landscape
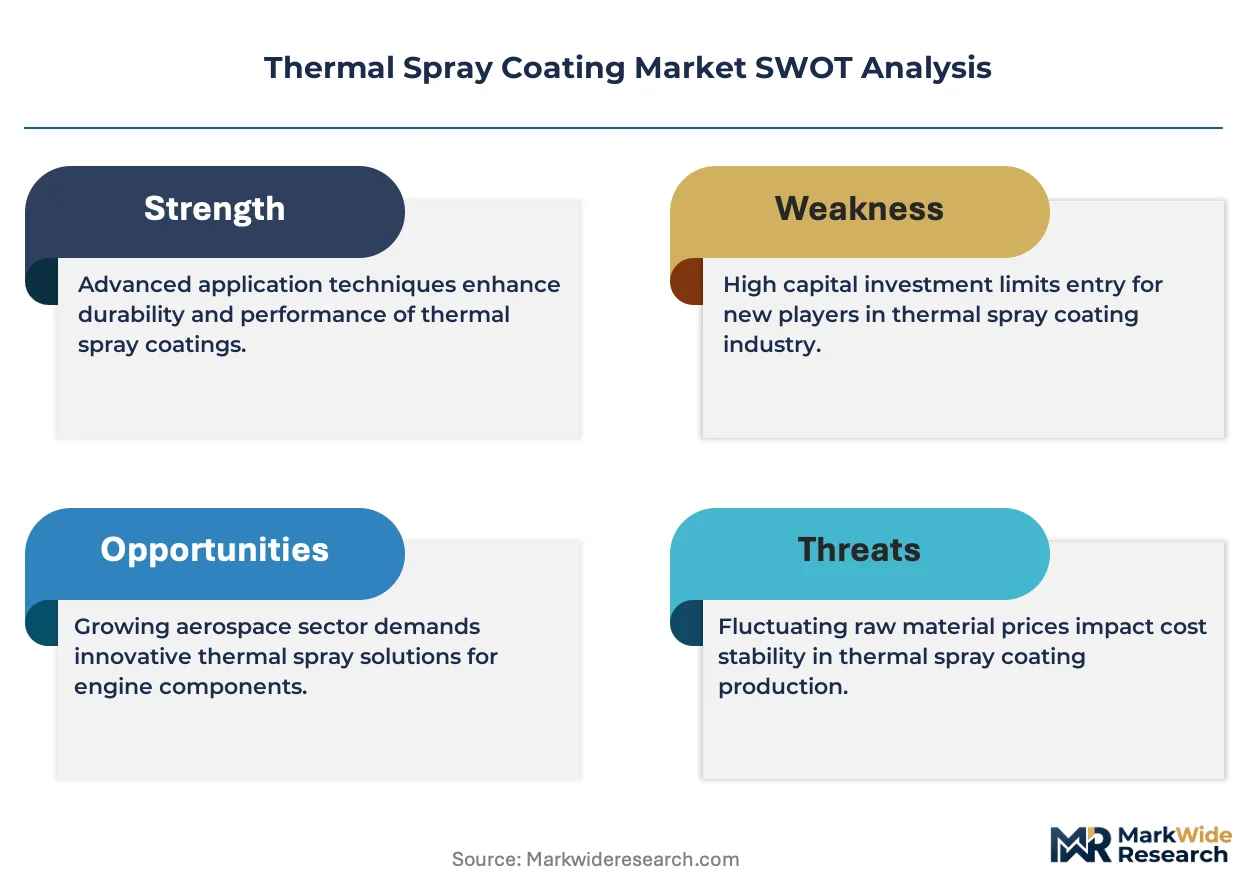
Player mix skews toward integrated powder-equipment-service providers with captive feedstock production and dense regional service networks. Market structure concentrates around three strategic archetypes: equipment-integrated powder suppliers controlling aerospace supply chains, independent coating job shops competing on turnaround velocity, and captive in-house operations at major OEMs. Dominant competitive moves include backward integration into powder production and geographic densification of service center footprints.
Within the integrated-systems tier, Oerlikon Metco and Praxair Surface Technologies exemplify equipment-captive powder models that anchor European and North American aerospace coating supply chains respectively. Bodycote occupies a position representing the dense service network archetype, with turnaround-speed competition concentrated in German industrial refurbishment markets. These three entities collectively illustrate how powder control, equipment integration, and geographic proximity to demand clusters define competitive positioning in thermal spray coating procurement.
| Leading Market Players |
|---|
| Oerlikon Metco |
| Praxair Surface Technologies |
| Bodycote |
| H.C. Starck |
| Surface Technology |
| ASB Industries |
| A&A Thermal Spray Coatings |
| Flame Spray Technologies |
| Metallisation Limited |
| Others |
Supply Flow & Price Mechanics
Automated plasma spray system utilization rates above eighty percent in European aerospace clusters create scale advantages that compress per-kilogram coating costs while simultaneously raising entry barriers for independent job shops. This capacity concentration in Germany and France enables integrated powder-equipment vendors to anchor price floors through captive feedstock supply, leaving smaller operators exposed to volatile nickel and cobalt alloy spot markets.
Pricing Analysis
The technology-generation pricing gap separates legacy flame spray services from HVOF premium tiers and emerging cold spray premium-plus positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and turnaround velocity, with AS9100-certified aerospace work commanding substantial premiums over general industrial corrosion protection. Cost compression in standard-tier HVOF services is intensifying because Gulf Coast oil and gas operators consolidate procurement volumes under long-term maintenance contracts. Defense contractors exhibit the lowest price sensitivity due to mission-critical performance requirements, while German machine tool rebuilders prioritize forty-eight-hour turnaround over unit cost minimization.
Supply Chain Analysis
Strategic stockpiling of yttria-stabilized zirconia and nickel-chromium powders dominates aerospace supply planning, while just-in-time feedstock delivery sustains leaner industrial refurbishment operations. Powder production concentrates in Germany, the United States, and Switzerland, with H.C. Starck and Oerlikon Metco controlling premium ceramic and superalloy feedstock formulations. Supply chain risk centers on single-source vulnerability for aerospace-qualified bond coat alternatives as REACH sunset dates eliminate legacy hexavalent chromium suppliers. Distribution runs through equipment-integrated vendor networks for aerospace OEMs and dense third-party service center clusters for industrial equipment refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal spray coating incumbents face substitution pressure from directed energy deposition and additive manufacturing repair protocols that bypass traditional spray deposition entirely. Defense maintenance depots increasingly specify hybrid cold spray-DED restoration workflows that threaten standalone thermal spray service volumes.
For Market Incumbents: Fortify powder supply security through backward integration into ceramic and superalloy feedstock production, eliminating third-party qualification dependencies that REACH authorization timelines expose. Anchor aerospace supply relationships by embedding technical service teams within Hamburg and Toulouse engineering centers, countering emerging cold spray equipment vendors that pitch lower-temperature deposition as a replacement technology. For New Entrants and Emerging Players: Differentiate on portable cold spray deployment for field repair applications in pipeline and shipyard maintenance, where fixed-facility incumbents lack mobilization capability. Target German Ruhr region industrial equipment refurbishment clusters with forty-eight-hour turnaround guarantees, exploiting incumbent capacity constraints and ISO 14918 certification scarcity that limits qualified competitor expansion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-integrated powder suppliers with long-term aerospace supply agreements and captive service networks. Over the projection horizon, acquisition candidates with dense European service center footprints and REACH-compliant bond coat qualification pipelines offer superior defensive positioning. Monitor cold spray equipment adoption rates in US Navy and German defense maintenance depots as the signal indicating technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Captive yttria-stabilized zirconia supply secures aerospace qualification pipelines against REACH-driven feedstock disruption. |
| Geographic Densification of Service Centers | Forty-eight-hour turnaround capability in German industrial clusters captures equipment refurbishment volume from aging machine tool fleets. |
| Cold Spray Equipment Miniaturization | Portable deposition systems unlock pipeline and shipyard field repair markets previously confined to fixed facilities. |
| Alternative Bond Coat Qualification | Trivalent chromium and cobalt-based formulations ensure European aerospace supply chain continuity past REACH sunset dates. |
| Hybrid Additive Repair Partnerships | Cold spray-DED integration positions coating vendors within defense maintenance depot workflow specifications. |
Methodological Framework
Cross-validation between primary interviews with thermal spray coating shop operators, aerospace OEM procurement directors, and defense maintenance depot engineers anchors the qualitative findings against secondary validation from EPA emissions filings, ECHA REACH authorization databases, and ISO 14918 certification registries. Bottom-up triangulation aggregates individual service center capacity and utilization estimates, while top-down reconciliation cross-checks against national industrial production indices and aerospace engine delivery forecasts.
Sensitivity analysis across the analysis window tests forecast robustness against alternative scenarios for REACH authorization timeline acceleration and cold spray technology adoption curves. Segmentation dimensions modeled include coating material chemistry, deposition technology, end-use vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year market sizing, with specific inputs including German machine tool fleet age profiles and US defense maintenance depot capital expenditure plans.
The analysis sits within stated boundaries; outcomes outside sustained aerospace production rates and stable regulatory phase-out schedules would require recalibration. Forecasts reflect assumptions regarding powder feedstock qualification continuity and certification pipeline throughput. Revision becomes warranted when cold spray equipment cost curves cross plasma spray system economics or when alternative bond coat qualification timelines exceed OEM engineering capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market