
 Aerogel Blanket Market | 2026-2036
Aerogel Blanket Market Size, Share, and Industry Trends Forecast 2026-2036
Aerogel Blanket Market Analysis
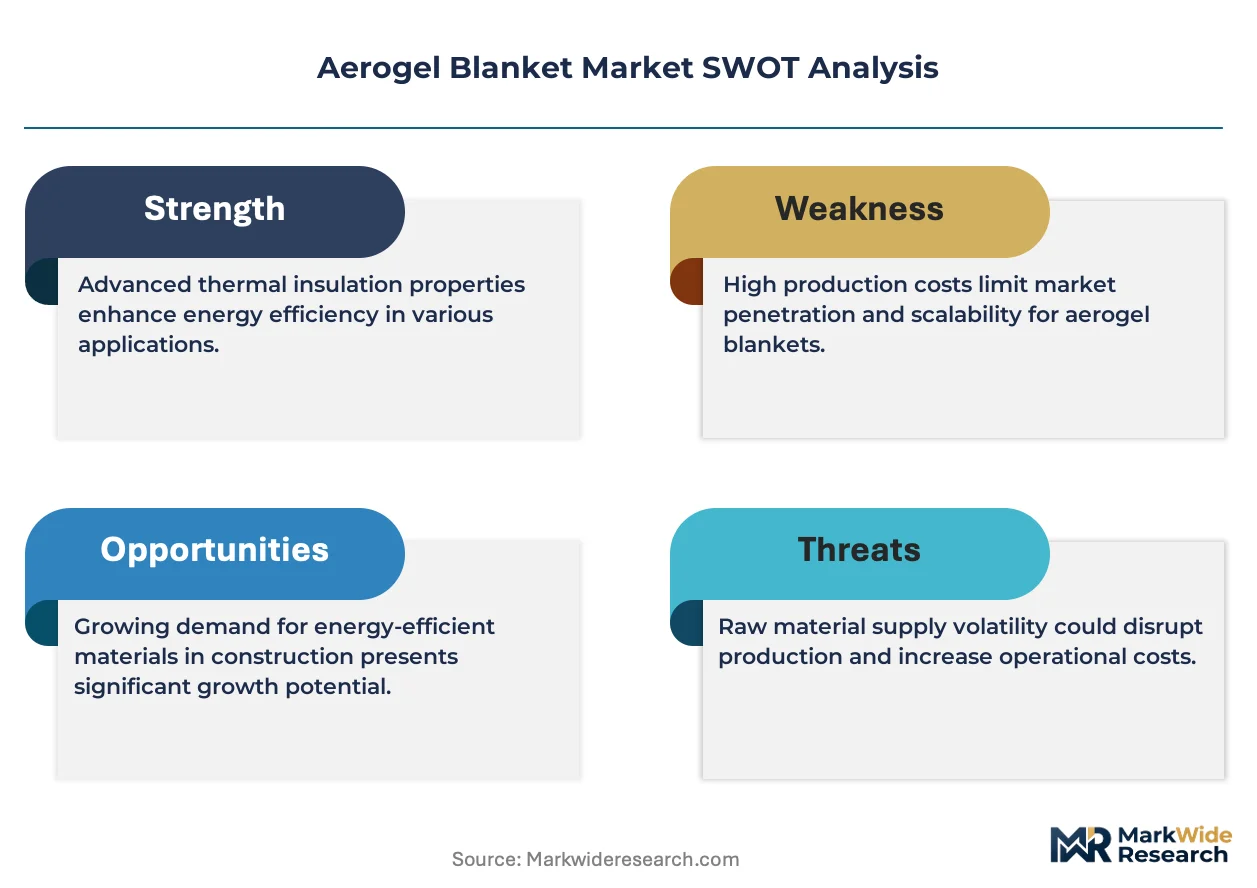
Buyer concentration in oil and gas is decoupling as utility-scale battery developers and data center operators enter procurement channels. Aspen Aerogels, Inc. anchors North American supply through specialized manufacturing for energy infrastructure. Cabot Corporation extends its materials science footprint across industrial insulation grades. ENERSENS competes in European markets with tailored aerogel solutions for building envelopes.
An aerogel blanket is a flexible insulation material composed of silica aerogel embedded in a fiber reinforcement matrix, typically achieving thermal conductivity below 0.020 W/m·K and serving critical temperature control in confined or weight-sensitive installations. The blanket format dominates commercial volumes due to its adaptability to curved surfaces and reduced installation labor compared to rigid panel alternatives. Thermal insulation leads application demand from LNG shipping and refining assets, while energy storage represents the fastest-growing segment as battery thermal management systems adopt superinsulation layers. Sol-gel processing remains the foundational technology pathway, though supercritical drying variants command premium positioning in aerospace and defense specifications.
EPA emissions standards and OSHA workplace safety rules shape product certification requirements for U.S. industrial insulation contractors. REACH compliance and CE marking under the EU Construction Products Regulation govern material content declarations and fire performance classifications for European market access. China's GB standards and dual carbon goals from MEE are tightening building envelope performance thresholds. Stakeholders must monitor how evolving fire safety codes and embodied carbon accounting frameworks reshape material specification criteria across their priority markets.
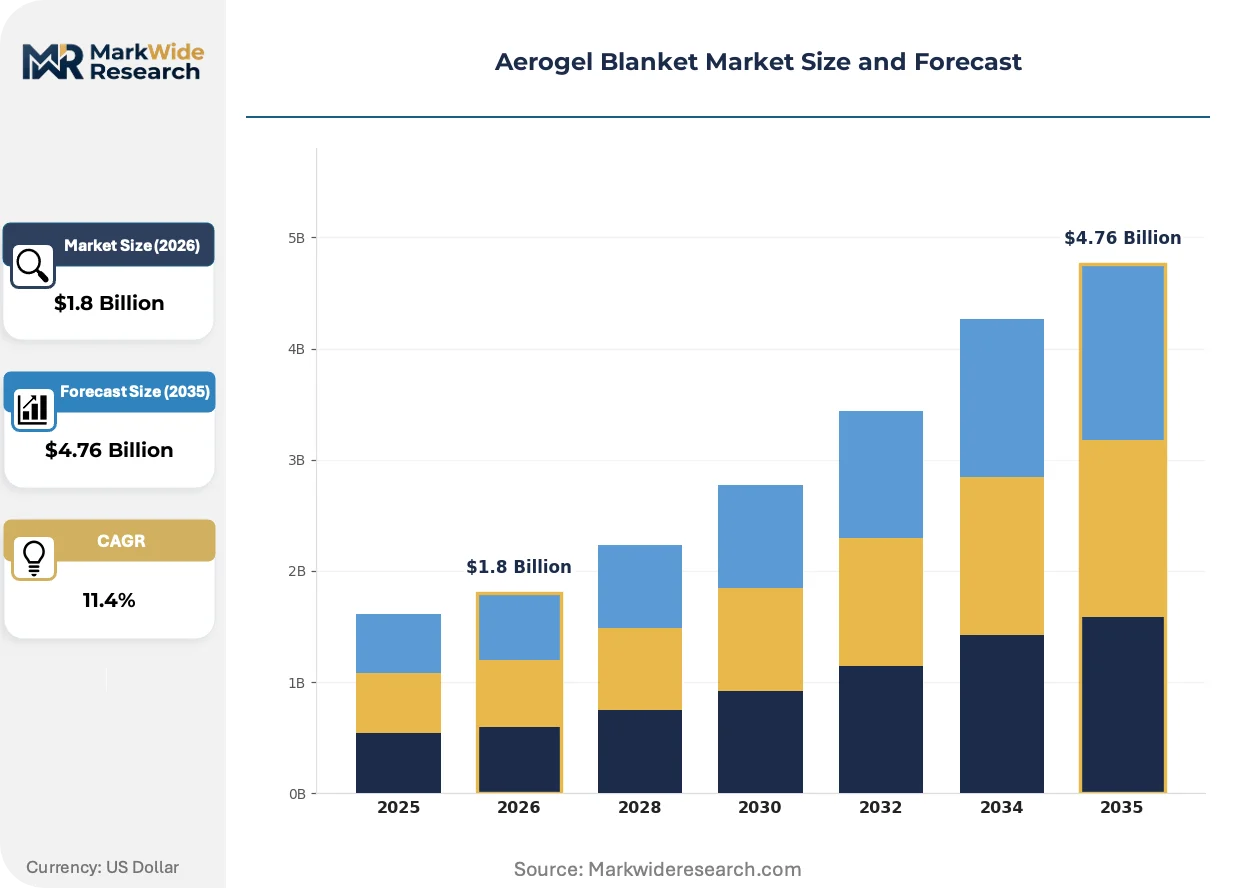
Market Dynamics
Supercritical drying process improvements are compressing unit economics for silica aerogel production while tightening thermal performance specifications from LNG infrastructure buyers reshape procurement criteria across energy and construction verticals.
Growth Catalysts
- EU Green Deal building codes:Tightened envelope performance standards under the Energy Performance of Buildings Directive mandate superinsulation layers in retrofit programs across Germany, France, and the Netherlands.
- LNG shipping fleet expansion:Cryogenic cargo containment systems on newbuild vessels require flexible sub-zero insulation that rigid alternatives cannot provide.
- Sol-gel automation:Continuous processing breakthroughs at pilot scale are reducing batch-to-batch thermal conductivity variance below 0.003 W/m·K.
Market Restraints
- Tetraethyl orthosilicate volatility:Precursor chemical costs swing with semiconductor foundry demand, compressing margin predictability for blanket producers.
- Single-source supercritical CO2 equipment:German and Italian machinery suppliers control 70% of high-pressure dryer manufacturing, creating bottleneck risk.
- Glass wool price anchoring:Mineral fiber alternatives at 15-20% of aerogel cost per R-value constrain specification in cost-sensitive commercial construction.
Strategic Opportunities
- India PLI scheme for advanced materials:Domestic manufacturing incentives for critical minerals and insulation align with industrial cold-chain buildout.
- Battery thermal runaway containment:EV pack designers are specifying aerogel compression pads between cells as a passive fire barrier.
- Direct-to-contractor digital channels:Specialized insulation distributors in Texas and Alberta are bypassing traditional reps for oilfield procurement.
Industry Challenges
- Fire classification testing backlog:EN 13501-1 reaction-to-fire certification queues at notified bodies extend 14-18 months for new product formulations.
- Cross-functional talent scarcity:Sol-gel chemists with fiber-matrix composite experience command premium compensation as materials science programs undersupply hybrid profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerogel Blanket Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic, Granular, Blanket, Panel End User: Aerospace, Oil & Gas, Construction, Automotive Application: Thermal Insulation, Fire Protection, Soundproofing, Energy Storage Technology: Sol-Gel, Supercritical Drying, Freeze Drying, Spray Drying |
| Companies Covered | Aerogel Technologies, LLC, ENERSENS, Aspen Aerogels, Inc., HUATAO GROUP LTD., Active Aerogels, Cabot Corporation, Armacell, Green Earth Aerogel Technologies, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerogel Blanket Market Emerging Trajectories
Manufacturing automation and regulatory carbon accounting are converging to redefine how aerogel blankets are specified, priced, and installed across temperature-critical infrastructure.
Ambient-pressure drying via hexamethyldisilazane surface modification is electrifying cost structures for mid-performance grades. Industrial HVAC contractors in the US Gulf Coast are piloting these materials for ductwork insulation where weight limits constrain glass wool. The process compression is enabling specification in commercial building segments previously priced out of aerogel adoption.
REACH SVHC candidate list expansion to include certain silane precursors is forcing reformulation investments across European supply chains. Manufacturers serving the German automotive sector are accelerating alternative surface chemistry development to maintain CE marking compliance. The regulatory pressure concentrates most acutely on suppliers of thin-gauge blankets for electric vehicle battery packs.
Specification authority is migrating from general contractors to specialized energy consultants who model whole-system thermal bridging. This pattern disrupts traditional distribution through building material wholesalers in California and New York. Data center developers in Northern Virginia now require consultant-validated U-value calculations before blanket approval.
Aerogel Blanket Market Segmentation
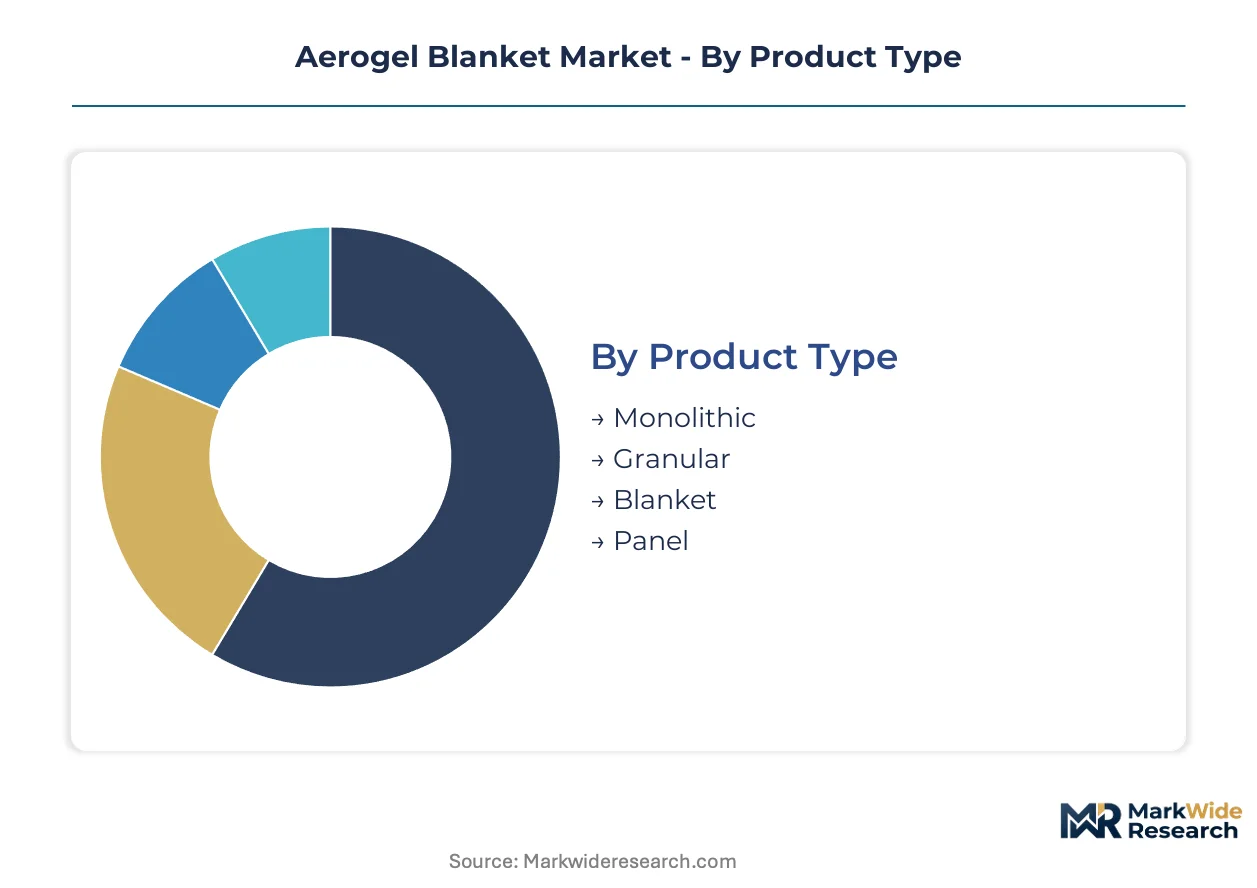
Aerogel blanket procurement varies sharply across product formats and end-use verticals, with certification requirements and thermal performance thresholds dictating specification authority. Understanding how segments cluster around LNG infrastructure, battery thermal management, and building envelope retrofits clarifies where margin concentrates and where volume expansion accelerates.
Product Type:
Blanket formats face distinct certification burdens: marine LNG applications require DNV-GL type approval, while building envelope specifications demand EN 13501-1 reaction-to-fire classification that monolithic and granular forms rarely pursue.
- Blanket:Silica aerogel embedded in fiber reinforcement matrices achieves thermal conductivity below 0.020 W/m·K. Demand concentrates in US Gulf Coast LNG export terminals and German industrial retrofit programs where curved surface adaptability reduces installation labor versus rigid alternatives.
- Panel:Rigid compressed aerogel boards serve aerospace cabin insulation and data center containment walls requiring structural rigidity. German automotive battery pack designers specify thin-gauge panels for thermal runaway barriers between cells.
- Monolithic:Cast silica aerogel blocks with optical transparency serve specialized aerospace window insulation and scientific instrument thermal isolation.
- Granular:Crushed aerogel particles fill cavity walls and double-skin facades where blown-in installation outperforms blanket cutting complexity.
Blanket sits at the top of the volume ranking, with panel climbing the fastest as EV battery pack specifications proliferate.
End User:
Cost tier stratification separates aerospace premium specifications from construction commodity procurement, with oil and gas occupying the mid-tier volume-leader position.
- Oil & Gas:Subsea pipeline operators and LNG liquefaction plants specify cryogenic-grade blankets for -160°C cargo containment. US Permian Basin operators are expanding procurement through direct-to-contractor digital channels in Texas and Alberta.
- Construction:EU Green Deal retrofit mandates in Germany, France, and the Netherlands are accelerating superinsulation specification for building envelope applications where energy efficiency codes tighten performance thresholds.
- Automotive:EV battery thermal management systems adopt aerogel compression pads as passive fire barriers between cells, with REACH SVHC compliance forcing reformulation investments across European supply chains.
- Aerospace:Supercritical-dried grades command premium positioning for satellite thermal protection and aircraft cabin insulation where weight constraints dominate specification criteria.
Oil and gas commands the largest revenue base, though automotive is expanding most quickly as battery pack volumes scale.
Application:
Application selection tracks directly to temperature regime: sub-zero LNG infrastructure, ambient building envelopes, and elevated battery thermal runaway scenarios each demand distinct fiber-matrix configurations and surface chemistries.
- Thermal Insulation:Dominates commercial volumes through LNG shipping fleet expansion and industrial cold-chain buildout. Cryogenic cargo containment systems on newbuild vessels require flexible sub-zero insulation that rigid alternatives cannot provide.
- Energy Storage:Battery pack designers specify aerogel layers between cells to delay thermal propagation during failure events. Northern Virginia data center developers now require consultant-validated U-value calculations before blanket approval.
- Fire Protection:Thin-gauge blankets serve as passive fire barriers in electric vehicle architectures and high-rise building curtain walls where EN 13501-1 classification testing backlog extends 14-18 months.
- Soundproofing:Acoustic damping applications in industrial HVAC systems leverage aerogel density gradients where weight limits constrain traditional mineral fiber alternatives.
Thermal insulation maintains volume leadership, while energy storage shows the steepest expansion trajectory as utility-scale battery deployments multiply.
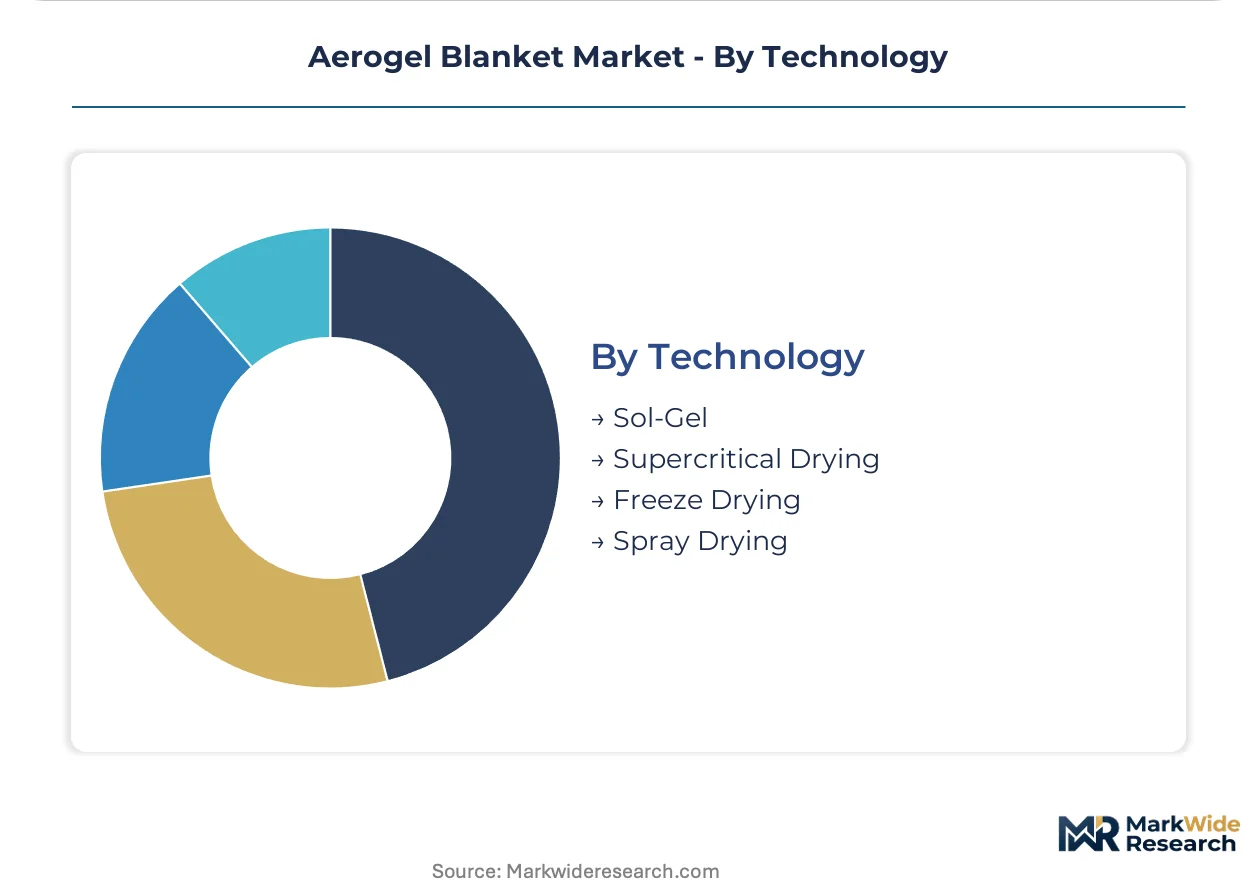
Technology:
Supply concentration in supercritical CO2 equipment manufacturing—where German and Italian machinery suppliers control 70% of high-pressure dryer output—creates bottleneck risk that shapes technology selection economics.
- Sol-Gel:Foundational silica network formation via alkoxide hydrolysis and condensation. Continuous processing breakthroughs at pilot scale are reducing batch-to-batch thermal conductivity variance below 0.003 W/m·K.
- Supercritical Drying:CO2 extraction preserves nanoscale porosity without capillary collapse. Ambient-pressure drying via hexamethyldisilazane surface modification is electrifying cost structures for mid-performance grades in US Gulf Coast HVAC ductwork pilots.
- Freeze Drying:Sublimation-based solvent removal serves lower-performance segments where cost sensitivity outweighs thermal conductivity optimization.
- Spray Drying:Rapid particle formation enables granular product streams for cavity fill applications in commercial building retrofits.
Sol-gel processing anchors production volumes, with supercritical drying gaining share fastest as LNG infrastructure buyers tighten thermal performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial retrofit programs under the EU Green Deal contrast with China's state-directed LNG infrastructure buildout, revealing how divergent policy architectures shape demand geography. The United States leverages Permian Basin energy investment alongside data center clustering in Northern Virginia. Each national market exhibits distinct procurement channel evolution and regulatory compliance burdens.
United States
Gulf Coast LNG export terminals and Permian Basin pipeline operators anchor cryogenic-grade blanket procurement. EPA emissions standards and OSHA workplace safety rules govern contractor certification requirements. Houston-based insulation distributors are pioneering direct-to-contractor digital channels that bypass traditional manufacturer representative networks.
Germany
Industrial building envelope retrofits under the Energy Performance of Buildings Directive mandate superinsulation layers across manufacturing facilities. REACH compliance and CE marking under the EU Construction Products Regulation enforce material content declarations and fire performance classifications. The Ruhr industrial corridor concentrates specification activity among energy consultants modeling whole-system thermal bridging.
China
State-backed LNG receiving terminal expansion and dual carbon goals from MEE are tightening building envelope performance thresholds. GB standards govern domestic product certification while import substitution policies favor local manufacturing scale-up. Yangtze River Delta shipyards are integrating cryogenic cargo containment systems on newbuild vessels.
India
Industrial cold-chain infrastructure buildout aligns with PLI scheme incentives for advanced materials manufacturing. Central Electricity Authority regulations and BIS standards shape insulation performance requirements for commercial construction. Gujarat pharmaceutical clusters are adopting superinsulation for temperature-sensitive production environments.
United Arab Emirates
District cooling system expansion and high-performance building mandates for Expo legacy developments drive specification of weight-constrained insulation. MOHAP and local civil defense authorities enforce fire safety classifications for curtain wall applications. Dubai's sustainable city initiatives are piloting aerogel layers in net-zero building demonstrations.
Aerogel Blanket Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven chemical majors and application-specific fabricators occupy distinct value capture zones. The vendor base clusters around three archetypes: integrated materials science conglomerates with insulation divisions, dedicated aerogel technology specialists, and regional composite manufacturers serving cost-sensitive construction segments. Capacity expansion and strategic partnerships dominate competitive moves, with supercritical drying equipment access serving as a critical constraint on scale-up velocity.
Among North American specialists, Aspen Aerogels, Inc. exemplifies the dedicated technology archetype, while Cabot Corporation represents diversified materials science positioning across industrial insulation grades. ENERSENS occupies a focused European specialist position serving building envelope retrofit demand. These three anchors illustrate how geographic origin and corporate structure shape strategic optionality—Massachusetts-based incorporation, Delaware-registered conglomerate scale, and French S.A.S. specialization each confer distinct channel access and regulatory navigation capabilities.
| Leading Market Players |
|---|
| Aerogel Technologies, LLC |
| ENERSENS |
| Aspen Aerogels, Inc. |
| HUATAO GROUP LTD. |
| Active Aerogels |
| Cabot Corporation |
| Armacell |
| Green Earth Aerogel Technologies |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
LNG liquefaction plant operators concentrate procurement authority for cryogenic-grade aerogel blankets, anchoring contract-based long-term offtake pricing that insulates premium tiers from spot-market volatility in precursor chemicals. This buyer concentration enables volume-scale discounts while supercritical drying equipment scarcity preserves margin capture for incumbent manufacturers serving energy infrastructure.
Pricing Analysis
Capacity additions in China are reshaping price floors for mid-performance grades as ambient-pressure drying adoption accelerates. Three-tier pricing structure across premium, standard, and economy levels separates DNV-GL certified marine specifications from commercial building envelope grades and industrial HVAC commodity tiers. Cost compression in standard grades stems from tetraethyl orthosilicate volatility tied to semiconductor foundry demand swings. Oil and gas contractors exhibit highest price sensitivity due to glass wool alternatives at 15-20% of aerogel cost per R-value, while aerospace specifications show least sensitivity given weight-constrained design mandates.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for blanket roll stock and custom-cut shipments. Manufacturing concentrates in the United States, Germany, and China as supercritical CO2 equipment access constrains scale-up velocity. Raw material flows draw from semiconductor-grade silica precursors, glass fiber reinforcement mats, and hexamethyldisilazane surface modifiers. Single-source vulnerability in German and Italian high-pressure dryer manufacturing creates bottleneck risk for capacity expansion. Distribution runs through specialized insulation distributors bypassing traditional manufacturer representative networks in Texas and Alberta oilfields.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal retrofit mandates tightening building envelope standards and China's state-directed LNG infrastructure buildout with lower compliance costs. Regulatory divergence between REACH SVHC expansion and GB standard alignment creates margin dispersion across manufacturing footprints.
For Market Incumbents: To counter ambient-pressure drying entrants compressing mid-grade price floors, secure captive supply of supercritical CO2 equipment through long-term machinery partnerships with German and Italian suppliers. Deepen backward integration into tetraethyl orthosilicate precursor production to buffer margin predictability against semiconductor foundry demand volatility. Prioritize EN 13501-1 certification investment to extend reaction-to-fire testing backlog advantages.
For New Entrants and Emerging Players: Launch via direct-to-contractor digital channels targeting Permian Basin pipeline operators and Northern Virginia data center developers seeking consultant-validated U-value calculations. White-space concentrates in Indian industrial cold-chain buildout under PLI scheme incentives and UAE district cooling system expansion with weight-constrained insulation mandates. Penetrate through ambient-pressure drying cost structures enabling specification in commercial HVAC segments previously priced out of aerogel adoption.
For Investors and Strategic Acquirers: Diversified materials science conglomerates with insulation divisions are the most active acquirer in this space, seeking technology access and energy infrastructure channel control. Five-to-ten year viability hinges on battery thermal runaway containment specification scaling with EV pack volumes. Monitor EN 13501-1 certification queue lengths at notified bodies as inflection indicator for new formulation market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursors | Captive tetraethyl orthosilicate supply buffers margin predictability against semiconductor demand swings. |
| Supercritical Drying Equipment Partnership | Long-term machinery agreements with German and Italian suppliers secure capacity expansion rights. |
| Direct-to-Contractor Digital Channel Launch | Bypassing manufacturer representative networks captures oilfield procurement authority in Texas and Alberta. |
| EN 13501-1 Certification Investment | Reaction-to-fire classification extends competitive moat amid 14-18 month testing backlog at notified bodies. |
| Ambient-Pressure Drying Scale-Up | Hexamethyldisilazane surface modification electrifies cost structures for mid-performance commercial grades. |
Methodological Framework
Coverage spans the United States, Germany, China, and India, with primary inputs from each market combining interviews with LNG project procurement managers, building envelope energy consultants, battery pack thermal engineers, and industrial insulation distributors with secondary validation. Stakeholder conversations included sol-gel chemists, supercritical drying equipment specialists, and REACH compliance officers. Secondary sources encompassed customs and trade data, SEC filings from listed materials science conglomerates, EU Construction Products Regulation databases, and MEE dual carbon policy documentation. Bottom-up volume modeling triangulated against top-down energy infrastructure investment forecasts.
Rate-of-change decomposition across the analysis window applied product format segmentation by blanket, panel, monolithic, and granular forms crossed with end-use verticals in oil and gas, construction, automotive, and aerospace. Technology pathway splits between sol-gel and supercritical drying anchored production cost curves. CAGRs derived from LNG shipping fleet order books, EU Green Deal retrofit program allocations, and utility-scale battery deployment pipelines. Regional regulatory cluster modeling incorporated EPA emissions standards, REACH SVHC candidate list evolution, and GB standard tightening trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tetraethyl orthosilicate supply disruption or supercritical CO2 equipment delivery delays. Forecasts reflect assumptions on energy efficiency code adoption timing and EV battery pack specification penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Composites in United States Defense Market