
 United States Defense Market | 2026-2036
United States Defense Market Size, Share, and Industry Trends Forecast 2026-2036
United States Defense Market Outlook
A cleared engineering workforce shortage is collapsing program timelines across major weapons systems. Lockheed Martin Corporation dominates classified satellite and hypersonic programs through its Skunk Works division. RTX Corporation sustains dominance in missile defense and radar systems via extensive supplier networks. Northrop Grumman Corporation anchors the nuclear triad modernization with the B-21 Raider and Ground-Based Strategic Deterrent programs.
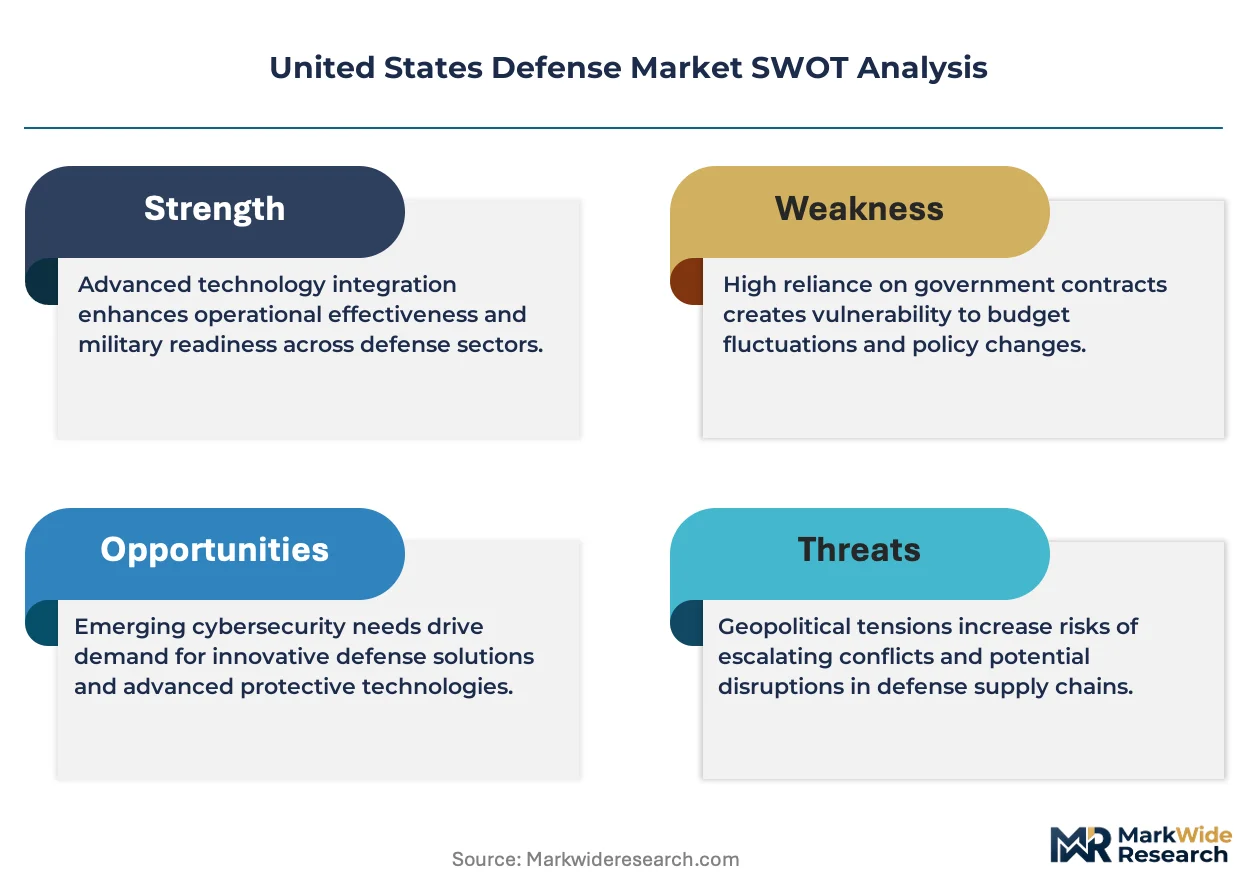
United States Defense encompasses the research, development, production, and sustainment of military platforms, weapons systems, and enabling technologies governed by federal procurement regulations and national security classification protocols. The sector operates through cost-plus and fixed-price contracts subject to Defense Federal Acquisition Regulation Supplement standards, with primary purpose being force projection and strategic deterrence. Weapons and military vehicles remain the largest value pools, while artificial intelligence represents the fastest-expanding technology segment as the Pentagon accelerates algorithmic warfare integration. Cybersecurity spending is deepening across all application areas, with surveillance and combat platforms commanding premium margins due to classified integration requirements.
The Department of Defense, Defense Counterintelligence and Security Agency, and National Institute of Standards and Technology shape market access through security clearance mandates, supply chain vetting, and cybersecurity maturity model certification requirements. These frameworks compel contractors to maintain cleared facilities, controlled access programs, and compliant information systems as baseline market participation conditions. Stakeholders must monitor how export control reforms under the International Traffic in Arms Regulations affect technology transfer boundaries with allied nations.
Market Dynamics
The Department of Defense's software modernization mandates are compressing traditional acquisition cycles and forcing contractors to restructure engineering workflows around continuous delivery pipelines rather than waterfall development schedules.
Growth Catalysts
- CMMC 2.0 Implementation:The Cybersecurity Maturity Model Certification program is mandating tiered security controls across the defense industrial base, creating sustained demand for compliance consulting and secure infrastructure upgrades.
- Hypersonic Weapons Proliferation:Multiple service branches are accelerating testing and fielding of maneuverable strike systems, driving thermal protection materials and guidance electronics procurement.
- Space Domain Awareness:Orbital congestion and adversary satellite constellations are expanding ground-based radar and optical tracking network investments.
Market Restraints
- Specialized Talent Scarcity:Cleared software engineers with embedded systems expertise command premium compensation, inflating program labor costs beyond original cost-plus estimates.
- Sole-Source Dependencies:Solid rocket motor production concentrates at two domestic suppliers, creating single-point-of-failure risk for missile program schedules.
- Export Control Friction:International Traffic in Arms Regulations reform delays are freezing technology transfer agreements with Five Eyes allies, limiting co-development opportunities.
Strategic Opportunities
- Alabama Test Range Expansion:The Army's Redstone Arsenal complex is adding hypersonic ground test capacity, attracting supplier facility relocations to the Tennessee Valley corridor.
- AI-Enabled Maintenance:Predictive algorithms applied to aircraft turbine health monitoring are reducing unplanned downtime and extending platform service intervals.
- Software-Defined Radio Convergence:Modular waveform architectures are collapsing separate communications, electronic warfare, and signals intelligence hardware into unified programmable payloads.
Industry Challenges
- Security Clearance Backlogs:Defense Counterintelligence and Security Agency processing delays are stretching program staffing timelines by six to eighteen months.
- Legacy Platform Integration:F-35 and B-21 programs must accommodate decades-old data bus standards while fielding quantum-resistant encryption, forcing complex protocol bridging architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Defense Market |
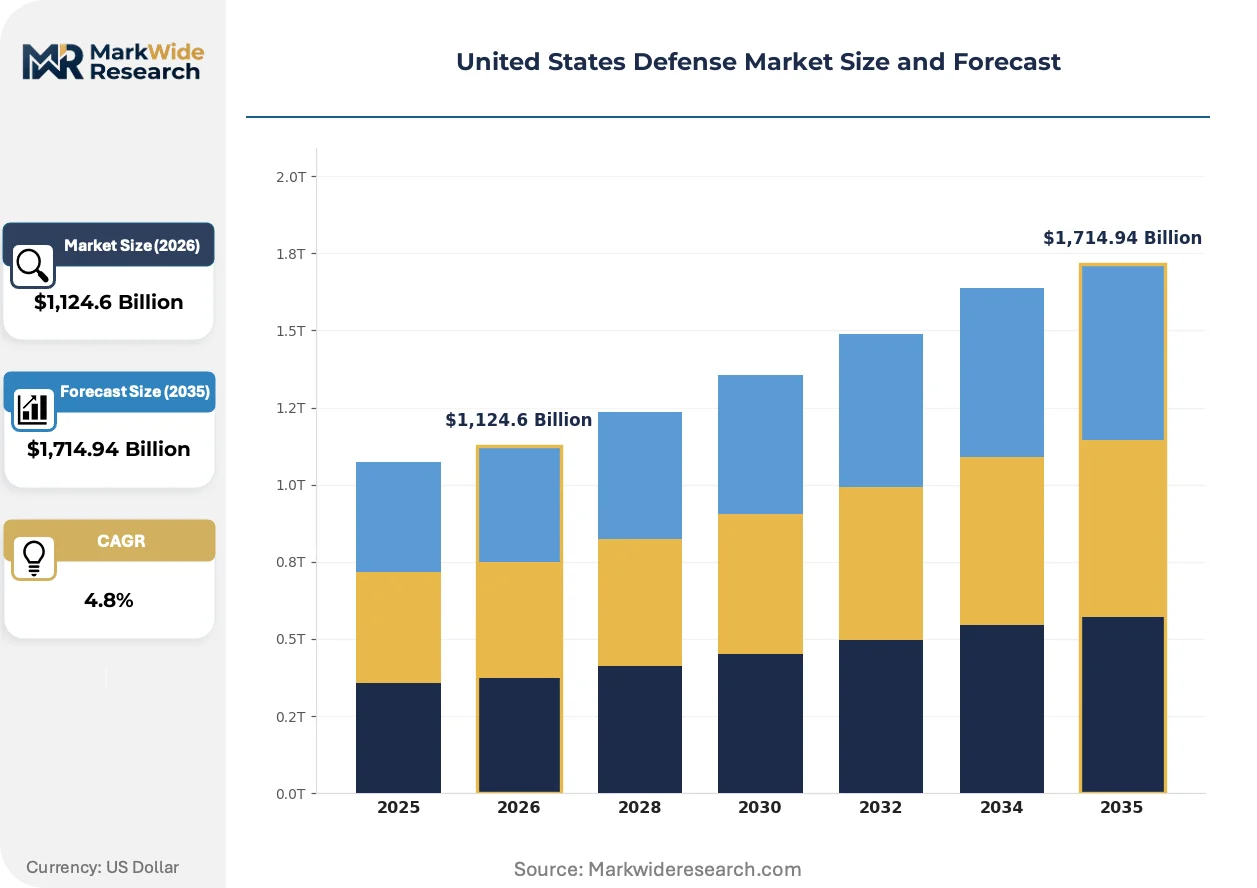
| Market Size in 2026 | $1,124.6 Billion |
| Market Size in 2035 | $1,714.94 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weapons, Ammunition, Military Vehicles, Drones Technology: Cybersecurity, Artificial Intelligence, Robotics, Communication Systems End User: Military, Defense Contractors, Government Agencies, Private Security Application: Surveillance, Combat, Logistics, Training |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, General Dynamics Corporation, The Boeing Company, L3Harris Technologies, Huntington Ingalls Industries, Kratos Defense & Security Solutions, Leonardo DRS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Defense Market Strategic Shifts
Algorithmic warfare integration is reshaping how the Pentagon evaluates contractor proposals, with software deliverables now weighted equally with hardware performance in source selection criteria.
Modular open systems architectures are fragmenting traditional prime contractor control over subsystem integration. The Navy's Columbia-class submarine program is mandating government-owned interface standards, enabling third-party software patches and hardware upgrades without original vendor involvement. This technical shift is compressing lifecycle sustainment margins while accelerating capability refresh cycles.
Department of Defense Instruction 5000.87 is formalulating software acquisition pathways separate from hardware programs, allowing middle-tier software vendors to bypass traditional milestone reviews. Defense Innovation Unit contracts are channeling commercial cloud-native development practices into classified environments, with Platform One and Black Pearl programs establishing DevSecOps pipelines for fighter jet mission systems.
Consolidated program management offices are displacing distributed procurement authority across the military services. The Space Force's Space Systems Command is centralizing satellite constellation acquisition under single program executive officers, reducing contractor interface complexity but increasing buyer concentration risk for suppliers dependent on specific platform portfolios.
United States Defense Market Segmentation
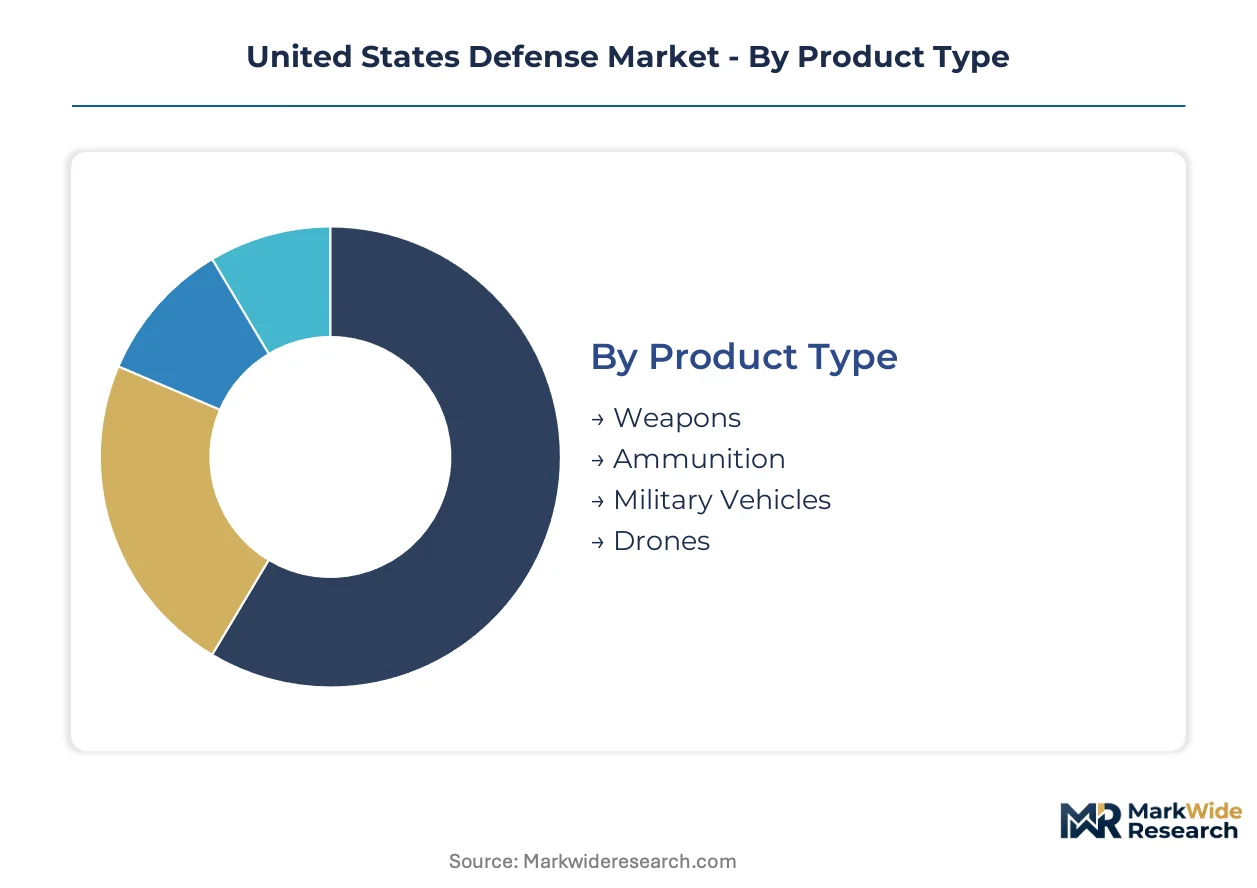
Defense procurement operates through rigid budget line-item structures that segment demand by platform type, technology readiness, and operational end-use. Understanding these partitions reveals where Pentagon funding flows concentrate and where contractor margins diverge.
Product Type:
Domestic demand dominates weapons and military vehicles through sole-source Army and Navy contracts, while drones draw significant export interest under Foreign Military Sales frameworks.
- Weapons:Nuclear-capable delivery systems and precision-guided munitions anchor Air Force and Navy modernization accounts. Demand clusters in hypersonic glide bodies and next-generation cruise missiles as the Pentagon replaces aging standoff arsenals.
- Military Vehicles:Ground combat platforms including the Optionally Manned Fighting Vehicle and Amphibious Combat Vehicle absorb Army procurement priority. Alabama and Michigan production facilities concentrate final assembly, driving localized supplier ecosystems.
- Ammunition:Artillery shell production lines at Scranton and Lake City Army Ammunition Plants strain to meet Ukraine replenishment and domestic stockpile targets simultaneously.
- Drones:Export-led growth characterizes MQ-9 Reaper and future Collaborative Combat Aircraft sales to NATO allies and Indo-Pacific partners.
Weapons holds the largest share; momentum sits with drones.
Technology:
Cost tiers separate mature communication systems from emerging AI and robotics investments requiring extensive integration engineering.
- Cybersecurity:CMMC 2.0 mandates now apply to the entire defense industrial base, forcing small suppliers toward managed security service providers. Compliance spending concentrates in secure cloud migrations and zero-trust architecture implementations.
- Artificial Intelligence:Algorithmic targeting and predictive maintenance applications expand fastest across the analysis window. Project Maven successors and autonomous swarming programs drive classified R&D budgets at DIU and service labs.
- Robotics:Ground-based autonomous logistics vehicles and explosive ordnance disposal platforms mature in Army and Marine Corps testing.
- Communication Systems:Legacy Link-16 upgrades and emerging resilient satellite constellations absorb steady procurement dollars with lower technical risk profiles.
Communication Systems captures the most procurement volume; AI climbs the fastest.
End User:
Customer type determines security clearance depth and contract vehicle complexity, with military services operating distinct acquisition cultures.
- Military:Unified combatant commands drive joint requirements for integrated air and missile defense. Service-specific platform demands from Army Futures Command and Navy PEOs fragment supplier targeting.
- Defense Contractors:Prime integrators and Tier 1 subsystem suppliers constitute the cleared industrial base subject to NIST 800-171 and CMMC audits.
- Government Agencies:Intelligence community demand for specialized technical collection platforms operates through separate budget channels with distinct security protocols.
- Private Security:Limited domestic scope; State Department diplomatic security contracts and select infrastructure protection roles represent accessible entry points.
Military commands the largest budget authority; government agencies show steepest expansion trajectory in technical intelligence systems.
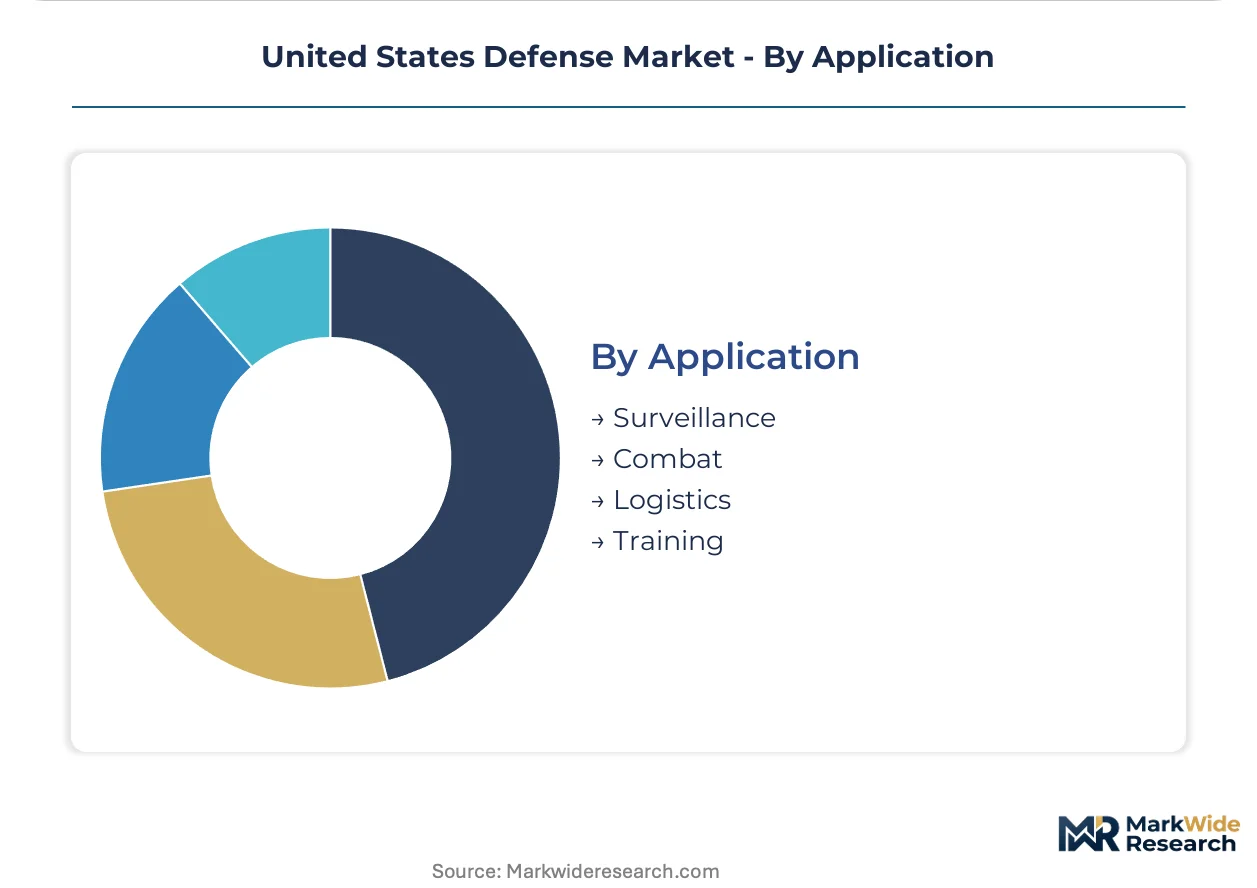
Application:
Margin profiles vary sharply across operational functions, with combat platforms commanding premium pricing for classified integration.
- Surveillance:Space-based radar and signals intelligence constellations absorb Space Force investment priority. Ground moving target indication and synthetic aperture radar payloads drive satellite bus and sensor procurement.
- Combat:Manned-unmanned teaming architectures reshape fighter and bomber mission systems. B-21 and Next Generation Air Dominance programs concentrate development funding.
- Logistics:Autonomous convoy systems and predictive supply chain analytics reduce theater distribution costs but face slower adoption timelines.
- Training:Synthetic training environments and live-virtual-constructive simulation suites modernize pilot and squad-level preparation.
Combat applications hold the largest share; surveillance gains share fastest as orbital infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pentagon procurement dollars concentrate in Virginia and California corridors, while Alabama and Texas test ranges command premium pricing for specialized engineering talent. This geographic asymmetry shapes contractor facility placement and state-level incentive competition.
Virginia
Northern Virginia hosts the intelligence community and Pentagon headquarters, driving demand for cleared cybersecurity and satellite systems. CMMC 2.0 implementation through the Defense Counterintelligence and Security Agency accelerates compliance spending across Fairfax and Arlington counties. The Dulles-Tysons corridor anchors classified cloud infrastructure investments by major integrators.
California
Southern California sustains aerospace manufacturing and space launch operations through legacy defense-industrial infrastructure. Air Force Space Command requirements flow through Los Angeles Air Force Base, concentrating satellite procurement authority. The Space Coast corridor from El Segundo to Seal Beach anchors orbital vehicle development and payload integration.
Alabama
Army Futures Command prioritizes hypersonic ground testing at Redstone Arsenal, attracting thermal protection materials suppliers. The Department of Defense's software modernization mandates compress acquisition cycles for missile defense programs. Huntsville's Cummings Research Park concentrates engineering talent for Army Space and Missile Defense Command.
Texas
Central Texas hosts Army Futures Command headquarters and Austin's emerging defense tech ecosystem. The Defense Innovation Unit channels commercial software practices into classified environments through local partnerships. San Antonio's cybersecurity training infrastructure feeds cleared workforce pipelines for NSA and service cryptologic elements.
Washington
The Pacific Northwest sustains naval aviation and submarine industrial base operations through Puget Sound shipyards. Navy PEOs concentrate unmanned maritime systems development in Kitsap County. Boeing's Renton and Everett facilities anchor military derivative aircraft production alongside commercial lines.
United States Defense Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the defense industrial base. The market structure concentrates around five prime integrators commanding classified program access, with a fragmented tier of subsystem specialists competing on technical differentiation. Two strategic archetypes dominate: full-spectrum primes managing system-of-systems integration, and niche technology providers capturing premium margins in specialized domains. Competitive moves center on facility consolidation near test ranges and strategic hiring of cleared software engineers.
Within the prime integrator tier, Lockheed Martin Corporation and RTX Corporation exemplify divergent specialization strategies. Lockheed Martin occupies a position anchored in classified satellite and hypersonic programs through its Skunk Works division. RTX sits within the missile defense and radar systems domain, sustaining market presence through extensive supplier network management. Northrop Grumman Corporation represents the nuclear modernization archetype, anchoring strategic deterrent programs including the B-21 Raider.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| The Boeing Company |
| L3Harris Technologies |
| Huntington Ingalls Industries |
| Kratos Defense & Security Solutions |
| Leonardo DRS |
| Others |
Value Chain & Pricing Dynamics
CMMC 2.0 certification tiers gate both supplier qualification and price differentiation simultaneously, forcing cleared contractors to absorb compliance premiums while uncertified competitors exit bidding pools entirely. Defense procurement officers now weight cybersecurity maturity equally with technical performance, collapsing traditional price-only evaluation frameworks.
Pricing Analysis
Alabama test range corridors command 15-25% labor cost premiums over coastal engineering clusters, while California satellite integration facilities price at the highest tier due to security-cleared workforce scarcity. Cost-plus contracting dominates major weapons programs, with fixed-price vehicles reserved for mature subsystems. Price differentiation rests on security clearance depth and ITAR compliance infrastructure. Margins are tightening in commoditized ammunition production as Army replenishment demands strain legacy plant capacity. Tier 2 component suppliers exhibit highest price sensitivity, while prime integrators with sole-source positions maintain pricing power.
Supply Chain Analysis
Inbound logistics costs for thermal protection materials and radiation-hardened semiconductors have intensified due to West Coast port congestion and constrained air freight capacity on transpacific lanes. Domestic supply concentrates in Alabama, California, and Virginia for final assembly, while rare earth processing draws from Australia and allied nation stockpiles. Solid rocket motor propellants and precision gyroscopes represent critical single-source dependencies. Tariff exposure runs through Canadian aluminum and Mexican electronic subassembly inputs. Distribution feeds from prime contractor facilities directly to military depots and test ranges, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States defense market rewards possession of cleared engineering talent and classified facility infrastructure above all other assets. Prime contractor consolidation has collapsed the middle tier, leaving capability gaps in software-defined systems and AI-enabled platforms.
For Market Incumbents: Fortify cleared workforce pipelines through partnerships with NSA-designated Centers of Academic Excellence and captive training programs at Redstone Arsenal and Space Coast facilities. Acquire specialized AI/ML boutiques before Defense Innovation Unit contracts validate their valuations. CMMC 2.0 implementation costs will squeeze mid-tier competitors unable to amortize compliance across program portfolios. For New Entrants and Emerging Players: CMMC Level 2 fast-track certification through accredited third-party assessors unlocks subcontracting opportunities on Columbia-class submarine and Next Generation Air Dominance programs. White-space exists in predictive maintenance algorithms for legacy aircraft turbine health monitoring, where primes lack commercial software velocity. Target Army Futures Command software acquisition pathways under DoDI 5000.87, bypassing traditional milestone reviews. Go-to-market through Platform One DevSecOps pipelines accelerates security accreditation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hypersonic ground test infrastructure and classified cloud environments. Long-term viability demands positions in nuclear modernization or space domain awareness, segments with decade-long procurement horizons. Acquisition target archetype: cleared software vendors with DIU contract traction and existing Platform One integration. Signal to watch: Defense Counterintelligence and Security Agency processing velocity for secret-level clearances, which gates staffing for all major programs.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC 2.0 Compliance Infrastructure | Unlocks bidding eligibility across Army and Space Force procurement pools. |
| Cleared Workforce Pipeline Development | Reduces program staffing delays at NSA-designated academic partnerships. |
| Software-Defined Radio Convergence | Collapses separate communications hardware into unified programmable payloads. |
| Hypersonic Test Range Co-location | Captures thermal protection materials engineering talent in Tennessee Valley corridor. |
| AI-Enabled Predictive Maintenance | Extends F-35 and B-21 platform service intervals through turbine health algorithms. |
Study Parameters
Cross-validation between Pentagon budget justification documents and contractor earnings disclosures anchors the qualitative findings. Primary interviews with program executive officers, cleared facility security officers, Defense Innovation Unit contract managers, and Army Futures Command requirements leads combined with secondary validation against DoD 7000.2 financial management regulations, NIST 800-171 audit reports, and Federal Procurement Data System contract awards. Bottom-up segment sizing and top-down budget authority triangulation produced convergent estimates.
Sensitivity analysis on CMMC implementation timelines and hypersonic test frequency assumptions shaped the projection framework. Segmentation dimensions modeled include platform type, technology readiness level, security classification tier, service branch end-user, and application mission area across the analysis window. CAGRs derive from historical obligation patterns and programmed procurement growth profiles. Industry-specific inputs include Defense Counterintelligence and Security Agency clearance processing rates and solid rocket motor production capacity constraints.
Decision-makers should treat outputs as directional under sustained congressional defense appropriations and allied nation co-development continuity; material deviation would warrant model refresh. Forecasts embed assumptions regarding ITAR reform progress and domestic rare earth processing scale-up. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
GCC Defense Market
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Europe Defense Market