
 Commercial Aerospace Carbon Brakes Market | 2026-2036
Commercial Aerospace Carbon Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aerospace Carbon Brakes Market Outlook
Performance-based brake maintenance contracts is repositioning how airlines procure carbon brake systems, shifting capital expenditure into operational expenditure frameworks. Safran Landing Systems leverages its integrated landing gear-to-brake architecture to capture long-term service agreements with major carriers. Collins Aerospace anchors North American aftermarket demand through its expansive MRO network and OEM relationships with Boeing. Honeywell International competes on thermal management expertise, extending its brake control systems into predictive analytics offerings.
Commercial aerospace carbon brakes utilize carbon-carbon composite discs manufactured through chemical vapor infiltration of carbon fiber preforms, achieving operating temperatures exceeding 1500°C while delivering weight savings of 40% versus steel brakes. Their primary purpose is to dissipate kinetic energy during aircraft landing and rejected takeoff scenarios under extreme thermal stress. Carbon-carbon brakes dominate the product type landscape for wide-body applications where heat absorption requirements peak, while carbon ceramic variants gain traction in business jets seeking reduced maintenance intervals. Narrow-body aircraft represent the largest aircraft type segment by installed base, though regional jets exhibit the fastest fleet renewal trajectory as operators replace aging turboprops.
FAA certification under Part 25.735 governs brake energy rating and stopping distance requirements, while EASA CS-25 imposes parallel standards that manufacturers must satisfy for dual-market access. EPA oversight of perfluorooctanoic acid emissions from carbon fiber processing is tightening supply chain environmental compliance costs. Stakeholders must monitor evolving FAA and EASA mandates on sustainable aviation materials, as regulatory pressure on carbon brake manufacturing processes intensifies alongside fleet decarbonization timelines.
Market Dynamics
Fleet renewal cycles at narrow-body carriers are compressing brake replacement intervals while FAA Part 25.735 energy absorption standards tighten material specifications, forcing suppliers to recertify architectures under accelerated timelines.
Growth Catalysts
- Part 25.735 Certification Stringency:FAA brake energy rating requirements are elevating carbon-carbon composite specifications, disqualifying marginal suppliers and consolidating procurement toward qualified vendors.
- Narrow-Body Fleet Renewal:Airlines replacing aging A320ceo and 737NG fleets with neo and MAX variants are specifying factory-installed carbon brakes as standard equipment.
- Chemical Vapor Infiltration:Advances in CVI processing cycles are reducing carbon fiber preform manufacturing time, expanding production capacity at existing facilities.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets, compressing brake disc margins during input spikes.
- US Supply Concentration:Boeing's domestic supply chain anchors procurement volumes, creating demand vulnerability to single-airline fleet decisions.
- Steel Brake Substitution in Regional Aviation:Cost-sensitive turboprop operators continue specifying steel brakes for short-haul cycles where thermal load remains modest.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India's narrow-body order backlogs create untapped aftermarket potential as these aircraft enter service.
- Predictive Maintenance Convergence:Integration of brake control systems with IoT sensor networks enables condition-based replacement scheduling.
- EU Green Deal Material Mandates:Sustainable aviation fuel certification pathways are extending to brake manufacturing processes, rewarding low-emission CVI facilities.
Industry Challenges
- Specialized Technician Scarcity:Carbon brake overhaul requires FAA-certified repair station personnel with composite thermal analysis expertise.
- Dual Certification Burden:Simultaneous FAA and EASA CS-25 compliance testing extends new product introduction timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aerospace Carbon Brakes Market |
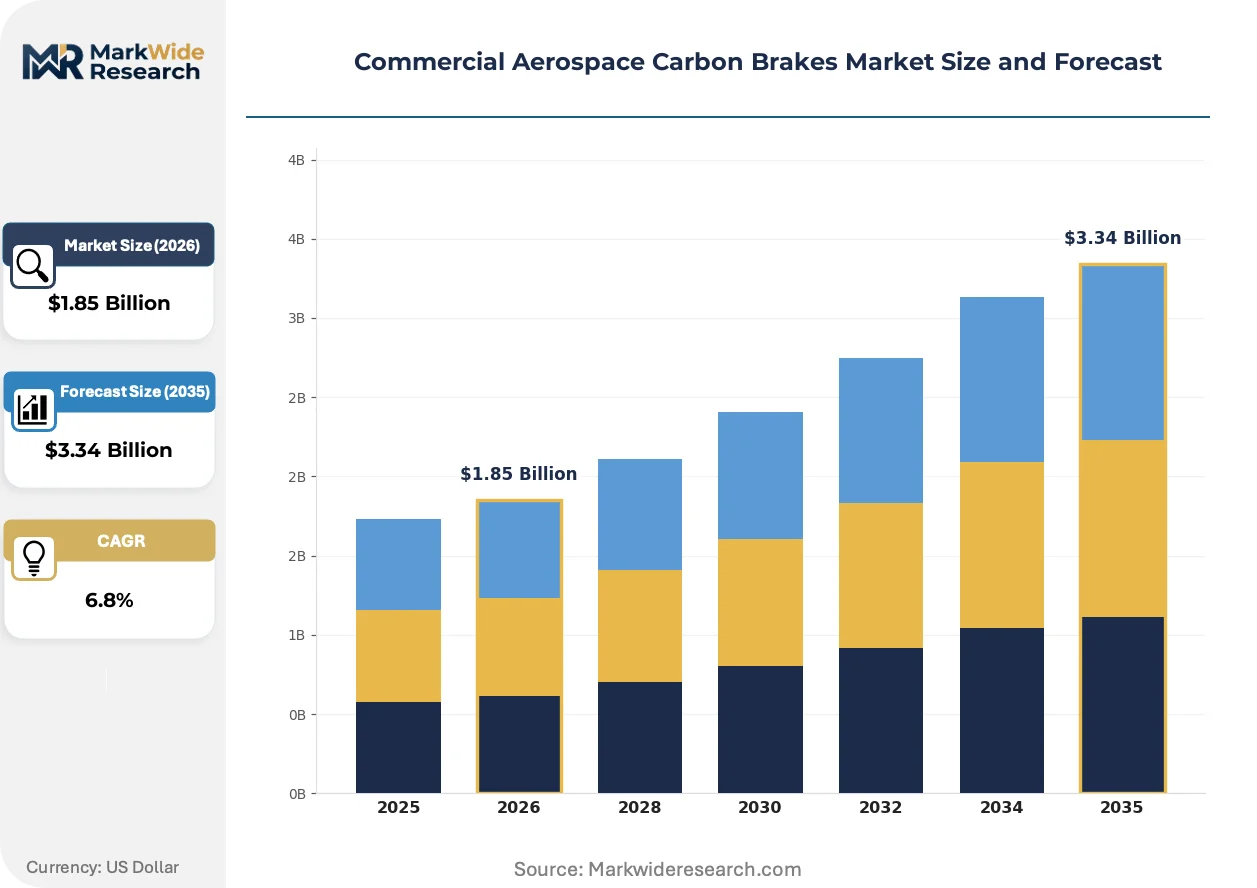
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon-Carbon Brakes, Carbon Ceramic Brakes, Hybrid Brakes, Others End User: Commercial Airlines, Cargo Operators, Private Jets, Military Aviation Aircraft Type: Narrow-Body Aircraft, Wide-Body Aircraft, Regional Jets, Business Jets Distribution Channel: OEMs, Aftermarket, Direct Sales, Online Retailers |
| Companies Covered | Meggitt PLC, Mersen Group, Safran Landing Systems, CFCCARBON Co. Ltd., SGL Carbon, Collins Aerospace, Crane Aerospace & Electronics, UTC Aerospace Systems, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aerospace Carbon Brakes Market Strategic Shifts
Carbon-carbon composite architectures are advancing through manufacturing process intensification and embedded sensor integration, reshaping how brake systems are specified, maintained, and monetized across commercial aviation.
Carbon-carbon brake discs manufactured via rapid chemical vapor infiltration are overtaking conventional CVI cycles in wide-body applications. Boeing 787 and Airbus A350 operators are specifying these enhanced discs for rejected takeoff scenarios exceeding 3000°C peak temperatures. The compressed manufacturing timeline is overtaking legacy 60-day infiltration cycles, enabling suppliers to match OEM delivery schedules.
EPA oversight of perfluorooctanoic acid emissions from carbon fiber processing is tightening environmental compliance costs. Manufacturers must retrofit CVI furnaces with thermal oxidizer systems or transition to aqueous-based precursor alternatives. Wide-body brake suppliers with US-based production facilities face the steepest capital reconfiguration requirements.
Airline procurement departments are bundling brake hardware with long-term thermal management service agreements. Low-cost carriers in Southeast Asia are replacing transactional spare part purchases with flight-hour-based contracts. This model shift is most visible at Indonesia's Lion Air Group, where maintenance reserves now cover complete brake system lifecycle costs.
Commercial Aerospace Carbon Brakes Market Segmentation
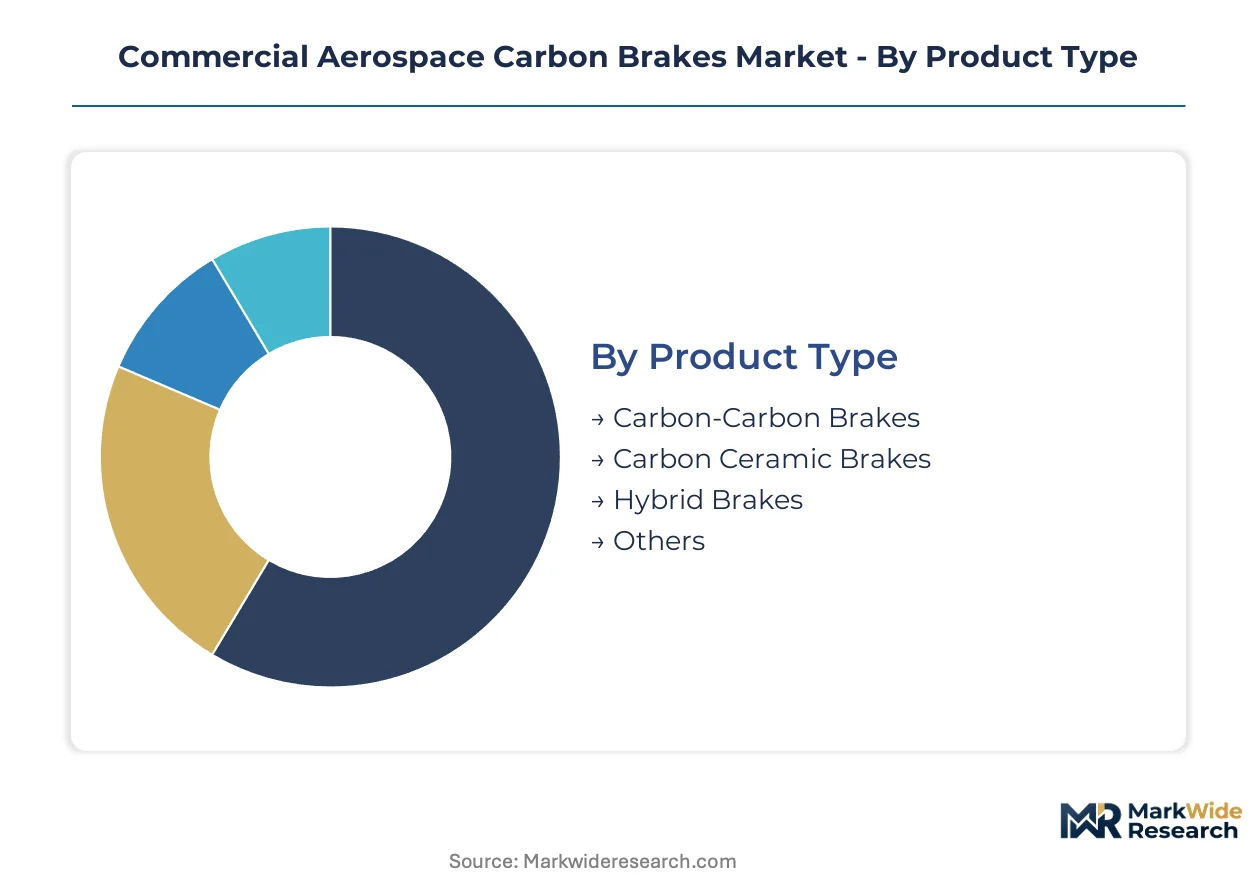
Brake procurement decisions in commercial aerospace hinge on thermal load profiles, fleet operating economics, and regulatory certification pathways. Each segmentation dimension reveals distinct buyer priorities that reshape supplier positioning and margin structures across the value chain.
Product Type:
Material selection determines energy absorption capacity, weight trade-offs, and recertification burdens under FAA Part 25.735.
- Carbon-Carbon Brakes:Manufactured through chemical vapor infiltration of carbon fiber preforms, these systems achieve operating temperatures exceeding 1500°C. Wide-body operators at Delta Air Lines and United Airlines specify carbon-carbon architectures for rejected takeoff scenarios where kinetic energy dissipation peaks.
- Carbon Ceramic Brakes:Silicon carbide matrix composites deliver reduced oxidation rates and extended service intervals. Business jet fleets at NetJets and Flexjet are migrating toward carbon ceramic specifications to compress maintenance downtime between flight cycles.
- Hybrid Brakes:Combines carbon-carbon heat sinks with metallic structural elements for intermediate thermal loads.
- Others:Experimental architectures including chopped fiber preforms and alternative matrix chemistries.
Volume sits with Carbon-Carbon Brakes; growth tilts toward Carbon Ceramic Brakes.
End User:
Procurement scale and contract structure vary sharply across operator categories, from flight-hour agreements at low-cost carriers to capital budgets at cargo integrators.
- Commercial Airlines:Full-service and low-cost carriers dominate installed base volume. Southwest Airlines and Ryan Holdings negotiate fleet-wide brake service contracts that bundle hardware, installation, and predictive replacement scheduling.
- Cargo Operators:FedEx Express and UPS Airlines operate high-cycle freighter fleets with accelerated brake wear profiles. Their procurement emphasizes rapid turnaround availability at Memphis and Louisville hub facilities.
- Private Jets:Fractional ownership programs and high-net-worth individuals prioritize OEM-certified replacement over cost optimization.
- Military Aviation:Defense procurement follows MIL-STD-1290 with specialized thermal shock requirements distinct from commercial certification.
Commercial Airlines capture the dominant revenue share; Cargo Operators are expanding most quickly as e-commerce air freight volumes climb.
Aircraft Type:
Fleet renewal timelines and brake energy ratings create divergent specification pressures across platform categories.
- Narrow-Body Aircraft:Boeing 737 MAX and Airbus A320neo production lines specify carbon brakes as factory standard. American Airlines and IndiGo are absorbing these systems through OEM delivery channels as fleet replacement accelerates.
- Wide-Body Aircraft:Heat absorption requirements peak on Boeing 777 and Airbus A350 platforms. Brake suppliers must demonstrate rejected takeoff capability at maximum landing weights above 250 metric tons.
- Regional Jets:Embraer E-Jet and ATR turboprop operators face cost pressures that sustain steel brake penetration on shorter sectors.
- Business Jets:Gulfstream and Dassault Falcon platforms emphasize weight reduction and corrosion resistance in specification criteria.
Narrow-Body Aircraft anchor procurement volume; Regional Jets are gaining share fastest as turboprop replacement cycles intensify.
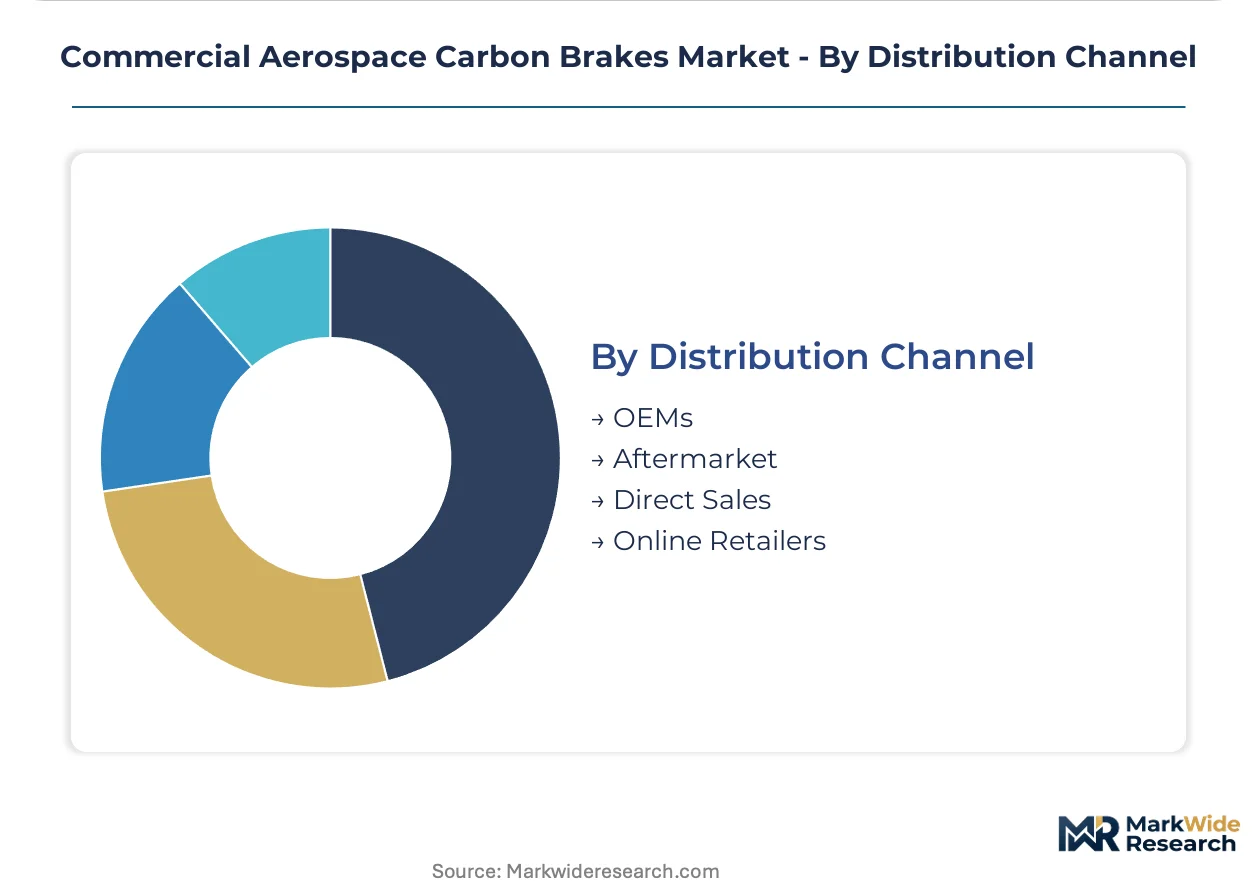
Distribution Channel:
Channel selection reflects fleet age, technical capability, and working capital constraints across operator types.
- OEMs:Boeing and Airbus integrate brake systems at final assembly, capturing specification lock-in for initial equipment. Their purchasing power compresses supplier margins while guaranteeing volume commitments.
- Aftermarket:Independent MRO facilities at Singapore, Dubai, and Frankfurt perform overhaul and replacement services. HAECO and ST Engineering compete on turnaround time and regulatory documentation support.
- Direct Sales:Brake manufacturers maintain direct relationships with select cargo and military operators.
- Online Retailers:Limited to small-scale business jet and general aviation spare part transactions.
OEMs dominate new equipment flow; Aftermarket channels are climbing the fastest as installed base ages and flight-hour contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the United States and France where OEM supply chains anchor manufacturing, while consumption spreads across airline operator bases in Asia-Pacific and Middle Eastern growth markets. The United States concentrates brake system fabrication near Boeing's Seattle and Charleston assembly lines. European suppliers serve Airbus Toulouse and Hamburg facilities.
United States
Boeing's 737 MAX and 787 production lines in Renton and North Charleston drive carbon brake procurement volumes. FAA Part 25.735 certification requirements shape supplier qualification timelines. The Greater Seattle aerospace cluster hosts Safran Landing Systems and Collins Aerospace manufacturing facilities serving domestic OEM demand.
France
Airbus final assembly in Toulouse and Hamburg channels brake specifications toward European suppliers. EASA CS-25 standards parallel FAA requirements for dual-market access. The Bordeaux aerospace corridor concentrates carbon-carbon composite processing expertise for wide-body brake discs.
China
COMAC C919 narrow-body deliveries are expanding domestic brake specification opportunities. MIIT industrial policy supports carbon fiber precursor localization under dual carbon goals. The Shanghai Pudong aviation industrial zone attracts joint ventures between Chinese fabricators and Western brake suppliers.
India
IndiGo and Air India narrow-body order backlogs exceeding 1,000 aircraft create aftermarket expansion potential. DGFT import substitution policies encourage local brake overhaul capabilities. The Bangalore-Hyderabad aerospace corridor hosts MRO facilities building composite thermal analysis expertise.
United Arab Emirates
Emirates and Etihad wide-body fleets generate concentrated heat-intensive brake replacement demand. GCAA regulations align with EASA standards for brake energy rating compliance. Dubai South's aviation district anchors aftermarket service capacity for Middle Eastern and African operators.
Commercial Aerospace Carbon Brakes Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the carbon brake value chain. The market structure consolidates around three qualified OEM suppliers while aftermarket channels fragment across independent MRO networks. Strategic archetypes separate integrated landing gear-to-brake architects, standalone thermal management specialists, and carbon fiber preform fabricators. Dominant competitive moves include long-term flight-hour service agreements and predictive maintenance platform integration.
Among French-integrated system architects, Safran Landing Systems exemplifies the full-stack landing gear approach. United States-based Collins Aerospace and Honeywell International occupy positions on the thermal management and control systems vector. German materials specialists SGL Carbon and Chinese fabricator CFCCARBON Co. Ltd. anchor the carbon fiber preform supply tier.
| Leading Market Players |
|---|
| Meggitt PLC |
| Mersen Group |
| Safran Landing Systems |
| CFCCARBON Co. Ltd. |
| SGL Carbon |
| Collins Aerospace |
| Crane Aerospace & Electronics |
| UTC Aerospace Systems |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap carbon fiber preform specialists in France and the United States anchor tier-two supply positions, translating Boeing and Airbus volume commitments into disciplined pricing floors that resist spot-market volatility while compressing margin elasticity for non-integrated brake assemblers.
Pricing Analysis
Margin tightening in aftermarket channels traces to flight-hour contract proliferation at Lion Air Group and IndiGo, where bundled thermal management services displace transactional spare part purchases. Three-tier pricing structure across OEM-certified, MRO-qualified, and uncertified rebuild tiers separates Boeing-approved discs from HAECO-overhauled units from grey-market alternatives. Cost-down pressure on carbon-carbon heat sinks accelerates because acrylonitrile precursor costs fluctuate with petrochemical feedstock indices. Cargo operators at FedEx Express exhibit highest price sensitivity; fractional business jet owners at NetJets show lowest.
Supply Chain Analysis
FAA Part 25.735 and EASA CS-25 certification gating restricts qualified brake disc fabrication to the United States, France, and emerging Chinese facilities serving COMAC C919 programs. Carbon fiber preforms, pyrolytic graphite coatings, and silicon carbide matrix precursors draw from specialized chemical vapor infiltration reactors concentrated near Bordeaux and Seattle. Single-source vulnerability persists in Boeing's domestic supply chain anchoring procurement volumes. Distribution runs through OEM integration at final assembly, independent MRO channels at Singapore and Dubai, and direct sales to military operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
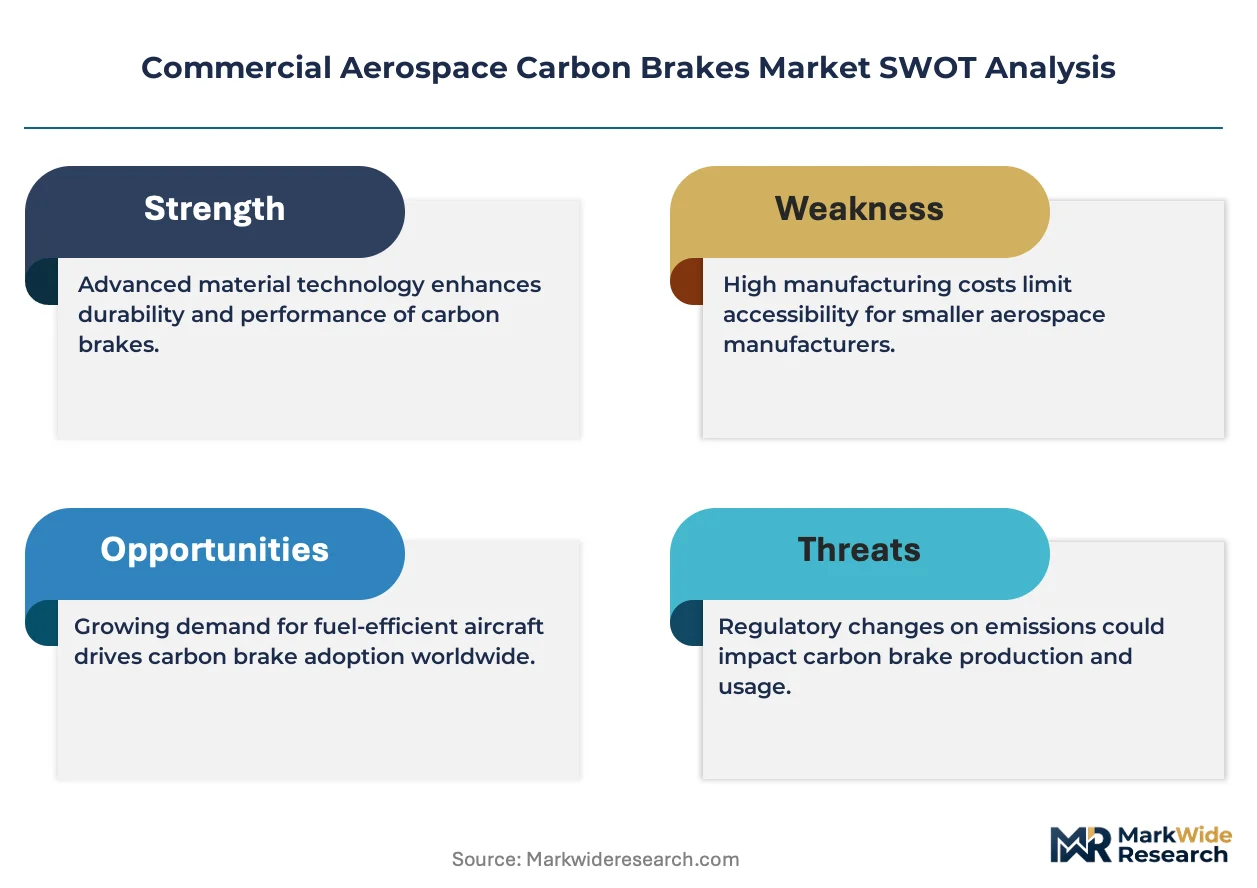
This market reads as a cost-of-compliance story where FAA Part 25.735 energy absorption standards erect barrier-to-entry moats favoring incumbents with recertified architectures and dual-market testing capabilities.
For Market Incumbents: Hedge acrylonitrile cost exposure through backward integration into precursor manufacturing or long-term offtake agreements with SGL Carbon and CFCCARBON Co. Ltd. Defend margin position by accelerating rapid chemical vapor infiltration capacity additions in the Bordeaux corridor to match Boeing 787 and Airbus A350 delivery schedules. Reinforce aftermarket lock-in through predictive maintenance platform integration with brake control system telemetry. For New Entrants and Emerging Players: India's cargo MRO operators represent an underserved buyer archetype as DGFT import substitution policies encourage local brake overhaul capabilities. Target the Bangalore-Hyderabad aerospace corridor for joint venture partnerships with composite thermal analysis specialists building FAA-certified repair station expertise. Penetrate through aqueous-based precursor alternatives that sidestep EPA perfluorooctanoic acid compliance costs burdening incumbent US facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor carbon fiber preform fabricators with EASA-qualified production lines in France as EU Green Deal material mandates reward low-emission CVI facilities. Long-term viability hinges on sustained narrow-body fleet renewal at IndiGo and Air India generating aftermarket annuity streams. Watch for MIIT industrial policy accelerating COMAC C919 brake specification localization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Flight-Hour Contract Proliferation | Lion Air Group's bundled thermal management agreements reposition airline procurement from CapEx to OpEx frameworks. |
| Rapid Chemical Vapor Infiltration Scale-Up | Bordeaux corridor facilities compress 60-day legacy cycles to match Boeing 787 and Airbus A350 OEM delivery schedules. |
| Dual Certification Investment | Simultaneous FAA Part 25.735 and EASA CS-25 compliance testing extends timelines 18-24 months, consolidating vendor pools. |
| Predictive Maintenance Platform Integration | Honeywell International extends brake control systems into IoT sensor networks enabling condition-based replacement scheduling. |
| Aqueous Precursor Transition | EPA perfluorooctanoic acid oversight forces thermal oxidizer retrofits or aqueous alternative adoption at US-based CVI furnaces. |
Study Parameters
Independent corroboration across FAA certification documentation, EASA CS-25 compliance filings, and EPA emissions disclosure records underwrites the qualitative findings. Primary interviews with brake system procurement directors at Delta Air Lines and United Airlines, MRO operations heads at HAECO and ST Engineering, and carbon fiber preform technical directors at SGL Carbon combined with secondary validation from SEC 10-K filings, customs trade data, and OEM delivery schedules. Bottom-up fleet renewal modeling and top-down aerospace component demand triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic fleet utilization baselines through narrow-body MAX and neo re-entry trajectories anchored the forecast window. Segmentation dimensions modeled include product type (carbon-carbon, carbon ceramic, hybrid), aircraft platform (narrow-body, wide-body, regional jet, business jet), end-user category (commercial airline, cargo operator, private jet, military), and distribution channel (OEM, aftermarket, direct). CAGRs derived from installed base aging curves and replacement interval compression under tightened FAA energy absorption standards. Forecast inputs incorporated MIIT industrial policy timelines for COMAC C919 brake localization and EU Green Deal CVI facility emission mandates.
Revisions become necessary when FAA or EASA mandates on sustainable aviation materials accelerate recertification burdens, COMAC C919 delivery schedules deviate from MIIT targets, or acrylonitrile precursor markets experience sustained petrochemical feedstock dislocation. Forecasts reflect assumptions around fleet renewal pacing at IndiGo and Air India, flight-hour contract adoption rates at Southeast Asian low-cost carriers, and EPA enforcement intensity on perfluorooctanoic acid emissions. A model refresh is warranted upon material change in Boeing 737 MAX and 787 production rates at Renton and North Charleston facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market