
 Europe Aluminium Composite Panel Market | 2026-2036
Europe Aluminium Composite Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminium Composite Panel Market Foresight
Transportation infrastructure cladding is expanding across European rail and airport terminals. ALUCOIL leverages its coil-coating expertise to serve high-speed rail stations in Spain and France. 3A Composites anchors premium architectural projects through its Alucobond brand recognition among specifiers. Arconic Inc. competes on large-format panel capacity for logistics hub facades.
Aluminium composite panels consist of two thin aluminium skins bonded to a non-aluminium core, typically polyethylene or mineral-filled material, yielding a lightweight rigid sheet with high flatness and weather resistance. The primary commercial purpose spans exterior building envelopes, interior decorative surfaces, and corporate signage systems. Fire-resistant panels dominate specification-driven tenders following tightened EN 13501-1 classifications across EU member states. Facade cladding captures the largest application value pool, while insulated panels represent the fastest-growing segment amid deep energy retrofit mandates.
CE marking under the Construction Products Regulation governs market access, while ECHA REACH restrictions on core material chemicals shape formulation choices. National regulators including Germany's KBA and France's ANSM enforce fire performance testing protocols that vary by member state. Stakeholders must monitor divergence between harmonized EN standards and emerging national fire safety amendments.
Market Dynamics
The Europe Aluminium Composite Panel Market pivots on regulatory divergence between harmonized EN standards and emerging national fire safety amendments. CE marking under the Construction Products Regulation governs baseline access, while member-state-specific testing protocols reshape competitive positioning across Germany, France, and Spain.
Growth Catalysts
- EU Green Deal energy retrofit mandates:Deep renovation targets in Nordic countries and Mediterranean hospitality construction are accelerating insulated panel specifications for facade systems.
- EN 13501-1 reaction-to-fire reclassification:Tightened fire performance standards across EU member states are prioritizing mineral-filled core panels in commercial tenders.
- Rail infrastructure expansion:High-speed terminal construction in Spain and France is creating dedicated demand for weather-resistant cladding systems with extended durability guarantees.
Market Restraints
- Aluminium ingot price volatility:Input cost swings tied to LME pricing compress margin predictability for coil coaters and fabricators serving project-based contracts.
- ECHA REACH chemical restrictions:Core material formulation constraints on polyethylene compounds limit low-cost panel options and extend R&D timelines.
- Fragmented national testing regimes:Divergence between Germany's KBA protocols and France's ANSM fire performance requirements raises compliance costs for cross-border suppliers.
Strategic Opportunities
- Eastern European construction acceleration:Poland and Romania's commercial real estate development is absorbing standard-grade panels with shorter specification cycles than Western markets.
- Photovoltaic-integrated cladding:Building-integrated solar facades combining ACP substrates with thin-film modules are penetrating Nordic net-zero building programs.
- Digital specification platforms:BIM-integrated product libraries are compressing architect decision timelines and enabling direct manufacturer-to-specifier engagement outside traditional distribution.
Industry Challenges
- Fire engineering talent scarcity:Qualified professionals capable of navigating multi-jurisdictional EN 13501-1 testing protocols command premium compensation and extend project staffing timelines.
- Legacy facade audit complexity:Post-Grenfell safety assessments across UK and French building portfolios require reverse-engineering of installed panel compositions without original documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminium Composite Panel Market |
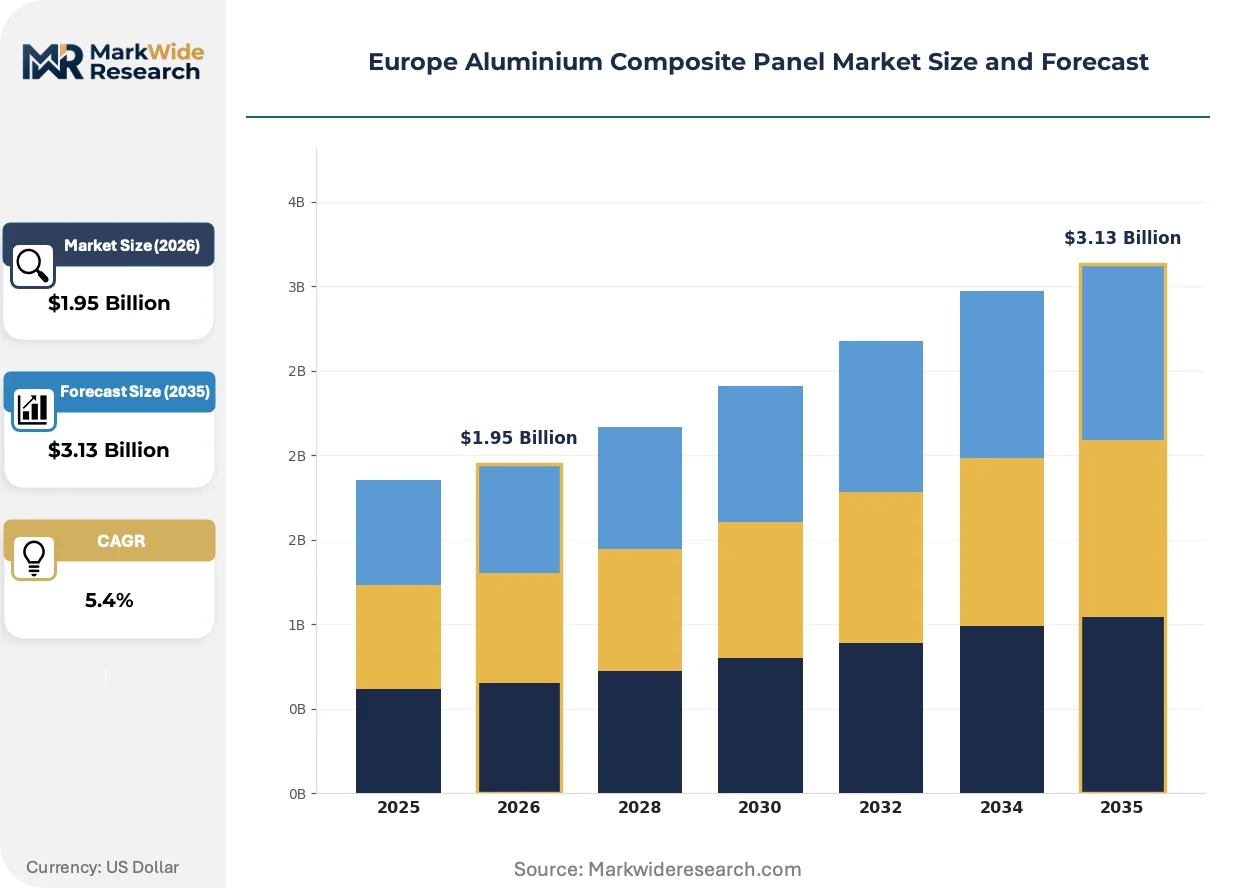
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Resistant Panels, UV-Resistant Panels, Insulated Panels, Waterproof Panels Application: Facade Cladding, Interior Work, Signage, Wall Partitioning End User: Construction, Transportation, Advertising, Architecture Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | ALUCOIL, Alumax Europe GmbH, 3A Composites, Euro Panel Products Pvt Ltd, Alstone, Arconic Inc., Alubond USA, Yingjia Aluminium Co Ltd, Mitsubishi Chemical Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminium Composite Panel Market Shifts & Advancements
Digital manufacturing and regulatory technology are compressing specification-to-installation cycles across European construction value chains. Three developments are restructuring how aluminium composite panels are produced, validated, and procured.
Robotic panel fabrication is automating cutting, routing, and edge-finishing operations previously requiring manual setup. Spanish and Italian fabricators serving high-speed rail terminals are deploying CNC nesting systems that reduce material waste and accelerate just-in-time delivery for complex geometric facades. This automation is compressing lead times for custom panel dimensions while raising capital barriers for smaller regional converters.
France's ANSM and Germany's KBA are enforcing divergent fire performance testing protocols that exceed baseline CE marking requirements. National regulators mandate additional large-scale facade testing for buildings above specified height thresholds, forcing manufacturers to maintain multiple certification portfolios. Mineral-filled core suppliers are responding with pre-certified system packages that bundle panel, adhesive, and fixing components under single approval documentation.
Architects and main contractors are consolidating procurement around performance-guaranteed facade systems rather than component sourcing. Specification decisions increasingly bundle panel supply with installation liability and long-term maintenance commitments, displacing traditional merchant distributor relationships. This bundling is most advanced in UK commercial development and German logistics hub construction, where single-point accountability reduces interface risk.
Europe Aluminium Composite Panel Market Segmentation
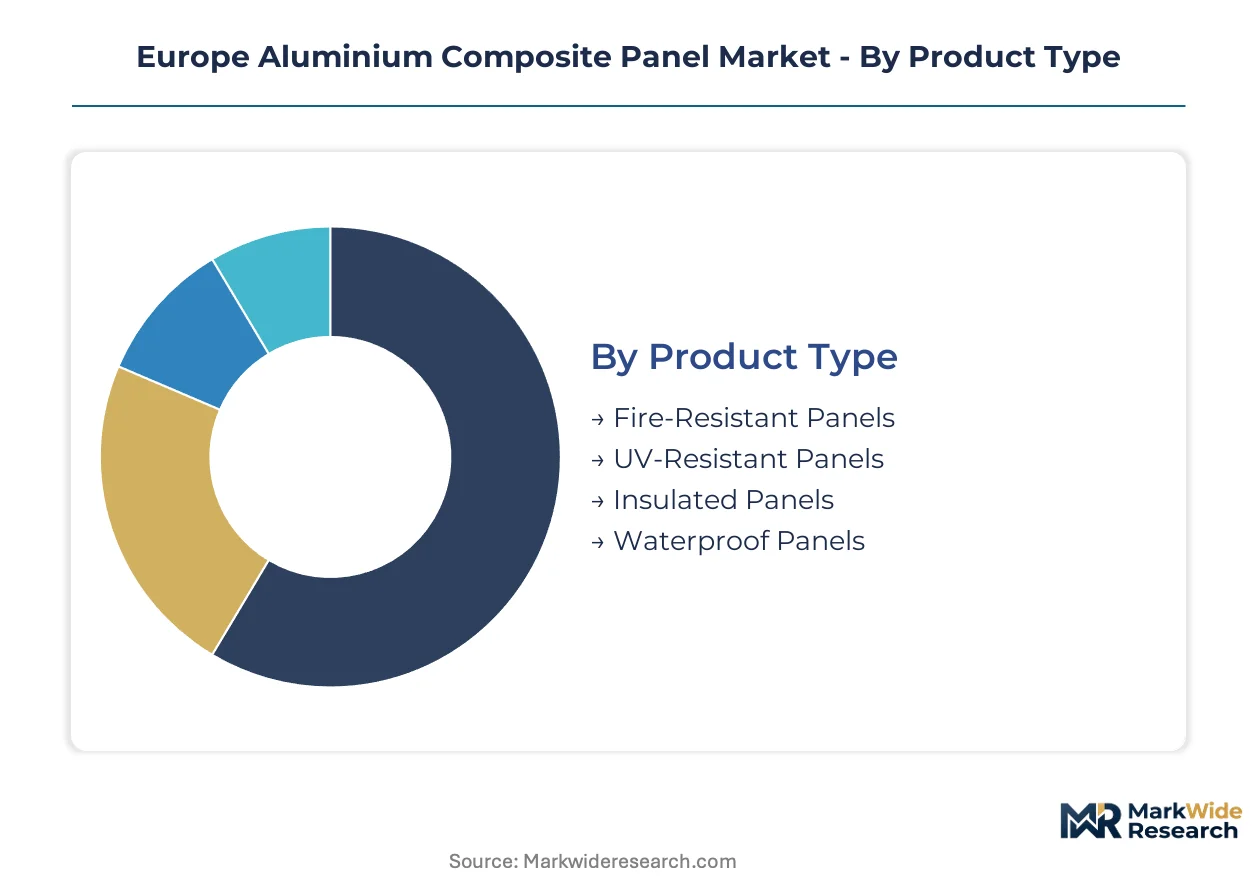
Aluminium composite panel procurement in Europe splits across performance grades, installation contexts, and channel structures that reflect divergent national fire codes and project delivery models. Specification decisions increasingly bundle product selection with installation liability, reshaping how segments interact across the value chain.
Product Type:
Upgrade cycles from standard polyethylene cores to mineral-filled alternatives are compressing replacement timelines as EN 13501-1 classifications tighten across Germany, France, and the United Kingdom.
- Fire-Resistant Panels:Mineral-filled cores bonded between aluminium skins achieve A2-s1,d0 or B-s1,d0 reaction-to-fire ratings under harmonized EU standards. German logistics hub developers and French high-rise commercial projects specify these exclusively, with tenders now mandating large-scale facade testing beyond baseline CE marking.
- UV-Resistant Panels:Fluoropolymer topcoats with PVDF or FEVE resin systems retain color stability under Mediterranean solar exposure. Spanish hospitality construction and Italian coastal retail developments drive specification volume, where extended warranty terms now exceed 20 years.
- Insulated Panels:PUR or PIR foam cores bonded to aluminium faces deliver thermal performance for Nordic deep retrofit programs.
- Waterproof Panels:Specialized edge-sealing and hydrophobic core treatments address maritime climate exposure in Netherlands and Belgian port facilities.
Volume placements concentrate in Fire-Resistant Panels; the faster expansion belongs to Insulated Panels amid EU Green Deal renovation mandates.
Application:
Cost tiering separates premium architectural specifications from standard commercial deployments, with facade systems commanding 3-4x the unit value of interior applications.
- Facade Cladding:Exterior envelope systems span rainscreen configurations to unitized curtain walls, with panel dimensions reaching 6m lengths for logistics hub projects. UK commercial development and German industrial construction absorb the largest project volumes, though specification cycles extend 18-24 months.
- Interior Work:Decorative wall linings, column covers, and ceiling systems prioritize surface finish consistency over weathering performance. Scandinavian airport terminals and Spanish rail stations deploy these for wayfinding integration and brand expression.
- Signage:Corporate identity systems and retail wayfinding utilize thinner panel gauges with printed or anodized finishes.
- Wall Partitioning:Demountable office systems and cleanroom enclosures leverage ACP flatness and modularity for rapid reconfiguration.
Facade Cladding generates the dominant revenue pool; Interior Work is climbing the fastest as transportation infrastructure investment accelerates.
End User:
Customer type fragmentation produces divergent procurement behaviors, with institutional buyers demanding performance guarantees that merchant distributors cannot underwrite.
- Construction:General contractors and facade specialists procure through framework agreements that bundle panel supply with installation liability. German and UK main contractors now require 10-year system warranties covering substrate, coating, and fixing performance.
- Transportation:Rail operators and airport authorities specify extended durability guarantees for high-traffic terminal environments. French SNCF and Spanish ADIF procurement frameworks prioritize whole-life cost over first-cost minimization.
- Advertising:Outdoor media companies and retail chains source standard-grade panels through merchant distributors with shorter specification cycles.
- Architecture:Design-led practices specify custom finishes and geometries for signature buildings, often engaging manufacturers directly.
Construction channels command the deepest volume; Transportation is expanding most quickly as terminal modernization programs advance.
Distribution Channel:
Supply concentration among large-format coil coaters is forcing channel consolidation, with direct manufacturer engagement displacing traditional distributor relationships for complex projects.
- Direct Sales:Manufacturers engage specifiers and main contractors through BIM-integrated product libraries and performance-guaranteed system packages. This channel captures premium facade projects in UK commercial development and German logistics construction where single-point accountability reduces interface risk.
- Distributors:Regional merchants stock standard dimensions and finishes for rapid fulfillment of maintenance and small-project demand. Polish and Romanian construction markets rely heavily on this channel given fragmented project scales.
- Online Retail:Digital platforms serve signage and small-format interior applications with cut-to-size services.
- Contractors:Installation specialists purchase direct for captive fabrication facilities serving local markets.
Direct Sales channels handle the largest project values; Distributors retain the broadest geographic coverage across secondary European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones attract coil-coating investments serving Eastern European construction acceleration. German logistics hubs and Nordic retrofit programs concentrate demand in distinct regulatory environments.
Germany
Logistics hub construction in Leipzig-Halle and Frankfurt Rhine-Main corridors absorbs large-format fire-resistant panels. Germany's KBA enforces supplementary facade testing for buildings exceeding 22 meters. Bavarian fabricators near Munich supply pre-certified system packages bundling panel, adhesive, and fixing components.
France
High-speed rail terminal modernization at Lyon-Saint-Exupéry and Paris-Charles de Gaulle drives weather-resistant cladding specifications. France's ANSM mandates large-scale facade testing beyond baseline CE marking for commercial high-rises. Auvergne-Rhône-Alpes hosts specialists serving SNCF procurement frameworks prioritizing whole-life cost.
United Kingdom
Post-Grenfell safety audits across London and Manchester commercial portfolios accelerate replacement cycles. UK Building Regulations Part B amendments enforce stricter reaction-to-fire classifications for external wall systems. Birmingham fabrication clusters serve framework agreements bundling supply with installation liability.
Spain
Mediterranean hospitality construction in Barcelona and Malaga prioritizes UV-resistant panels with 20-year warranty terms. Spanish building codes align with EU Green Deal energy performance targets for new commercial developments. Basque Country coil coaters leverage rail terminal projects for ADIF procurement channels.
Poland
Commercial real estate development in Warsaw and Krakow absorbs standard-grade panels through shorter specification cycles than Western markets. EU Cohesion Fund infrastructure investments support transportation terminal construction. Lodz Special Economic Zone attracts fabricators serving fragmented regional project scales via distributor channels.
Europe Aluminium Composite Panel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Premium architectural specifications concentrate around recognized facade system brands, while project contractors source commodity grades through regional converters. Three archetypes dominate: coil-coating multinationals with pre-certified fire systems, national fabricators serving public infrastructure frameworks, and merchant distributors stocking standard dimensions for rapid fulfillment. Consolidation pressures intensify as specification decisions bundle product with installation liability, forcing smaller regional players toward captive fabrication or exit.
Among established European fabricators, ALUCOIL and 3A Composites exemplify the branded specialist archetype, anchoring premium specification channels through recognized system warranties. Arconic Inc. occupies a position among large-format capacity providers serving logistics hub developers requiring extended panel dimensions. Alumax Europe GmbH represents the regional fabricator model, concentrating on framework-compliant procurement for German public infrastructure. These three patterns illustrate how competitive positioning diverges between specification-driven architectural markets and price-sensitive commercial deployments.
| Leading Market Players |
|---|
| ALUCOIL |
| Alumax Europe GmbH |
| 3A Composites |
| Euro Panel Products Pvt Ltd |
| Alstone |
| Arconic Inc. |
| Alubond USA |
| Yingjia Aluminium Co Ltd |
| Mitsubishi Chemical Corporation |
| Others |
Supply & Pricing Matrix
Fire-resistance certification tiers split Europe's aluminium composite panel market into sharply divergent value bands, with A2-s1,d0 rated mineral-core panels commanding substantial premiums over standard polyethylene-core alternatives while coil-coating capacity concentration in Germany and Spain determines who captures that margin. This bifurcation manifests in procurement patterns where German logistics developers and French high-rise contractors pay for pre-certified system packages bundling panel, adhesive, and fixing components, whereas Polish and Romanian commercial projects absorb spot-priced standard grades through distributor channels.
Pricing Analysis
Expedited lead-time premiums dominate pricing structures for European rail terminal and airport projects, where French SNCF and Spanish ADIF procurement frameworks penalize schedule overruns more severely than material cost overruns. Project-based contract pricing stratifies across fire-performance certification levels, with EN 13501-1 A2-rated panels carrying meaningful premiums over B-rated alternatives. Cost compression in standard-grade segments is intensifying as Chinese and Turkish coil coaters expand spot-market presence, while German and UK main contractors show least price sensitivity given bundled installation liability requirements.
Supply Chain Analysis
Facade panel refurbishment and core material recovery flows remain underdeveloped across Europe, creating stranded asset risks for installed polyethylene-core inventories facing replacement mandates. Primary coil-coating capacity concentrates in Germany, Spain, and Italy, with raw material dependencies on LME-traded aluminium ingots and mineral-core compounds subject to ECHA REACH formulation constraints. Single-source vulnerability runs through German KBA and French ANSM certification bottlenecks for large-scale facade testing. Distribution runs through direct manufacturer engagement for premium projects and regional merchant networks for standard-grade maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's aluminium composite panel market operates as a supply-constrained environment where pre-certified fire-system capacity cannot expand fast enough to meet EU Green Deal retrofit mandates, propping pricing power for qualified coil-coaters.
For Market Incumbents: Deepen backward integration into mineral-core compound production to secure formulation flexibility under tightening ECHA REACH restrictions. Expand large-format panel capacity near German logistics corridors where 6-meter dimension requirements filter out smaller competitors. Certification investment in dual KBA-ANSM testing protocols defends against emerging Spanish and Italian fabricators capturing rail terminal frameworks. For New Entrants and Emerging Players: The premium-economy price-point gap in insulated panel specifications opens viable entry paths for Eastern European fabricators. Poland's commercial real estate acceleration absorbs standard-grade capacity with shorter specification cycles than Western markets. Photovoltaic-integrated cladding trials in Nordic net-zero programs offer a go-to-market angle bypassing entrenched architectural specifier relationships. For Investors and Strategic Acquirers: Re-rating potential sits with national fabricators holding framework-compliant procurement positions for German public infrastructure given EU Cohesion Fund deployment acceleration. Long-term viability over a multi-year horizon hinges on mineral-core technology transitions outpacing polyethylene legacy exposure. Watch for ANSM-KBA testing protocol convergence as the inflection signal for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Fire System Expansion | Captures German KBA and French ANSM tender requirements for commercial high-rises. |
| Mineral-Core Backward Integration | Secures formulation control under ECHA REACH polyethylene restrictions. |
| BIM-Integrated Specification Platforms | Compresses architect decision timelines for UK and German facade projects. |
| Photovoltaic Cladding Partnerships | Penetrates Nordic net-zero building programs with building-integrated solar substrates. |
| Eastern European Fabrication Footprint | Serves Poland and Romania's accelerated commercial construction through distributor channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with facade system specifiers, coil-coating plant managers, German logistics hub developers, French rail procurement officers, and Polish distributor principals. Construction Products Regulation CE marking databases, EN 13501-1 test reports, and ECHA REACH substance restriction filings provided regulatory validation. Bottom-up project pipeline tracking across transportation terminals and commercial developments triangulated against top-down coil-coater capacity assessments.
Granularity-level modeling distinguished fire-resistance certification tiers, application contexts spanning facade cladding to interior work, and end-user procurement behaviors across construction and transportation channels. CAGRs were derived from segment-level volume trajectories projected across the analysis window, incorporating EU Green Deal renovation targets, national fire safety amendment timelines, and rail infrastructure investment programs as demand-side anchors.
Inputs from ECHA regulatory filings and national fire safety authority test registries were available through the study window; gaps in legacy facade composition documentation for post-Grenfell audit portfolios introduce uncertainty bands around replacement volume estimates. Forecasts reflect assumptions on mineral-core capacity expansion rates and testing protocol harmonization progress. Practitioners should monitor ANSM-KBA regulatory convergence announcements and Nordic BIPV subsidy program renewals for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
High Performance Composites Market
Composite Materials
Phenolic Panel Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Composite Adhesives Market
Composite Materials
FRP Reactor Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
China Marine Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Global Geocomposites Market
Composite Materials
Pultrusion Market
Composite Materials
Thermoset Composites Market
Composite Materials
Composites Testing Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market