
 Pulp Moulding Tooling Market | 2026-2036
Pulp Moulding Tooling Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Moulding Tooling Market Outlook
EU Single-Use Plastics Directive enforcement is pivoting the cost-of-entry calculus for European packaging converters seeking compliant tray and clamshell formats. BeSure Technology Co. leverages integrated CNC machining and heat-treatment capabilities to shorten die delivery cycles for Asian equipment OEMs. SODALTECH anchors Nordic and Baltic demand through precision-matched tooling pairs optimized for Inmaco forming machines. HGHY Pulp Molding Pack Co., Ltd. dominates domestic Chinese aftermarket refurbishment, sustaining margin pools in die resurfacing and cavity reconditioning.
Pulp moulding tooling comprises precision-engineered dies, molds, and forming surfaces that shape aqueous fiber slurry into dimensionally stable packaging articles under heat and pressure, typically achieving cavity tolerances of 0.05–0.1 mm to ensure consistent wall thickness across high-speed rotary or reciprocating equipment. These tools serve the primary industrial purpose of enabling mass production of molded fiber containers that replace petroleum-based packaging in foodservice, electronics, and automotive dunnage applications. Compression moulds capture the largest installed base owing to their compatibility with legacy reciprocating presses, while thermoforming moulds represent the fastest-expanding category as transfer molding and direct-in-line drying systems displace older wet-press configurations. Automated production technology concentrates investment-grade tooling demand among tier-one packaging groups, whereas handcrafted moulds retain niche utility in artisan and short-run specialty formats where geometric complexity exceeds CNC cost thresholds.
FDA food-contact substance regulations in the United States, EU F-Gas Regulation constraints on drying energy profiles, and China's GB standards for pulp molded products collectively shape material eligibility, surface finish requirements, and thermal efficiency benchmarks across export-oriented tooling shops. EAMC and DKM Machine Manufacturing Inc. navigate this compliance mosaic through multi-certification die metallurgy and process documentation packages that accelerate customer audit cycles. Stakeholders must monitor evolving extended producer responsibility frameworks and carbon border adjustment mechanisms, as these instruments will increasingly determine which tooling specifications qualify for premium packaging procurement tenders.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polystyrene tray demand into molded fiber alternatives, forcing packaging converters to retool forming lines at unprecedented velocity and reshaping die procurement patterns across European foodservice supply chains.
Growth Catalysts
- F-Gas Regulation thermal efficiency mandates:European drying energy constraints are accelerating tooling upgrades to direct-in-line thermal profiles that reduce gas consumption per cavity cycle.
- Foodservice packaging substitution:Quick-service restaurant chains are eliminating polystyrene clamshells and expanding molded fiber tray specifications across North American and European outlets.
- Yangtze River Delta cluster density:Die shops concentrated near machine builders in Jiangsu and Zhejiang provinces are compressing delivery cycles through co-located CNC machining and heat-treatment facilities.
Market Restraints
- Aluminum alloy price volatility:Tooling-grade aluminum ingot fluctuations compress margin predictability for mid-cap die shops unable to hedge raw material exposure.
- Single-region supply concentration:Precision cavity machining capacity clusters disproportionately in eastern Chinese industrial zones, creating geographic vulnerability to logistics disruption.
- Legacy press incompatibility:Existing reciprocating forming equipment lacks the thermal uniformity required for next-generation thin-wall designs, stranding capital in depreciating machine bases.
Strategic Opportunities
- India food-contact packaging expansion:FSSAI compliance pathways for molded fiber are opening quick-service and institutional catering procurement channels previously dominated by plastic converters.
- Carbon border adjustment mechanism alignment:EU CBAM documentation requirements for imported packaging will favor tooling suppliers offering certified low-carbon metallurgy and process traceability packages.
- Hybrid thermoforming-compression integration:Convergence of transfer molding precision with wet-press throughput is enabling single-tool flexibility across multiple product formats.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact substance notifications and EU F-Gas thermal profile validations extend new product qualification cycles beyond customer launch windows.
- Legacy CAD-CAM integration friction:Handcrafted die shops face capability gaps in five-axis CNC programming required for complex undercut geometries demanded by electronics dunnage applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Moulding Tooling Market |
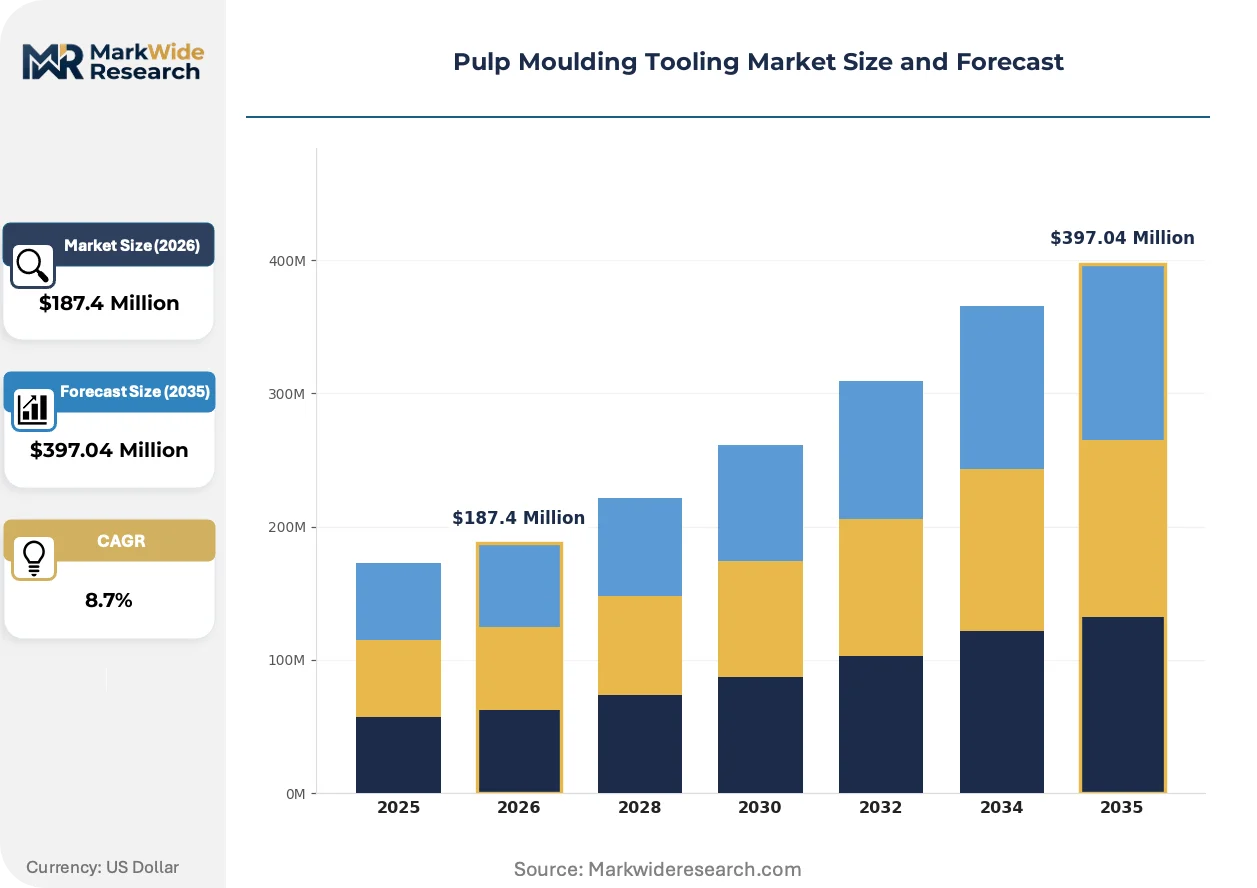
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Moulds, Thermoforming Moulds, Injection Moulds, Compression Moulds End User: Automotive, Consumer Goods, Electronics, Packaging Material: Paper, Starch, Biodegradable Plastics, Fibers Technology: CNC Machining, 3D Printing, Handcrafted Moulds, Automated Production |
| Companies Covered | Pulp Moulding Dies Inc., DKM Machine Manufacturing Inc., Guangzhou Nanya Pulp Molding Equipment Co., Ltd., Beston (Henan) Machinery Co., Ltd., BeSure Technology Co., Inmaco Solutions B.V., SODALTECH, EAMC, HGHY Pulp Molding Pack Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Moulding Tooling Market Strategic Shifts
Tooling metallurgy and thermal management systems are undergoing rapid specification shifts as energy regulations tighten and end-users demand thinner-wall, higher-definition molded fiber surfaces.
Direct-in-line drying technology is absorbing the capital investment previously allocated to separate hot-press stations, enabling continuous forming-to-drying workflows that eliminate intermediate handling damage. Tier-one European packaging groups are adopting these integrated systems for high-volume egg carton and produce tray lines, compressing total installed tooling counts per million-unit output capacity.
REACH substance restrictions on chromium-based surface treatments are forcing die shops to migrate toward plasma-nitrided and PVD-coated cavity finishes that maintain release properties without hexavalent chromium exposure. Tooling suppliers serving export markets are dual-certifying metallurgical processes to preempt customer audit failures, with Scandinavian buyers enforcing the strictest documentation protocols.
Specification consolidation among multinational foodservice buyers is compressing vendor counts, with procurement teams mandating unified die standards across regional forming facilities. This concentration favors tooling shops offering global refurbishment networks and digital cavity inventory management, particularly visible in North American quick-service chain rollouts where identical tray specifications deploy across multiple co-packer locations.
Pulp Moulding Tooling Market Segmentation
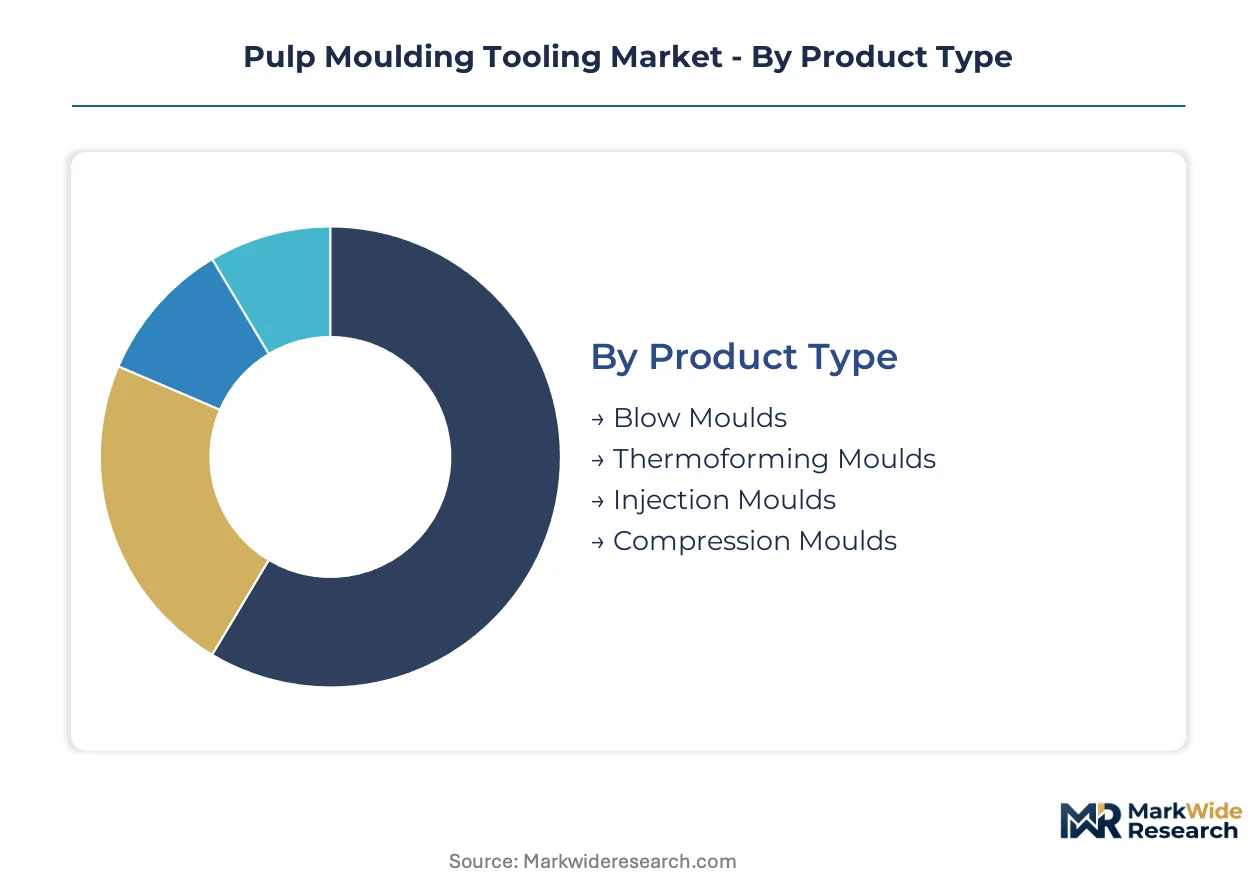
Pulp moulding tooling procurement follows distinct technical and commercial logics across product formats, end-use specifications, and manufacturing methods. Buyers weight cavity precision, thermal uniformity, and format flexibility differently depending on production scale and regulatory exposure.
Product Type:
Tooling selection pivots on the trade-off between legacy equipment compatibility and energy efficiency mandates in target export markets.
- Compression Moulds:Reciprocating press dies machined from aluminum bronze alloys dominate installed capacity across foodservice tray lines. European packaging converters facing F-Gas Regulation thermal constraints are accelerating refurbishment cycles for these legacy configurations.
- Thermoforming Moulds:Transfer molding tooling with integrated direct-in-line drying surfaces enables continuous fiber slurry processing without intermediate handling. Quick-service restaurant chains in North America are specifying these formats for clamshell replacement programs.
- Blow Moulds:Hollow-form cavity designs serve specialized bottle and container geometries with lower volume throughput than flat-stock formats.
- Injection Moulds:High-pressure precision tooling for complex undercut geometries in electronics dunnage applications requiring tight dimensional tolerances.
Compression moulds lead on scale; thermoforming moulds lead on momentum.
End User:
Application-specific performance requirements drive metallurgy selection and surface finish protocols across buyer categories.
- Packaging:Food-contact cavity specifications dominate procurement volume, with FDA substance notifications and EU F-Gas thermal profiles determining die shop qualification. Quick-service chains and produce distributors are the primary demand anchors.
- Electronics:Anti-static surface treatments and sub-0.05 mm cavity tolerances protect sensitive components during shipment. Asian contract manufacturers are expanding molded fiber dunnage specifications for consumer electronics.
- Automotive:Heavy-duty fiber forms for parts containment and shipping protection, with OEMs specifying recycled content thresholds in supplier tooling contracts.
- Consumer Goods:Short-run specialty formats and artisan packaging where geometric complexity exceeds automated machining cost thresholds.
Packaging commands the largest share; electronics shows the steepest expansion trajectory.
Material:
Feedstock composition determines release properties, drying energy profiles, and end-of-life biodegradation certifications for finished articles.
- Fibers:Recycled paper pulp and agricultural residue blends constitute the primary feedstock for food-contact packaging, with REACH substance restrictions on additives shaping slurry formulation.
- Biodegradable Plastics:PLA and PHA hybrid formulations for moisture barrier applications in refrigerated food packaging.
- Paper:Virgin and recycled kraft pulp grades for premium surface finish requirements in visible presentation packaging.
- Starch:Modified starch binders for enhanced wet strength in high-humidity distribution environments.
Fibers anchor volume demand; biodegradable plastics are climbing fastest on regulatory substitution pressure.
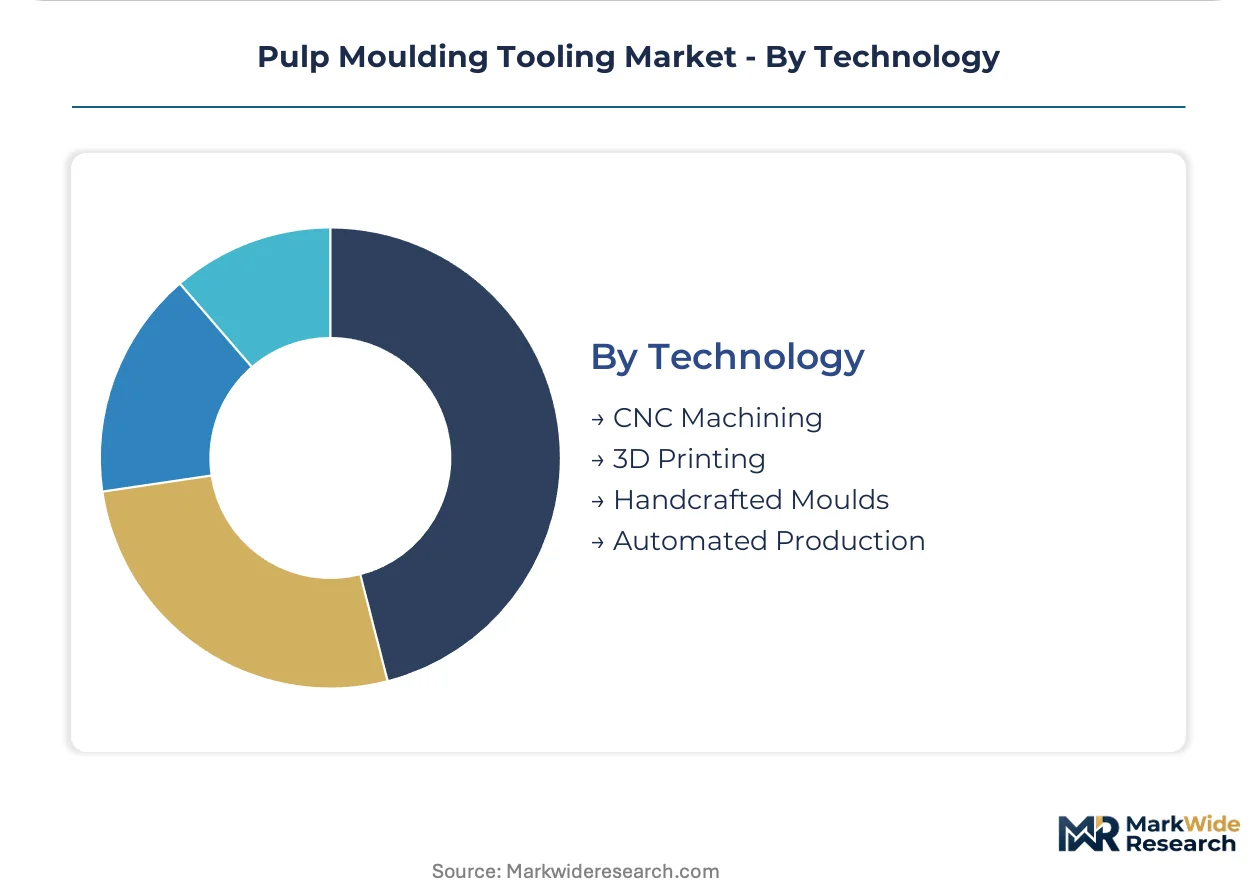
Technology:
Production method selection reflects the tension between geometric precision and capital investment thresholds across customer tiers.
- CNC Machining:Five-axis milling centers achieve 0.05 mm cavity tolerances for high-speed rotary equipment. Yangtze River Delta die shops cluster these capabilities near molded pulp machine builders.
- Automated Production:Integrated machining and heat-treatment lines compress delivery cycles for Asian equipment OEMs with standardized die specifications.
- 3D Printing:Additive manufacturing for prototype cavities and short-run specialty formats where conventional tooling economics fail.
- Handcrafted Moulds:Artisan techniques retain utility in complex undercut geometries and heritage packaging formats where CNC programming costs exceed production volumes.
CNC machining holds the dominant position; automated production lines are expanding most quickly on delivery speed requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp moulding tooling originated in European food packaging during the mid-20th century, with Sweden and Germany pioneering rotary press die designs for egg carton mass production. This industrial lineage established metallurgical standards and cavity tolerance benchmarks that persist in contemporary specifications.
China
Yangtze River Delta die shops supply precision-machined aluminum bronze tooling to domestic molded pulp equipment OEMs. GB standards for pulp molded products govern surface finish and food-contact compliance. Jiangsu and Zhejiang provinces concentrate CNC machining capacity within 50 kilometers of major machine builders.
United States
Quick-service restaurant chains are eliminating polystyrene clamshells across thousands of outlets. FDA food-contact substance notifications determine die shop qualification for foodservice packaging procurement. Tooling refurbishment networks cluster in Midwest industrial corridors serving legacy reciprocating press installations.
Germany
Packaging converters are retooling forming lines to meet F-Gas Regulation thermal efficiency mandates. ECHA REACH substance restrictions on chromium-based surface treatments are forcing migration to plasma-nitrided cavity finishes. Bavarian precision engineering shops supply matched tooling pairs for high-speed rotary equipment.
India
FSSAI compliance pathways for molded fiber are opening quick-service and institutional catering procurement channels. Central government PLI scheme incentives support domestic packaging machinery manufacturing. Gujarat and Maharashtra industrial zones attract die fabrication investment serving South Asian export markets.
Netherlands
EU Single-Use Plastics Directive enforcement is compressing polystyrene tray demand into molded fiber alternatives. Rotterdam port logistics facilitate die import from Asian fabrication centers. Randstad region packaging technology firms specify unified tooling standards across European co-packer networks.
Pulp Moulding Tooling Market Competitive Environment
The competitive structure tilts toward integrated machine-tooling bundlers with captive die fabrication capabilities. Mid-cap independent specialists retain position in aftermarket refurbishment and short-run custom geometries. Three archetypes dominate: Yangtze River Delta cluster fabricators co-located with equipment OEMs, European precision engineering houses serving regulatory-intensive markets, and Asian integrated bundlers controlling full production system delivery. Consolidation pressure concentrates among tier-one packaging groups demanding global refurbishment networks and digital cavity inventory management.
Among Chinese fabricators, Guangzhou Nanya Pulp Molding Equipment Co., Ltd. and Beston (Henan) Machinery Co., Ltd. exemplify the integrated bundler archetype. BeSure Technology Co. occupies a position within the precision machining tier, while SODALTECH represents European specialist positioning. These named entities anchor commentary on geographic and structural segmentation without attributing specific strategic actions or market shares.
| Leading Market Players |
|---|
| Pulp Moulding Dies Inc. |
| DKM Machine Manufacturing Inc. |
| Guangzhou Nanya Pulp Molding Equipment Co., Ltd. |
| Beston (Henan) Machinery Co., Ltd. |
| BeSure Technology Co. |
| Inmaco Solutions B.V. |
| SODALTECH |
| EAMC |
| HGHY Pulp Molding Pack Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
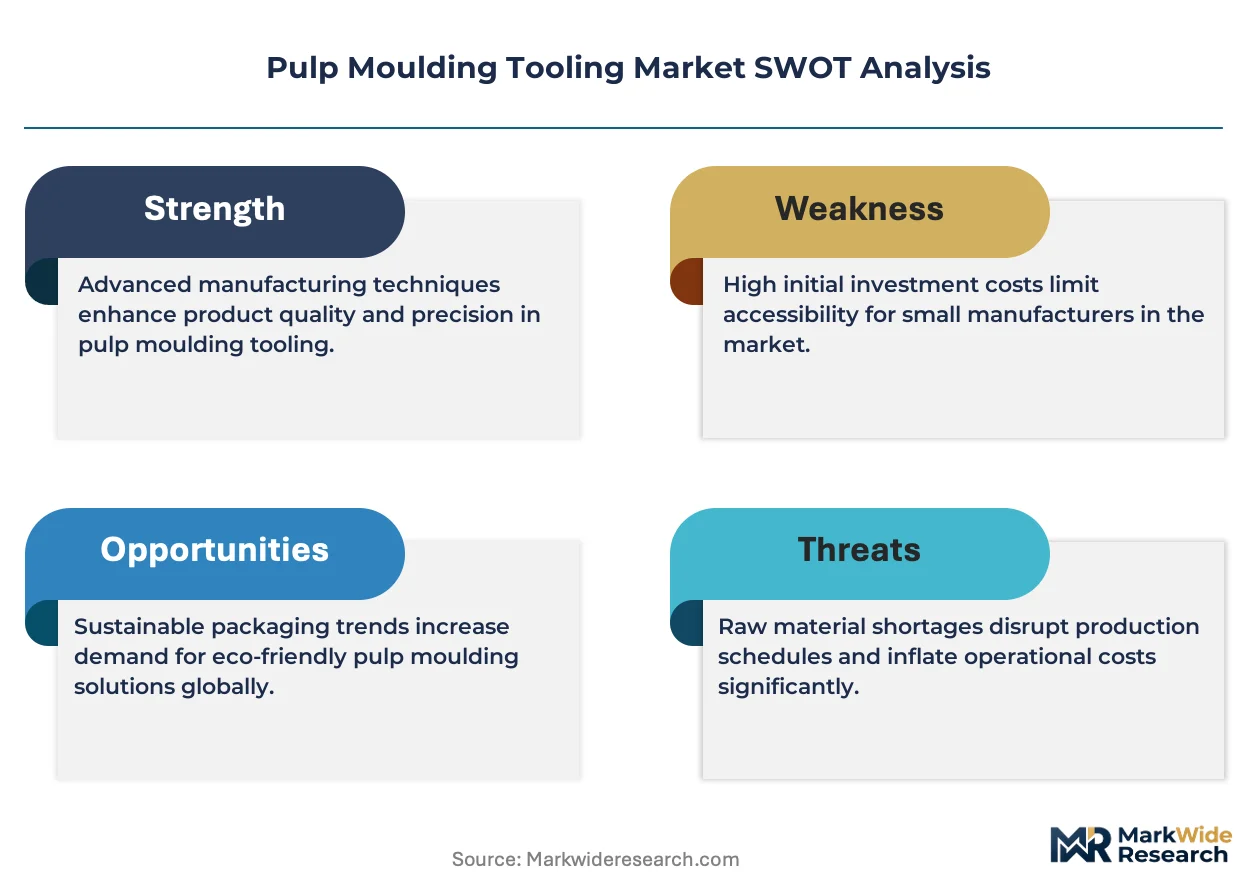
Certification-grade bifurcation between FDA-notified and non-certified tooling separates premium die shops from commodity fabricators, concentrating pricing power with integrated bundlers who control metallurgical documentation while fragmenting margin pools among undifferentiated Yangtze River Delta job shops dependent on spot aluminum markets.
Pricing Analysis
Bundled machine-tooling packages command sustained premiums over unbundled die procurement, with integrated Asian OEMs capturing value through captive heat-treatment and CNC finishing that compress delivery cycles. Price differentiation rests on F-Gas thermal profile certification and FDA food-contact substance notification status, with European buyers paying substantial uplifts for dual-compliant metallurgy. Cost compression in commodity aluminum bronze tooling is intensifying because ingot volatility erodes hedging capacity at mid-cap fabricators. Quick-service restaurant chains exhibit highest price sensitivity in volume tray specifications, while electronics dunnage buyers prioritize sub-0.05 mm cavity tolerances over unit cost.
Supply Chain Analysis
Skilled five-axis CNC programming talent scarcity in Jiangsu and Zhejiang provinces constrains precision cavity machining expansion, tethering high-tolerance thermoforming mould output to established Yangtze River Delta clusters. Raw material supply draws from tooling-grade aluminum ingot streams, aluminum bronze alloy foundries, and plasma-nitriding service providers concentrated in eastern Chinese industrial zones. Single-region machining capacity creates geographic vulnerability to logistics disruption and export documentation delays. Distribution runs through equipment OEM bundlers for new press installations and independent refurbishment networks for legacy reciprocating press aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulp moulding tooling has entered a late-cycle quality phase where specification consolidation among multinational foodservice buyers favors die shops with global certification depth and digital cavity inventory systems over pure-play price competitors.
For Market Incumbents: Deploy backward integration into captive aluminum bronze foundry operations to insulate margin structures from ingot volatility while accelerating heat-treatment throughput. Incorporate plasma-nitrided surface finishing capabilities in-house to preempt REACH substance restriction compliance failures that threaten European customer retention. Consolidate refurbishment network density in Midwest US corridors and Randstad European zones to defend against emerging Asian bundlers expanding aftermarket service footprints. For New Entrants and Emerging Players: Begin with FSSAI compliance pathway navigation for Indian quick-service and institutional catering channels where molded fiber penetration remains underdeveloped relative to plastic converter dominance. Target electronics dunnage specifications for Asian contract manufacturers demanding anti-static surface treatments and complex undercut geometries that exceed legacy die shop CNC programming capabilities. Pursue equipment OEM co-location partnerships in Gujarat and Maharashtra industrial zones to bypass Yangtze River Delta supply concentration risks. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-one packaging groups demand unified die standards across regional forming facilities and global refurbishment networks. Five-to-ten year viability favors precision machining specialists with integrated certification documentation capabilities over commodity job shops without captive metallurgy control. Monitor EU Carbon Border Adjustment Mechanism implementation timelines as the critical inflection signal determining which tooling specifications qualify for premium packaging procurement tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Metallurgy Investment | Simultaneous FDA and EU F-Gas compliance accelerates customer audit cycles for export-oriented die shops. |
| Direct-in-Line Drying Tooling Integration | Thermoforming mould designs compatible with continuous forming-to-drying workflows capture quick-service replacement demand. |
| Global Refurbishment Network Expansion | Distributed cavity reconditioning capacity satisfies multinational buyer mandates for standardized die performance across co-packer locations. |
| Plasma-Nitrided Surface Treatment Migration | Hexavalent chromium-free cavity finishes preempt ECHA REACH restriction enforcement and Scandinavian documentation protocols. |
| Five-Axis CNC Programming Capability Buildout | Complex undercut geometry machining opens electronics dunnage specifications with sub-0.05 mm tolerance requirements. |
Study Parameters
Coverage spans China, the United States, Germany, India, and the Netherlands, with primary inputs from each market gathered through structured interviews with molded pulp equipment OEM procurement directors, die shop operations managers, packaging converter maintenance engineers, quick-service restaurant chain sustainability officers, and regulatory compliance specialists at export-oriented fabricators. Secondary validation incorporates customs and trade data, ECHA substance restriction filings, FDA food-contact substance notification databases, FSSAI compliance pathway documentation, and SEC filings from publicly traded packaging groups. Bottom-up tooling unit demand estimates triangulate against top-down packaging production capacity projections.
Segmentation granularity extends to compression versus thermoforming mould technology categories, food-contact versus electronics versus automotive end-use specifications, and CNC machining versus automated production versus handcrafted fabrication methods across the projection horizon. CAGRs derive from installed base refurbishment cycle analysis, new press deployment trajectories, and regulatory substitution elasticity modeling. Industry-specific forecast inputs include F-Gas Regulation thermal efficiency mandate compliance timelines, EU Single-Use Plastics Directive enforcement phase schedules, and quick-service restaurant chain polystyrene elimination commitment disclosure patterns.
Several conditions sit outside the modeled scope, including acute aluminum alloy price spike scenarios exceeding historical volatility bands, geopolitical logistics disruption affecting Yangtze River Delta export corridors, and unanticipated REACH substance restriction expansions beyond chromium-based treatments. Forecasts reflect assumptions regarding steady regulatory enforcement progression and continued foodservice packaging substitution momentum. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Performance Composites Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Case Material Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Structural Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Plastic Composites Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Graphite Felt Market
Composite Materials
Composite Preforms Market