

PCR Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Laminates Market Insights
Direct procurement channels between laminate producers and large furniture manufacturers is reshaping how PCR laminates reach end users. Amcor plc leverages its global packaging infrastructure to secure recycled resin streams for laminate substrate production. Mondi plc anchors European supply through integrated pulp and paper recycling operations that feed decorative overlay papers. Constantia Flexibles Group GmbH competes on specialized barrier coatings that protect recycled core layers from moisture degradation.
PCR laminates are multi-layered surface materials manufactured from post-consumer recycled paper, wood fibers, or thermoplastic resins bonded under heat and pressure, typically achieving densities of 0.7–1.4 g/cm³ depending on pressure class and resin loading. Their primary purpose is to deliver durable, aesthetically finished surfaces for furniture, interiors, and architectural applications while displacing virgin material content. High-pressure laminates dominate current production volumes due to established performance certification and builder familiarity, though compact laminates are gaining fastest in healthcare and transportation interiors where impact resistance and hygiene standards converge. Decorative laminates carry the deepest margin pools because brand-owning furniture manufacturers pay premiums for exclusive surface designs and batch-consistent color matching across recycled feedstocks.
The EU Green Deal and REACH compliance frameworks constrain allowable formaldehyde emissions and mandate recycled content disclosure, pushing laminate producers toward phenolic and melamine resin systems with lower volatile profiles. EPA TSCA Title VI in the United States parallels these limits on composite wood products, creating dual-jurisdiction certification burdens for exporters. BIS standards in India are beginning to address recycled content claims in building materials, though enforcement remains fragmented across states. Stakeholders must monitor how evolving extended producer responsibility schemes in the European Union and individual US state legislatures will alter cost allocation between resin suppliers, laminate manufacturers, and finished goods assemblers.
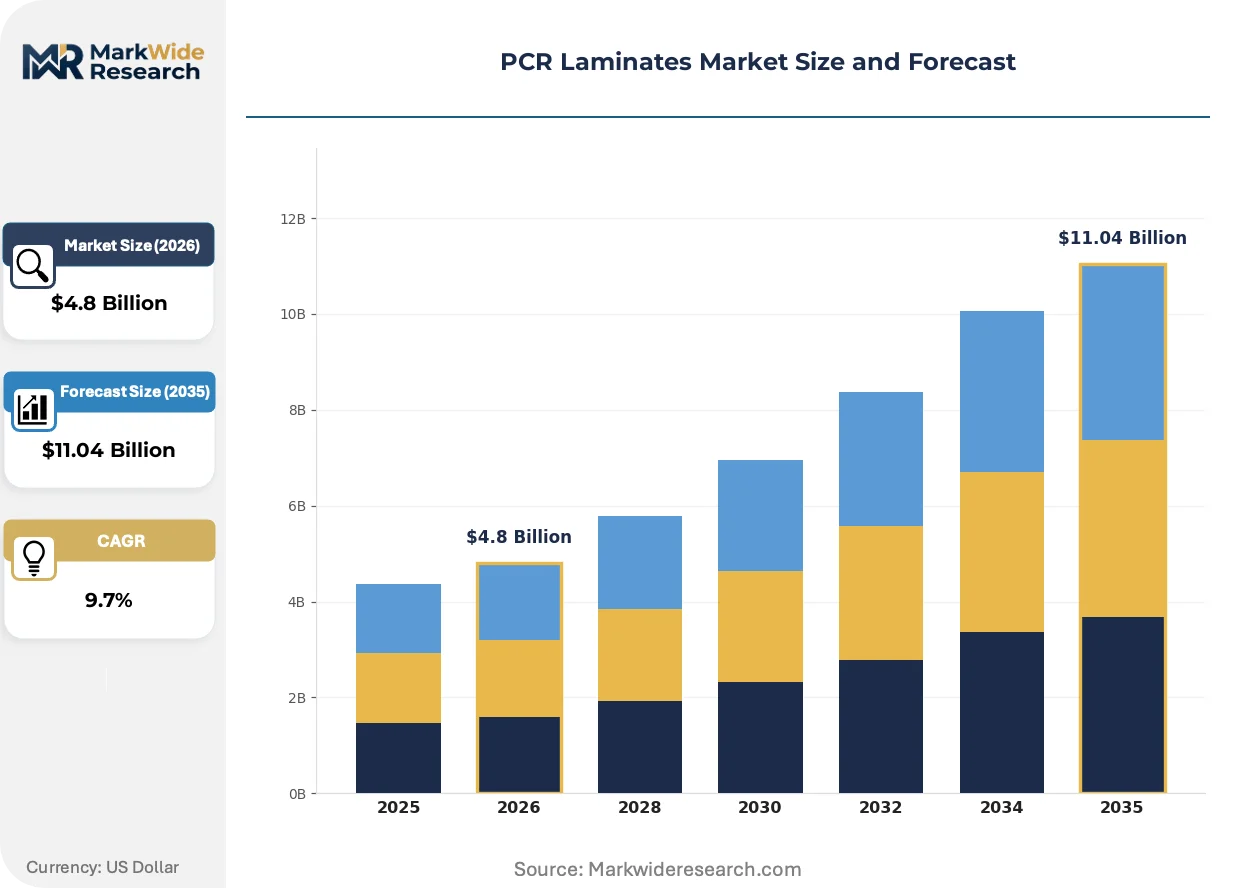
Market Dynamics
The EU Green Deal's circular economy mandates are compressing laminate supply chains into shorter, certified loops where post-consumer resin provenance determines market access. Furniture manufacturers now face binding recycled content thresholds that reshape sourcing relationships with substrate and overlay suppliers.
Growth Catalysts
- REACH formaldehyde limits:Stricter ECHA emission caps on composite wood products accelerate phenolic resin adoption in high-pressure laminate cores, favoring producers with low-VOC formulation capabilities.
- Kitchen furniture sector:German cabinet manufacturers are integrating certified PCR laminates into premium product lines to meet retailer sustainability scorecards and consumer disclosure expectations.
- Compact laminate technology:Thicker, densified panels are displacing conventional surfaces in healthcare interiors where impact resistance and steam sterilization compatibility converge.
Market Restraints
- Recycled resin feedstock volatility:Post-consumer thermoplastic collection rates fluctuate seasonally, creating input cost instability for substrate producers dependent on rPET and rPP streams.
- Decorative paper supply concentration:European specialty paper mills in Scandinavia and Germany control the majority of overlay-grade pulp recycling capacity, creating geographic chokepoints.
- Performance certification gaps:Lack of harmonized international standards for PCR content verification forces duplicate testing under EPA TSCA Title VI, REACH, and BIS regimes.
Strategic Opportunities
- Indian building materials sector:BIS standards for recycled content claims are emerging in Maharashtra and Gujarat, creating first-mover positioning for certified laminate imports ahead of full federal enforcement.
- Transportation interiors:Rail and aviation seat manufacturers are specifying compact laminates with flame-retardant recycled cores to meet updated fire safety codes without virgin phenolic loading.
- Extended producer responsibility schemes:France's Citeo packaging eco-modulation fees reward high-recycled-content surfaces, creating cost advantages for PCR laminate adopters in contract furniture.
Industry Challenges
- Color matching expertise:Batch consistency across variable recycled feedstocks requires specialized spectrophotometry and formulation chemists in short supply among mid-tier laminate producers.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA Title VI and EU CE marking processes extend product launch cycles by 8-14 months for export-oriented manufacturers.
- Legacy press reconfiguration:Converting high-pressure laminate lines to handle higher-moisture recycled paper overlays demands capital-intensive press control system upgrades.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Laminates Market Trends and Innovations
Digital traceability systems and automated sorting technologies are compressing the cost premium between virgin and post-consumer laminate substrates. These innovations intersect with tightening chemical disclosure rules to reshape how surface materials are specified, certified, and procured across construction and furniture value chains.
Spectroscopic resin identification is digitizing quality control at recycled substrate plants, enabling real-time polymer grade sorting that was previously manual and error-prone. German laminate producers are deploying near-infrared scanners to maintain melamine-phenolic ratios despite variable post-consumer paper fiber inputs. This digitizing of feedstock characterization is compressing batch rejection rates and narrowing the cost gap with virgin-core laminates.
REACH Annex XVII restrictions on formaldehyde-releasing substances are forcing decorative overlay producers toward modified melamine resins with lower free formaldehyde content. The industrial consequence is extended press cycle times and higher energy consumption per panel. Kitchen furniture manufacturers in Northern Europe are responding by consolidating supplier bases to favor integrated resin-laminate operations with captive chemical synthesis.
Direct mill-to-furniture-factory contracting is displacing traditional distributor networks for high-volume PCR laminate procurement. Large German and French kitchen producers are negotiating multi-year offtake agreements that specify recycled content percentages and batch traceability. This channel compression is most visible in the Benelux region, where logistics platforms now coordinate just-in-time laminate delivery to automated panel processing centers.
PCR Laminates Market Segmentation
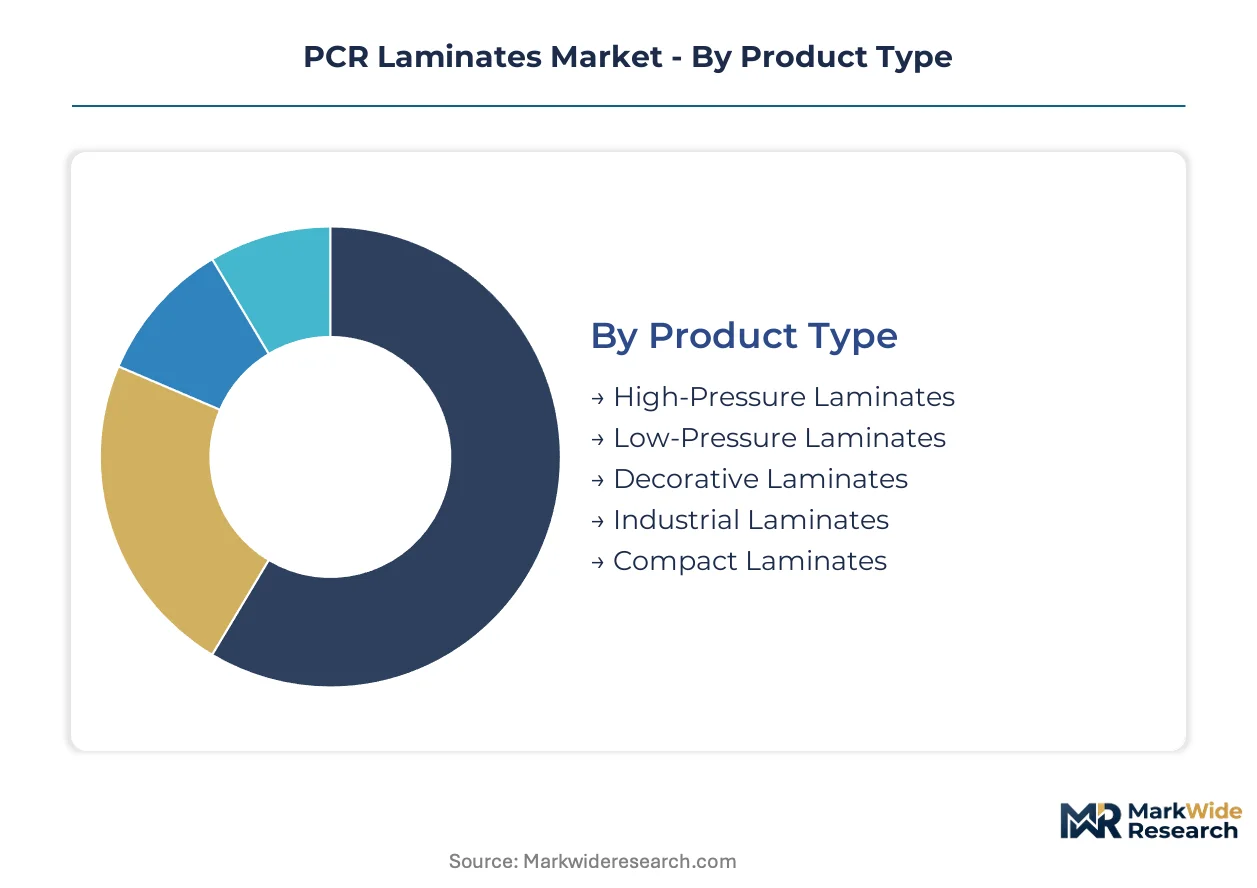
PCR laminate specifications diverge sharply across pressure classes, resin systems, and end-use durability requirements. Manufacturers configure production lines around these dimensional splits to capture margin pools in premium furniture versus commodity construction applications.
Product Type:
Cost tier separates commodity substrates from performance-engineered surfaces commanding formulation premiums.
- High-Pressure Laminates:Multi-layer construction achieves densities of 1.3–1.4 g/cm³ through phenolic-impregnated kraft cores and decorative overlays cured at 7–9 MPa. German kitchen furniture manufacturers specify these for countertop and cabinet door applications where moisture resistance and surface hardness prove decisive.
- Compact Laminates:Self-supporting panels 2–25mm thick eliminate substrate dependency through homogeneous resin-fiber composition. Healthcare interiors in France and Belgium specify compact grades for operating room wall cladding and laboratory casework requiring steam sterilization compatibility without substrate delamination risk.
- Decorative Laminates:Surface aesthetics drive specification through printed overlay papers and synchronized embossed textures.
- Low-Pressure Laminates:Continuous lamination onto particleboard or MDF substrates reduces unit costs for mass-market furniture.
- Industrial Laminates:Electrical and mechanical grade specifications prioritize dielectric strength and dimensional stability over surface appearance.
High-Pressure Laminates command the established base. The steepest expansion runs through Compact Laminates.
Application:
End-use durability requirements reshape resin selection and panel thickness specifications across interior surface categories.
- Furniture Surfaces:Cabinet doors, tabletops, and shelving components demand scratch-resistant melamine overlays with post-consumer recycled kraft cores. REACH-compliant low-formaldehyde formulations are becoming baseline requirements for contract furniture exports to Northern Europe.
- Countertops:Horizontal work surfaces require enhanced moisture barriers and heat resistance driving phenolic-rich core formulations. Kitchen renovation specialists in Stuttgart and Munich specify certified PCR laminates meeting retailer sustainability scorecards.
- Wall Paneling:Vertical installations prioritize lightweight substrates with fire-retardant ratings for commercial interiors.
- Flooring:Abrasion class AC3–AC5 specifications govern laminate flooring overlays with recycled HDF cores.
- Ceiling Panels:Acoustic and fire-rated suspended systems utilize perforated compact laminates in transportation hubs.
Furniture Surfaces absorb the majority of current volume. Countertops are gaining share fastest as kitchen renovation cycles accelerate.
Technology:
Resin chemistry determines volatile emissions, cure speed, and compatibility with recycled fiber inputs.
- Melamine Resins:Formaldehyde-melamine condensation polymers provide transparent, hard, heat-resistant surface overlays. Modified low-free-formaldehyde grades are displacing conventional formulations under ECHA Annex XVII pressure.
- Phenolic Resins:Phenol-formaldehyde systems bond kraft paper cores into rigid, moisture-resistant substrates. German producers favor phenolic-rich formulations for high-pressure laminate cores exposed to humid kitchen environments.
- Thermosetting Resins:Cross-linked polymer networks irreversibly cure under heat and pressure.
- Acrylic Resins:UV-curable systems enable digital printing and short-run decorative customization.
- Epoxy Resins:High-performance industrial laminates utilize epoxy for electrical insulation and chemical resistance.
Phenolic Resins anchor core layer production. Melamine Resins are climbing the fastest as surface overlay specifications tighten.
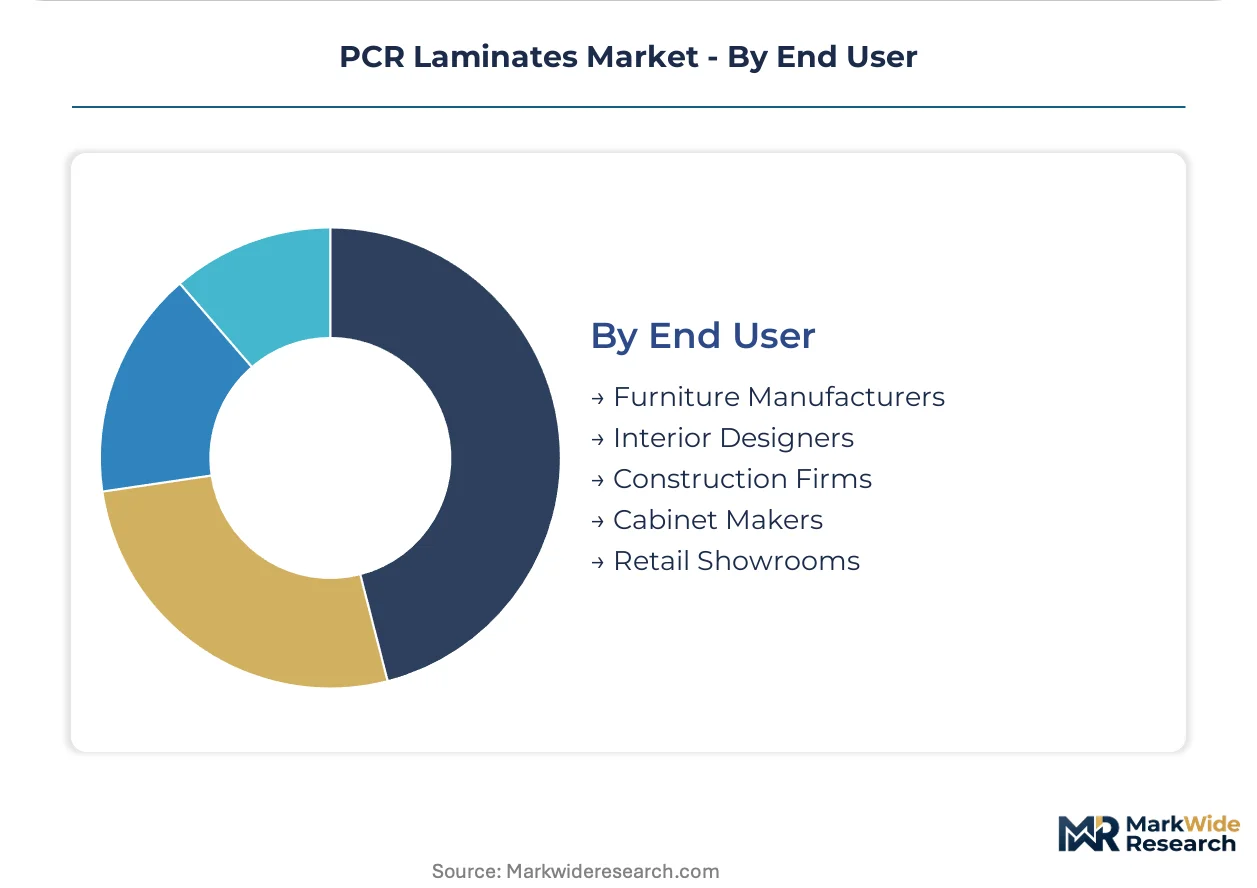
End User:
Customer scale and technical capability segment procurement patterns from specification-grade to commodity volume purchasing.
- Furniture Manufacturers:Large-scale panel processors negotiate direct mill contracts specifying recycled content percentages and batch traceability. Automated cutting and edgebanding lines in the Benelux region coordinate just-in-time laminate delivery to minimize inventory carrying costs.
- Construction Firms:Project-based procurement bundles laminates with substrate panels and installation services. French commercial contractors leverage Citeo eco-modulation fees to specify high-recycled-content surfaces in public building tenders.
- Cabinet Makers:Small-batch custom fabricators purchase through distributor networks with color-matching services.
- Interior Designers:Specification influence drives premium decorative laminate selection for hospitality and corporate interiors.
- Retail Showrooms:Point-of-sale display and fixture manufacturers utilize low-pressure laminates for short-lifecycle promotional installations.
Furniture Manufacturers dominate volume procurement. Construction Firms are expanding most quickly as green building certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German laminate producers commanding premium contracts, while Indian manufacturers absorb feedstock volatility without comparable margin recovery. This asymmetry reflects divergent regulatory enforcement timelines and certification infrastructure maturity across the two markets.
Germany
Kitchen furniture manufacturers in Stuttgart and Munich drive specification-grade demand for certified PCR laminates meeting retailer sustainability scorecards. The EU Green Deal's circular economy mandates bind producers to verified recycled content thresholds through ECHA oversight. The Baden-Württemberg industrial corridor concentrates high-pressure laminate production serving contract furniture exporters.
United States
EPA TSCA Title VI compliance creates dual-certification burdens for laminate importers serving residential construction and commercial interiors. State-level extended producer responsibility schemes in California and New York are beginning to reward high-recycled-content surfaces through procurement preferences. The Southeast manufacturing belt around Atlanta and Charlotte hosts automated panel processing centers coordinating just-in-time laminate delivery.
France
Citeo packaging eco-modulation fees reward furniture manufacturers specifying PCR laminates with verified post-consumer resin content in public building tenders. REACH Annex XVII formaldehyde limits accelerate adoption of low-VOC phenolic core formulations among Paris-region kitchen producers. The Hauts-de-France industrial zone anchors decorative overlay paper recycling operations feeding laminate substrate plants.
India
BIS standards for recycled content claims in building materials are emerging in Maharashtra and Gujarat ahead of full federal enforcement. State-level green procurement guidelines in these industrial hubs create first-mover positioning for certified laminate imports. The Mumbai-Pune corridor concentrates furniture manufacturing clusters integrating imported PCR laminates into mid-market product lines.
Belgium
Benelux logistics platforms coordinate cross-border laminate distribution to automated cutting and edgebanding lines serving German and French furniture factories. EU CE marking requirements for construction products enforce harmonized performance testing across recycled-content surfaces. The Port of Antwerp handles bulk resin feedstock imports for regional substrate producers.
PCR Laminates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream managing resin formulation and overlay paper supply. The vendor base organizes around three functional layers: substrate producers controlling recycled fiber streams, decorative overlay specialists managing color consistency, and barrier coating formulators protecting core layers from moisture degradation. Consolidation pressure runs strongest among mid-tier laminate producers lacking captive resin synthesis or direct mill-to-furniture-factory contracting relationships. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers seek to secure certified recycled feedstock volumes.
Among packaging-sector conglomerates with laminate-adjacent operations, Amcor plc occupies a position exemplifying global resin stream integration, while Mondi plc anchors European supply through pulp and paper recycling infrastructure. Constantia Flexibles Group GmbH sits within the specialized barrier coating tier, representing the formulation expertise required to protect recycled core layers from performance degradation.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi plc |
| Constantia Flexibles Group GmbH |
| Coveris Holdings S.A. |
| ProAmpac LLC |
| Berry Global Group |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Winpak Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Baden-Württemberg industrial corridor concentrates European high-pressure laminate capacity, and this geographic chokepoint translates into asymmetric pricing power for German substrate producers serving contract furniture exporters. Recycled resin feedstock volatility compresses margins for Indian manufacturers who lack comparable certification premiums to recover input cost swings.
Pricing Analysis
Configured-to-order pricing commands spreads of 15-25% above standard catalog laminates, with premium-mid-economy pricing differentiation anchored by ECHA REACH certification tiers and batch traceability guarantees. Price differentiation stems from formaldehyde compliance grade and volume scale, with large German kitchen manufacturers negotiating multi-year offtake agreements at indexed rates. Cost compression in commodity low-pressure laminates is intensifying because decorative paper mills in Scandinavia control overlay-grade pulp recycling capacity. Small-batch cabinet makers prove most price-sensitive, while integrated furniture manufacturers absorb premiums for exclusive surface designs and color-matched recycled feedstocks.
Supply Chain Analysis
Export-control regimes on phenolic resin precursor chemicals constrain flows from Chinese phenol manufacturers to European laminate substrate plants, creating formulation bottlenecks during supply disruptions. Geographic supply concentration centers on Germany, Belgium, and India, with the Mumbai-Pune corridor emerging as a secondary hub for mid-market furniture integration. Raw material dependencies draw from post-consumer thermoplastic collection systems, Scandinavian specialty paper recycling operations, and phenol-formaldehyde resin synthesis. Single-source vulnerability runs through European overlay-grade pulp mills, where mill closures would cascade through decorative laminate availability. Distribution runs through direct mill-to-furniture-factory contracting for high-volume procurement, displacing traditional distributor networks in the Benelux and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR laminate incumbents face substitution pressure from bio-based surface materials and thin porcelain slabs capturing premium kitchen renovation spend. Defense requires insulating core capabilities from feedstock volatility and certification fragmentation.
For Market Incumbents: Insulate formulation expertise by securing captive phenolic resin synthesis or backward integration into recycled paper pulping operations. Prioritize ECHA REACH Annex XVII pre-certification for low-formaldehyde grades to compress multi-jurisdiction approval timelines. Channel control through direct mill contracts with large German and French kitchen manufacturers locks in volume commitments and reduces distributor margin leakage.
For New Entrants and Emerging Players: Pursue white-space positioning in Indian state-level green procurement corridors, specifically Maharashtra and Gujarat, where BIS standards for recycled content claims are emerging ahead of federal enforcement. Target transportation interior specifications for rail and aviation seat manufacturers seeking flame-retardant compact laminates with recycled cores. A go-to-market angle anchored by Citeo eco-modulation fee optimization for French public building tenders creates immediate specification access.
For Investors and Strategic Acquirers: Carve-out targets emerge from packaging-sector conglomerates with laminate-adjacent operations but non-core decorative surface exposure, where substrate recycling infrastructure can be extracted and focused. Long-term viability hinges on 5-10 year regulatory trajectory alignment, with extended producer responsibility schemes expanding across EU member states and US state legislatures. The signal to watch is harmonization of PCR content verification standards between EPA TSCA Title VI and EU CE marking regimes, which would eliminate duplicate testing burdens and accelerate margin recovery for certified producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Streams | Captive rPET and rPP supply secures input cost stability for substrate producers facing seasonal collection volatility. |
| REACH Annex XVII Pre-Certification Investment | Low-formaldehyde formulation approval compresses product launch cycles by 8-14 months for export-oriented manufacturers. |
| Direct Mill-to-Furniture-Factory Contracting | Multi-year offtake agreements with German kitchen producers lock in volume and displace distributor margin leakage. |
| Spectroscopic Feedstock Characterization Deployment | Near-infrared scanning at recycled substrate plants reduces batch rejection rates and narrows cost gaps with virgin-core laminates. |
| Transportation Interior Specification Capture | Compact laminate qualification for rail and aviation seats opens fire-retardant recycled core demand outside furniture saturation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laminate plant managers, furniture manufacturer procurement leads, decorative overlay paper mill technical directors, and ECHA regulatory affairs specialists; and secondary validation through customs and trade data, SEC filings of packaging-sector conglomerates with laminate-adjacent operations, BIS draft standard notifications, and Citeo eco-modulation fee schedules. Bottom-up triangulation across resin formulation inputs, press capacity utilization, and furniture production volumes was cross-checked against top-down market sizing through end-use sector absorption analysis.
Forecast inputs considered pressure class segmentation, resin chemistry splits between phenolic and melamine systems, and end-use durability requirements across furniture, healthcare, and transportation interior applications. Modeled dimensions included product type, application, technology, and end user categories, with CAGRs derived from regression analysis of historical capacity expansion, regulatory enforcement timelines, and substitution elasticity parameters. Industry-specific inputs incorporated EU Green Deal circular economy mandate implementation pacing and extended producer responsibility scheme adoption curves.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, furniture export demand, and recycled feedstock collection economics would shift the trajectory. Forecasts reflect assumptions around regulatory harmonization progress and certification infrastructure maturation. Material shifts in REACH Annex XVII enforcement stringency or US state-level EPR scheme proliferation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.