
 CFRTP Market | 2026-2036
CFRTP Market Size, Share, and Industry Trends Forecast 2026-2036
CFRTP Market Analysis
A shortage of trained thermoplastic composite technicians is unwinding capacity expansion timelines at multiple Tier 1 suppliers. Hexcel Corporation leverages its Salt Lake City operations to sustain prepreg CFRTP output for aerospace prime contractors. Toray Industries dominates unidirectional tape supply through integrated carbon fiber-to-CFRTP manufacturing in Japan. LANXESS anchors European automotive programs with hybrid CFRTP compounds certified for crash-critical applications.
Continuous fiber-reinforced thermoplastic composites combine carbon, glass, or aramid fibers with polyamide, PEEK, or polypropylene matrices, achieving specific stiffness values exceeding aluminum at half the weight. The materials process in seconds via injection molding or compression molding rather than hours for thermoset equivalents. Fabric CFRTP holds mature margins in aerospace secondary structures, while injection-molded automotive parts represent the fastest-expanding application segment. Prepreg CFRTP commands premium positioning in sporting goods where batch consistency and surface finish justify higher material costs.
FAA airworthiness directives and EASA CS-25 standards govern CFRTP qualification for commercial aircraft structures in the United States and Europe. REACH restricts certain resin chemistries, forcing reformulation of polyamide matrices used in consumer electronics housings. China's GB standards for automotive plastics are converging with international test methods, reducing certification friction for multinational suppliers. Stakeholders must monitor thermoplastic recycling infrastructure buildout, as closed-loop fiber recovery will determine long-term cost competitiveness against virgin material supply chains.
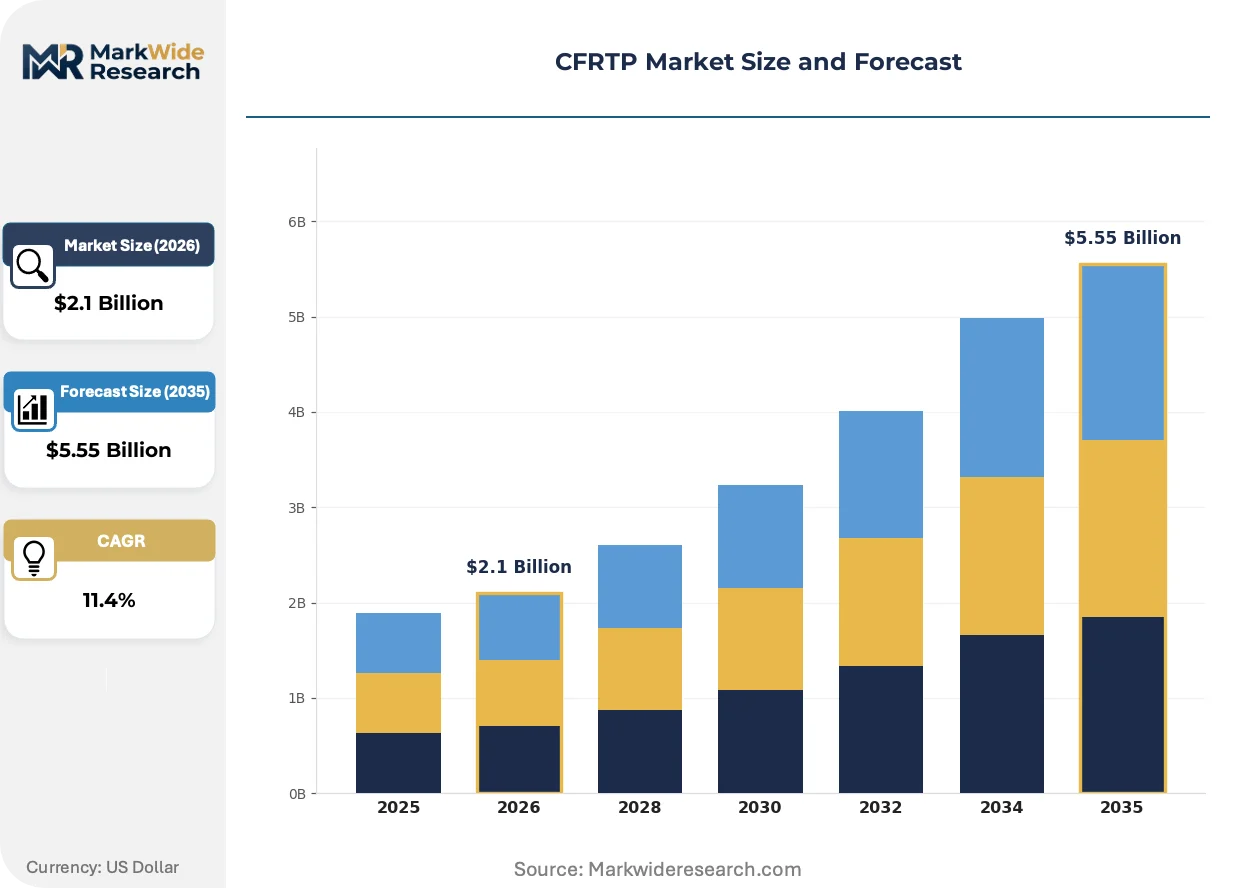
Market Dynamics
Automotive lightweighting mandates and aerospace qualification timelines are compressing CFRTP adoption cycles, forcing material suppliers to reconcile thermoplastic processing speed with legacy thermoset certification pathways.
Growth Catalysts
- EU Green Deal emissions targets:German and French automotive OEMs now specify CFRTP for crash-critical structural members to meet fleet CO2 reduction thresholds.
- FAA-EASA harmonized airworthiness pathways:Streamlined dual certification for thermoplastic primary structures accelerates platform integration at US and European aerospace primes.
- PEEK matrix formulations:High-temperature thermoplastic matrices enable engine-adjacent aerospace applications previously reserved for thermosets or metals.
Market Restraints
- Carbon fiber supply concentration:Precursor and fiber production clusters in Japan and the United States create geographic vulnerability for CFRTP compounders dependent on Toray or Hexcel supply.
- REACH chemical restrictions:ECHA scrutiny of certain polyamide additives forces costly reformulation of consumer electronics-grade CFRTP without performance degradation.
- Aluminum-lithium substitution:Airbus and Boeing suppliers retain metal options for wing structures where CFRTP damage tolerance data remains incomplete.
Strategic Opportunities
- Chinese automotive CFRTP penetration:Domestic EV manufacturers in Shanghai and Shenzhen seek localized unidirectional tape supply for battery enclosure structural members.
- Closed-loop fiber recovery infrastructure:Pyrolysis-based carbon fiber reclamation from end-of-life aerospace parts promises 40% cost reduction versus virgin fiber for non-structural applications.
- Hybrid CFRTP-steel overmolding:Metal-composite hybrid processing enables crash management systems that leverage steel energy absorption with CFRTP weight savings.
Industry Challenges
- Certified thermoplastic composite technician scarcity:Tier 1 suppliers in Germany and the United States report 18-month training pipelines for automated fiber placement operators.
- In-process quality verification:Real-time weld line monitoring for induction-welded thermoplastic joints lacks standardized non-destructive testing protocols accepted by FAA and EASA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CFRTP Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unidirectional CFRTP, Fabric CFRTP, Hybrid CFRTP, Prepreg CFRTP End Use Industry: Aerospace, Automotive, Electronics, Consumer Goods Application: Structural Components, Interior Panels, Automotive Parts, Sporting Goods Manufacturing Method: Injection Molding, Compression Molding, Resin Transfer Molding, Thermoforming |
| Companies Covered | Hexcel Corporation, LANXESS, Toray Industries Inc., Mitsubishi Chemical Corporation, Avient Corporation, Solvay SA, SGL Carbon SE, Celanese Corporation, Teijin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CFRTP Market Emerging Trajectories
CFRTP processing economics are fundamentally restructuring competitive boundaries between thermoset incumbents and thermoplastic entrants across aerospace and automotive supply chains.
Automated fiber placement with in-situ consolidation is decomposing the traditional autoclave bottleneck for large thermoplastic structures. Boeing and Airbus tier suppliers in Kansas and Hamburg deploy laser-assisted AFP systems achieving deposition rates exceeding thermoset prepreg layup by an order of magnitude. This velocity is compressing lead times for wing spars and fuselage frames from months to weeks.
REACH authorization requirements for certain flame-retardant additives are forcing reformulation of polyamide 6 and PA66 matrices used in consumer electronics housings. Compounders in the Netherlands and Belgium now qualify halogen-free phosphorus-based alternatives meeting UL 94 V-0 ratings. Electronics OEMs in Taiwan and South Korea are accelerating supplier qualification for these reformulated grades to maintain EU market access.
Automotive procurement teams are consolidating CFRTP sourcing around crash-performance-certified compounders capable of lot-traceable supply. Tier 1 seating and interior suppliers in Michigan and Bavaria now require resin batch certificates and fiber tow identification codes for every production lot. This traceability mandate favors vertically integrated carbon fiber-to-CFRTP manufacturers over merchant compounders.
CFRTP Market Segmentation
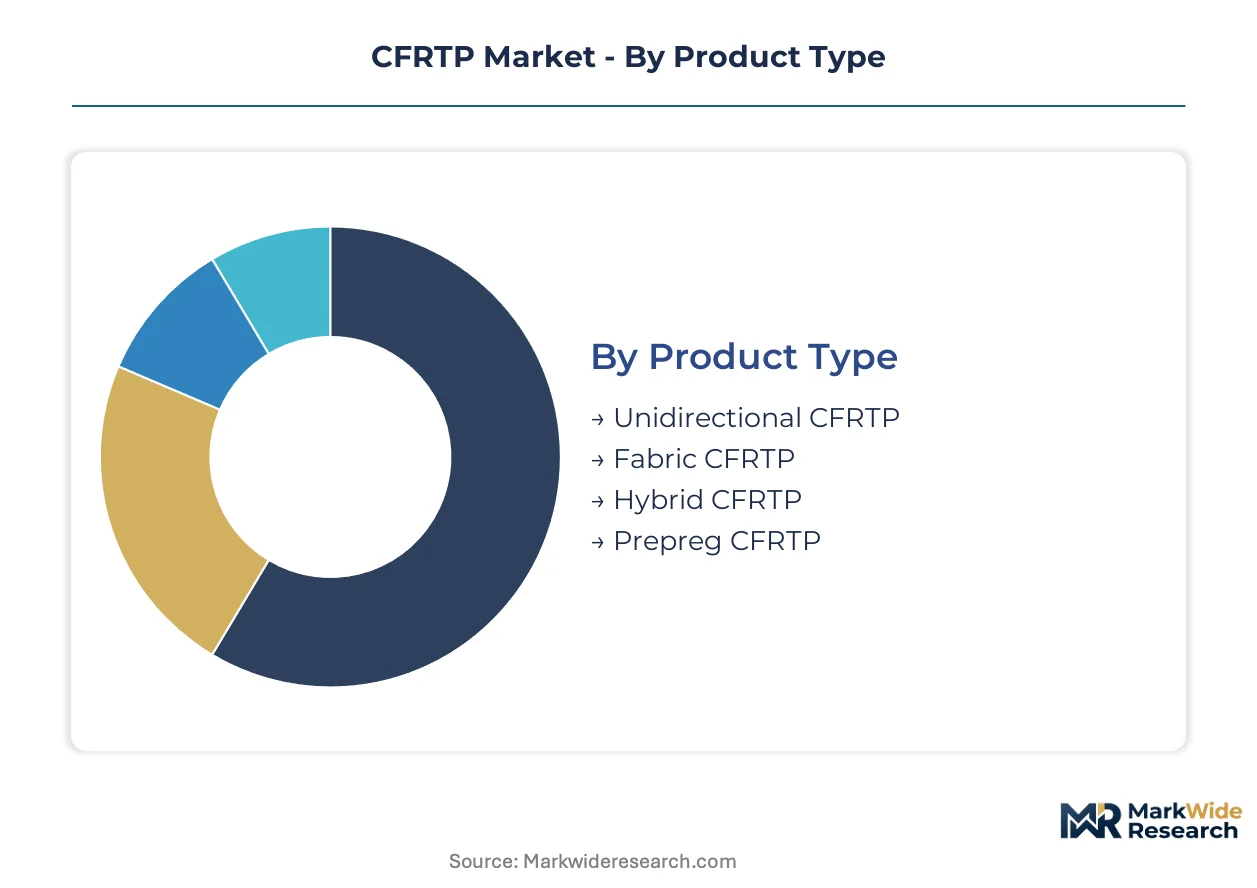
CFRTP segmentation reveals divergent certification pathways and margin structures across product architectures and manufacturing methods. Regulatory frameworks from FAA, EASA, and REACH create tiered compliance burdens that reshape supplier economics by segment.
Product Type:
Regulatory differentiation separates aerospace-qualified formats from industrial grades, with FAA-EASA harmonization favoring continuous fiber architectures over discontinuous alternatives.
- Unidirectional CFRTP:Continuous carbon fibers aligned in a single direction within polyamide or PEEK matrices deliver maximum specific stiffness for primary load-bearing structures. Aerospace tier suppliers in Wichita and Hamburg specify this format for wing spars and fuselage frames where FAA airworthiness directives mandate damage tolerance documentation.
- Prepreg CFRTP:Pre-impregnated fiber-resin combinations stored under controlled temperature enable batch-consistent processing for sporting goods manufacturers demanding surface finish precision. ECHA scrutiny of certain resin chemistries forces compounders toward halogen-free formulations to maintain EU market access.
- Fabric CFRTP:Woven fiber architectures suit complex-curvature aerospace secondary structures with established qualification protocols.
- Hybrid CFRTP:Discontinuous fiber-reinforced compounds blend CFRTP with steel or aluminum for automotive crash management systems.
Fabric CFRTP handles the majority of throughput; unidirectional CFRTP is the fastest mover on share.
End Use Industry:
Cost tier separation distinguishes premium-certified aerospace supply from high-volume automotive procurement.
- Aerospace:Primary and secondary structures governed by FAA-EASA harmonized airworthiness pathways command material premiums justified by extensive qualification testing. Boeing and Airbus tier suppliers in Kansas and Hamburg drive specification development for thermoplastic primary structures.
- Automotive:Crash-critical structural members specified by German and French OEMs to meet EU Green Deal emissions thresholds represent the steepest expansion trajectory. Tier 1 seating and interior suppliers in Michigan and Bavaria now mandate lot-traceable supply with resin batch certificates.
- Electronics:Consumer electronics housings face REACH-driven reformulation of polyamide matrices as compounders qualify halogen-free phosphorus-based alternatives.
- Consumer Goods:Sporting goods applications leverage prepreg CFRTP batch consistency for premium positioning.
Automotive procurement concentrates the highest volume demand; aerospace maintains the steepest margin premiums.
Application:
Volume scale separates structural load-bearing applications from cosmetic or secondary uses.
- Structural Components:Wing spars, fuselage frames, and battery enclosure members require unidirectional tape or fabric formats with documented mechanical property retention. Wichita-based tier suppliers deploy laser-assisted automated fiber placement to compress lead times from months to weeks.
- Automotive Parts:Injection-molded brackets, clips, and underhood components specified by Shanghai and Shenzhen EV manufacturers gain share fastest as domestic Chinese producers seek localized unidirectional tape supply.
- Interior Panels:Aircraft cabin components with established flame-retardant certification favor mature fabric CFRTP formats.
- Sporting Goods:Bicycles, hockey sticks, and racquets justify prepreg premiums through surface finish and batch consistency requirements.
Structural components absorb the greatest material tonnage; automotive parts are climbing the fastest.
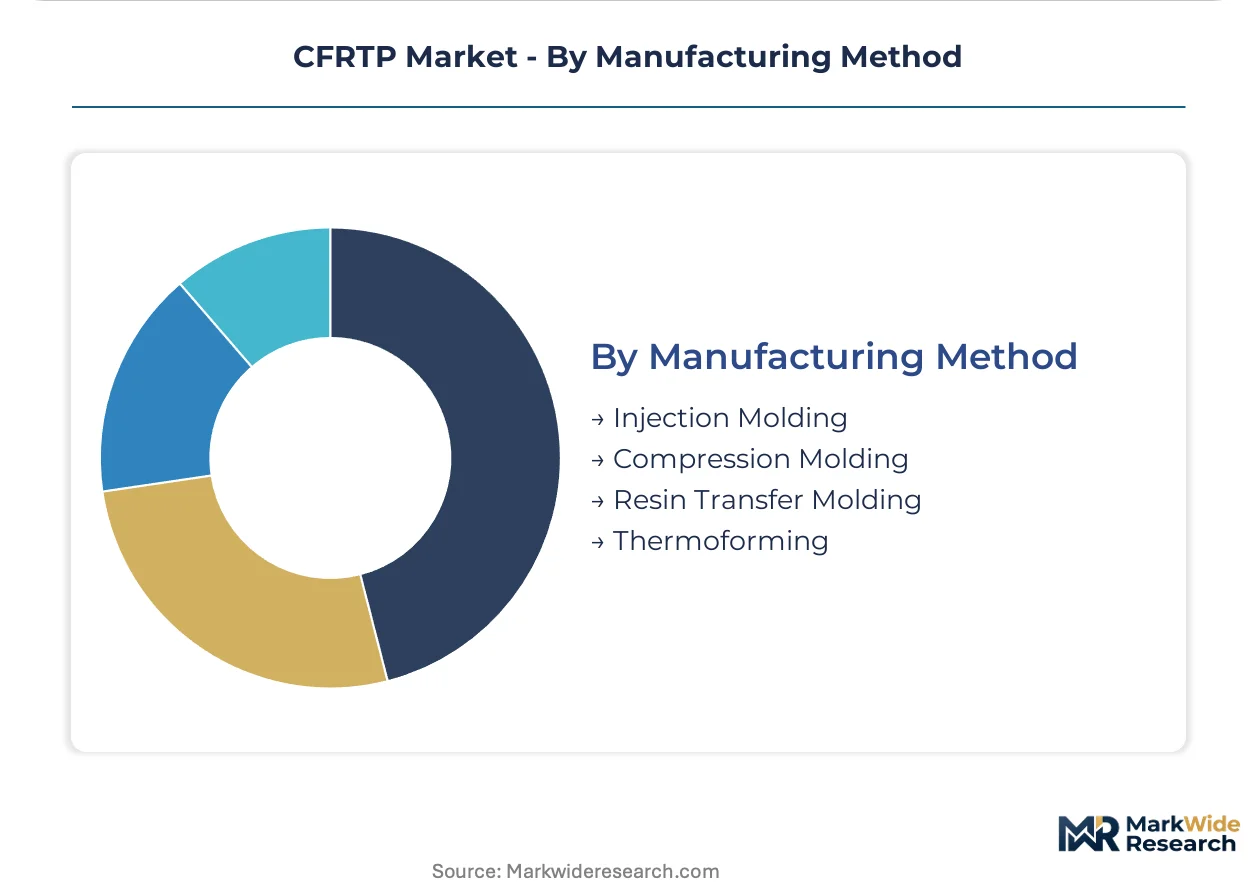
Manufacturing Method:
Processing speed determines competitive positioning against thermoset incumbents.
- Injection Molding:Discontinuous fiber compounds process in seconds versus hours for thermoset equivalents, enabling high-volume automotive production. Michigan and Bavaria-based Tier 1 suppliers consolidate sourcing around crash-performance-certified compounders with lot-traceable supply.
- Compression Molding:Sheet formats consolidate under heat and pressure for aerospace secondary structures with moderate geometric complexity.
- Resin Transfer Molding:Lower-volume aerospace applications retain this method where fiber architecture control exceeds speed priorities.
- Thermoforming:Heated sheet shaping suits aircraft interior panels with established tooling amortization.
Injection molding dominates automotive throughput; compression molding anchors aerospace secondary structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor North American aerospace demand, while EASA CS-25 standards and REACH chemical restrictions govern European procurement. Japanese METI industrial policy and Chinese GB standards for automotive plastics complete the regulatory triad shaping regional CFRTP deployment.
United States
Boeing tier suppliers in Wichita and Kansas drive specification development for thermoplastic primary structures. FAA-EASA harmonized airworthiness pathways streamline dual certification for wing spars and fuselage frames. Hexcel Corporation leverages Salt Lake City operations to sustain prepreg CFRTP output for aerospace prime contractors.
Germany
Automotive OEMs in Stuttgart and Munich specify CFRTP for crash-critical structural members to meet EU Green Deal emissions thresholds. KBA vehicle certification requirements mandate documented mechanical property retention for lightweight structural components. LANXESS anchors European automotive programs with hybrid CFRTP compounds certified for crash-critical applications.
Japan
Toray Industries dominates unidirectional tape supply through integrated carbon fiber-to-CFRTP manufacturing under METI industrial standards. PMDA pharmaceutical-grade material specifications influence medical device CFRTP adoption. Nagoya and Tokyo industrial clusters concentrate precursor production and fiber conversion capacity.
China
Domestic EV manufacturers in Shanghai and Shenzhen seek localized unidirectional tape supply for battery enclosure structural members. GB standards for automotive plastics are converging with international test methods, reducing certification friction for multinational suppliers. MIIT industrial policy supports domestic carbon fiber capacity buildout to reduce import dependency.
France
Airbus tier suppliers in Toulouse and Nantes deploy laser-assisted automated fiber placement for thermoplastic fuselage components. EASA CS-25 damage tolerance documentation requirements favor established fabric CFRTP formats for secondary structures. ANSM oversight of medical device materials creates adjacent demand for biocompatible thermoplastic composites.
CFRTP Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in CFRTP supply. Carbon fiber producers with captive compounding capabilities occupy the upper stratum, while merchant compounders and regional fabricators fill volume gaps. Strategic archetypes include fiber-integrated manufacturers, resin-centric compounders, and application-specific processors. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers reconcile thermoplastic processing speed with legacy certification pathways.
Within the integrated fiber-to-composite tier, Hexcel Corporation, Toray Industries Inc., and LANXESS occupy positions that exemplify divergent geographic and end-use anchoring. Hexcel represents North American aerospace-centric supply, Toray anchors Japanese integrated manufacturing, and LANXESS exemplifies European automotive-focused compounding. These three entities represent the structural poles around which merchant compounders and regional specialists arrange their competitive positioning.
| Leading Market Players |
|---|
| Hexcel Corporation |
| LANXESS |
| Toray Industries Inc. |
| Mitsubishi Chemical Corporation |
| Avient Corporation |
| Solvay SA |
| SGL Carbon SE |
| Celanese Corporation |
| Teijin Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between aerospace primes and carbon fiber producers lock in both supply access and price visibility for unidirectional CFRTP tape across the qualification-heavy procurement cycle. These arrangements insulate Tier 1 suppliers from precursor volatility while committing buyers to volume minimums that amortize dedicated production lines at Toray and Hexcel facilities.
Pricing Analysis
Japan commands a 15-20% premium over European CFRTP pricing due to integrated carbon fiber-to-compounding economics and METI-supported capacity. Three-tier pricing structure across aerospace-qualified, automotive crash-certified, and industrial grades reflects certification burden and lot-traceability requirements. Price differentiation stems from FAA-EASA qualification documentation and fiber tow provenance tracking. Cost compression in industrial-grade fabric CFRTP is intensifying because Chinese domestic capacity buildout under MIIT policy expands merchant supply.
Supply Chain Analysis
Japan and the United States anchor carbon fiber precursor and conversion capacity, with Nagoya and Salt Lake City clusters feeding global CFRTP compounders. Raw material dependencies rest on acrylonitrile monomer supply, polyamide and PEEK resin streams, and specialized sizing chemistries for fiber-matrix adhesion. Single-source vulnerability concentrates in Toray's unidirectional tape dominance for aerospace primary structures. Distribution runs through qualified Tier 1 converter networks in Wichita, Hamburg, and Nagoya that hold FAA-EASA delegated authority for material release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CFRTP penetration sits at early-cycle expansion, with automotive lightweighting mandates in Germany and China accelerating specification velocity faster than prior thermoset composite adoption curves.
For Market Incumbents: Compound certification advantages by deepening captive fiber supply through backward integration into precursor production or securing exclusive offtake from emerging carbon fiber capacity in China. Anchor automotive procurement consolidation by embedding lot-traceability systems that satisfy KBA and MIIT documentation requirements. Defend against aluminum-lithium substitution in wing structures by completing damage tolerance databases for thermoplastic primary structures under FAA-EASA harmonized pathways. For New Entrants and Emerging Players: Differentiate on localized unidirectional tape supply for Chinese EV battery enclosures, where domestic qualification under converging GB standards reduces incumbent lock-in. Target crash-critical automotive brackets in Michigan and Bavaria where Tier 1 suppliers seek second-source compounders with certified hybrid CFRTP-steel overmolding capability. Pursue direct qualification with Shenzhen and Shanghai EV manufacturers bypassing traditional aerospace-centric distribution channels. For Investors and Strategic Acquirers: Automated fiber placement specialists with laser-assisted in-situ consolidation expertise represent the highest-conviction acquisition archetype as Boeing and Airbus tier suppliers compress lead times from months to weeks. Monitor closed-loop fiber recovery infrastructure buildout as the inflection signal—pyrolysis-based carbon fiber reclamation achieving 40% cost reduction versus virgin fiber would restructure raw material economics for non-structural applications across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray's Nagoya cluster demonstrates captive acrylonitrile supply insulates margin from petrochemical volatility. |
| Laser-Assisted Automated Fiber Placement Deployment | Wichita and Hamburg tier suppliers achieve deposition rates exceeding thermoset prepreg layup by an order of magnitude. |
| Halogen-Free Polyamide Matrix Reformulation | Dutch and Belgian compounders qualify phosphorus-based alternatives maintaining UL 94 V-0 ratings under REACH authorization. |
| Closed-Loop Carbon Fiber Recovery Infrastructure | Pyrolysis reclamation from end-of-life aerospace parts promises cost parity for non-structural CFRTP applications. |
| Crash-Performance Certification Investment | LANXESS anchors European automotive programs with hybrid compounds certified for KBA structural member requirements. |
Methodological Framework
Cross-validation between primary interviews with aerospace Tier 1 procurement directors, automotive platform engineers, and thermoplastic composite R&D leads anchors the qualitative findings against secondary validation. Regulatory filings with FAA, EASA, and ECHA; carbon fiber trade flow data; and OEM technical specification releases provide external calibration. Bottom-up build of unidirectional tape, prepreg, fabric, and hybrid CFRTP volumes triangulates against top-down aerospace and automotive lightweighting spend analysis.
Sensitivity analysis around carbon fiber price trajectories, REACH authorization timelines for flame-retardant additives, and Chinese domestic capacity buildout under MIIT policy stress-tests projection outputs across the modeling period. Segmentation dimensions include product architecture, end-use industry, application load-bearing requirement, and manufacturing method velocity. CAGRs derive from elasticity modeling against automotive CO2 compliance thresholds and aerospace platform introduction cycles, with PEEK matrix adoption in engine-adjacent applications as a specific demand-pull input.
The analysis sits within stated boundaries; outcomes outside sustained FAA-EASA harmonization progress or accelerated Chinese GB standards convergence would require recalibration. Forecasts reflect assumptions on technician training pipeline resolution and in-process quality verification protocol standardization. Recalibration cycles align with material shifts in thermoplastic recycling infrastructure economics and automotive OEM platform standardization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Composite Cans Market
Composite Materials
Turbine Blade Material Market
Composite Materials
FRP Tanks Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Carbon Composites Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Marine Composites Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
FRP Grating Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Aramid Fiber Reinforced Polymer Market