
 Polypropylene and Polypropylene Composites Market | 2026-2036
Polypropylene and Polypropylene Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene and Polypropylene Composites Market Analytics
Direct procurement channels between resin producers and automotive Tier-1 molders is rewriting traditional distributor economics in polypropylene supply. ExxonMobil Chemical Company leverages its Baton Rouge polymerization complex to sustain captive feedstock advantage for North American automotive compounding. SABIC anchors Middle Eastern supply through its Yanbu derivatives hub, while Borealis AG differentiates via Borstar proprietary reactor technology yielding narrow melt-flow distribution for thin-wall packaging.
Polypropylene and polypropylene composites comprise thermoplastic polymers built from propylene monomer homopolymerization or copolymerization with ethylene, reinforced with mineral fillers or glass fibers to achieve tensile moduli exceeding 5 GPa and heat deflection temperatures above 120°C. These materials serve primarily as lightweight, chemically resistant substitutes for metals and engineering plastics in injection-molded components and extruded films. Homopolymer grades dominate volume in rigid packaging and textile fiber applications where stiffness and clarity command premium placement. Glass-filled compounds represent the fastest-expanding product category as automotive platforms substitute 40% glass-reinforced polypropylene for painted steel in bumper beams and instrument-panel carriers, concentrating margin pools with compounders mastering long-fiber impregnation technology.
REACH registration requirements and the EU Green Deal's plastics recycling mandates compel European producers to certify post-industrial and post-consumer content thresholds, while China's MEE enforces dual carbon emissions caps on naphtha crackers that elevate bio-based propylene pathway economics. The US EPA and OSHA jointly govern resin handling and volatile organic compound limits at compounding facilities, creating compliance cost divergence between integrated and merchant producers. Stakeholders must monitor feedstock passporting standards and recycled-content verification protocols as these frameworks mature and cross-border shipment rules tighten.
Market Dynamics
Automotive lightweighting mandates and circular-economy feedstock requirements are forcing compounders to reconfigure their propylene sourcing and long-fiber impregnation capabilities simultaneously.
Growth Catalysts
- China's NMPA circular-economy directives:Post-consumer recycled content mandates under updated GB standards redirect capital toward chemical recycling infrastructure for polypropylene feedstock recovery.
- Glass-filled compound adoption:Tier-one automotive suppliers substitute 40% glass-reinforced grades for painted steel in bumper beams and structural carriers, concentrating volume with long-fiber technology specialists.
- Yangtze River Delta integration:East China's petrochemical corridor achieves lowest delivered costs through captive propylene-to-compound operations, attracting downstream molding investments.
Market Restraints
- Naphtha feedstock volatility:Crude-linked propylene production economics expose merchant compounders to margin compression when olefin spreads tighten.
- REACH registration burdens:ECHA compliance timelines and dossier costs create asymmetric barriers for smaller compounders serving European automotive OEMs.
- Engineering thermoplastic substitution:Polyamide and PBT compounds compete for under-hood applications requiring continuous service temperatures above 150°C.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic content requirements for electric vehicle platforms create localized compounding demand for battery housings and thermal management modules.
- Bio-based propylene pathways:Renewable naphtha and bio-ethanol-to-propylene technologies gain economic viability under EU Green Deal carbon border adjustments.
- Direct resin-to-molder procurement:Bypassing traditional distributor networks captures margin pools currently held by regional polymer traders serving mid-tier packaging converters.
Industry Challenges
- Long-fiber impregnation expertise scarcity:Compounders struggle to recruit process engineers capable of maintaining fiber length distribution through twin-screw extrusion without thermal degradation.
- Dual carbon compliance timelines:China's MEE emissions caps on steam crackers force simultaneous capital deployment into efficiency retrofits and renewable feedstock qualification.
- Post-consumer feedstock traceability:Developing auditable chain-of-custody systems for mechanically recycled polypropylene strains existing ERP and quality management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene and Polypropylene Composites Market |
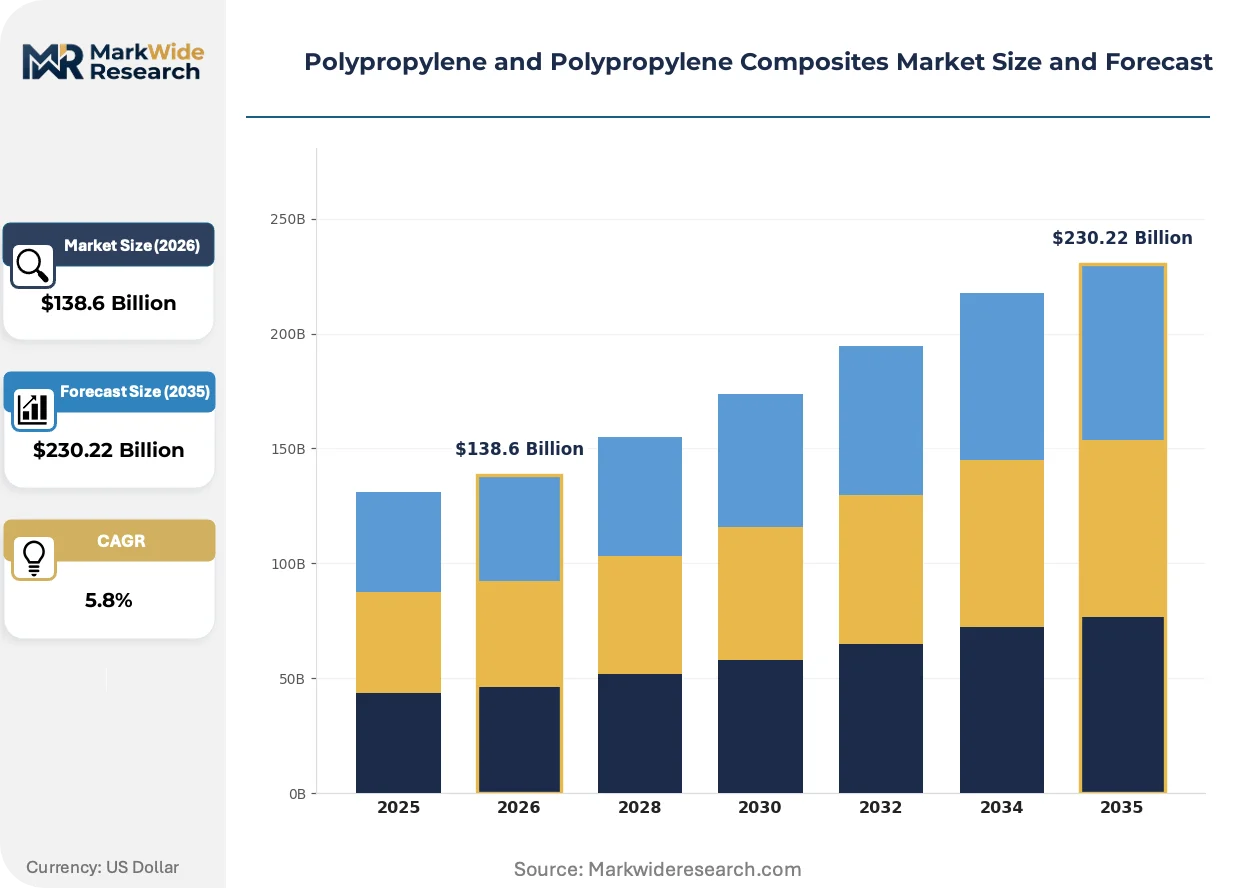
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $230.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Mineral-Reinforced, Glass-Filled Application: Packaging, Automotive, Consumer Goods, Textiles End User: Manufacturing, Construction, Agriculture, Electronics Form: Granules, Sheets, Films, Fibers |
| Companies Covered | LyondellBasell Industries Holdings B.V., ExxonMobil Chemical Company, SABIC, Borealis AG, Sumitomo Chemical Co., Ltd., Kingfa Sci. & Tech. Co., Ltd., Mitsui Chemicals, Inc., Trinseo, Washington Penn Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene and Polypropylene Composites Market Evolving Landscape
Digital process control and closed-loop material authentication are converging to transform how compounders guarantee performance consistency and recycled-content claims across distributed supply networks.
Advanced rheology modeling software is digitizing melt-flow prediction for multi-phase polypropylene composites during injection molding cycle design. Tier-one automotive molders deploy these tools to reduce warpage in thin-wall instrument panel carriers by 30% versus traditional trial-and-error methods. Real-time viscosity feedback loops compress new grade qualification timelines from months to weeks.
The EU Green Deal's plastics recycling mandates compel compounders to certify post-industrial and post-consumer content thresholds through mass-balance accounting. ECHA's evolving REACH annex restrictions on additive substances force reformulation of flame-retardant and UV-stabilized grades. European automotive OEMs now require third-party verification of recycled content claims in supplier scorecards.
Consolidated procurement functions at multinational packaging groups are disintermediating regional distributors through direct mill contracts with integrated propylene producers. Large beverage brand owners negotiate polymer supply agreements spanning multiple continents, centralizing specification authority at headquarters while decentralizing logistics execution. This concentration is most visible in North American rigid container markets where three buyers account for majority homopolymer volume.
Polypropylene and Polypropylene Composites Market Segmentation
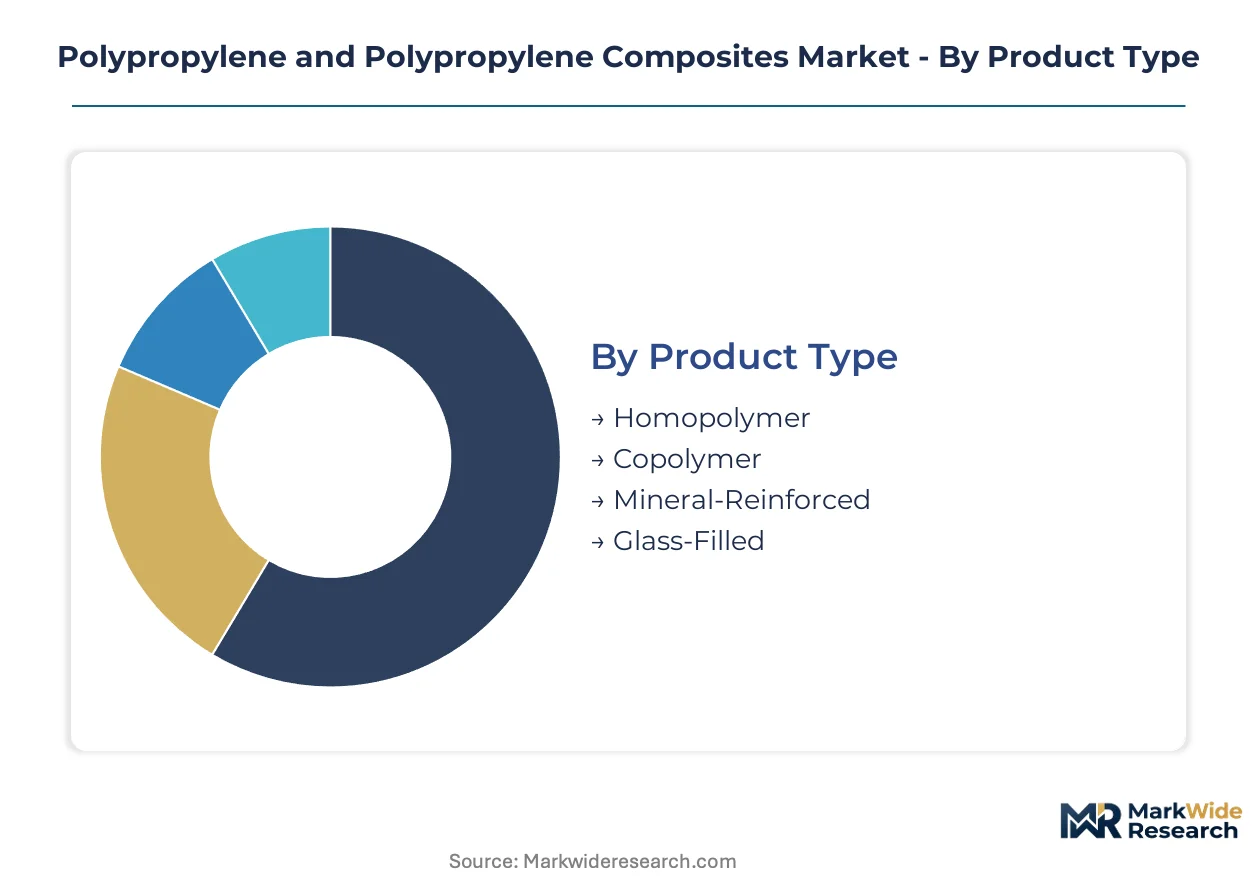
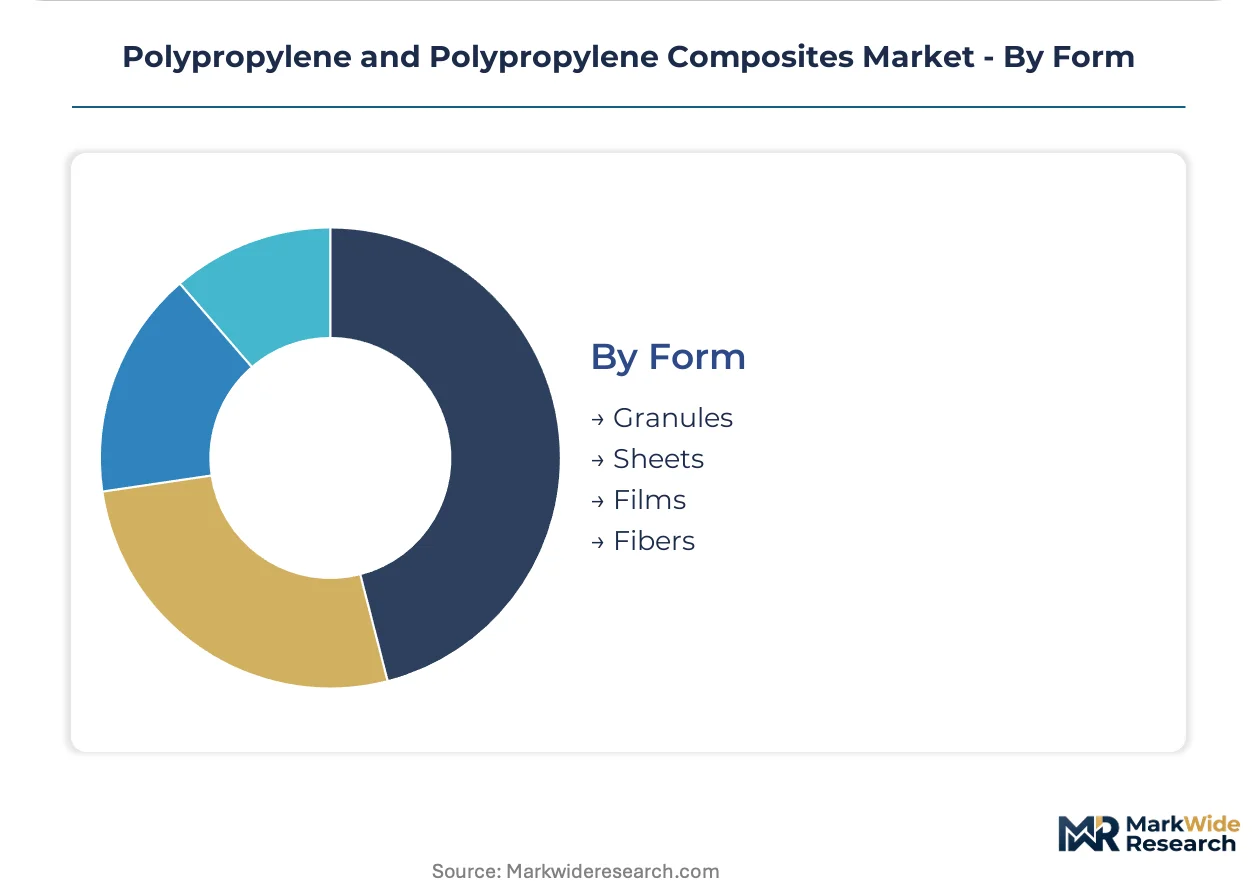
Polypropylene and polypropylene composites fragment across four distinct classification axes that determine specification authority, margin capture, and supply chain configuration. Product type governs mechanical properties and thermal performance. Application verticals dictate regulatory exposure and recycled-content thresholds. End-user industries drive volume scale versus customization intensity. Form factor determines conversion economics and logistics density.
Product Type:
Mature commodity grades dominate tonnage while reinforced compounds concentrate value pools through performance differentiation.
- Homopolymer:Isotactic polypropylene homopolymer delivers maximum stiffness and heat resistance through high crystallinity. Rigid packaging converters in China's Yangtze River Delta corridor consume bulk volumes for thin-wall injection molded containers where clarity and dimensional stability command specification.
- Glass-Filled:Long-fiber thermoplastic compounds achieve tensile moduli exceeding 5 GPa with 40% glass loading. Automotive Tier-1 suppliers substitute these grades for painted steel in bumper beams and instrument-panel carriers, concentrating procurement with compounders mastering impregnation technology without fiber attrition.
- Copolymer:Random and impact copolymers incorporate ethylene to balance clarity against low-temperature toughness. Medical device molders specify these grades for syringe barrels and diagnostic cassettes requiring US FDA compliance.
- Mineral-Reinforced:Talc and calcium carbonate filled compounds reduce material cost and improve dimensional stability. Appliance housings and automotive under-bonnet components utilize these grades where moderate stiffness suffices.
Homopolymer retains volume leadership; Glass-Filled holds the steepest expansion curve.
Application:
Cost tier stratification separates high-volume packaging from specification-intensive automotive procurement.
- Packaging:Rigid containers, flexible films, and caps/closures consume homopolymer and random copolymer grades. China's NMPA circular-economy directives mandate post-consumer recycled content thresholds, redirecting compounder investments toward chemical recycling feedstock integration for food-contact compliance.
- Automotive:Lightweighting programs substitute glass-reinforced compounds for metal in structural and semi-structural components. Tier-one suppliers achieve 15-25% mass reduction in bumper systems and front-end modules versus painted steel assemblies.
- Consumer Goods:Housewares, furniture, and sporting equipment utilize copolymer and mineral-filled grades. India's PLI scheme for auto components indirectly supports adjacent molding capacity serving consumer durables.
- Textiles:Fiber-grade homopolymer feeds spunbond nonwovens and staple fiber operations. Hygiene product manufacturers specify narrow melt-flow distribution resins for consistent fiber diameter control.
Packaging commands absolute tonnage; Automotive generates the highest value per kilogram.
End User:
Customer type determines specification complexity and contract duration across procurement relationships.
- Manufacturing:Injection molders and extrusion operators purchase resin through direct mill contracts or distributor channels. Consolidated procurement functions at multinational packaging groups are disintermediating regional distributors.
- Construction:Geotextiles, vapor barriers, and piping systems demand UV-stabilized and flame-retardant grades. REACH registration requirements under ECHA jurisdiction constrain additive selection for European infrastructure projects.
- Agriculture:Twine, netting, and greenhouse films prioritize cost minimization over performance. Short product lifecycles favor mechanically recycled feedstock integration where property degradation is acceptable.
- Electronics:Connectors, housings, and cable insulation require halogen-free flame retardancy and precise dimensional tolerances. EU RoHS and REACH annex restrictions force continuous reformulation of additive packages.
Manufacturing absorbs the largest resin volumes; Electronics imposes the most stringent qualification protocols.
Form:
Supply concentration varies with logistics density and conversion step requirements.
- Granules:Pelletized resin feeds injection molding and extrusion operations. Integrated propylene-to-compound producers achieve lowest delivered cost through captive feedstock.
- Films:Cast and biaxially oriented polypropylene serve flexible packaging and labeling. China's MEE dual carbon emissions caps on steam crackers elevate bio-based pathway economics for film-grade production.
- Sheets:Extruded and thermoformed sheet serves rigid packaging and industrial applications. Thickness tolerance requirements favor compounders with advanced rheology control.
- Fibers:Melt-spun filaments and staple fiber supply textiles and nonwovens. Fiber-grade specifications demand narrow molecular weight distribution achievable through Borstar proprietary reactor technology.
Granules dominate merchant trade; Films concentrate value-add at converter level.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE's dual carbon emissions caps on Chinese steam crackers anchor the dominant geography, redirecting capital toward efficiency retrofits and renewable feedstock qualification across East Asia's petrochemical corridor.
China
Yangtze River Delta petrochemical clusters consume bulk homopolymer volumes for thin-wall rigid packaging. NMPA circular-economy directives mandate post-consumer recycled content thresholds under updated GB standards. Shanghai and Ningbo compounders achieve lowest delivered costs through captive propylene-to-compound operations.
United States
Automotive Tier-1 molders source glass-filled compounds for bumper beam substitution programs. EPA and OSHA jointly govern resin handling and volatile organic compound limits at compounding facilities. ExxonMobil's Baton Rouge polymerization complex sustains captive feedstock advantage for North American automotive compounding.
Germany
REACH registration requirements and EU Green Deal plastics recycling mandates compel producers to certify post-industrial content thresholds. ECHA dossier costs create asymmetric barriers for smaller compounders serving automotive OEMs. Bavarian compounders master long-fiber impregnation technology for instrument-panel carriers.
Saudi Arabia
Export-oriented derivative production supplies glass-reinforced compounds to European automotive platforms. SABIC anchors Middle Eastern supply through its Yanbu derivatives hub. Integrated propylene operations achieve cost positions that attract downstream molding investments from tier-one suppliers.
Japan
Medical device molders specify random copolymers for syringe barrels requiring PMDA compliance. METI guidelines on plastic resource circulation elevate chemical recycling pathway economics. Osaka-based compounders serve diagnostics manufacturers with narrow melt-flow distribution resins.
Polypropylene and Polypropylene Composites Market Competitive Landscape
Integrated petrochemical majors and specialized compounders split the market along feedstock control versus formulation expertise lines. The vendor base concentrates around reactor technology differentiation and long-fiber impregnation capability. Two archetypes dominate: upstream-integrated producers with captive propylene supply, and downstream compounders mastering fiber length distribution. Competitive moves center on backward integration into propylene production and direct mill contracts bypassing distributor networks.
Within the integrated-major tier, LyondellBasell Industries Holdings B.V. and ExxonMobil Chemical Company exemplify upstream-integrated positioning through polymerization complex ownership. SABIC anchors Middle Eastern supply architecture. Among specialized compounders, Kingfa Sci. & Tech. Co., Ltd. occupies a position representing Asia-Pacific formulation expertise, while Borealis AG sits within the European technology-differentiated segment through proprietary reactor systems.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| ExxonMobil Chemical Company |
| SABIC |
| Borealis AG |
| Sumitomo Chemical Co., Ltd. |
| Kingfa Sci. & Tech. Co., Ltd. |
| Mitsui Chemicals, Inc. |
| Trinseo |
| Washington Penn Plastics |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta petrochemical clusters concentrate integrated propylene-to-compound capacity, translating captive feedstock control into pricing leverage over merchant compounders serving downstream packaging converters. This geographic supply density enables integrated producers to undercut naphtha-dependent competitors when olefin spreads tighten, while distributor networks face margin compression from direct mill contracts.
Pricing Analysis
East China commands a 12-15% delivered-cost advantage over European and North American supply basins due to integrated steam cracker operations. Three-tier pricing structure across premium, standard, and economy levels separates long-fiber glass-reinforced compounds from mineral-filled grades and commodity homopolymer. Cost compression in standard-tier mineral-filled compounds is intensifying because India's PLI scheme for auto components attracts new compounding capacity. Tier-one automotive OEMs exhibit lowest price sensitivity due to qualification barriers, while agricultural twine producers remain most exposed to spot resin volatility.
Supply Chain Analysis
Export-control regimes on advanced twin-screw extrusion technology limit long-fiber impregnation capability transfer to emerging compounders outside established manufacturing zones. Supply concentrates in China, Saudi Arabia, and the United States, with each hub drawing from distinct propylene feedstock economics—coal-to-olefins, ethane cracking, and naphtha steam cracking respectively. Raw material dependencies span propylene monomer, glass fiber rovings, and mineral fillers sourced from dedicated mining operations. Single-source vulnerability around Borstar proprietary reactor technology for narrow melt-flow distribution resins creates specification lock-in for thin-wall packaging grades. Distribution runs through direct mill contracts consolidating procurement authority at multinational beverage and automotive OEM headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement functions at multinational packaging groups and automotive OEMs, fragmenting regional distributor economics as direct resin-to-molder contracts capture margin pools previously held by polymer traders.
For Market Incumbents: Harden long-fiber impregnation expertise barriers by recruiting process engineers capable of maintaining fiber length distribution without thermal degradation, while securing backward integration into propylene production through efficiency retrofits under China's MEE dual carbon emissions caps. Engineering thermoplastic substitution from polyamide and PBT compounds threatens under-hood applications above 150°C service temperatures, making certification investment in automotive qualification protocols the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme for electric vehicle battery housings and thermal management modules, where domestic content requirements create localized compounding demand absent entrenched supplier relationships. Chemical recycling feedstock integration for post-consumer polypropylene recovery represents the most penetrable white-space, given NMPA circular-economy mandates and traceability system gaps among incumbent compounders. A go-to-market angle anchored in auditable chain-of-custody certification bypasses ERP infrastructure limitations constraining established players. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders mastering long-fiber technology for automotive structural substitution programs, where multi-year platform contracts lock in volume visibility. Over the projection horizon, viability hinges on feedstock passporting compliance as cross-border shipment rules tighten. Acquisition targets should display integrated propylene supply or proprietary reactor technology differentiation. The signal to watch is ECHA REACH annex restriction timelines on flame-retardant additive reformulation, which would force accelerated R&D spend among unprepared compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Production | Captive feedstock economics under China's MEE dual carbon caps secure margin protection against naphtha volatility. |
| Long-Fiber Impregnation Capacity Expansion | Automotive Tier-1 substitution programs for painted steel bumper beams concentrate volume with technology specialists. |
| Chemical Recycling Feedstock Partnership | NMPA post-consumer content mandates redirect capital toward auditable recovery infrastructure for food-contact compliance. |
| Direct Mill Contract Establishment | Bypassing distributor networks captures margin pools as multinational packaging groups centralize procurement authority. |
| Bio-Based Propylene Pathway Qualification | EU Green Deal carbon border adjustments elevate renewable naphtha economics for European automotive supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive Tier-1 procurement directors, packaging converter plant managers, compounder technical R&D leads, and petrochemical derivatives traders. Secondary validation drew from customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings of integrated majors, and GB standards documentation from China's SAMR. Bottom-up volume modeling across grade tiers and end-use segments was triangulated against top-down propylene derivative demand forecasts.
Calibration against historical capacity utilization rates and announced steam cracker expansion timelines anchored the analytical framework. Segmentation dimensions modeled include product type hierarchy, application vertical cost tiers, end-user procurement complexity, and regional production hub feedstock economics. CAGRs were derived from elasticity-adjusted demand projections and substitution elasticity estimates for glass-reinforced compounds displacing painted steel. Industry-specific forecast inputs incorporated automotive lightweighting program announcements and NMPA circular-economy directive implementation schedules.
Sensitivities concentrate around naphtha-to-polymer margin compression events, REACH registration burden escalations, and dual carbon compliance timeline accelerations in China. Forecasts reflect documented assumptions on olefin spread trajectories and recycled-content verification protocol maturation. Material shifts in EU carbon border adjustment mechanisms or MEE emissions enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
CFRTP Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Plastic Composites Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Core Material for Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Pultrusion Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Pcb Laminate Materials Market