

High Performance Carbon Fiber Precursor Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Carbon Fiber Precursor Market Insights
Steel is pivoting toward displacement in commercial aviation primary structures as carbon fiber reinforced polymers demonstrate superior fatigue resistance and weight reduction. Toray Industries leverages backward integration into acrylonitrile feedstock to secure precursor cost stability. Mitsubishi Chemical anchors its position through proprietary high-modulus pitch-based precursor chemistry for satellite and defense applications. Hexcel Corporation competes via qualification lock-ins with Boeing and Airbus supply chains.
High performance carbon fiber precursor denotes a highly purified polymeric feedstock, typically polyacrylonitrile with comonomer content below 10 percent, engineered to achieve carbon yields exceeding 50 percent through controlled oxidative stabilization and carbonization. The material serves as the structural backbone for ultra-high-strength carbon fibers used in load-bearing applications where stiffness-to-weight ratios determine system performance. Polyacrylonitrile precursor dominates commercial volumes due to established tensile strength translation from fiber to composite, while pitch-based grades command premium positioning in satellite bus structures and optical benches where modulus extremes justify higher processing costs. Wet spinning technology sustains the bulk of aerospace-grade output, though gel spinning is gaining traction for ballistic protection and specialized industrial ropes.
REACH registration requirements in Europe and EPA emissions protocols in the United States constrain solvent recovery and acrylonitrile handling practices at precursor plants, elevating capital thresholds for new entrants. Japan's METI designates carbon fiber as a strategically controlled material under export monitoring frameworks, affecting cross-border supply planning for defense contractors. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate qualification timeline risks and feedstock sourcing constraints.
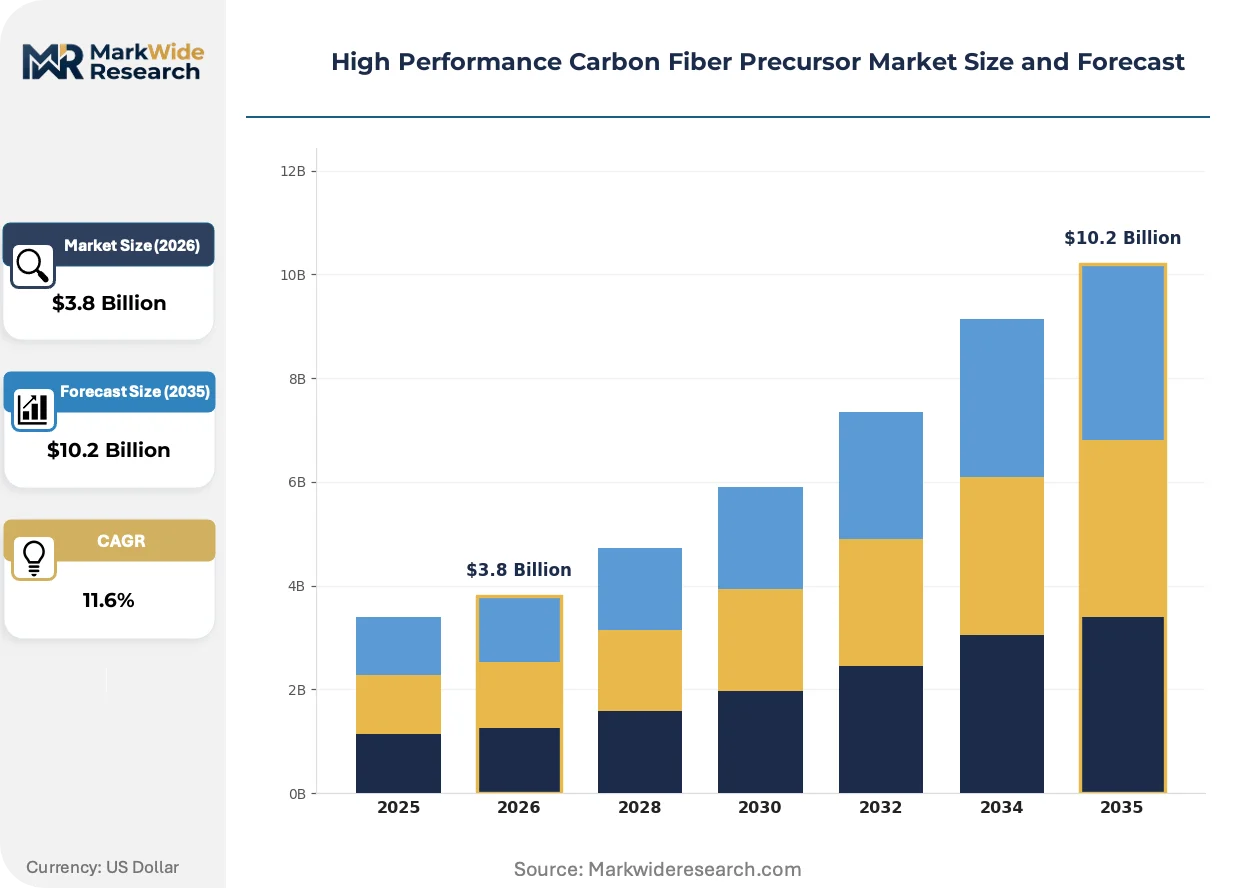
Market Dynamics
Aerospace OEM qualification timelines and REACH carbon-intensity benchmarks are compressing supplier margins while concentrating procurement among vertically integrated PAN-to-fiber producers with captive acrylonitrile supply.
Growth Catalysts
- EU Green Deal carbon-intensity benchmarks:Precursor producers achieving sub-50 kg CO2 per kg fiber output gain preferential qualification status with Airbus and Safran procurement teams.
- Commercial aviation primary structure substitution:Boeing 787 and Airbus A350 program ramp-ups sustain PAN precursor offtake commitments through 2030.
- Defense satellite bus modulus requirements:Pitch-based precursor demand from Northrop Grumman and Lockheed Martin space divisions accelerates high-modulus fiber qualification cycles.
Market Restraints
- Acrylonitrile feedstock cost volatility:Propylene-ammonia price correlation exposes non-integrated precursor producers to margin compression during petrochemical cycle peaks.
- Japanese supply concentration risk:METI export monitoring frameworks and Toray-Mitsubishi duopoly control over aerospace-grade PAN precursor create single-source vulnerability for European and US fiber producers.
- Carbon yield ceiling in wet spinning:Conventional PAN precursor chemistry plateaus near 55% carbon yield, limiting downstream fiber cost reduction potential against theoretical gel spinning pathways.
Strategic Opportunities
- US Inflation Reduction Act clean manufacturing credits:Domestic precursor production facilities in South Carolina and Texas qualify for production tax credits tied to carbon intensity thresholds.
- Urban air mobility airframe demand:eVTOL manufacturers including Joby Aviation and Archer Aviation specify thermoplastic-compatible intermediate-modulus precursors for rapid-forming fuselage structures.
- Hydrogen pressure vessel liner integration:Type IV composite tank producers seek precursor grades optimized for filament winding compatibility with high-density polyethylene liner adhesion.
Industry Challenges
- Oxidative stabilization oven operator skill scarcity:Temperature profiling expertise for PAN tow conversion requires 18-24 month training cycles that outpace workforce expansion in US Gulf Coast and German precursor plants.
- FAA-EASA dual certification timeline compression:New precursor grades face 36-48 month qualification windows for primary structure applications, locking working capital in pre-production inventory.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Carbon Fiber Precursor Market Trends and Innovations
Precursor manufacturing is pivoting from commodity chemical production toward materials engineering disciplines where carbon yield, defect density, and tow uniformity determine downstream fiber performance.
Gel spinning technology is expanding into ballistic protection and industrial rope applications where ultra-high molecular weight polyethylene faces modulus limitations. Defense contractors in the US and South Korea are qualifying gel-spun PAN precursors for body armor inserts requiring specific energy absorption above 100 J/kg. This expansion is compressing the addressable market for conventional wet-spun grades in non-aerospace segments.
REACH authorization requirements for acrylonitrile handling and solvent recovery are forcing European precursor plants to retrofit closed-loop dimethyl sulfoxide purification systems. ECHA substance evaluation protocols now require full lifecycle carbon footprint documentation for precursor imports. German and French fiber producers are responding by localizing precursor supply contracts within EU customs territory.
Long-term offtake agreements are displacing spot market purchasing for aerospace-grade precursor. Tier-1 composite manufacturers including Spirit AeroSystems and GKN Aerospace now contract directly with acrylonitrile producers to secure precursor cost visibility through 2028. This pattern is most visible in US Southeast manufacturing corridors where Boeing and Airbus final assembly concentration drives supplier co-location decisions.
High Performance Carbon Fiber Precursor Market Segmentation
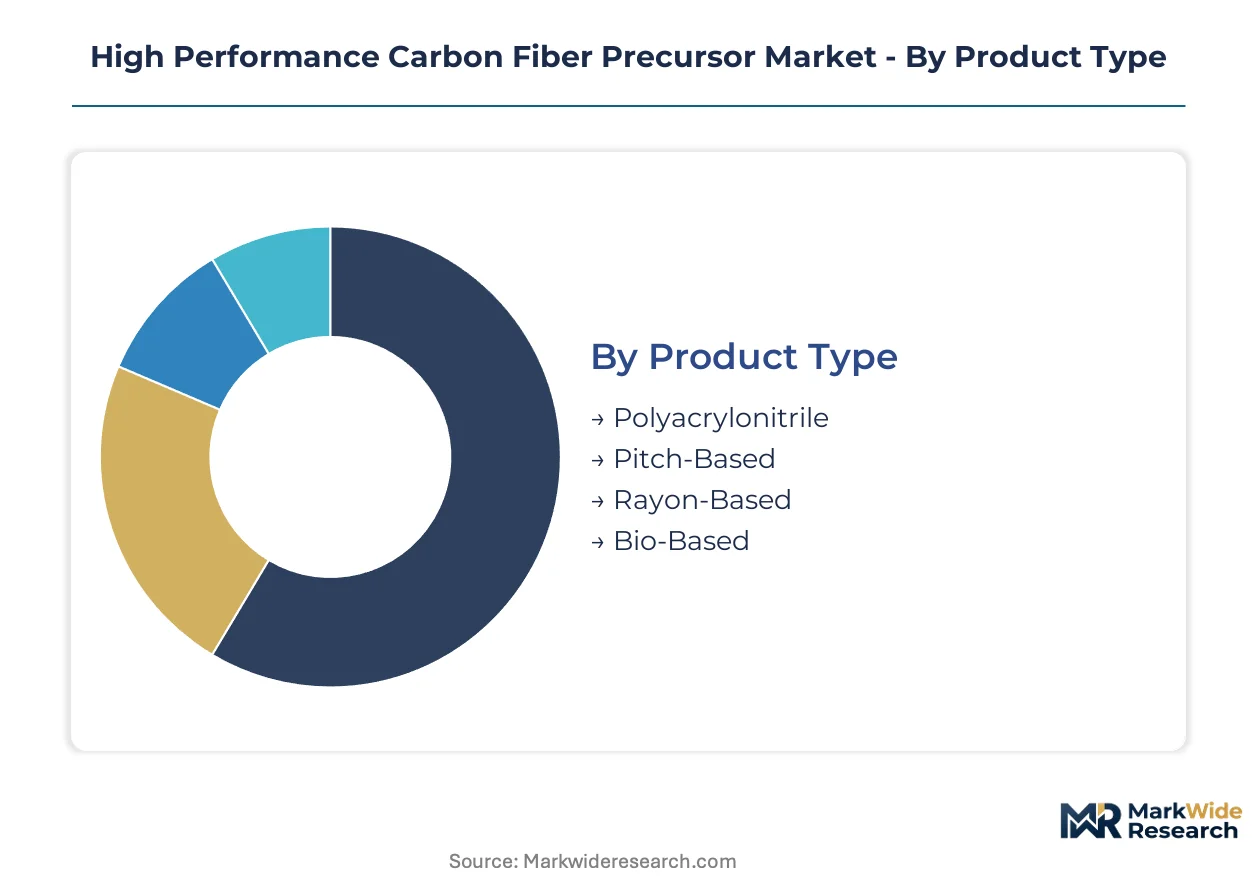
Carbon fiber precursor segmentation reflects divergent technical requirements across aerospace qualification pathways and industrial cost-performance tradeoffs. Precursor chemistry and spinning methodology determine carbon yield ceilings and downstream fiber modulus ranges that lock suppliers into specific end-use verticals.
Product Type:
Polymer feedstock chemistry governs carbon yield potential, oxidative stabilization energy requirements, and ultimate fiber mechanical properties.
- Polyacrylonitrile:Comonomer-modified acrylonitrile polymers with controlled tacticity deliver carbon yields exceeding 50 percent through oxidative ladder formation. Boeing 787 and Airbus A350 primary structure programs sustain aerospace-grade PAN precursor offtake commitments through qualification-locked supply agreements.
- Pitch-Based:Mesophase pitch derived from petroleum or coal tar feedstocks achieves modulus extremes above 500 GPa through graphitic crystal alignment. Northrop Grumman and Lockheed Martin satellite bus structures drive demand for ultra-high-modulus pitch precursor grades where stiffness-to-mass ratios dominate system design.
- Rayon-Based:Cellulosic precursor chemistry serves specialized ablative thermal protection applications with lower carbon yields but controlled char morphology.
- Bio-Based:Lignin-derived and cellulose-based alternatives target EU Green Deal carbon-intensity benchmarks for precursor production with reduced petrochemical feedstock dependency.
Polyacrylonitrile leads on scale; bio-based precursors lead on momentum.
Technology:
Spinning methodology determines tow uniformity, defect density, and achievable molecular orientation prior to carbonization.
- Wet Spinning:Coagulation bath precipitation of PAN dope solutions produces aerospace-grade tow with established tensile strength translation. German and Japanese precursor plants sustain the bulk of commercial aviation-qualified output through dimethyl sulfoxide solvent recovery systems.
- Gel Spinning:Ultra-high molecular weight PAN processing achieves ballistic-grade energy absorption above 100 J/kg for body armor inserts. US and South Korean defense contractors accelerate qualification cycles for gel-spun precursors displacing conventional wet-spun grades in protection applications.
- Dry Spinning:Solvent evaporation without liquid coagulation reduces washing requirements for selected industrial fiber grades.
- Melt Spinning:Solvent-free thermoplastic precursor routes target cost reduction for automotive and pressure vessel applications where modulus requirements permit reduced performance tiers.
Wet spinning leads on scale; gel spinning leads on momentum.
Application:
End-use performance specifications dictate precursor purity thresholds, tow count requirements, and composite processing compatibility.
- Aerospace Components:Primary structure applications demand precursor carbon yields above 55 percent with defect densities below 0.1 percent to achieve FAA-EASA dual certification for wing spars and fuselage barrels.
- Wind Turbine Blades:Intermediate-modulus precursor grades balance stiffness and cost for 80-meter-plus blade spar caps requiring fatigue resistance across 25-year design lifetimes.
- Sports Equipment:Recreational carbon fiber applications utilize standard-modulus precursors with relaxed specification tolerances for bicycle frames and hockey sticks.
- Marine Hydrodynamics:Corrosion-resistant composite hulls and mast structures specify precursor grades compatible with vinyl ester and epoxy resin systems.
Aerospace components lead on scale; wind turbine blades lead on momentum.
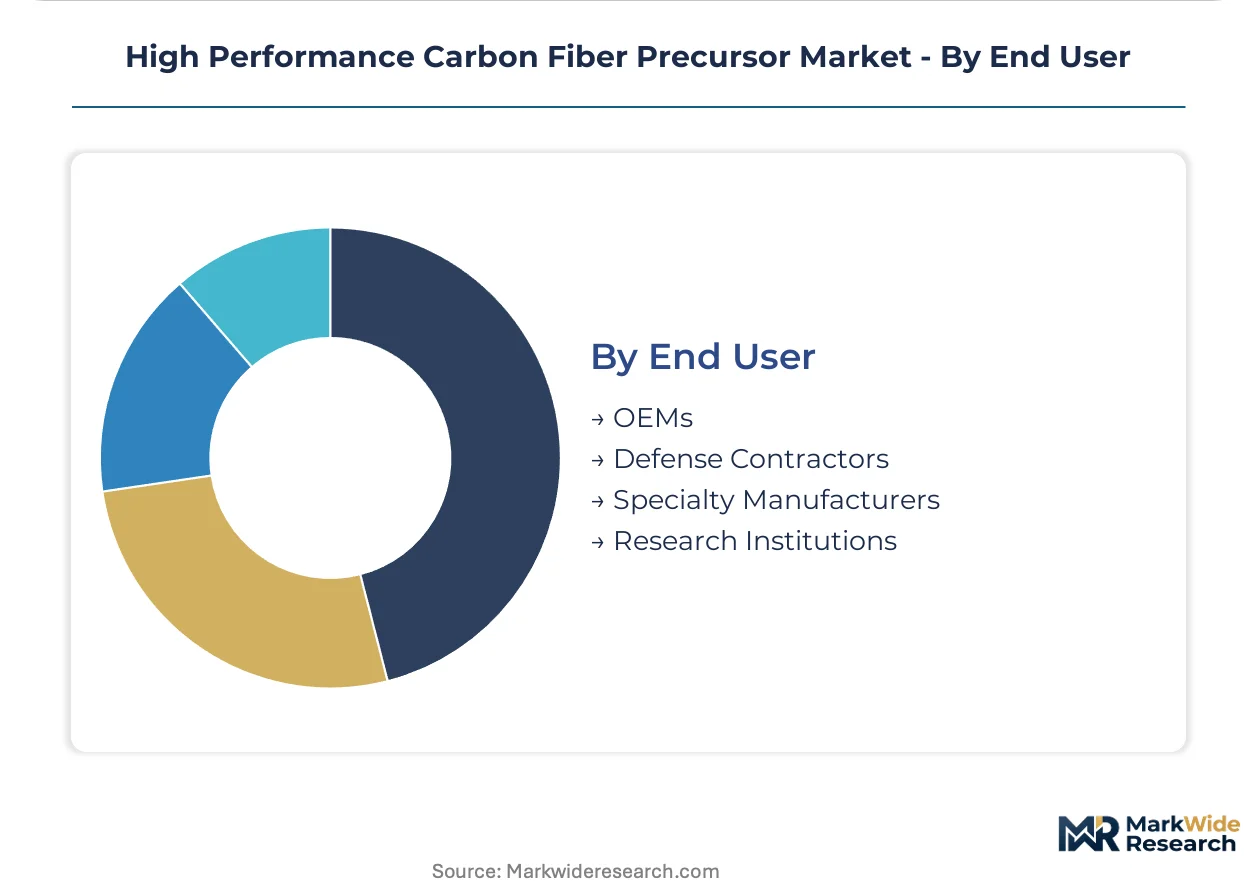
End User:
Customer procurement patterns range from multi-year qualification-locked agreements to spot purchasing for developmental programs.
- OEMs:Boeing, Airbus, and Tier-1 aerostructures manufacturers contract directly for precursor cost visibility through 2028, co-locating supplier facilities near final assembly concentrations in Washington State, South Carolina, and Toulouse.
- Defense Contractors:Classified satellite and hypersonic vehicle programs drive pitch-based precursor demand with METI export monitoring compliance requirements for Japanese-sourced materials.
- Specialty Manufacturers:Industrial composite producers purchase standard-modulus precursors through distributor networks for pressure vessels and automotive applications.
- Research Institutions:National laboratories and university consortia source developmental precursor grades for next-generation carbon fiber chemistry validation.
OEMs lead on scale; defense contractors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's integrated PAN-to-carbon fiber production corridors anchor global precursor supply, with Toray Industries and Mitsubishi Chemical maintaining captive acrylonitrile supply chains that insulate against feedstock volatility. European REACH carbon-intensity benchmarks and US Inflation Reduction Act manufacturing credits are reshaping regional competitive positioning.
United States
Boeing 787 and Airbus A350 program ramp-ups sustain PAN precursor offtake commitments through 2030. EPA emissions protocols constrain solvent recovery practices at precursor plants in South Carolina and Texas. The US Southeast manufacturing corridor sees supplier co-location decisions driven by final assembly concentration near Charleston and Mobile.
Japan
METI designates carbon fiber as a strategically controlled material under export monitoring frameworks affecting cross-border supply planning. Japanese precursor producers achieve preferential qualification status with aerospace OEMs through sub-50 kg CO2 per kg fiber output benchmarks. The Chubu region around Nagoya maintains integrated production corridors linking acrylonitrile feedstock to fiber conversion.
Germany
ECHA substance evaluation protocols require full lifecycle carbon footprint documentation for precursor imports. German fiber producers localize precursor supply contracts within EU customs territory to comply with REACH authorization requirements. The North Rhine-Westphalia industrial cluster retrofits closed-loop dimethyl sulfoxide purification systems at precursor plants.
China
Domestic wind turbine blade manufacturers drive intermediate-modulus precursor demand for 80-meter-plus blade spar caps. The country's national chemical regulator enforces emissions standards for acrylonitrile handling at precursor facilities. The Jilin province chemical fiber cluster expands production capacity to serve aerospace and industrial composite applications.
South Korea
Defense contractors accelerate qualification cycles for gel-spun precursors displacing conventional wet-spun grades in ballistic protection applications. The national industrial technology ministry supports carbon fiber precursor R&D through strategic materials programs. The Busan-Ulsan manufacturing corridor develops precursor grades for hydrogen pressure vessel liner integration.
High Performance Carbon Fiber Precursor Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and qualification-locked supply agreements. The vendor base concentrates among vertically integrated PAN-to-fiber producers with captive acrylonitrile supply, while non-integrated players face margin compression during petrochemical cycle peaks. Three archetypes dominate: backward-integrated Japanese conglomerates, European specialty chemical producers with REACH-compliant systems, and emerging Asian fabricators scaling for industrial-grade output. Competitive moves center on long-term offtake agreements with aerospace OEMs and co-location decisions near final assembly concentrations.
Within the backward-integrated tier, Toray Industries and Mitsubishi Chemical exemplify the Japanese model of controlling acrylonitrile feedstock through upstream chemical operations. Hexcel Corporation occupies a position representing North American qualification lock-ins with Boeing and Airbus supply chains. These three anchors illustrate how geographic origin and customer access patterns stratify competitive positioning across premium aerospace-grade and industrial-grade precursor segments.
| Leading Market Players |
|---|
| Toray Industries |
| Mitsubishi Chemical |
| Teijin |
| Hexcel Corporation |
| SGL Carbon |
| Hyosung Advanced Materials |
| AKSA |
| Jilin Chemical Fiber |
| Formosa Plastics Corporation |
| Others |
Pricing and Supply Chain Analysis
Backward integration into acrylonitrile feedstock anchors both supply security and pricing power for Japanese producers, insulating Toray Industries and Mitsubishi Chemical from propylene-ammonia volatility that compresses margins at non-integrated European and North American competitors.
Pricing Analysis
Acrylonitrile cost pass-through dominates precursor pricing, with contract-based long-term offtake agreements displacing spot purchasing as Boeing and Airbus Tier-1 suppliers seek cost visibility through 2028. Price differentiation hinges on carbon yield certification and REACH compliance tier, with EU Green Deal sub-50 kg CO2 per kg fiber benchmarks commanding premium positioning. Cost compression in standard-modulus grades intensifies as Chinese industrial producers scale wet-spun output for wind turbine applications. Defense contractors exhibit lowest price sensitivity due to satellite bus modulus requirements, while automotive pressure vessel manufacturers face acute margin pressure from high-density polyethylene liner adhesion specifications.
Supply Chain Analysis
Solvent recovery and dimethyl sulfoxide purification system refurbishment flows constrain European precursor plant throughput as ECHA substance evaluation protocols tighten closed-loop requirements. Raw material dependencies center on petroleum-derived acrylonitrile, comonomer additives for tacticity control, and mesophase pitch feedstocks for ultra-high-modulus grades. Geographic concentration in Japan, Germany, and the US Southeast creates single-source vulnerability under METI export monitoring frameworks. Distribution runs through qualification-locked supply agreements with aerospace OEMs rather than distributor networks, with logistics chokepoints at oxidative stabilization oven capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through carbon yield ceiling breakthroughs in gel spinning pathways, enabling premium-tier positioning for ballistic protection and hydrogen pressure vessel applications.
For Market Incumbents: To counter acrylonitrile feedstock cost volatility, Toray Industries and Mitsubishi Chemical should deepen captive supply of propylene derivatives while expanding oxidative stabilization oven capacity in South Carolina to capture US Inflation Reduction Act clean manufacturing credits. Certification investment in FAA-EASA dual qualification pathways locks out emerging Asian competitors from primary structure procurement. For New Entrants and Emerging Players: Enter via bio-based lignin-derived precursor chemistry targeting EU Green Deal carbon-intensity benchmarks, where ECHA authorization requirements disadvantage petrochemical incumbents. The most penetrable white-space sits in thermoplastic-compatible intermediate-modulus grades for eVTOL rapid-forming fuselage structures, with go-to-market through Joby Aviation and Archer Aviation supplier qualification programs. For Investors and Strategic Acquirers: Roll-up economics work for regional Japanese precursor specialists with METI export licenses because aerospace-grade PAN qualification timelines create defensive moats against new capacity. Long-term viability centers on hydrogen pressure vessel and urban air mobility demand trajectories. Watch for gel spinning technology licensing announcements from South Korean defense contractors as inflection indicators for next-generation ballistic protection market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Toray Industries secures feedstock cost stability against propylene-ammonia volatility cycles. |
| Long-term Supply Agreement | Spirit AeroSystems contracts directly with precursor producers through 2028 for Boeing 787 program visibility. |
| Green Manufacturing Transition | German producers retrofit closed-loop DMSO systems to satisfy ECHA substance evaluation protocols. |
| Capacity Expansion | South Carolina facilities target US Inflation Reduction Act production tax credit thresholds. |
| Joint Venture | Busan-Ulsan corridor partnerships develop filament winding-compatible grades for Type IV hydrogen tanks. |
Research Methodology
Direct dialogue with precursor plant managers, aerospace OEM procurement leads, ECHA regulatory affairs specialists, and oxidative stabilization oven operators grounded qualitative insights, validated against customs trade data, SEC 10-K filings from Hexcel and Toray, METI export monitoring disclosures, and REACH authorization databases. Bottom-up capacity modeling triangulated with top-down carbon fiber composite demand forecasts from Boeing and Airbus program ramp-up schedules.
Segment-level outputs across the analysis window reflect polymer chemistry type, spinning methodology, and end-use qualification tier, with CAGR derivation anchored in aerospace OEM delivery schedules and wind turbine blade length trajectories. Key inputs included acrylonitrile spot price correlation models and EU Green Deal carbon-intensity benchmark adoption curves.
Inputs from ECHA substance evaluation protocols and METI export license disclosures were available through the study window; gaps in classified defense satellite bus procurement volumes introduce uncertainty bands in pitch-based precursor forecasts. Practitioners should monitor gel spinning technology qualification announcements and eVTOL manufacturer supplier selection timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.