
 Thermoset Composites Market | 2026-2036
Thermoset Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoset Composites Market Outlook
Specialty chemical distribution networks serving wind blade and aerospace tiers is reshaping how resin systems reach fabrication floors in the Thermoset Composites Market. Owens Corning leverages its captive glass fiber supply to anchor North American wind energy demand. Toray Industries dominates carbon fiber prepreg channels for commercial aviation. Hexcel Corporation specializes in toughened epoxy formulations that sustain qualification thresholds for primary aircraft structures.
Thermoset composites are fiber-reinforced polymers cured through irreversible cross-linking reactions, typically achieving glass transition temperatures above 150°C and tensile moduli exceeding 40 GPa depending on reinforcement architecture. These materials serve structural applications where dimensional stability under sustained load and thermal exposure outweighs recyclability concerns. Epoxy resin systems lead aerospace and high-performance industrial segments due to superior adhesion and environmental resistance. Phenolic formulations occupy flame-retardant transportation and construction niches where regulatory smoke toxicity standards are stringent. Prepreg form factors command premium positioning in automated fiber placement workflows for complex contoured parts.
EPA oversight of styrene emissions and OSHA permissible exposure limits govern US laminating operations, while REACH registration requirements and the EU Green Deal chemical sustainability framework constrain monomer selection across European supply chains. EASA airworthiness certification protocols and FAA material qualification standards dictate resin system approval timelines for commercial aviation applications. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions and emerging bio-based epoxy certification pathways that could redraw supplier competitiveness across end-use segments.
Market Dynamics
Epoxy prepreg qualification timelines for primary aircraft structures now dominate supplier resource allocation, compressing development bandwidth for secondary applications while aerospace OEMs consolidate qualified vendor pools around fewer resin system platforms.
Growth Catalysts
- Wind blade length escalation:Turbine OEMs in China's Jiangsu and Guangdong provinces specify carbon-glass hybrid spar caps requiring toughened vinyl ester systems that sustain fatigue loads across 25-year service lives.
- REACH chemical sustainability mandates:ECHA registration requirements for novel bio-based hardeners accelerate reformulation investments, opening qualification pathways for lignin-derived curing agents in European automotive structural components.
- Automated fiber placement:Robotic deposition systems for complex contoured aerospace parts demand prepreg form factors with precise tack and drape characteristics, pulling resin system design toward controlled rheology platforms.
Market Restraints
- Petrochemical feedstock volatility:Bisphenol A and epichlorohydrin price swings compress formulation margins, forcing long-term supply agreements that lock processors into single-source aromatics.
- Carbon fiber supply concentration:Toray, Hexcel, and SGL Carbon control 70% of aerospace-grade precursor capacity, creating bottleneck risk for prepreg manufacturers without backward fiber integration.
- Thermoset recyclability limitations:Irreversible cross-linking prevents mechanical reprocessing, exposing wind blade operators to landfill restrictions and extended producer liability frameworks in Germany and the Netherlands.
Strategic Opportunities
- India defense indigenization:DRDO procurement mandates for composite airframe structures create first-mover advantage for epoxy system suppliers establishing local mixing and qualification laboratories.
- Out-of-autoclave curing:Oven-curable prepreg systems eliminate autoclave capital intensity, enabling tier-two aerospace fabricators in Italy and Spain to bid on secondary structure contracts previously reserved for prime-tier suppliers.
- EU Green Deal circularity incentives:Chemical recycling pilot programs for thermoset composites in the Netherlands and Belgium attract venture funding for solvolysis and pyrolysis scale-up, potentially unlocking feedstock recovery economics.
Industry Challenges
- Qualification timeline compression:FAA and EASA material approval protocols for new resin systems require 18-36 month test matrices, delaying revenue recognition for reformulated low-toxicity hardeners.
- Process engineer scarcity:Automated fiber placement programming and cure cycle optimization expertise concentrates at aerospace primes, constraining expansion at independent fabrication shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoset Composites Market |
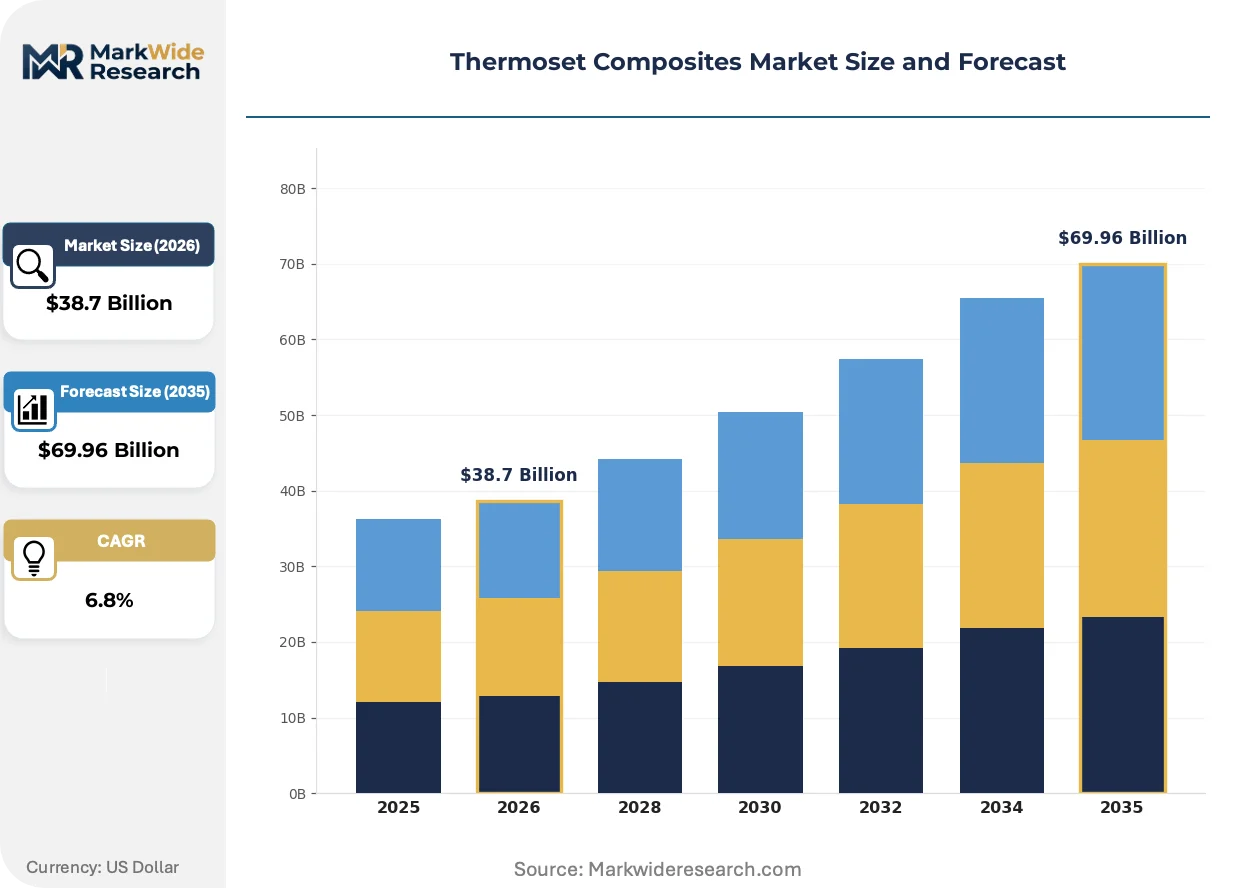
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Polyurethane, Acrylic Application: Aerospace, Automotive, Recreational, Electronics End User: Manufacturers, Suppliers, Distributors, Contractors Form: Sheet, Fiber, Rod, Prepreg |
| Companies Covered | Owens Corning, Toray Industries, Hexcel Corporation, Teijin Limited, SGL Carbon, Huntsman International, PPG Industries, Mitsubishi Chemical, China Jushi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoset Composites Market Strategic Shifts
Digital thread integration across resin formulation, prepreg manufacturing, and part fabrication is compressing quality assurance cycles while generating proprietary data assets that reshape supplier-customer relationships.
Digital twin platforms for cure cycle simulation are virtualizing thermal management optimization that previously required physical tool trials. Aerospace tier suppliers in Germany and Japan now deploy finite element-based cure models to predict residual stress distributions before cutting production tooling, reducing first-article qualification iterations by half. This virtualization is compressing the traditional 24-month new program ramp while locking customers into software-embedded resin system specifications.
EPA styrene emission regulations under the Clean Air Act are forcing open-mold laminating operations toward closed-mold resin transfer molding and light RTM processes. Boat builders in Florida and North Carolina face capital equipment decisions between exhaust abatement systems and process technology conversion, with most selecting vacuum-assisted infusion to maintain OSHA permissible exposure limit compliance. Phenolic and vinyl ester formulations with lower monomer volatility are capturing marine and corrosion-resistant tank applications previously dominated by orthophthalic polyesters.
Consolidated procurement by wind turbine OEMs now specifies resin system performance guarantees spanning blade life, not just material properties. Vestas and Siemens Gamesa negotiate outcome-based contracts where prepreg suppliers assume financial exposure for delamination or fatigue failure, shifting technical risk onto chemical formulators. This arrangement concentrates in China's wind manufacturing zones, where blade fabricators lack in-house materials engineering capabilities and outsource specification compliance to resin system vendors.
Thermoset Composites Market Segmentation
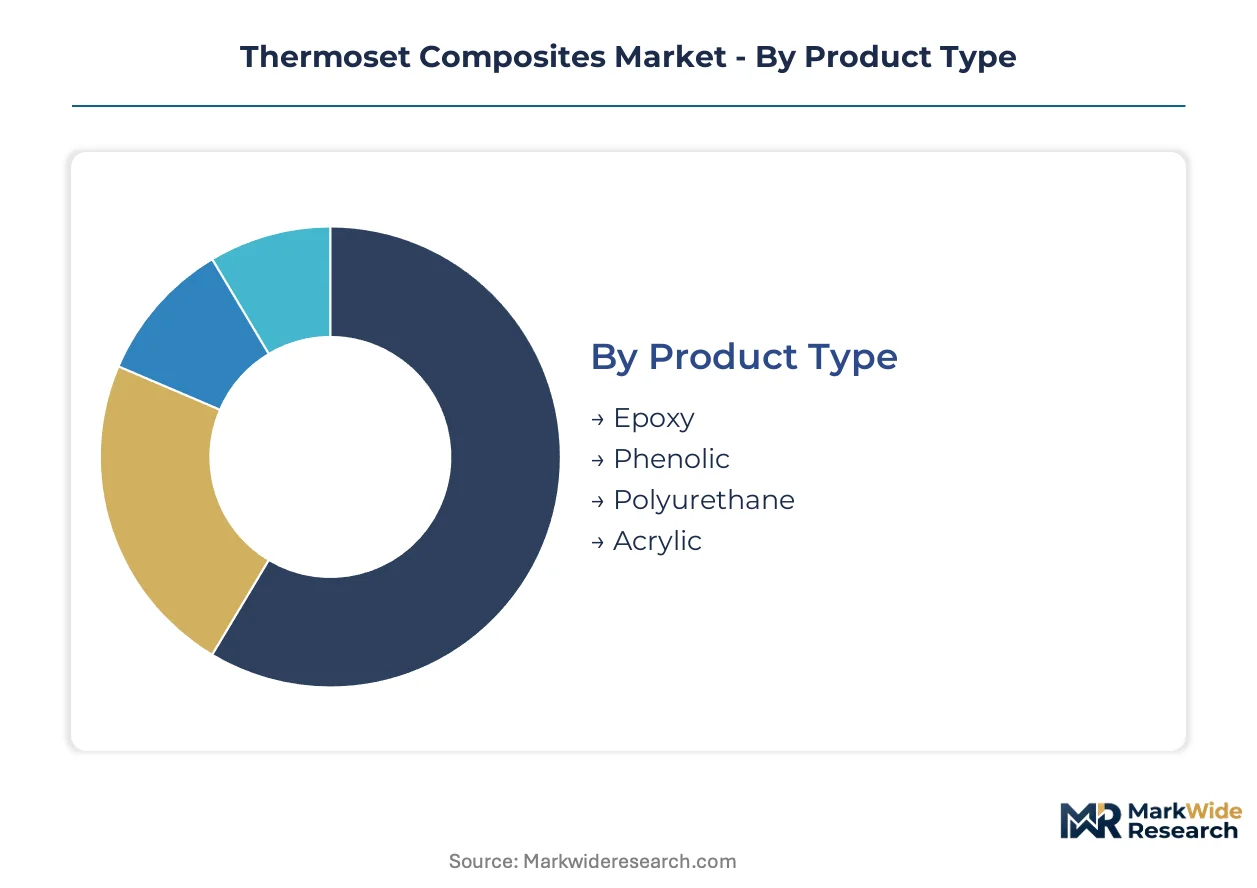
Thermoset composites demand fragments across resin chemistry, fabrication form, and end-use qualification intensity. Segment boundaries determine supplier technical service commitments and inventory holding patterns.
Product Type:
After-sales technical service intensity varies sharply by resin chemistry, with aerospace-qualified systems demanding on-site cure cycle support and failure analysis.
- Epoxy:Dominates structural aerospace and wind energy applications through superior fiber adhesion and environmental resistance. Demand concentrates in Germany's automotive corridor and China's Jiangsu wind manufacturing zone, where blade fabricators require 25-year fatigue performance guarantees.
- Phenolic:Char-forming chemistry delivers low smoke toxicity for rail interior and aircraft cabin applications. Regulatory pressure from EASA flame-retardant standards and FAA heat release requirements drives specification in European and US transportation programs.
- Polyurethane:Rapid cure kinetics suit high-volume automotive panel production.
- Acrylic:UV-curable systems serve decorative and corrosion-coating niches with minimal thermal processing.
By volume, epoxy leads. By growth pace, phenolic is climbing the fastest on regulatory smoke toxicity mandates.
Application:
Cost tier stratification separates qualification-heavy primary structures from commoditized secondary components.
- Aerospace:Primary and secondary airframe structures demand EASA and FAA material qualification protocols with 18-36 month approval timelines. Automated fiber placement workflows in Germany and Japan concentrate prepreg consumption for commercial aviation programs.
- Automotive:Sheet molding compound and resin transfer molding processes serve structural body panels and battery enclosures. Germany's OEM supply chain specifies carbon-fiber-reinforced epoxy for electric vehicle weight reduction targets.
- Recreational:Marine hulls and sporting goods utilize lower-cost vinyl ester and polyester formulations.
- Electronics:Printed circuit board substrates and encapsulation compounds require high glass transition temperatures.
Aerospace commands the highest margin tier. Automotive represents the steepest expansion trajectory on electrification-driven lightweighting.
End User:
Customer type determines specification authority and technical risk allocation across the value chain.
- Manufacturers:Wind blade and airframe fabricators hold direct resin system qualifications and negotiate outcome-based performance contracts. China's blade producers outsource materials engineering to prepreg suppliers, shifting technical liability upstream.
- Suppliers:Tier-one chemical formulators manage ECHA registration and FAA qualification portfolios.
- Distributors:Regional inventory and mixing operations serve fragmented marine and construction markets.
- Contractors:Field repair and maintenance operations consume lower-volume specialty formulations.
Manufacturers capture the largest procurement volume. Distributors are expanding most quickly on specialty chemical consolidation trends.
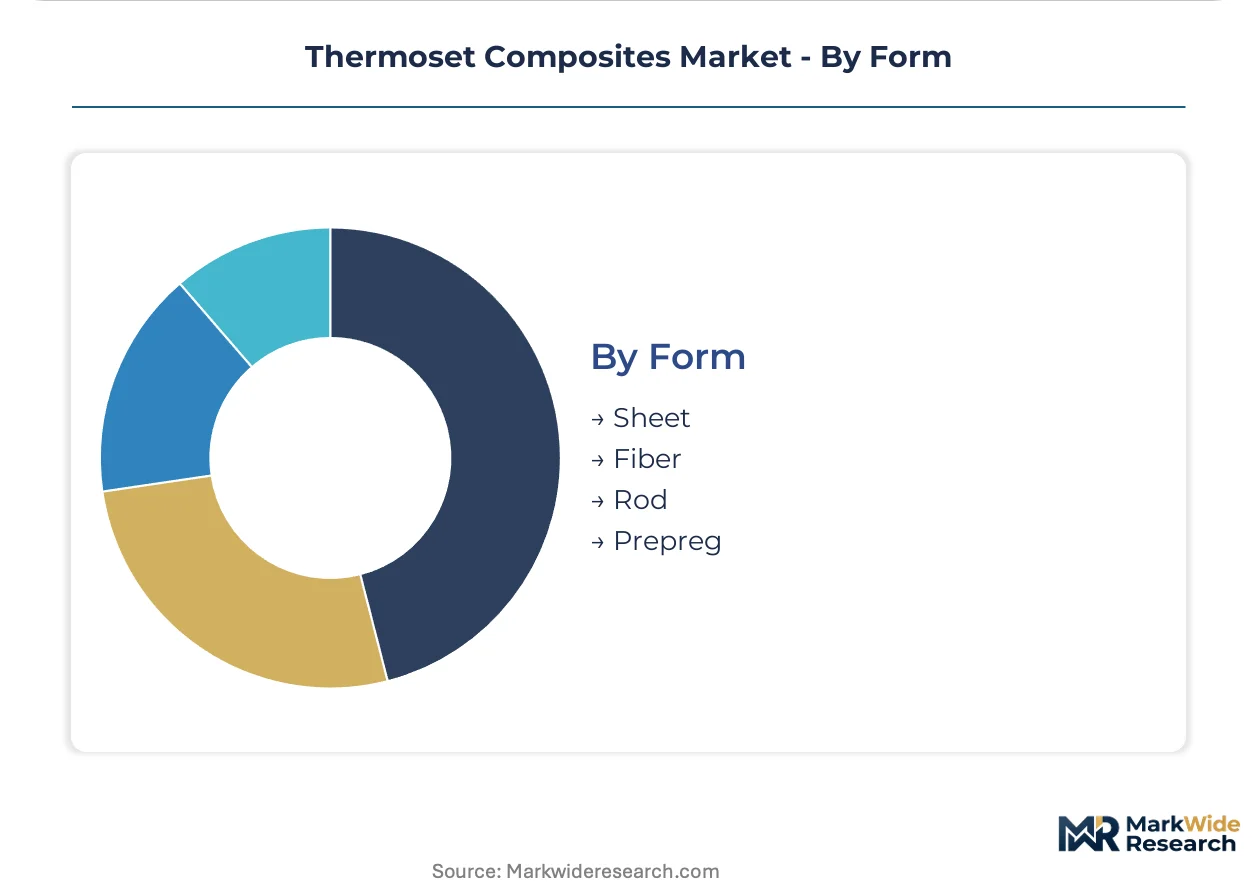
Form:
Supply concentration varies by processing complexity and capital equipment requirements.
- Prepreg:Refrigerated storage and controlled tack characteristics command premium positioning in automated aerospace fabrication. Toray and Hexcel anchor carbon fiber prepreg supply for commercial aviation programs in Japan and the US.
- Sheet:Bulk molding and sheet molding compounds serve high-volume automotive and electrical applications.
- Fiber:Direct roving and chopped strand formats feed compression molding and pultrusion processes.
- Rod:Pultruded profiles serve corrosion-resistant infrastructure and electrical insulation markets.
Sheet leads by volume. Prepreg gains share fastest on aerospace program ramp rates and out-of-autoclave curing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European resin import flows, while China's Jiangsu manufacturing corridor depends on Yangtze River logistics for carbon fiber feedstock delivery.
United States
Commercial aviation OEMs in Wichita and Charleston drive epoxy prepreg consumption for next-generation airframes. FAA material qualification protocols govern resin system approval timelines spanning 18-36 months. The Gulf Coast petrochemical corridor supplies bisphenol A and epichlorohydrin feedstocks, though OSHA permissible exposure limits constrain open-mold laminating operations.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify carbon-fiber-reinforced epoxy for electric vehicle battery enclosures and structural body panels. REACH registration requirements and the EU Green Deal chemical sustainability framework accelerate reformulation toward bio-based hardeners. The Stuttgart industrial cluster concentrates automated fiber placement expertise for aerospace tier suppliers.
China
Wind turbine OEMs in Jiangsu and Guangdong provinces specify carbon-glass hybrid spar caps requiring toughened vinyl ester systems. The country's national chemical regulator enforces dual carbon goals that constrain styrene emissions from open-mold operations. The Yangtze River Delta manufacturing zone hosts blade fabricators outsourcing materials engineering to prepreg suppliers.
Japan
Commercial aviation programs in Nagoya and Tokyo drive carbon fiber prepreg demand for primary aircraft structures. METI industrial standards govern composite material certification pathways for aerospace applications. The Chubu region concentrates Toray Industries' precursor and prepreg manufacturing capacity.
India
DRDO procurement mandates for composite airframe structures create qualification opportunities for epoxy system suppliers. The country's national defense procurement framework prioritizes indigenization of critical materials. The Bangalore-Hyderabad aerospace corridor hosts emerging fabrication facilities seeking local resin mixing capabilities.
Thermoset Composites Market Competitive Environment
On the supply side, the industry is tiered between integrated fiber-resin systems suppliers and specialized chemical formulators. The top tier commands aerospace qualification portfolios and backward fiber integration. Three archetypes dominate: captive fiber suppliers with resin formulation capabilities, independent prepreg specialists with EASA/FAA qualification expertise, and regional compounders serving automotive and wind energy tiers. Competitive moves center on qualification timeline acceleration and local mixing laboratory establishment.
Within the integrated fiber-resin tier, Owens Corning anchors North American wind energy demand through captive glass fiber supply, while Toray Industries exemplifies carbon fiber prepreg dominance for commercial aviation. Hexcel Corporation occupies a position among toughened epoxy specialists sustaining primary aircraft structure qualification thresholds. These three represent distinct competitive positions: fiber-captive systems integration, carbon fiber channel control, and aerospace formulation expertise.
| Leading Market Players |
|---|
| Owens Corning |
| Toray Industries |
| Hexcel Corporation |
| Teijin Limited |
| SGL Carbon |
| Huntsman International |
| PPG Industries |
| Mitsubishi Chemical |
| China Jushi |
| Others |
Value Chain & Pricing Dynamics
Jiangsu Province's carbon fiber prepreg manufacturing corridor anchors global supply for wind blade spar caps, concentrating pricing power among integrated fiber-resin suppliers serving Vestas and Siemens Gamesa procurement desks. This geographic clustering amplifies volume leverage for buyers qualifying multiple resin system platforms while squeezing margin recovery for independent formulators lacking backward fiber integration.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, automotive-performance, and industrial-commodity levels separates prepreg systems with EASA/FAA certification from sheet molding compounds for body panels and bulk polyester formulations for marine hulls. Price differentiation rests on qualification timeline recovery and after-sales technical service bundling, with aerospace tiers commanding premium positioning for 25-year fatigue guarantees. Cost compression in wind energy vinyl ester systems is intensifying because turbine OEMs negotiate outcome-based contracts transferring delamination liability upstream. Marine and construction buyers exhibit highest price sensitivity, while aviation primes prioritize supply security over unit economics.
Supply Chain Analysis
Export-control restrictions on aerospace-grade carbon fiber precursor technology limit flow between Japan, the United States, and European fabrication hubs, fragmenting qualified supplier pools. Raw material dependencies draw from bisphenol A and epichlorohydrin feedstocks in the US Gulf Coast, acrylonitrile precursor for carbon fiber in Japan, and glass fiber roving from China. Single-source vulnerability concentrates in Toray Industries' precursor capacity for commercial aviation programs. Distribution runs through refrigerated prepreg logistics networks serving automated fiber placement lines in Germany and Japan, with regional mixing laboratories emerging in India and Italy to compress lead times for qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoset composites constitute a regulatory-entrenchment defensive moat, where EASA and FAA qualification timelines spanning 18-36 months lock incumbent resin systems into airframe platforms and raise switching costs for aerospace OEMs consolidating vendor pools.
For Market Incumbents: Insulate qualified supplier status by deepening backward integration into carbon fiber precursor production and establishing local mixing laboratories in India's Bangalore-Hyderabad aerospace corridor. Bio-based hardener reformulation investments address REACH chemical sustainability mandates while extending certification portfolio dominance. Threat vectors include solvolysis recycling scale-up potentially unlocking circular feedstock economics for new entrants.
For New Entrants and Emerging Players: India's defense indigenization procurement under DRDO mandates offers white-space entry for epoxy system suppliers establishing qualification capabilities outside Toray-Hexcel-SGL supply orbits. Out-of-autoclave curing adoption among Italian and Spanish tier-two fabricators creates secondary structure opportunities previously reserved for prime-tier suppliers. Go-to-market positioning should emphasize oven-curable prepreg systems eliminating autoclave capital barriers for independent fabrication shops.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fiber-resin specialists with captive aerospace qualification portfolios over independent chemical formulators exposed to petrochemical feedstock volatility. Long-term viability over a decade horizon rests on circularity technology scale-up and bio-based certification pathway capture. Signal to monitor: chemical recycling pilot program economics in the Netherlands and Belgium reaching commercial feedstock recovery thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Toray Industries' acrylonitrile supply control secures aerospace-grade prepreg channel dominance against feedstock volatility. |
| Local Mixing Laboratory Establishment | Hexcel Corporation's qualification facilities in India compress DRDO procurement timelines for composite airframe structures. |
| Bio-Based Hardener Certification Investment | REACH registration for lignin-derived curing agents opens European automotive structural component supply positions. |
| Out-of-Autoclave Curing Technology Scale-Up | Oven-curable systems enable Italian tier-two fabricators to bid on secondary aviation contracts previously blocked by capital barriers. |
| Chemical Recycling Pilot Program Participation | Solvolysis scale-up in the Netherlands attracts venture funding for thermoset composite circularity economics breakthrough. |
Study Parameters
A standing panel of resin formulation chemists, wind blade procurement managers, aerospace tier supplier engineers, and ECHA regulatory affairs specialists provided ongoing calibration against primary field observations and secondary validation sources. This study combined structured interviews with plant managers at Jiangsu blade fabrication facilities, technical R&D directors at German automotive OEMs, and distribution channel partners serving North American marine builders. Secondary sources included customs and trade flow data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical companies, and FAA material qualification databases. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down supply-side capacity assessments.
Scenario bracketing around petrochemical feedstock volatility, REACH regulatory stringency evolution, and aerospace program ramp rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled included resin chemistry tier, fabrication form factor, end-use qualification intensity, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution dynamics between thermoset and thermoplastic systems. Industry-specific forecast inputs captured wind blade length escalation trajectories and automated fiber placement adoption curves in commercial aviation.
Practitioners should monitor EASA bio-based certification pathway announcements, chemical recycling pilot economic thresholds, and India defense procurement indigenization milestones for early signals of forecast revision. Forecasts reflect assumptions about qualification timeline stability, carbon fiber supply concentration persistence, and regulatory framework continuity. Material shifts in per- and polyfluoroalkyl substance restrictions or aerospace OEM vendor consolidation strategies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Global Sports Composites Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Composite Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Expandable Graphite Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Laminar Composites Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Wood Plastic Composite (WPC) Market