
 Cubital Tunnel Syndrome Market | 2026-2036
Cubital Tunnel Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Cubital Tunnel Syndrome Market Analysis
Minimally invasive surgical protocol upgrades is unwinding traditional open decompression economics across the cubital tunnel syndrome landscape. Smith & Nephew PLC leverages integrated arthroscopy portfolios to anchor premium positioning in ambulatory settings. Medtronic sustains R&D intensity around nerve monitoring adjuncts that reduce iatrogenic injury rates. Stryker Corporation dominates the powered instrument segment through proprietary microsagittal blade systems optimized for ulnar nerve release.
Cubital tunnel syndrome denotes ulnar nerve compression at the elbow within the retrocondylar groove or cubital tunnel, characterized by Tinel sign positivity, Froment sign weakness, and slowed nerve conduction velocities below 50 m/s across the elbow segment. The condition drives commercial demand for both diagnostic confirmation and functional restoration in manual laborers, computer operators, and sleep-position-related compression cases. Surgical treatment leads absolute revenue generation due to bundled facility and physician fees, while diagnostic devices represent the fastest-expanding margin pool as point-of-care ultrasound displaces electrodiagnostic referrals. Conservative treatment occupies a mature, price-sensitive tier where generic splinting and NSAID protocols limit branded premium capture.
The FDA governs 510(k) premarket notification for nerve decompression instruments and biologic nerve wraps, while the EU MDR imposes clinical evidence requirements that extend CE marking timelines for novel cubital tunnel implants. Japan's PMDA maintains distinct biocompatibility testing standards for permanent implant materials contacting peripheral neural tissue. Stakeholders must monitor evolving CMS reimbursement determinations for office-based ultrasound diagnostics versus hospital-based electrophysiology studies.
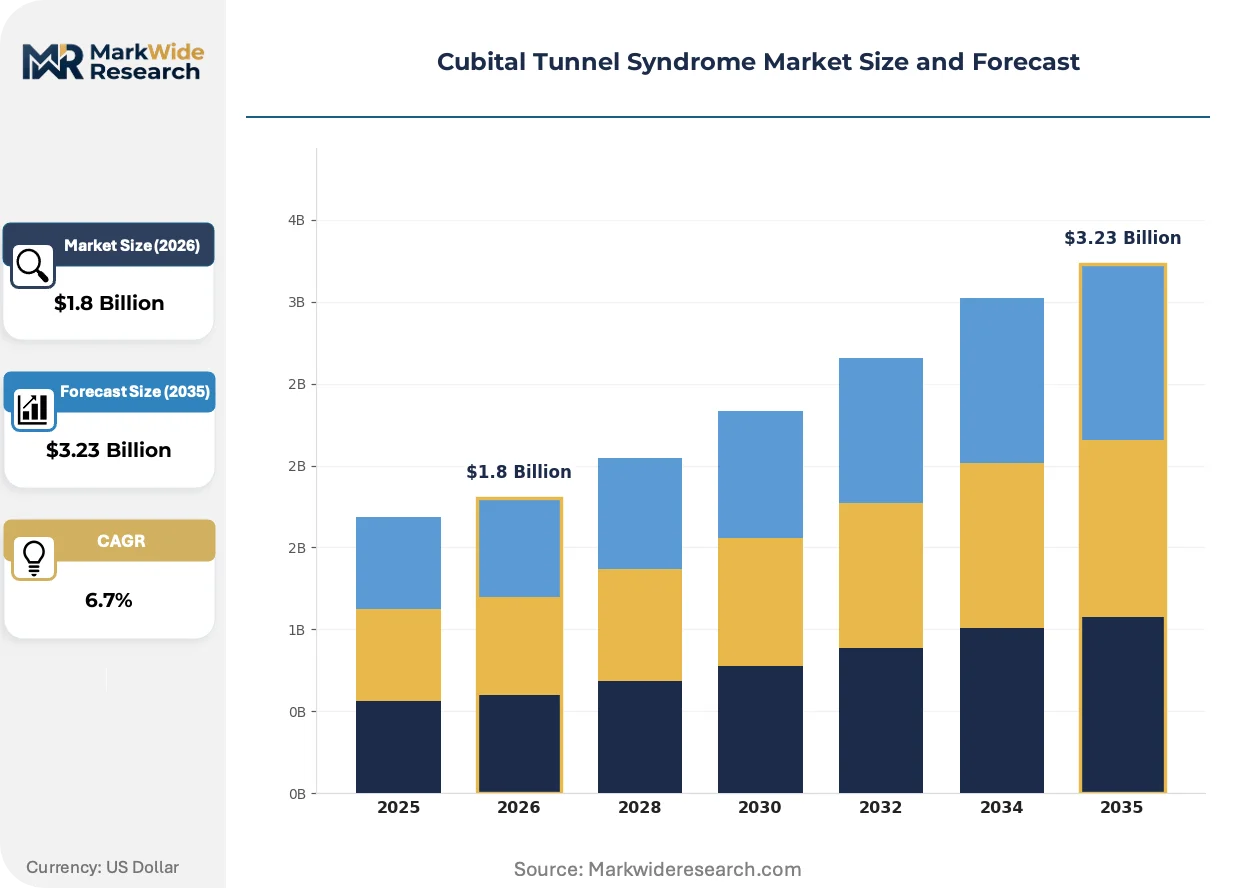
Market Dynamics
Minimally invasive nerve decompression protocols are compressing traditional open surgical economics across ambulatory settings. The FDA's streamlined 510(k) pathway for nerve monitoring adjuncts accelerates commercial entry while hospital systems consolidate purchasing around integrated arthroscopy platforms.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage determinations for office-based diagnostic ultrasound reduce referral friction to electrophysiology laboratories. This shift concentrates diagnostic volume in orthopedic and hand surgery clinics.
- Aging Workforce Demographics:Manual laborers and computer operators in Germany, Japan, and the United States exhibit elevated compressive neuropathy prevalence. Occupational health mandates drive employer-funded screening programs.
- Biologic Nerve Wrap Materials:Absorbable collagen conduits and amniotic membrane derivatives improve functional recovery metrics. These materials command premium pricing in tertiary hospital surgical departments.
Market Restraints
- EU MDR Clinical Evidence Requirements:Extended CE marking timelines for novel cubital tunnel implants delay commercial launch by 18-24 months. Small manufacturers face disproportionate compliance cost burdens.
- Silicone Raw Material Concentration:Nerve protector manufacturing depends on medical-grade silicone supply concentrated in Northeast Asian petrochemical clusters. Input cost volatility compresses margin pools for device converters.
- Conservative Treatment Substitution:Generic splinting protocols and NSAID regimens capture price-sensitive early-stage patients. Branded premium capture remains limited in this mature tier.
Strategic Opportunities
- Point-of-Care Ultrasound Displacement:Portable diagnostic devices replace hospital-based electrophysiology referrals in United States ambulatory surgery centers. Margin expansion concentrates in orthopedic group purchasing organizations.
- Japan PMDA Biocompatibility Pathway:Distinct testing standards for permanent neural implants create first-mover advantage for compliant manufacturers. Domestic partnership requirements favor localized clinical trial investment.
- Sleep-Position Compression Awareness:Consumer education campaigns targeting nocturnal ulnar nerve compression expand addressable patient pools. Direct-to-patient channels bypass traditional physician referral gatekeeping.
Industry Challenges
- Microsurgical Skill Scarcity:Fellowship-trained hand surgeons capable of internal neurolysis and anterior transposition remain concentrated in academic medical centers. Community hospital expansion requires proctored training program investment.
- 510(k) Predicate Device Drift:FDA equivalence determinations for novel nerve decompression instruments face heightened scrutiny. Substantial equivalence arguments require expanded clinical validation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cubital Tunnel Syndrome Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Treatment, Conservative Treatment, Diagnostic Devices, Anti-inflammatory Medications End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Research Institutions Technology: Ultrasound, MRI, Electrodiagnostics, Surgical Instruments Application: Pain Management, Rehabilitation, Diagnosis, Surgical Intervention |
| Companies Covered | Smith & Nephew PLC, Medtronic, Stryker Corporation, Sonex Health LLC, Zimmer Biomet, Arthrex Inc, Integra LifeSciences Corporation, MicroAire Surgical Instruments LLC, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cubital Tunnel Syndrome Market Emerging Trajectories
Endoscopic cubital tunnel release systems are compressing operative time and facility cost structures. Three parallel developments are reshaping competitive positioning across diagnostic and therapeutic segments.
High-definition endoscopic visualization platforms with integrated nerve monitoring are fragmenting the traditional open decompression market. Ambulatory surgery centers in the United States adopt these systems to reduce anesthesia duration and same-day discharge protocols. The technology is fragmenting case volume away from inpatient hospital settings toward lower-cost sites of service.
Japan's PMDA maintains distinct biocompatibility testing standards for permanent implant materials contacting peripheral neural tissue. These requirements extend premarket approval timelines but create regulatory moats for compliant manufacturers. Domestic distributors with established PMDA relationships capture disproportionate market access for novel nerve wraps and conduits.
Orthopedic group purchasing organizations consolidate diagnostic device procurement around bundled service contracts. Hospital systems negotiate comprehensive ultrasound and electrodiagnostic packages rather than discrete instrument purchases. This concentration is most visible in United States integrated delivery networks seeking standardized protocols across multiple facilities.
Cubital Tunnel Syndrome Market Segmentation
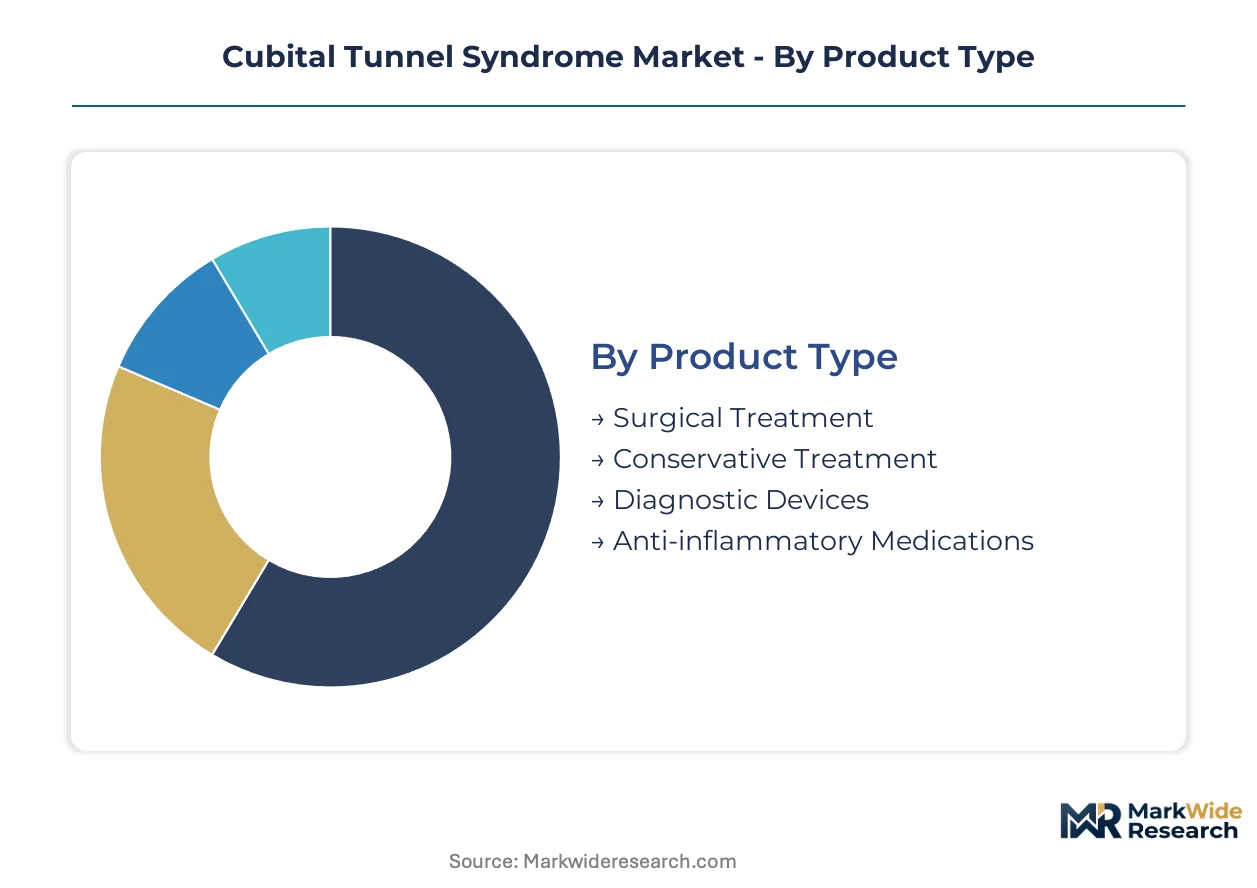
Segmentation in the cubital tunnel syndrome market reveals divergent margin structures across intervention types. Surgical and diagnostic modalities command premium pricing in tertiary settings, while conservative protocols compete on accessibility.
Product Type:
Surgical treatment and diagnostic devices concentrate revenue in the United States and Germany, while conservative protocols distribute across primary care networks in price-sensitive markets.
- Surgical Treatment:Open decompression, endoscopic release, and anterior transposition procedures generate bundled facility and physician fees. United States ambulatory surgery centers drive volume as CMS reimbursement shifts toward site-neutral payment structures.
- Diagnostic Devices:Point-of-care ultrasound systems and nerve conduction units displace hospital-based electrophysiology referrals. Portable equipment sales concentrate in orthopedic group purchasing organizations seeking standardized protocols.
- Conservative Treatment:Night splinting and activity modification protocols serve early-stage patients through occupational health channels.
- Anti-inflammatory Medications:Generic NSAID regimens and corticosteroid injections capture primary care prescriptions with limited branded premium opportunity.
Surgical treatment holds the largest share; momentum sits with diagnostic devices.
End User:
Procurement authority fragments across integrated delivery networks, independent surgical centers, and employer-funded occupational health programs.
- Hospitals:Tertiary academic medical centers perform complex revision surgeries and internal neurolysis procedures. Bundled payment contracts with commercial insurers concentrate high-acuity cases in urban referral hubs.
- Outpatient Clinics:Ambulatory settings capture endoscopic release volume through reduced anesthesia duration and same-day discharge protocols. United States Medicare site-neutral policies accelerate this shift.
- Rehabilitation Centers:Postoperative therapy and conservative management protocols serve workers compensation cases and employer-funded return-to-work programs.
- Research Institutions:Clinical trial sites evaluate novel biologic nerve wraps and absorbable conduit materials under FDA and PMDA investigational device exemptions.
Hospitals retain procedural revenue dominance; outpatient clinics are expanding most quickly.
Technology:
Capital equipment cycles and regulatory clearance timelines create distinct competitive moats across imaging and intervention platforms.
- Ultrasound:High-frequency linear transducers enable real-time ulnar nerve visualization at the cubital tunnel. Office-based deployment in orthopedic clinics reduces electrodiagnostic referral friction.
- Electrodiagnostics:Nerve conduction studies and electromyography remain the reference standard for severity grading. Hospital-based electrophysiology laboratories face volume pressure from point-of-care alternatives.
- Surgical Instruments:Powered microsagittal systems and endoscopic visualization platforms optimize operative efficiency.
- MRI:Advanced imaging reserves for atypical presentations and preoperative planning in complex revision cases.
Electrodiagnostics maintains clinical authority; ultrasound gains share fastest.
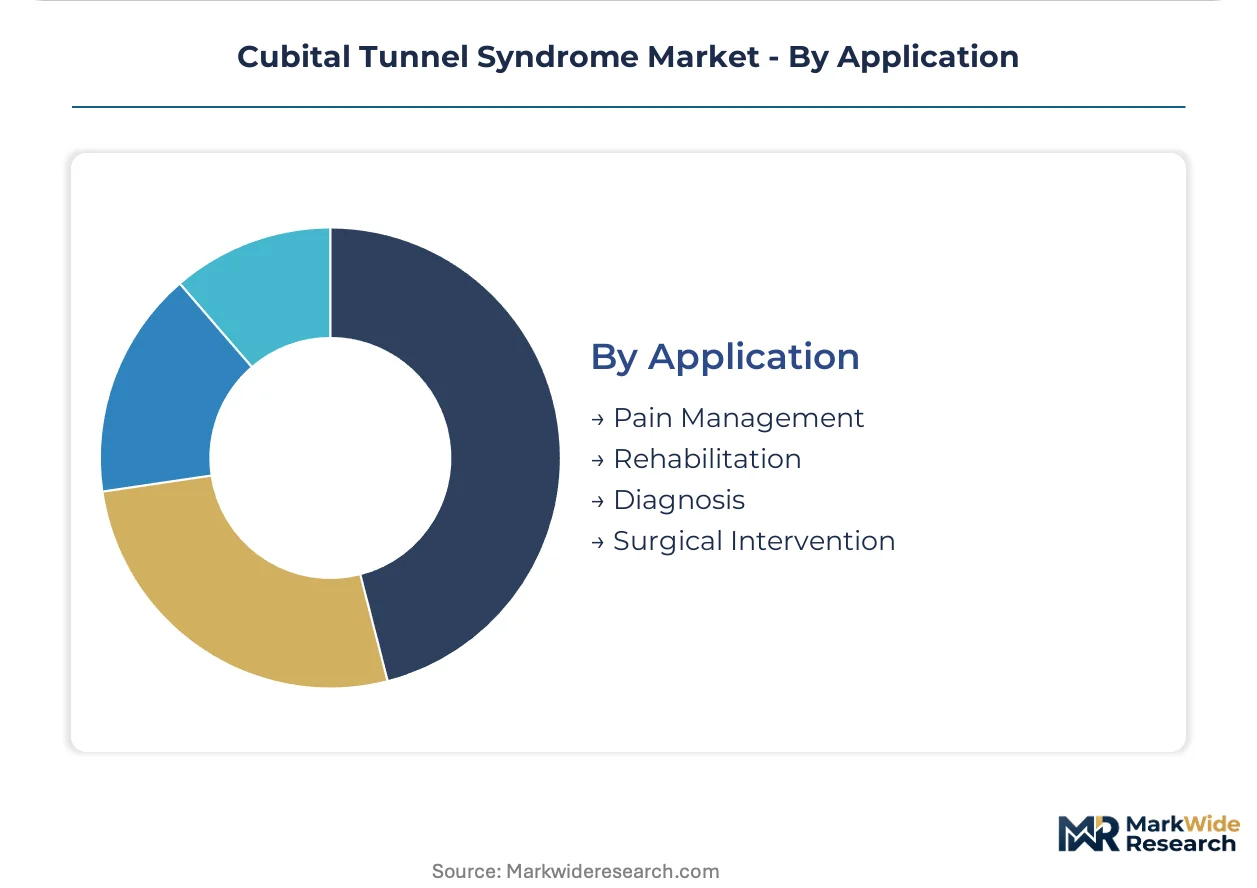
Application:
Reimbursement pathways and patient acuity determine whether interventions address symptoms, restore function, or confirm diagnosis.
- Surgical Intervention:Decompression and transposition procedures target motor deficit progression and failed conservative trials. Tertiary hospitals in Japan and Germany concentrate fellowship-trained hand surgeons.
- Diagnosis:Tinel sign confirmation, electrodiagnostic severity grading, and imaging characterization precede treatment selection. Diagnostic accuracy requirements vary across workers compensation jurisdictions.
- Rehabilitation:Postoperative therapy and neuromuscular reeducation protocols optimize functional recovery metrics.
- Pain Management:Symptom-focused protocols address nocturnal paresthesia and activity-related discomfort through splinting and medication.
Surgical intervention generates absolute revenue; diagnosis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import reliance for nerve decompression instruments concentrates in Northeast Asian silicone supply chains, while the United States, Germany, and Japan generate surplus surgical service exports through tertiary hospital networks.
United States
Medicare site-neutral payment policies accelerate ambulatory surgery center volume capture from inpatient hospitals. The FDA's 510(k) pathway for nerve monitoring adjuncts compresses commercial entry timelines for device innovators. Fellowship-trained hand surgeons cluster in urban academic medical centers across the Northeast Corridor and California, performing complex revision procedures.
Germany
Occupational health mandates in manufacturing sectors drive employer-funded cubital tunnel screening programs for aging manual laborers. The EU MDR imposes extended clinical evidence requirements that delay CE marking for novel nerve wraps by 18-24 months. Baden-Württemberg and Bavaria host concentrated orthopedic device manufacturing and surgical training hubs.
Japan
PMDA maintains distinct biocompatibility testing standards for permanent implants contacting peripheral neural tissue, creating regulatory moats for compliant manufacturers. Domestic partnership requirements favor localized clinical trial investment. Kanto and Kansai regions concentrate tertiary hand surgery departments and absorbable conduit research programs.
United Kingdom
NHS bundled payment contracts for orthopedic procedures concentrate high-acuity cubital tunnel cases in London and Southeast referral networks. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for nerve decompression devices. Midlands and North England rehabilitation centers handle postoperative therapy volume for workers compensation cases.
South Korea
MFDS accelerated review pathways for innovative surgical instruments attract multinational manufacturers seeking Asian market entry. Seoul Capital Area hospitals adopt endoscopic release systems to reduce anesthesia duration and facility costs. Busan-Ulsan industrial zones supply medical-grade silicone components for nerve protector manufacturing.
Cubital Tunnel Syndrome Market Vendor Landscape
Concentration sits with diversified orthopedic conglomerates controlling integrated arthroscopy platforms and powered instrument portfolios. The vendor base stratifies across three tiers: multinational device conglomerates with comprehensive surgical portfolios, mid-cap specialists in nerve monitoring and biologic materials, and regional distributors with PMDA or FDA regulatory relationships. Dominant competitive moves include strategic partnerships with ambulatory surgery center networks and technology licensing for point-of-care diagnostic platforms.
Within the diversified conglomerate tier, Smith & Nephew PLC, Medtronic, and Stryker Corporation exemplify scale-driven positioning across nerve decompression, arthroscopy, and intraoperative monitoring segments. These entities anchor procurement relationships with United States integrated delivery networks and German hospital systems through bundled service contracts. Mid-cap specialists and regional distributors occupy positions in Japan's PMDA-compliant biologic wrap segment and European CE marking pathways for novel conduit materials.
| Leading Market Players |
|---|
| Smith & Nephew PLC |
| Medtronic |
| Stryker Corporation |
| Sonex Health LLC |
| Zimmer Biomet |
| Arthrex Inc |
| Integra LifeSciences Corporation |
| MicroAire Surgical Instruments LLC |
| CONMED Corporation |
| Others |
Supply Flow & Price Mechanics
Point-of-care ultrasound displacement of hospital-based electrodiagnostic referrals simultaneously redraws procurement geography and compresses margin structures across diagnostic tiers. This substitution dynamic concentrates purchasing authority in orthopedic group purchasing organizations while fragmenting traditional electrophysiology laboratory revenue pools.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the cubital tunnel syndrome market. Premium positioning rests on FDA 510(k) clearance tier and integrated nerve monitoring capabilities, while standard tiers compete on ambulatory surgery center compatibility. Cost compression in the economy tier intensifies because generic splinting protocols capture price-sensitive early-stage patients. Hospital systems exhibit lowest price sensitivity due to bundled payment contracts, whereas primary care networks demonstrate highest sensitivity to out-of-pocket diagnostic costs.
Supply Chain Analysis
Germany and Japan anchor precision manufacturing of powered microsagittal systems and endoscopic visualization platforms. Medical-grade silicone feedstock draws from Northeast Asian petrochemical clusters, while biologic nerve wrap materials source from domestic amniotic membrane processing facilities. Single-source vulnerability concentrates in medical-grade silicone supply chains exposed to regional logistics disruptions. Distribution runs through integrated delivery network procurement offices and specialized orthopedic device distributors with PMDA regulatory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as site-neutral reimbursement policies disperse procedural volume from tertiary hospitals toward ambulatory settings. This demand-side shift rewards specialized players with targeted regulatory and channel capabilities.
For Market Incumbents: Secure PMDA biocompatibility compliance for permanent neural implants ahead of domestic partnership requirements tightening in Japan. Acquire point-of-care ultrasound specialists to defend against electrodiagnostic referral erosion. Lock in exclusive ambulatory surgery center contracts before site-neutral payment policies fully mature.
For New Entrants and Emerging Players: Lead with sleep-position compression awareness campaigns targeting direct-to-patient channels that bypass traditional physician gatekeeping. Target nocturnal splinting and consumer diagnostic segments where incumbent presence remains thin. Pursue white-label manufacturing partnerships with established PMDA-compliant distributors for rapid Japanese market entry.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap nerve monitoring specialists holding 510(k) clearances but limited ambulatory channel penetration. Five-to-ten year viability hinges on successful migration from hospital-based to site-neutral service models. Monitor CMS reimbursement determinations for office-based ultrasound as the critical inflection signal for diagnostic device valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercial entry for nerve decompression instruments through streamlined predicate equivalence pathway. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines but create compliance moats for prepared manufacturers. |
| Hospital System Partnership | Bundled service contracts with United States integrated delivery networks concentrate high-acuity procedural volume. |
| Software Companion Development | Integrated nerve monitoring algorithms reduce iatrogenic injury rates and support premium pricing in arthroscopy platforms. |
| Reimbursement Strategy | CMS site-neutral payment alignment captures ambulatory surgery center volume from traditional inpatient settings. |
Methodological Framework
The analysis maps surgical treatment modalities, diagnostic device platforms, and conservative intervention tiers, each validated through hand surgeons, biomedical engineers, GPO contracts managers, and ambulatory surgery center administrators. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS reimbursement determinations, hospital procurement databases, and PMDA approval records. Bottom-up procedure volume estimates and top-down market sizing triangulate through orthopedic group purchasing organization contract analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include intervention type, end-user setting, technology platform, and application purpose. CAGRs derived from procedure growth trajectories, reimbursement rate evolution, and equipment replacement cycles. Industry-specific forecast inputs incorporate fellowship-trained hand surgeon supply constraints and PMDA biocompatibility testing timeline variability.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR implementation, and Japan PMDA standards; material policy shifts would require re-modeling. Specific risks that could revise projections include CMS reimbursement determination reversals, medical-grade silicone supply disruptions, and microsurgical skill scarcity limiting procedure expansion. Recalibration cycles align with material shifts in reimbursement policy, regulatory clearance timelines, and supply chain concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market