
 Trench Cover Market | 2026-2036
Trench Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Trench Cover Market Analytics
The capability gap between capital-heavy composite manufacturers and legacy metal fabricators is collapsing as automated resin-transfer molding cuts tooling costs. Fibrelite leverages its proprietary composite formulations to dominate airport and fuel-station specifications across North America. HERMEQ anchors its position through backward integration into pultruded fiberglass production, controlling raw material quality and delivery timelines.
A trench cover is a load-bearing access panel engineered to span underground utility trenches, typically manufactured from steel, aluminum, plastic, or fiber-reinforced composites with specified load ratings from pedestrian-grade to heavy-vehicle duty. These covers seal excavations for water mains, telecommunications, and power distribution while enabling safe pedestrian and vehicular traffic. Composite materials are capturing margin pools in corrosive environments where lifecycle replacement costs favor non-metallic solutions. Civil engineering applications lead volume, though modular installation systems are accelerating fastest as urban retrofit projects demand minimal-disruption deployment.
Load-rating standards from ISO, EN 124 in Europe, and BIS IS 1726 in India dictate material selection and testing protocols for trench cover suppliers seeking market access. OSHA excavation safety rules in the United States and the EU's Construction Products Regulation together elevate product certification costs while filtering out uncertified competitors. Stakeholders must monitor how municipal decarbonization targets redirect procurement toward recycled-content composites versus traditional steel and aluminum grades.
Market Dynamics
Automated resin-transfer molding is collapsing the tooling cost barrier that historically separated capital-heavy composite manufacturers from legacy metal fabricators, redrawing competitive boundaries across material categories.
Growth Catalysts
- EU Green Deal circular economy mandates:Municipal utilities in Germany are expanding composite trench cover procurement under binding recycled-content requirements, redirecting public spending toward non-metallic solutions.
- BIS IS 1726 load-rating standard tightening:India's Bureau of Indian Standards is enforcing stricter certification protocols for smart city infrastructure corridors, filtering uncertified suppliers from high-value projects.
- Automated resin-transfer molding:This production technology cuts composite tooling costs by enabling mid-scale manufacturers to achieve quality parity with established composite specialists.
Market Restraints
- Petrochemical feedstock volatility:Glass-reinforced polyester and vinyl ester resins face input cost swings tied to crude oil derivatives, compressing margin predictability for composite producers.
- Steel scrap price arbitrage:Legacy metal fabricators in Turkey and Vietnam exploit regional scrap metal cost advantages, undercutting composite pricing in price-sensitive procurement segments.
- EN 124 certification timeline:European load-rating compliance requires 18-24 month testing cycles, creating a structural barrier for new entrants seeking market access.
Strategic Opportunities
- Modular rapid-installation systems:Urban retrofit projects in São Paulo and Mexico City are adopting tool-free deployment configurations that minimize street closure duration and labor hours.
- Corrosion-resistant specifications:Coastal desalination plants and chemical processing facilities are specifying fiber-reinforced composites to eliminate galvanic degradation and lifecycle replacement costs.
- OSHA excavation safety rule alignment:US infrastructure contractors are bundling trench cover specification with site safety compliance, creating integrated procurement packages that favor certified composite suppliers.
Industry Challenges
- Resin formulation expertise shortage:Composite manufacturers struggle to recruit polymer chemists capable of optimizing fire-retardant and UV-stable formulations for infrastructure-grade applications.
- Legacy anchor compatibility:Retrofit projects require trench covers to interface with existing cast-iron seating frames, demanding custom engineering that extends delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trench Cover Market |
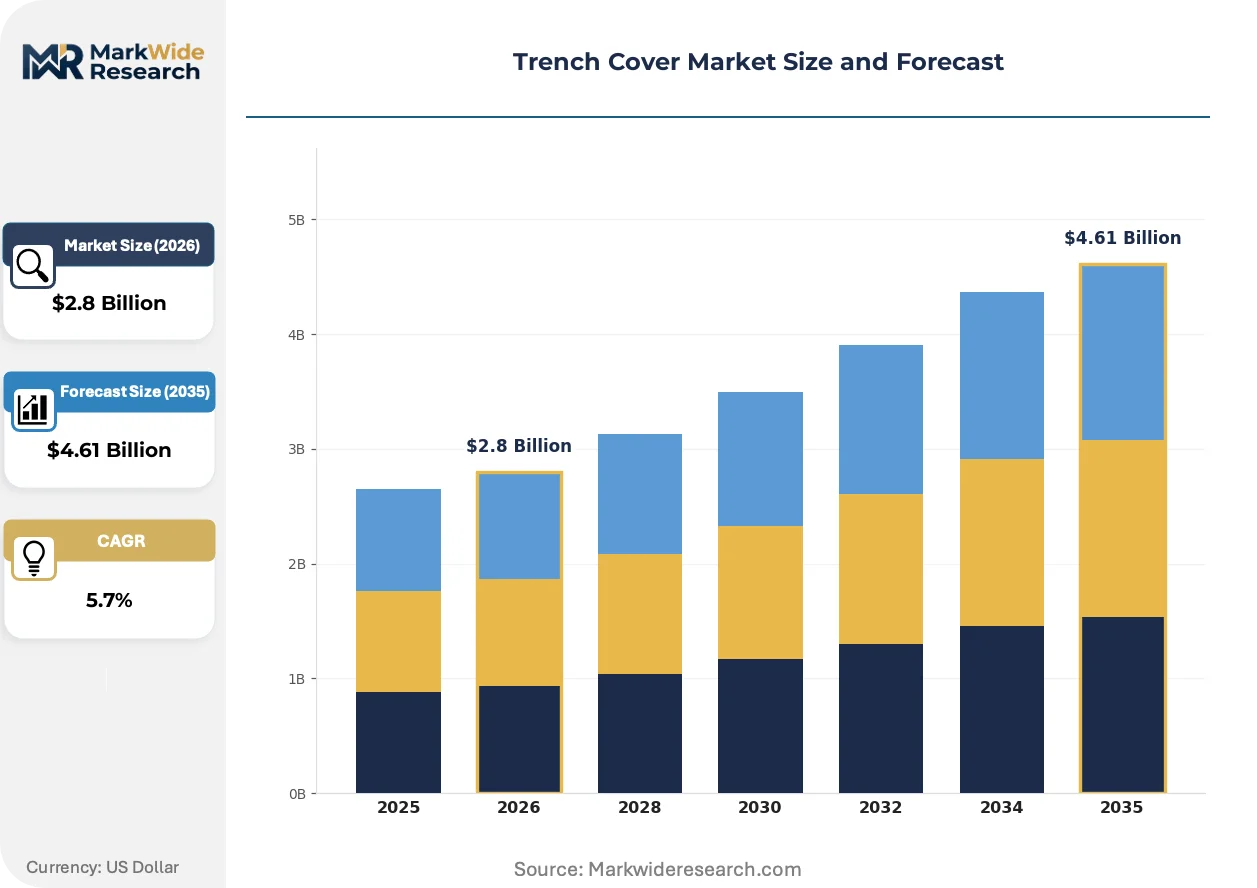
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Composite, Steel, Aluminum Application: Civil Engineering, Construction, Utilities, Infrastructure Type: Heavy Duty, Light Duty, Industrial, Modular Installation Method: Temporary, Permanent, Removable, Embedded |
| Companies Covered | Fibrelite, HERMEQ, Alcomet, Oxford Plastics, Ducast, Trench Shoring Company, Speed Shore Corporation, Pacific Shoring, TrenchTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trench Cover Market Evolving Landscape
Material science advances and procurement digitization are splitting the market between premium engineered composites and commoditized metal alternatives, with specification authority shifting from fabricators to asset owners.
Continuous fiber-reinforced thermoplastic composites are bifurcating the airport and fuel-station specification landscape. These materials combine glass or carbon fiber with polypropylene matrices to deliver impact resistance without the brittle failure modes of thermoset alternatives. Major hub airports in Atlanta and Dubai are specifying thermoplastic covers for high-frequency baggage handling areas. The technology is bifurcating supplier tiers by rewarding manufacturers with in-house compounding capabilities while marginalizing resin buyers.
REACH SVHC disclosure requirements are forcing raw material transparency across European supply chains. Composite manufacturers must now document Substances of Very High Concern content in resins, pigments, and fire retardants down to 0.1% concentration thresholds. German municipal procurement offices are rejecting bids lacking full material disclosure, compressing the qualified supplier base for public infrastructure tenders.
Digital twin integration is altering how asset owners manage trench cover lifecycle decisions. Water utilities in Singapore and Sydney are embedding RFID tags and load sensors into composite covers, feeding real-time condition data into centralized asset management platforms. This telemetry-enabled approach shifts procurement criteria from upfront capital cost to total lifecycle value, favoring suppliers offering predictive maintenance partnerships over transactional product sales.
Trench Cover Market Segmentation
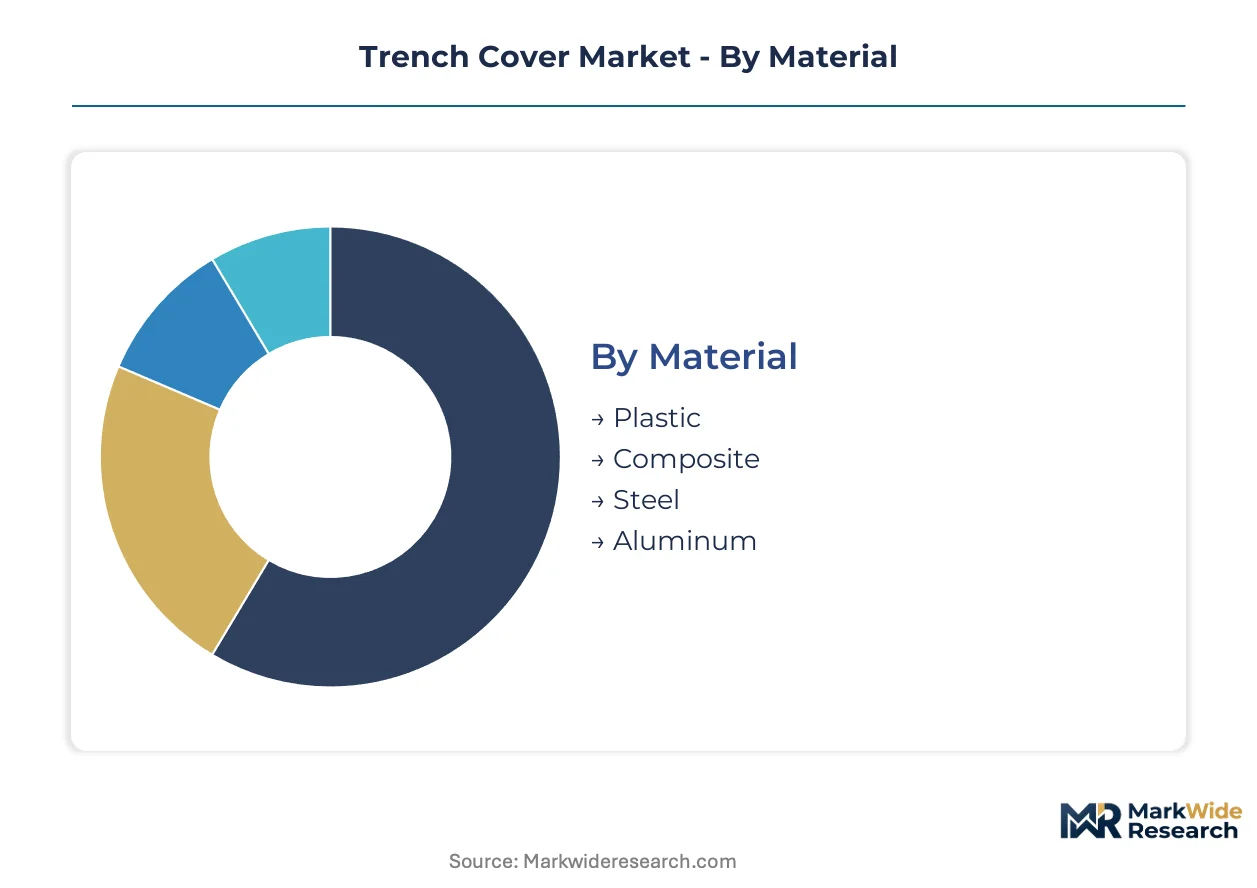
Trench cover procurement splits across material specifications, load-rating protocols, and deployment configurations. Each dimension carries distinct certification requirements and lifecycle economics that reshape supplier selection criteria.
Material:
EN 124 and BIS IS 1726 load-rating standards enforce divergent material performance thresholds across European and Indian procurement corridors.
- Composite:Glass-reinforced polyester and vinyl ester formulations deliver corrosion immunity for coastal desalination plants and chemical processing facilities. German municipal utilities under EU Green Deal mandates are redirecting capital toward recycled-content composite procurement, filtering uncertified metal fabricators from public tenders.
- Steel:Cast and ductile iron grades dominate heavy-vehicle duty specifications where EN 124 Class D400 and above ratings apply. Turkish and Vietnamese fabricators exploit regional scrap metal arbitrage to undercut composite pricing in price-sensitive Middle Eastern and Southeast Asian infrastructure bids.
- Plastic:High-density polyethylene covers serve pedestrian-grade and light-vehicle applications with minimal maintenance overhead. Singapore water utilities specify thermoplastic grades for RFID-embedded smart monitoring deployments.
- Aluminum:Lightweight extrusions target airport baggage handling areas and fuel station canopies where manual liftability intersects with moderate load requirements. Dubai International Airport specifications favor aluminum for frequent-access maintenance points.
Steel handles the majority of throughput; Composite is the fastest mover on share.
Application:
Project scale and asset ownership structure determine whether procurement flows through municipal utilities, private contractors, or industrial facility operators.
- Civil Engineering:Highway drainage systems and bridge expansion joints require certified load ratings with documented fatigue testing. India's smart city infrastructure corridors under tightened BIS protocols are concentrating demand among pre-qualified composite suppliers.
- Utilities:Water, telecommunications, and power distribution networks prioritize corrosion resistance and telemetry integration. Sydney's digital twin-enabled asset management platforms are shifting utility procurement toward predictive maintenance partnerships.
- Infrastructure:Airport runways, rail yards, and port terminals specify continuous fiber-reinforced thermoplastics for impact resistance without brittle failure modes. Atlanta's Hartsfield-Jackson hub mandates thermoplastic covers for high-frequency ground support equipment zones.
- Construction:Temporary site access and phased development projects favor rapid-installation systems with minimal foundation requirements. São Paulo urban retrofit contractors specify tool-free modular configurations to compress street closure windows.
Civil Engineering commands the largest project volumes; Utilities is expanding most quickly on digitization tailwinds.
Type:
Load-rating tier and deployment permanence split manufacturing investment between heavy-tooling metal casting and adaptable composite molding.
- Heavy Duty:EN 124 Class E600 and F900 ratings for aircraft and industrial vehicle loads demand reinforced rib geometries and locking mechanisms. Frankfurt Airport specifications require composite heavy-duty covers with integrated anti-slip surfaces for de-icing chemical exposure.
- Modular:Interlocking panel systems enable custom span configurations without site-fabrication. Mexico City metro expansion projects specify modular composites for curved platform edges and irregular trench geometries.
- Industrial:Chemical plants and refineries specify fire-retardant formulations with ASTM E-84 smoke index compliance. REACH SVHC disclosure requirements are compressing the qualified supplier base for European industrial tenders.
- Light Duty:Pedestrian and park-grade covers prioritize aesthetic integration and manual handling. Melbourne's urban renewal corridors specify light-duty composites with customizable surface patterns for heritage district compatibility.
Heavy Duty absorbs the bulk of material tonnage; Modular is climbing the fastest on urban retrofit demand.
Installation Method:
Site constraints and traffic management protocols determine whether covers integrate with existing cast-iron seating frames or deploy as standalone systems.
- Permanent:Cementitious bedding and welded anchoring provide maximum security for high-theft-risk locations. Johannesburg's copper cable protection corridors specify permanent composite installations with tamper-evident fasteners.
- Removable:Key-lift and cam-lock mechanisms balance security with maintenance access for frequent inspection points. Tokyo's underground flood mitigation systems specify removable aluminum covers with integrated lifting points for emergency response protocols.
- Temporary:Steel road plates and composite overlay panels serve construction phasing without foundation work. Los Angeles metro expansion contractors rent temporary composite systems with traffic-rated surfaces for 18-24 month staging periods.
- Embedded:Cast-in-place frames integrate with concrete trench walls for seamless surface continuity. Rotterdam's flood-resilient district cooling networks specify embedded composite frames with expansion joint compatibility.
Permanent dominates installed base; Removable is gaining share fastest on smart city telemetry integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement in Turkey and Vietnam squeezes composite margins, while German and Australian buyers absorb premium pricing for certified recycled-content specifications. Demand elasticity splits sharply between infrastructure-rich mature markets and cost-driven emerging corridors.
Germany
Municipal utilities in the Rhine-Ruhr and Bavaria regions are accelerating composite trench cover procurement under binding EU Green Deal recycled-content mandates. The country's national construction regulator enforces EN 124 load-rating standards with documented fatigue testing for public infrastructure tenders. Stuttgart's smart city corridor concentrates specification authority among pre-qualified composite suppliers offering full REACH SVHC material disclosure.
United States
OSHA excavation safety compliance drives bundled procurement packages linking trench cover specification with site safety certification. Federal infrastructure spending channels demand toward corrosion-resistant composites for coastal flood mitigation systems. Atlanta's Hartsfield-Jackson airport anchors thermoplastic cover adoption for high-frequency ground support equipment zones.
India
Smart city infrastructure corridors in Maharashtra and Karnataka face tightened BIS IS 1726 load-rating enforcement filtering uncertified suppliers from high-value projects. The Bureau of Indian Standards mandates stricter certification protocols for composite and metal covers in urban utility networks. Mumbai's metro expansion and Bengaluru's tech corridor concentrate demand among pre-qualified domestic and international fabricators.
Australia
Sydney Water and Melbourne's urban renewal authorities specify RFID-embedded composite covers feeding digital twin asset management platforms. The country's national construction regulator aligns with ISO load-rating standards while elevating lifecycle value criteria over upfront capital cost. Queensland's coastal desalination plants specify fiber-reinforced composites to eliminate galvanic degradation in marine environments.
Brazil
São Paulo's urban retrofit contractors adopt tool-free modular trench cover configurations to compress street closure windows and labor hours. ANVISA material safety requirements intersect with municipal procurement rules for utility infrastructure. The São Paulo metro expansion and Rio de Janeiro port modernization concentrate demand for rapid-installation systems with minimal foundation requirements.
Trench Cover Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with automated resin-transfer molding collapsing historical capital barriers between composite and metal fabricators. The structure bifurcates between capital-heavy formulation specialists controlling proprietary resin systems and agile mid-scale manufacturers achieving quality parity through automation. Three archetypes dominate: backward-integrated composite compounders, scrap-advantaged metal fabricators, and telemetry-enabled solution providers bundling hardware with predictive maintenance. Competitive moves center on capacity expansion in recycled-content composites and strategic partnerships embedding RFID and load-sensor technology into cover systems.
Among the integrated composite specialists, Fibrelite and HERMEQ occupy distinct positioning archetypes. Fibrelite exemplifies the formulation-led tier leveraging proprietary composite systems to anchor premium specifications. HERMEQ represents backward integration into pultruded fiberglass production, controlling raw material quality and delivery timelines. Oxford Plastics sits within the mid-scale agile tier, achieving market access through automated molding without historical capital burdens. Together these three illustrate how automated production technology is redrawing competitive boundaries across material categories.
| Leading Market Players |
|---|
| Fibrelite |
| HERMEQ |
| Alcomet |
| Oxford Plastics |
| Ducast |
| Trench Shoring Company |
| Speed Shore Corporation |
| Pacific Shoring |
| TrenchTech |
| Others |
Value Network & Pricing Analysis
Automated resin-transfer molding displacing legacy compression tooling simultaneously redraws supply geography toward mid-scale automated producers and compresses pricing premiums previously commanded by capital-heavy composite specialists. This substitution dynamic redirects procurement power from established compounders toward agile manufacturers achieving quality parity without historical tooling burdens.
Pricing Analysis
Predictive maintenance service contracts and telemetry-enabled lifecycle partnerships now drive lifetime value capture beyond transactional cover sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by EN 124 certification grade and REACH SVHC disclosure completeness. Cost compression in standard-grade composites is intensifying because Turkish and Vietnamese scrap-advantaged metal fabricators undercut non-metallic alternatives in Middle Eastern and Southeast Asian bids. Municipal utilities in Germany absorb premium pricing for recycled-content specifications, while price-sensitive private contractors in emerging corridors prioritize upfront capital cost minimization.
Supply Chain Analysis
Inventory buffers for glass-reinforced polyester and vinyl ester resins have shortened as petrochemical feedstock volatility forces just-in-time sourcing discipline. Manufacturing concentrates in Germany, China, and the United States, with pultruded fiberglass production anchoring in the Rhine-Ruhr and Bavaria regions. Raw material sourcing draws from crude oil derivatives for thermoset resins, recycled steel scrap for metal fabricators, and continuous glass fiber from captive suppliers. Single-source vulnerability in specialized fire-retardant resin formulations threatens delivery timelines for infrastructure-grade orders. Distribution runs through municipal procurement offices, industrial facility operators, and specialized civil engineering contractors with certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German municipal utilities and Indian smart city authorities with pre-qualification mandates, fragmenting the supplier base into certified tiers and uncertified price competitors.
For Market Incumbents: Fortify specification authority by deepening backward integration into pultruded fiberglass production and securing exclusive REACH SVHC disclosure partnerships with raw material suppliers. Automated resin-transfer molding entrants threaten margin pools in mid-grade segments; incumbents must anchor premium positioning through proprietary fire-retardant formulations and predictive maintenance telemetry bundling. For New Entrants and Emerging Players: Differentiate on rapid-installation modular systems targeting São Paulo and Mexico City urban retrofit corridors where tool-free deployment compresses street closure windows. The most penetrable white-space sits in corrosion-resistant specifications for coastal desalination plants and chemical processing facilities underserved by legacy metal fabricators. A go-to-market angle bundling RFID-embedded covers with digital twin integration partnerships bypasses entrenched supplier relationships with asset owners. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors automated mid-scale manufacturers with in-house compounding capabilities over capital-heavy legacy specialists. Long-term viability over the next decade hinges on positioning within recycled-content composite supply chains aligned with EU Green Deal procurement mandates. The signal to watch is BIS IS 1726 certification timeline compression in India, which would accelerate filtration of uncertified suppliers and concentrate value among pre-qualified compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pultruded Fiberglass | Captive resin supply secures REACH compliance and insulates against petrochemical volatility. |
| RFID and Load-Sensor Technology Embedding | Telemetry partnerships with Sydney Water and Singapore utilities shift procurement toward lifecycle value. |
| Recycled-Content Composite Capacity Expansion | EU Green Deal mandates in Germany redirect public spending toward certified circular economy suppliers. |
| Modular Rapid-Installation System Development | Tool-free configurations address São Paulo and Mexico City urban retrofit demand for minimal-disruption deployment. |
| Fire-Retardant Formulation R&D Investment | ASTM E-84 smoke index compliance opens chemical plant and refinery specifications in Europe and North America. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, civil engineering contractors, composite manufacturing plant managers, and airport infrastructure planners. Secondary validation drew from EN 124 certification databases, BIS IS 1726 regulatory filings, EU Green Deal procurement disclosures, and customs trade data for glass fiber and resin imports. Bottom-up project pipeline analysis across smart city corridors in India, Germany, and Brazil was triangulated against top-down composite and metal fabrication capacity estimates.
Across the analysis window, volume and value outputs reflect segmentation modeling across material specifications, load-rating tiers, installation methods, and regional regulatory clusters. CAGRs were derived from weighted projections of municipal capital expenditure cycles, airport infrastructure modernization timelines, and industrial facility corrosion-resistant replacement demand. Industry-specific forecast inputs include petrochemical feedstock price trajectory assumptions and EN 124 certification queue duration estimates.
Material uncertainties — abrupt petrochemical price spikes, BIS enforcement intensity variations, and REACH SVHC list expansions — sit outside the modeled envelope. Forecasts reflect documented assumptions about automation adoption rates and recycled-content mandate implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Sheet Metal Market
Construction and Engineering
North America Concrete Conditioner Market
Construction and Engineering
Bearing Installation Tool Kit Market
Construction and Engineering
Noise Insulation Jackets Market
Construction and Engineering
Mallets and Sledgehammers Market
Construction and Engineering
Recycled Concrete Aggregates Market
Construction and Engineering
Mexico Flexible Concrete Vibrator Market
Construction and Engineering
Saudi Arabia Prefabricated Buildings Market
Construction and Engineering
North America Construction Equipment Market
Construction and Engineering
Rock Drill Shank Adaptor Market
Construction and Engineering
Thread Milling Machine Market
Construction and Engineering
Global Radiant Floor Heating Market
Construction and Engineering
Wood Router Market
Construction and Engineering
Road Construction Machinery Market
Construction and Engineering
Canada Forklift Market
Construction and Engineering
Loader Bucket Attachments Market