
 Drum Handling Equipment Market | 2026-2036
Drum Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Handling Equipment Market Foresight
China is fragmenting as domestic drum handling equipment makers expand foundry and fabrication capacity across Shandong and Jiangsu provinces. Jungheinrich AG leverages its European distribution network to sustain premium positioning in automated drum transport systems. Morse Manufacturing Co. Inc. specializes in mechanical drum lifters and occupies a defensible niche in North American chemical processing facilities.
Drum handling equipment encompasses mechanical and powered devices designed to lift, tilt, rotate, and transport cylindrical containers typically ranging from 30 to 55 gallons in capacity, utilizing steel or aluminum frames with hydraulic, electric, or manual actuation to manipulate loads up to 3,000 lbs in industrial environments. Electric drum manipulators lead product type demand as facilities automate material handling workflows to reduce ergonomic injuries and throughput bottlenecks. Steel construction dominates material selection due to its load-bearing reliability in corrosive chemical industry settings where drum integrity failures carry severe operational consequences.
OSHA workplace ergonomics standards and EU machinery directives under CE marking requirements compel manufacturers to integrate guarding systems and load-limiting controls into drum lifter designs. EPA spill prevention regulations and REACH chemical handling protocols further shape equipment specifications for secondary containment and sealed drum engagement. Stakeholders must monitor evolving carbon border adjustments and raw material traceability mandates that threaten to restructure supplier qualification criteria across major industrial economies.
Market Dynamics
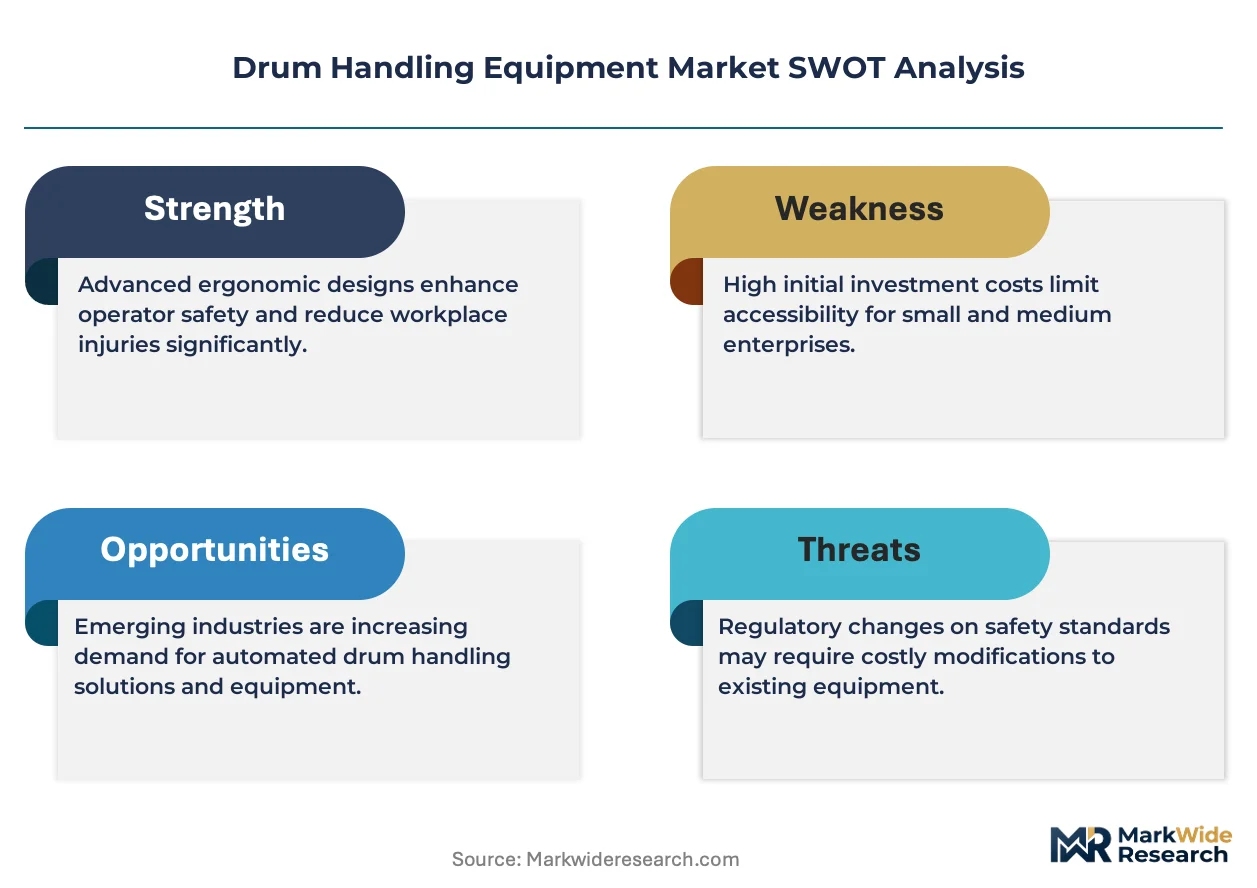
OSHA workplace ergonomics standards and EU machinery directives are compressing design cycles for drum handling equipment manufacturers, forcing rapid integration of load-limiting controls and guarding systems into existing product architectures.
Growth Catalysts
- EU machinery safety directives:CE marking requirements mandate automated guarding systems in drum lifters, compelling chemical processors across Germany and France to upgrade mechanical equipment.
- Petrochemical corridor expansion:Gulf Coast facilities in Texas and Louisiana are automating drum transport workflows to reduce ergonomic injuries in high-throughput environments.
- Electric drum manipulators:These powered systems eliminate manual lifting in corrosive chemical handling, addressing EPA spill prevention protocols while improving throughput.
Market Restraints
- Steel price volatility:Load-bearing frame construction depends on alloy steel inputs subject to carbon border adjustment fluctuations, squeezing margin structures for fabricators.
- Foundry concentration in Shandong:Domestic Chinese equipment makers control casting capacity, creating supply vulnerability for Western manufacturers without captive metalworking.
- REACH chemical handling protocols:Secondary containment specifications add engineering complexity and certification delays to sealed drum engagement systems.
Strategic Opportunities
- India chemical processing:BIS standards adoption and PLI scheme incentives for manufacturing automation create entry points for drum handling equipment in specialty chemical plants.
- Carbon border adjustments:Raw material traceability mandates in the EU and US are restructuring supplier qualification criteria, favoring equipment makers with documented steel sourcing.
- Autonomous mobile robots:Convergence of AMR navigation with drum manipulator attachments enables unmanned transport in hazardous material zones previously requiring manual intervention.
Industry Challenges
- CE marking timeline compression:Machinery directive compliance requires third-party certification for guarding systems, extending product launch cycles by six to nine months.
- Legacy system integration:Automated drum lifters must interface with existing warehouse management software, creating protocol mismatch friction in brownfield chemical facilities.
- Hydraulic technician scarcity:Powered equipment maintenance demands specialized fluid power expertise that chemical plant maintenance teams rarely possess in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Handling Equipment Market |
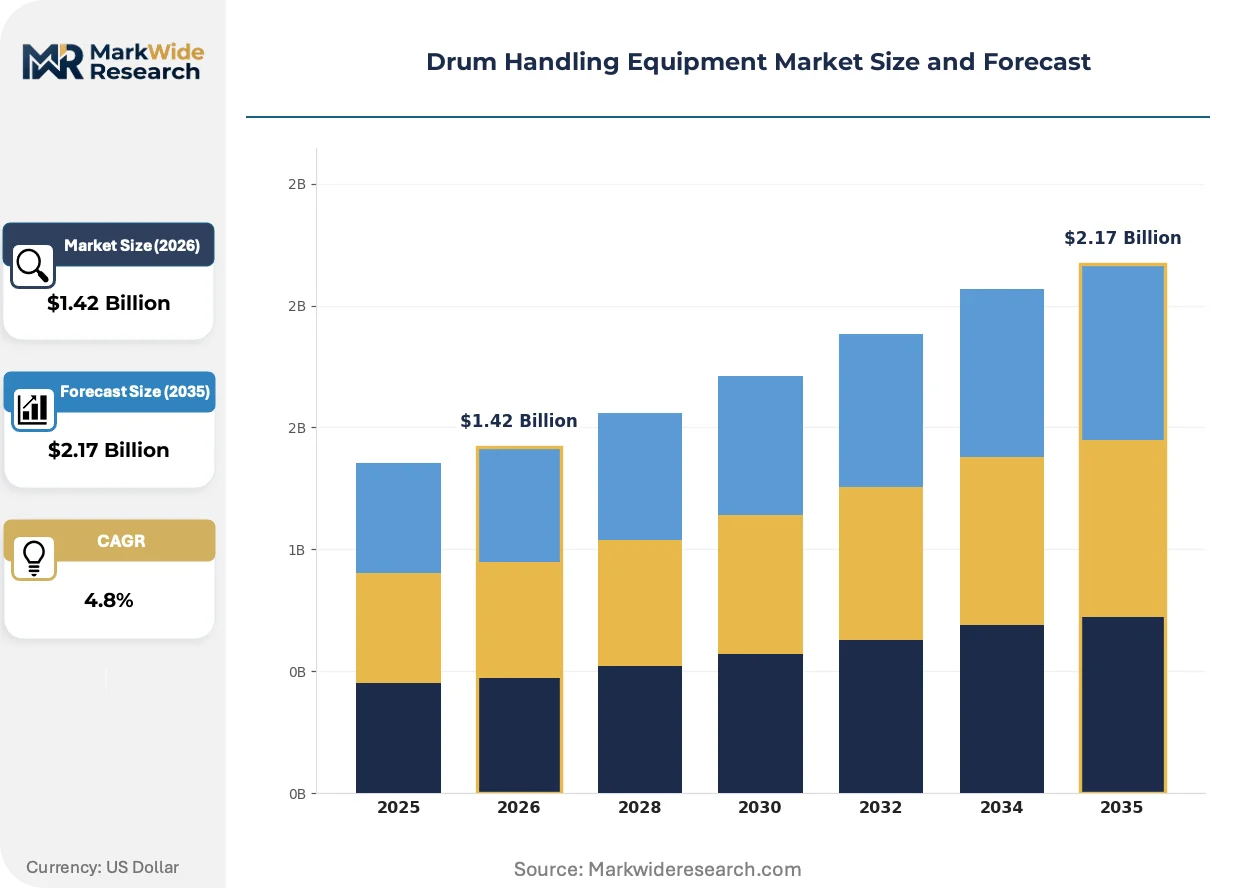
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Drum Lifters, Electric Drum Manipulators, Drum Tilters, Drum Rollers End User: Chemical Industry, Manufacturing Plants, Warehousing, Logistics Providers Capacity: 500 lbs, 1000 lbs, 2000 lbs, 3000 lbs Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | Jungheinrich AG, Crown Equipment Corporation, Komatsu Ltd., Beumer Group GmbH, SSI SCHAEFER Group, Wesco Industrial Products LLC, Hyster-Yale Group Inc., Morse Manufacturing Co. Inc., KION Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Handling Equipment Market Shifts & Advancements
Automation architectures are displacing mechanical drum handling across hazardous material environments, with sensor-integrated systems now standard in new chemical plant construction. Three developments are compressing competitive timelines.
Sensor-fusion drum positioners combining LiDAR, load cells, and torque feedback are rendering obsolete manual alignment procedures in high-volume chemical processing. BASF and Dow facilities in Germany and Texas are deploying these systems at scale. The technology is rendering obsolete the traditional operator-in-the-loop drum engagement model, compressing training requirements while eliminating pinch-point injuries.
REACH chemical handling protocols are mandating sealed drum engagement and secondary containment specifications across EU chemical facilities. Equipment manufacturers must redesign gripper mechanisms and spill containment trays to satisfy ECHA documentation requirements. Stainless steel construction with certified welds is displacing painted carbon steel in premium equipment tiers serving pharmaceutical and fine chemical verticals.
Leasing arrangements for drum handling equipment are displacing capital purchase models among mid-sized chemical processors. Hyster-Yale and equipment finance providers are bundling maintenance and certification services into per-drum-moved contracts. This shift is most visible in US Gulf Coast independent chemical distributors lacking dedicated maintenance departments.
Drum Handling Equipment Market Segmentation
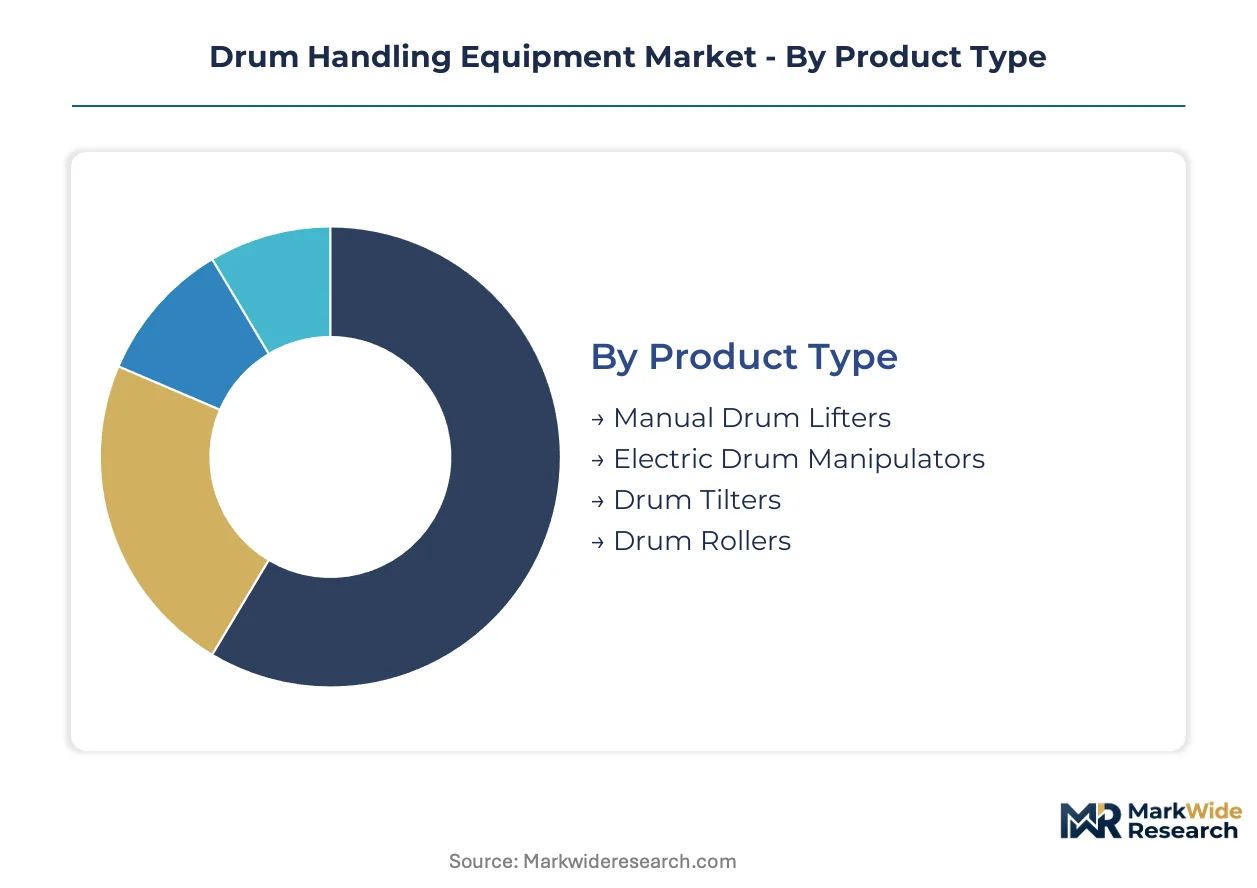
Drum handling equipment segmentation reveals divergent replacement cycles across product categories. Electric systems turn over every seven to ten years under heavy chemical plant utilization. Manual equipment persists fifteen to twenty years in low-throughput warehousing environments.
Product Type:
Cycle times vary dramatically: electric drum manipulators require component refresh every eight years, while manual lifters depreciate over two decades in intermittent-use settings.
- Manual Drum Lifters:Lever-actuated mechanical devices utilizing ratchet mechanisms and manual hydraulic pumps to raise drums up to 1,000 lbs. Demand concentrates in small-batch chemical processors across India and Southeast Asia where capital constraints limit automation investment and BIS standards enforcement remains uneven.
- Electric Drum Manipulators:Powered systems employing servo motors and programmable logic controllers to lift, rotate, and position drums up to 3,000 lbs with precision. Facilities along the US Gulf Coast petrochemical corridor are standardizing on these units to satisfy OSHA ergonomic mandates and reduce workers' compensation exposure in high-throughput drum decanting operations.
- Drum Tilters:Pivot-frame devices enabling controlled pouring from 55-gallon drums at angles up to 180 degrees. Found in food additive and pharmaceutical manufacturing where FDA contamination protocols require sealed transfer.
- Drum Rollers:Cylindrical conveyance platforms for horizontal drum movement across flat surfaces. Common in third-party logistics warehouses serving chemical distributors with low vertical lift requirements.
Manual drum lifters dominate installed base. Electric drum manipulators are where expansion concentrates.
End User:
Cost tiers separate this category: chemical industry buyers pay premium prices for corrosion-resistant specifications, while logistics providers minimize acquisition spend on intermittent-use equipment.
- Chemical Industry:Facilities handling acids, solvents, and petrochemical feedstocks require sealed drum engagement systems with secondary containment trays. EPA spill prevention regulations and REACH protocols mandate stainless steel construction and certified weld documentation, pushing procurement toward premium-tier suppliers with ECHA compliance records.
- Manufacturing Plants:Automotive and electronics producers utilize drum handling for lubricants, coatings, and process chemicals. These buyers prioritize integration with existing automated guided vehicle networks and warehouse management software protocols.
- Warehousing:General storage operations emphasize acquisition cost minimization over specification sophistication. Equipment here sees lower duty cycles and deferred maintenance schedules.
- Logistics Providers:Third-party operators serving multiple chemical shippers demand rapid reconfiguration between drum sizes and containment requirements. Leasing arrangements predominate in this segment.
Chemical industry specifications command price premiums. Logistics providers represent the volume expansion path.
Capacity:
Application intensity determines specification: high-volume decanting operations demand maximum rated load, while sampling and laboratory transfer utilize lighter capacities.
- 500 lbs:Bench-scale and pilot plant operations handling sample drums and specialty chemical batches. Common in pharmaceutical development facilities.
- 1000 lbs:Standard 55-gallon drum handling with moderate safety margin for partial fills. The default specification for general chemical warehousing.
- 2000 lbs:Reinforced frames for dense materials and double-drum lifts. Favored by petrochemical processors moving lubricant base stocks and heavy process intermediates.
- 3000 lbs:Maximum-duty construction with hardened steel frames and oversized hydraulic cylinders. Deployed in refinery maintenance operations and bulk chemical transloading terminals where single-point failure carries catastrophic cost.
1000 lbs equipment dominates current installations. 3000 lbs systems are climbing the fastest as facilities consolidate drum movements.
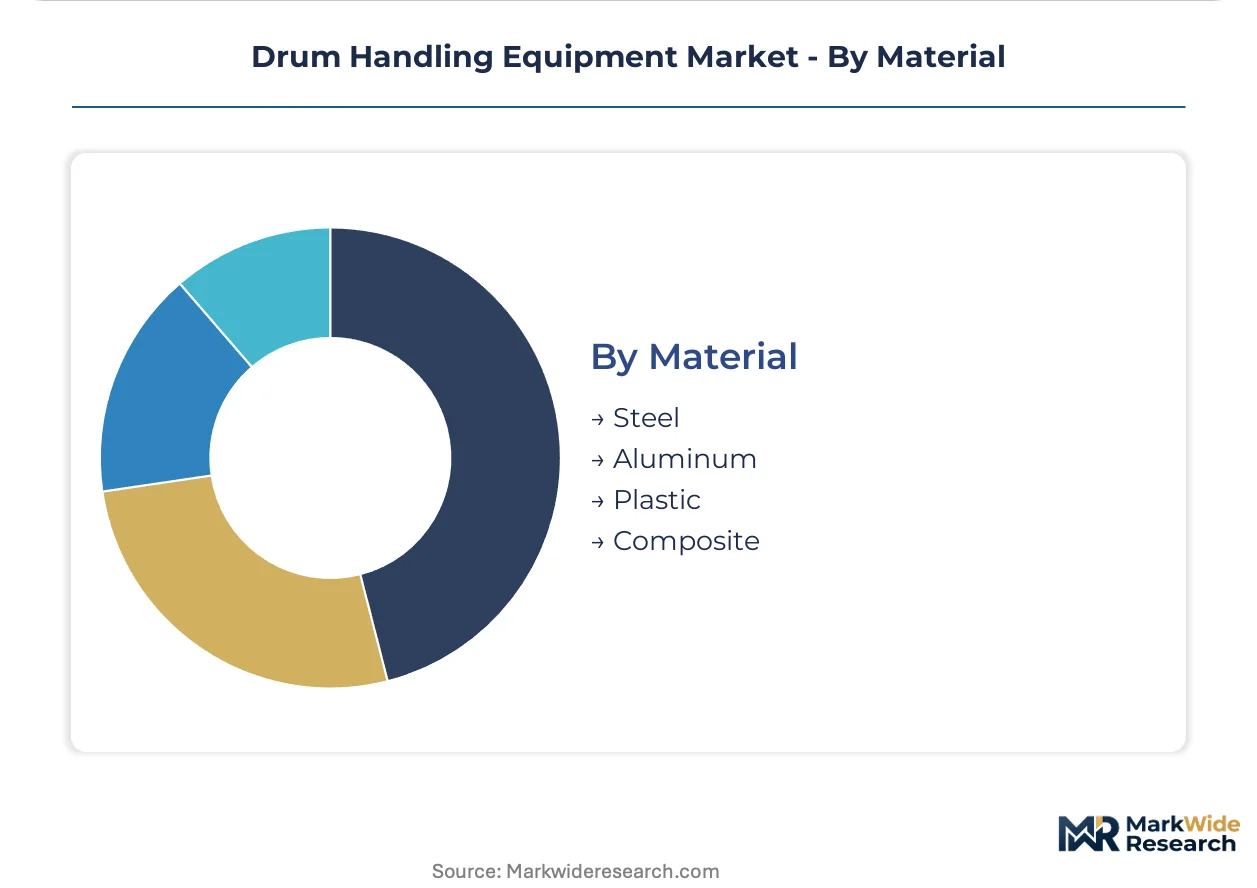
Material:
Supply concentration shapes availability: Shandong and Jiangsu foundries control steel casting capacity, while aluminum extrusion depends on energy-intensive smelting vulnerable to carbon border adjustments.
- Steel:Alloy and stainless grades provide load-bearing reliability in corrosive environments. CE marking requirements and EPA spill prevention regulations favor documented weld certification available primarily from European and North American fabricators with captive metallurgical testing.
- Aluminum:Lightweight extrusions reduce operator fatigue in manual equipment and enable higher payload ratios in mobile systems. Demand concentrates in food-grade and pharmaceutical applications where surface contamination risks prohibit painted carbon steel.
- Plastic:Polymer frames for explosive atmosphere zones where spark generation must be eliminated. Limited to lighter capacities below 500 lbs.
- Composite:Fiber-reinforced structures combining strength-to-weight advantages with corrosion immunity. Emerging in offshore platform and marine chemical handling where salt exposure degrades conventional metals.
Steel construction dominates installed base. Aluminum is gaining share fastest in pharmaceutical and food verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American drum handling equipment demand, channeling petrochemical feedstocks through the continent's densest concentration of refineries and specialty chemical plants.
United States
Gulf Coast petrochemical corridor expansion and OSHA ergonomic mandates drive electric drum manipulator procurement. EPA spill prevention regulations require secondary containment integration in new installations. Texas and Louisiana facilities along the Houston Ship Channel are automating drum transport workflows to reduce workers' compensation exposure.
Germany
Chemical plant automation investments and REACH compliance documentation requirements sustain premium equipment demand. CE marking mandates under EU machinery directives compress design cycles for guarding system integration. BASF and Dow facilities in Ludwigshafen and Leverkusen deploy sensor-fusion drum positioners at scale.
China
Domestic foundry capacity expansion across Shandong and Jiangsu provinces fragments equipment supply. GB standards and dual carbon goals reshape steel sourcing requirements for fabricators. Yangtze River Delta chemical clusters absorb locally manufactured drum lifters as domestic makers upgrade casting and fabrication capabilities.
India
BIS standards adoption and PLI scheme incentives for manufacturing automation create specialty chemical plant entry points. CDSCO pharmaceutical regulations and state-level industrial policies favor documented equipment certification. Gujarat and Maharashtra chemical corridors show concentrated demand for corrosion-resistant drum handling specifications.
Japan
Automotive and electronics manufacturing sustain precision drum handling requirements for coatings and process chemicals. METI industrial efficiency directives and JIS standards enforce ergonomic design specifications. Kansai and Chubu industrial zones maintain steady replacement cycles for automated drum transport systems.
Drum Handling Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a fragmented supply structure. The vendor base distributes across three tiers: multinational material handling conglomerates with captive distribution networks, regional fabricators serving chemical corridor clusters, and specialized drum equipment makers occupying narrow vertical niches. Consolidation pressure concentrates at the premium tier where CE marking compliance and documented weld certification create qualification barriers. Geographic expansion and strategic partnerships constitute the dominant competitive vectors as fabricators seek to decouple from Shandong foundry concentration.
Within the multinational conglomerate tier, Jungheinrich AG and KION Group AG exemplify platform-scale positioning through European distribution network leverage. Hyster-Yale Group Inc. occupies a distinct archetype bundling equipment finance and maintenance services into operational contracts. Morse Manufacturing Co. Inc. represents the specialist fabricator model, anchoring a defensible niche in North American chemical processing facilities through mechanical drum lifter concentration.
| Leading Market Players |
|---|
| Jungheinrich AG |
| Crown Equipment Corporation |
| Komatsu Ltd. |
| Beumer Group GmbH |
| SSI SCHAEFER Group |
| Wesco Industrial Products LLC |
| Hyster-Yale Group Inc. |
| Morse Manufacturing Co. Inc. |
| KION Group AG |
| Others |
Supply & Pricing Matrix
Shandong and Jiangsu foundries control steel casting capacity for drum handling equipment frames, concentrating margin capture upstream while downstream fabricators in Germany and the US compete on certification documentation and guarding system integration. This geographic asymmetry forces Western manufacturers to absorb alloy steel price volatility or surrender margin to domestic Chinese competitors with captive metallurgical supply.
Pricing Analysis
CE marking requirements under EU machinery directives dictate the pricing tier structure across the drum handling equipment market. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel systems with ECHA-compliant weld documentation from painted carbon steel units and basic mechanical lifters. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese makers leverage foundry proximity to undercut Western fabricators on alloy steel frame production. Logistics providers represent the most price-sensitive buyer segment, while chemical processors in the US Gulf Coast demonstrate lowest sensitivity due to workers' compensation cost avoidance priorities.
Supply Chain Analysis
Alloy steel feedstock draws from foundry concentration in China, Germany, and the US, with Shandong province casting capacity serving domestic equipment makers and export markets alike. Hydraulic cylinder components, servo motors, and programmable logic controllers rest on supply lines anchored in Japan, South Korea, and Taiwan. Single-source vulnerability in Chinese foundry output creates structural exposure for Western manufacturers lacking backward integration into metallurgical production. Distribution runs through regional equipment dealers serving chemical corridor clusters, with direct OEM relationships dominating high-volume petrochemical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drum handling equipment sits in early-cycle expansion as OSHA ergonomic mandates and EU machinery directives force mechanical-to-electric conversion across installed bases. Automation tailwinds in hazardous material handling justify capacity positioning ahead of replacement wave concentration.
For Market Incumbents: Entrench certification advantage by deepening captive weld documentation capabilities and expanding guarding system engineering teams to compress CE marking timelines. Shandong foundry concentration among domestic Chinese competitors threatens margin structures in standard-tier equipment, making European and North American fabricators' metallurgical testing investment a critical defensive lever. Prioritize aftermarket service contract attachment to electric drum manipulator placements along the US Gulf Coast petrochemical corridor.
For New Entrants and Emerging Players: Establish a beachhead in India's specialty chemical processing segment where BIS standards adoption and PLI scheme incentives create qualification windows before incumbent certification documentation saturates the market. Gujarat and Maharashtra chemical corridors offer penetrable geography with corrosion-resistant specification demand that domestic fabricators struggle to satisfy. Pursue leasing arrangement partnerships with equipment finance providers to bypass capital purchase barriers among mid-sized chemical distributors.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap fabricators with documented ECHA compliance records and captive distribution networks serving dense chemical corridor geographies. Long-term viability over a five-to-ten-year horizon favors equipment makers with backward integration into steel sourcing that can absorb carbon border adjustment impacts. Monitor autonomous mobile robot convergence with drum manipulator attachments as the inflection signal for platform-level consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Sourcing | Carbon border adjustments in the EU and US favor fabricators with documented alloy traceability and captive metallurgical testing. |
| CE Marking Acceleration Program | Machinery directive compliance timelines compress competitive positioning for guarding system certification in German chemical plants. |
| Leasing Model Expansion | Per-drum-moved contracts with bundled maintenance address capital constraints among US Gulf Coast independent chemical distributors. |
| Sensor-Fusion Positioner Development | LiDAR and load cell integration eliminates manual alignment procedures at BASF and Dow facilities in Ludwigshafen and Texas. |
| India Market Entry Partnership | BIS standards adoption and PLI incentives in Gujarat create early-mover positioning before domestic fabrication capacity matures. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at chemical processing facilities and material handling distributors, combined with secondary validation through customs and trade data, SEC filings from publicly traded equipment manufacturers, OSHA enforcement records, and ECHA REACH documentation databases. Bottom-up equipment shipment tallies by product type and capacity tier were triangulated against top-down petrochemical capital expenditure tracking and chemical industry facility automation surveys.
Forecast inputs span electric drum manipulator replacement cycles, manual lifter depreciation schedules in intermittent-use warehousing, and REACH protocol expansion timelines across EU chemical facilities. Modeled dimensions include product type segmentation, end-use industry vertical, capacity rating, construction material grade, and regional regulatory cluster adoption patterns. CAGRs were derived from installed base turnover analysis and penetration rate assumptions for automation displacement of mechanical systems. Industry-specific inputs incorporate OSHA ergonomic mandate enforcement intensity and carbon border adjustment implementation scope.
Stress conditions across steel price volatility, CE marking timeline extensions, and hydraulic technician labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding chemical plant automation investment continuity and regulatory compliance cost pass-through elasticity. Cross-checking against ACC and Cefic chemical industry capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Industrial Lift Ladder Market