
 Modular Self-Contained Aisle and Racking Systems Market | 2026-2036
Modular Self-Contained Aisle and Racking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Self-Contained Aisle and Racking Systems Market Foresight
Single-source procurement for warehouse infrastructure is rebalancing toward multi-source strategies as buyers diversify supply risk. Mecalux, S.A. anchors European manufacturing scale through captive steel fabrication facilities. Schneider Electric SE differentiates via integrated power and thermal management within racking enclosures. Daifuku competes in automated retrieval integration, pairing modular structures with robotics.
Modular self-contained aisle and racking systems are engineered steel or aluminum frameworks designed for configurable bay widths, load ratings typically spanning 2,000–30,000 pounds per level, and aisle widths optimized for forklift or automated guided vehicle clearance. These assemblies serve commercial and industrial facilities requiring dense, reconfigurable storage with minimal facility modification. Mobile Shelving commands premium positioning in archival and pharmaceutical verticals where floor-space efficiency determines project economics. Pallet Rack dominates volume throughput in food and beverage distribution, where standardization reduces installation labor. Steel as a material category sustains margin pools given raw material hedging capabilities and established recycling infrastructure.
FDA facility guidelines for pharmaceutical warehousing influence cleanroom-adjacent racking specifications, while OSHA structural integrity standards mandate periodic load testing in US distribution networks. The EU Green Deal embodied carbon requirements are pressuring aluminum and steel suppliers to disclose lifecycle emissions data for racking components. Buyers must evaluate supplier certification breadth against evolving multi-jurisdiction compliance obligations.
Market Dynamics
E-commerce fulfillment networks are compressing installation timelines for warehouse infrastructure, forcing modular racking suppliers to pre-engineer configurable bay assemblies that deploy without facility modification. This velocity imperative is restructuring competitive advantage around fabrication lead time rather than unit economics alone.
Growth Catalysts
- FDA pharmaceutical warehousing guidelines:Cleanroom-adjacent racking specifications in US drug distribution centers are mandating corrosion-resistant finishes and sealed joint designs that modular systems deliver faster than welded alternatives.
- Automotive parts distribution in Germany:High-density storage configurations for just-in-sequence assembly lines are specifying adjustable beam elevations and concentrated load ratings above 20,000 pounds per level.
- OSHA structural integrity mandates:Periodic load testing requirements in US distribution networks are accelerating replacement cycles for legacy bolted rack systems with certified modular alternatives.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs swing with energy pricing and scrap availability, compressing fabrication margins for captive steel producers.
- European aluminum smelter concentration:Primary aluminum supply concentrates in Nordic and Icelandic hydro-powered facilities, exposing racking suppliers to carbon border adjustment mechanism exposure.
- Seismic zone engineering complexity:California and Japan building codes require site-specific structural calculations that delay modular system standardization.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for logistics infrastructure are creating specification pull for AGV-compatible aisle widths in Mumbai and Delhi NCR fulfillment hubs.
- EU Green Deal embodied carbon tracking:Lifecycle emissions disclosure mandates are favoring domestic steel recyclers with verified Environmental Product Declarations over imported aluminum extrusions.
- Cold chain convergence with robotics:Integration of automated storage and retrieval systems with insulated modular enclosures is opening pharmaceutical and perishable food verticals previously served by fixed rack installations.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction load-bearing approvals from TÜV, UL, and BSI require parallel testing tracks that strain engineering bandwidth.
- Legacy WMS integration friction:Warehouse management software protocols from the 1990s lack API connectivity with modern racking sensor arrays, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Self-Contained Aisle and Racking Systems Market |
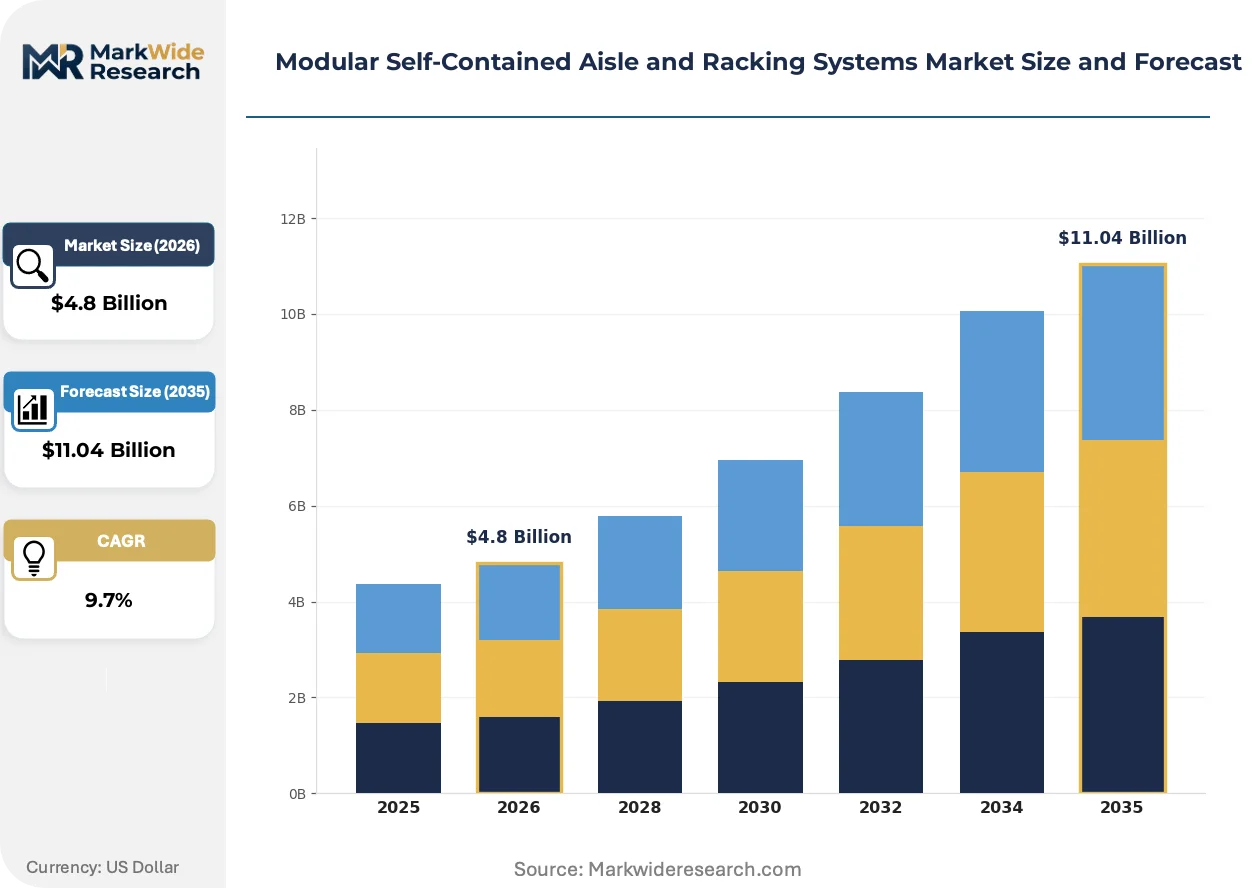
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Shelving, Static Rack, Multi-Tier Rack, Pallet Rack End User: Retail Stores, Warehouses, Distribution Centers, Workspaces Material: Steel, Aluminum, Plastic, Composite Installation Type: Permanent, Demountable, Customizable, Modular |
| Companies Covered | Vertiv Holdings Co., Schneider Electric SE, Eaton Corporation plc, Rittal GmbH & Co. KG, Panduit Corp., Emerson Electric Co., Mecalux, S.A., Daifuku, SSI Schaefer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Self-Contained Aisle and Racking Systems Market Shifts & Advancements
Automation integration is restructuring how modular racking systems are specified, sold, and commissioned. Buyers now evaluate rack assemblies as robotics infrastructure rather than static storage, shifting supplier relationships toward system integration partnerships.
Light-gauge cold-formed steel rack uprights are replacing traditional hot-rolled structural sections in bay heights below 20 feet. Third-party logistics operators in the Netherlands and Belgium are specifying these profiles for rapid-reconfiguration e-commerce facilities. The technology is decentralizing fabrication capacity toward regional roll-forming operations that serve 200-mile radii, compressing delivery schedules from weeks to days.
EU Green Deal embodied carbon requirements are pressuring aluminum and steel suppliers to disclose lifecycle emissions data for racking components. Industrial buyers in Germany and France are now requiring Environmental Product Declarations as gate criteria for tender participation. Pharmaceutical and food-grade warehousing segments are responding fastest, embedding carbon thresholds into specification templates ahead of regulatory mandates.
Multi-source procurement strategies are displacing single-source infrastructure contracts among large warehouse operators. Risk-conscious buyers in the United States and United Kingdom are qualifying secondary fabrication sources for identical rack profiles, unbundling engineering from manufacturing. This pattern is most visible among grocery and consumer electronics distributors with network-scale deployment schedules spanning multiple continents.
Modular Self-Contained Aisle and Racking Systems Market Segmentation
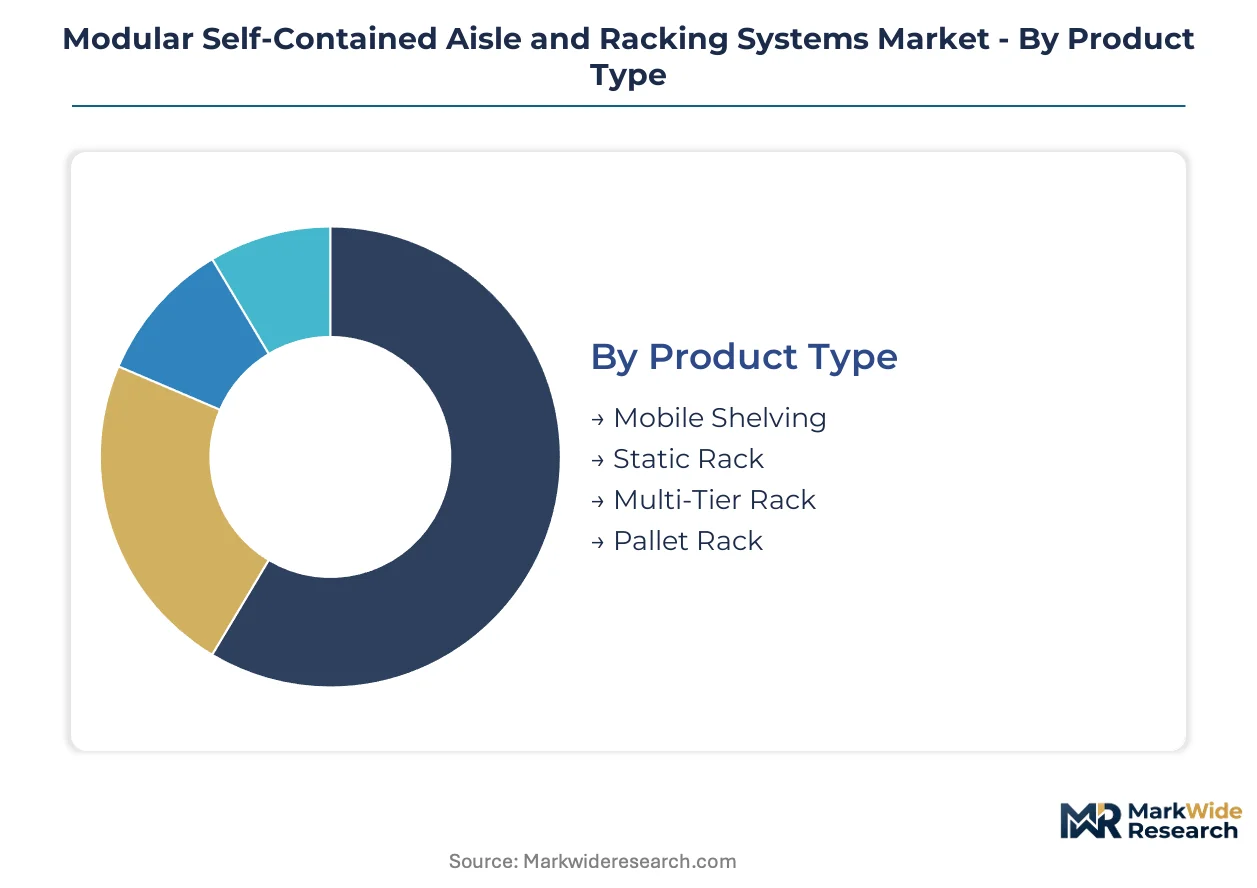
Segmentation in modular racking systems reveals how integration depth varies from standalone archival units to embedded automation infrastructure. Buyers specify differently when systems must interface with robotics versus static storage applications.
Product Type:
Integration depth splits this category between standalone mobile systems and fixed assemblies designed for automated retrieval embedding.
- Mobile Shelving:Rail-mounted carriages with hand-crank or electric drive mechanisms compress aisle spacing by eighty percent versus static alternatives. Archival facilities in Germany and pharmaceutical cleanrooms in Switzerland specify these for floor-space economics where land costs dominate project returns. FDA corrosion-resistant finish mandates for drug distribution centers accelerate modular mobile system adoption over welded fixed installations.
- Pallet Rack:Beam-and-upright assemblies with standardized 2,000–30,000 pound load ratings per level form the volume backbone of food and beverage distribution. Third-party logistics operators in the Netherlands specify these for rapid-reconfiguration e-commerce facilities where bay widths must adapt to SKU profile shifts. OSHA periodic load testing requirements in US networks compress replacement cycles toward certified modular alternatives.
- Static Rack:Fixed-position shelving for light-duty commercial and industrial storage without reconfiguration requirements.
- Multi-Tier Rack:Elevated platform-integrated structures maximizing vertical cube utilization in high-rent urban logistics locations.
Volume placements concentrate in Pallet Rack; the faster expansion belongs to Mobile Shelving.
End User:
Cost tier stratification separates specification intensity, with pharmaceutical and automotive verticals commanding premium engineering against commodity retail deployments.
- Distribution Centers:High-velocity fulfillment nodes specifying AGV-compatible aisle widths and sensor-integrated rack assemblies. Mumbai and Delhi NCR hubs under India's PLI scheme for logistics infrastructure are pulling specification intensity for automated retrieval integration. EU Green Deal embodied carbon disclosure requirements favor domestic steel recyclers with verified Environmental Product Declarations.
- Warehouses:General storage facilities spanning ambient, refrigerated, and frozen environments with variable throughput requirements.
- Retail Stores:Back-of-house stockrooms and showroom displays with aesthetic finish requirements and moderate load ratings.
- Workspaces:Office and light industrial environments requiring reconfigurable storage without material handling equipment access.
Specification value concentrates in Distribution Centers; Workspaces expand most quickly from automation spillover into adjacent commercial segments.
Material:
Supply concentration and carbon accountability are rebalancing procurement toward recycled steel with verified lifecycle data against aluminum exposure to border adjustment mechanisms.
- Steel:Hot-rolled structural and cold-formed light-gauge profiles dominating load-bearing applications. Captive fabrication facilities at major European producers hedge raw material volatility through vertical integration into scrap recycling and energy-intensive rolling operations. EU Green Deal requirements pressuring disclosure of embodied carbon favor domestic recyclers over imported primary aluminum.
- Aluminum:Extruded profiles for corrosion-resistant and weight-sensitive applications in pharmaceutical and food-grade environments.
- Plastic:Polymer shelving for wet environments, cleanrooms, and chemical storage where metallic corrosion risks exceed load requirements.
- Composite:Fiber-reinforced materials for specialized applications requiring non-conductive or radar-transparent properties.
Volume concentrates in Steel; Aluminum gains share fastest from cleanroom-adjacent pharmaceutical warehousing expansion.
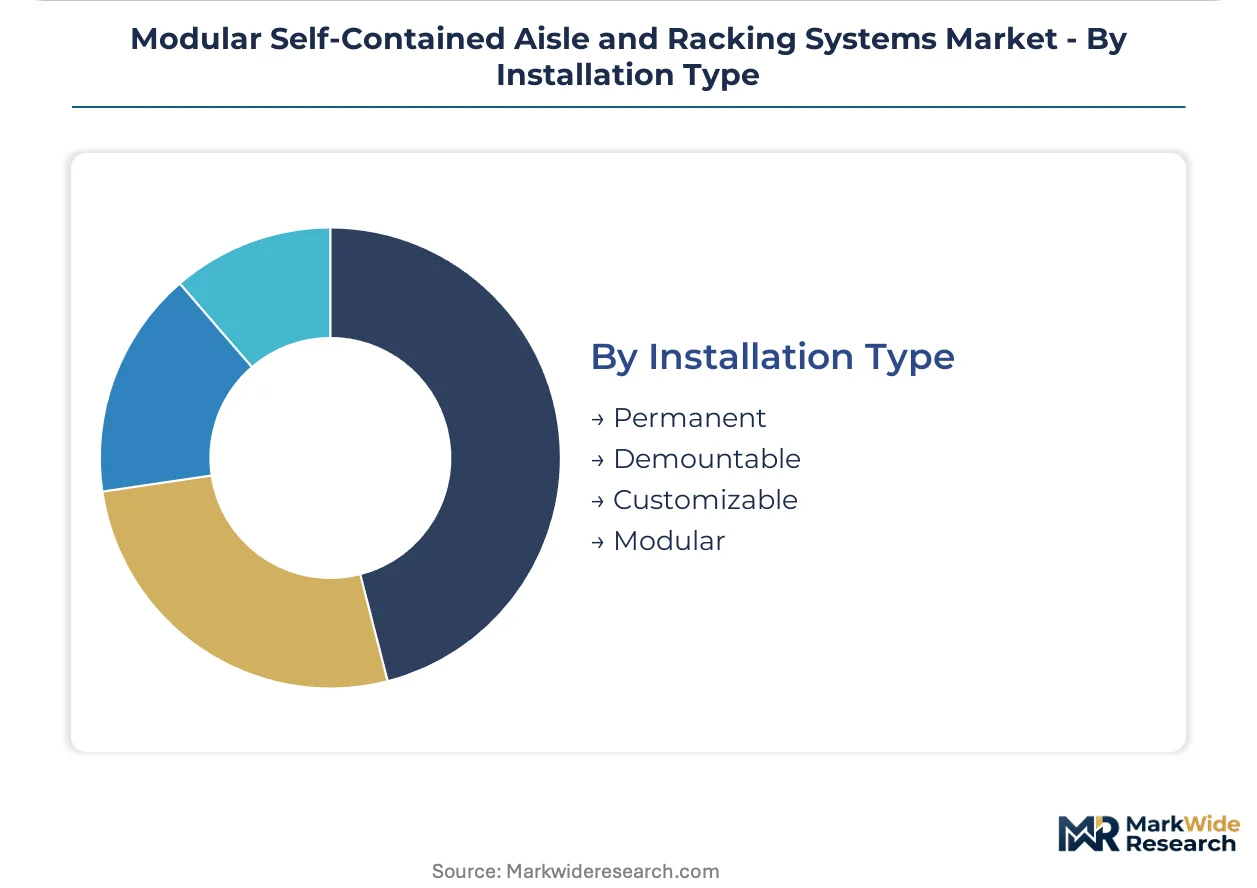
Installation Type:
Maturity gradients separate legacy permanent installations from emerging demountable systems serving velocity-pressured e-commerce networks.
- Demountable:Boltless or tool-free assemblies enabling rapid deployment, relocation, and reconfiguration without facility modification. E-commerce fulfillment networks in Belgium and the Netherlands compress installation timelines by specifying pre-engineered bay assemblies. Light-gauge cold-formed uprights in heights below twenty feet decentralize fabrication toward regional roll-forming operations.
- Modular:Standardized component platforms with configurable dimensions and accessory ecosystems.
- Customizable:Engineer-to-order systems with site-specific structural calculations for seismic zones or unusual load concentrations.
- Permanent:Welded or chemically anchored installations with no reconfiguration capability, now declining in new specification.
Volume concentrates in Modular; Demountable climbs the fastest from e-commerce velocity imperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scrap steel recycling clusters in Germany's Ruhr Valley anchor European fabrication capacity for modular racking systems. Automotive parts distribution centers in Stuttgart and Wolfsburg pull specification intensity for high-density storage configurations. This regional production base supplies adjacent markets while responding to distinct regulatory pressures across national boundaries.
United States
E-commerce fulfillment networks in California and Texas compress installation timelines for warehouse infrastructure. OSHA structural integrity mandates require periodic load testing in distribution networks, accelerating replacement cycles toward certified modular alternatives. The Inland Empire logistics cluster east of Los Angeles specifies AGV-compatible aisle widths for rapid-growth fulfillment nodes.
Germany
Automotive parts distribution centers for just-in-sequence assembly lines demand adjustable beam elevations and concentrated load ratings above 20,000 pounds per level. EU Green Deal embodied carbon requirements pressure steel suppliers to disclose lifecycle emissions data for racking components. Bavarian automotive clusters around Munich and Ingolstadt drive specification intensity for high-density storage.
India
PLI scheme incentives for logistics infrastructure create specification pull for AGV-compatible aisle widths in Mumbai and Delhi NCR fulfillment hubs. BIS certification requirements for structural steel products influence procurement patterns for domestic warehouse operators. The Delhi-Mumbai Industrial Corridor anchors new distribution center construction with modular system deployment.
China
Dual carbon goals under MEE supervision reshape steel procurement toward electric-arc furnace production with verified emissions data. Yangtze River Delta logistics hubs around Shanghai specify rapid-reconfiguration systems for volatile e-commerce SKU profiles. NMPA pharmaceutical warehousing guidelines in drug distribution centers mandate corrosion-resistant finishes adjacent to cleanroom environments.
Netherlands
Third-party logistics operators in the Randstad specify light-gauge cold-formed steel rack uprights for rapid-reconfiguration e-commerce facilities. REACH compliance for surface treatments influences finish specifications for food-grade warehousing applications. The Port of Rotterdam logistics cluster decentralizes fabrication capacity toward regional roll-forming operations serving 200-mile radii.
Modular Self-Contained Aisle and Racking Systems Market Competitive Landscape
Global majors compete with regional champions across fabrication scale and automation integration depth. The vendor base stratifies between captive steel producers with backward integration into scrap recycling, electrical infrastructure specialists embedding power management within racking enclosures, and automation integrators pairing modular structures with robotics. Three archetypes dominate: steel-centric fabricators hedging raw material volatility, systems integrators bundling racking with retrieval automation, and electrical specialists converging thermal and power management. Competitive moves concentrate on geographic expansion through regional roll-forming partnerships and technology licensing for seismic zone engineering.
Among European fabricators, Mecalux, S.A. occupies a position exemplifying steel-centric production scale with captive fabrication facilities. Schneider Electric SE represents the electrical infrastructure archetype, embedding power and thermal management capabilities within racking enclosures. Daifuku sits within the automation integration tier, pairing modular structural assemblies with robotics for retrieval-intensive applications.
| Leading Market Players |
|---|
| Vertiv Holdings Co. |
| Schneider Electric SE |
| Eaton Corporation plc |
| Rittal GmbH & Co. KG |
| Panduit Corp. |
| Emerson Electric Co. |
| Mecalux, S.A. |
| Daifuku |
| SSI Schaefer |
| Others |
Supply & Pricing Matrix
Hot-rolled coil price indices cascade through modular racking supply chains, compressing fabrication margins at captive steel producers while amplifying price differentiation between certified load-bearing tiers and commodity alternatives. Buyers in automotive and pharmaceutical verticals absorb premium positioning for corrosion-resistant finishes and sealed joint designs, whereas third-party logistics operators negotiate volume-based standard rack pricing.
Pricing Analysis
Warranty and load-testing certification bundling separates premium modular rack suppliers from unbundled commodity fabricators serving rapid-reconfiguration e-commerce facilities. Three-tier pricing structure across premium, standard, and economy levels reflects UL/TÜV certification grade and after-sales service inclusion. Cost compression in standard pallet rack tiers intensifies because light-gauge cold-formed steel decentralizes fabrication toward regional roll-forming operations. Third-party logistics operators in the Netherlands and Belgium exhibit highest price sensitivity; pharmaceutical cleanroom operators in Switzerland and Germany demonstrate lowest sensitivity due to FDA-mandated specification rigidity.
Supply Chain Analysis
Skilled welder and roll-forming technician availability constrains output expansion in Germany's Ruhr Valley and China's Yangtze River Delta manufacturing clusters. Supply concentrates in Germany, China, and India, with raw material flows drawing from scrap steel recycling networks and primary aluminum smelters in Nordic hydro-powered facilities. Carbon border adjustment mechanism exposure creates structural risk for aluminum-dependent suppliers serving EU markets. Distribution runs through regional fabrication partnerships serving 200-mile radii from major logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into scrap steel recycling and captive rolling operations defines competitive positioning in this market, with players racing to secure verified Environmental Product Declarations ahead of EU Green Deal enforcement.
For Market Incumbents: Deepen captive fabrication scale in Germany and China while accelerating TÜV/UL/BSI certification parallel testing tracks to compress approval timelines. Threats from light-gauge cold-formed steel regional roll-formers erode margin pools in sub-20-foot bay height segments. Priority investment in seismic zone engineering licensing defends specification access in California and Japan markets.
For New Entrants and Emerging Players: Automation integrators represent the most penetrable channel partner type for modular racking suppliers lacking robotics capabilities. White-space targets include AGV-compatible aisle width specifications in India's Mumbai and Delhi NCR fulfillment hubs under PLI scheme incentives, and cold chain convergence with insulated modular enclosures for pharmaceutical perishable verticals. Go-to-market angle emphasizes pre-engineered demountable bay assemblies compressing installation timelines for velocity-pressured e-commerce networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional roll-forming specialists with 200-mile radius service models in Belgium and the Netherlands. Long-term viability across the analysis window hinges on carbon disclosure capabilities and domestic steel recycler relationships. Signal to watch: BIS certification acceleration in India and NMPA pharmaceutical warehousing guideline tightening in China as inflection indicators for specification intensity shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | Captive steel supply hedges hot-rolled coil volatility and secures EPD verification for EU Green Deal compliance. |
| Seismic Zone Engineering Licensing | Site-specific structural calculation capabilities unlock California and Japan building code specifications. |
| AGV-Compatible Aisle Width Pre-Engineering | Standardized bay assemblies serve India's PLI-subsidized Mumbai and Delhi NCR fulfillment hub construction. |
| Environmental Product Declaration Certification | Verified lifecycle emissions data satisfies German and French pharmaceutical tender gate criteria. |
| Cold Chain Robotics Integration | Insulated modular enclosures with automated retrieval open pharmaceutical and perishable food verticals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with warehouse operations directors, plant engineers at captive steel fabrication facilities, third-party logistics procurement leads, and automation integration specialists. OSHA, FDA, and EU Green Deal regulatory databases combined with BIS and NMPA certification records provided compliance trajectory validation. Bottom-up installation volume estimates triangulated against top-down steel consumption models across the analysis window.
Granularity-level modeling deployed product type, end user vertical, material category, and installation type as core segmentation dimensions, with additional modeling at the regional regulatory cluster level for carbon disclosure mandates. CAGRs derived from curve-fitting historical installation patterns against projected e-commerce fulfillment network expansion and automotive parts distribution center buildouts. Forecast inputs included PLI scheme incentive timelines in India and MEE dual carbon goal enforcement intensity in China.
Several conditions sit outside the modeled scope, including extreme steel price volatility scenarios beyond historical bands and seismic event frequency exceeding building code design bases. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology adoption curves. A small set of named triggers warrants ongoing watch: carbon border adjustment mechanism implementation timing, BIS certification acceleration in India, and NMPA pharmaceutical warehousing guideline revisions in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Asia Pacific Mobile Crane Market