
 Commercial Vehicle Traction Battery Systems Market | 2026-2036
Commercial Vehicle Traction Battery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Traction Battery Systems Market Insights
A capital-intensity divergence between integrated cell manufacturers and pack assemblers is reorganizing competitive tiers in commercial vehicle traction battery systems. CATL leverages captive cathode material refining and cell-to-pack architectures to dominate heavy-duty contracts. BYD sustains vertical integration through in-house semiconductor and battery production, anchoring its position in city bus and delivery truck electrification. Samsung SDI competes on high-nickel chemistry leadership, extending its reach into European long-haul OEM programs.
Commercial Vehicle Traction Battery Systems comprise electrochemical energy storage assemblies engineered to deliver sustained high-current discharge for propulsion, typically configured in series-parallel arrays with nominal voltages exceeding 400V and thermal management integrated at pack level. These systems serve the primary industrial purpose of displacing diesel combustion in freight and passenger transport applications subject to duty-cycle endurance requirements. Lithium-Ion chemistry occupies the dominant share of current procurement, though Solid-State configurations are attracting development capital for their energy density and safety profile advantages in long-haul trucking. The Fleet Vehicles application category generates concentrated order volumes from logistics operators pursuing total-cost-of-ownership reduction through centralized charging infrastructure and standardized battery specifications.
The EPA's Clean Trucks Plan and the EU's CO2 standards for heavy-duty vehicles are mandating fleet-average emissions reductions that compel OEMs to electrify model lineups. China's MIIT administers NEV production quotas and GB standards for battery safety that shape which suppliers qualify for domestic commercial vehicle platforms. NHTSA's forthcoming heavy-duty fuel economy rules will extend these pressures to North American manufacturers. Stakeholders must monitor how cell chemistry certification requirements and local content rules in battery supply chains reshape sourcing decisions and manufacturing location strategies.
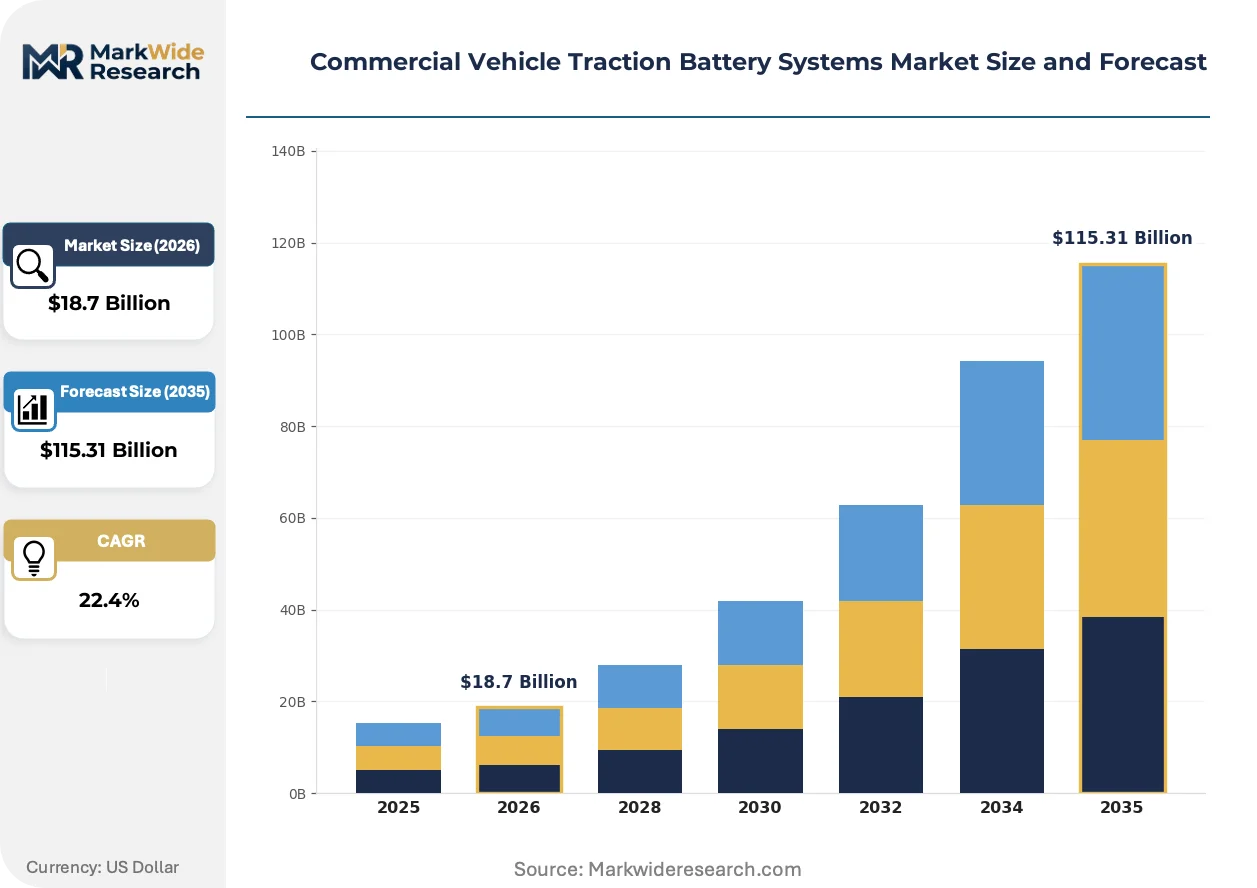
Market Dynamics
Fleet operators are consolidating battery procurement around standardized pack architectures to secure volume pricing and simplify charging infrastructure deployment across depots.
Growth Catalysts
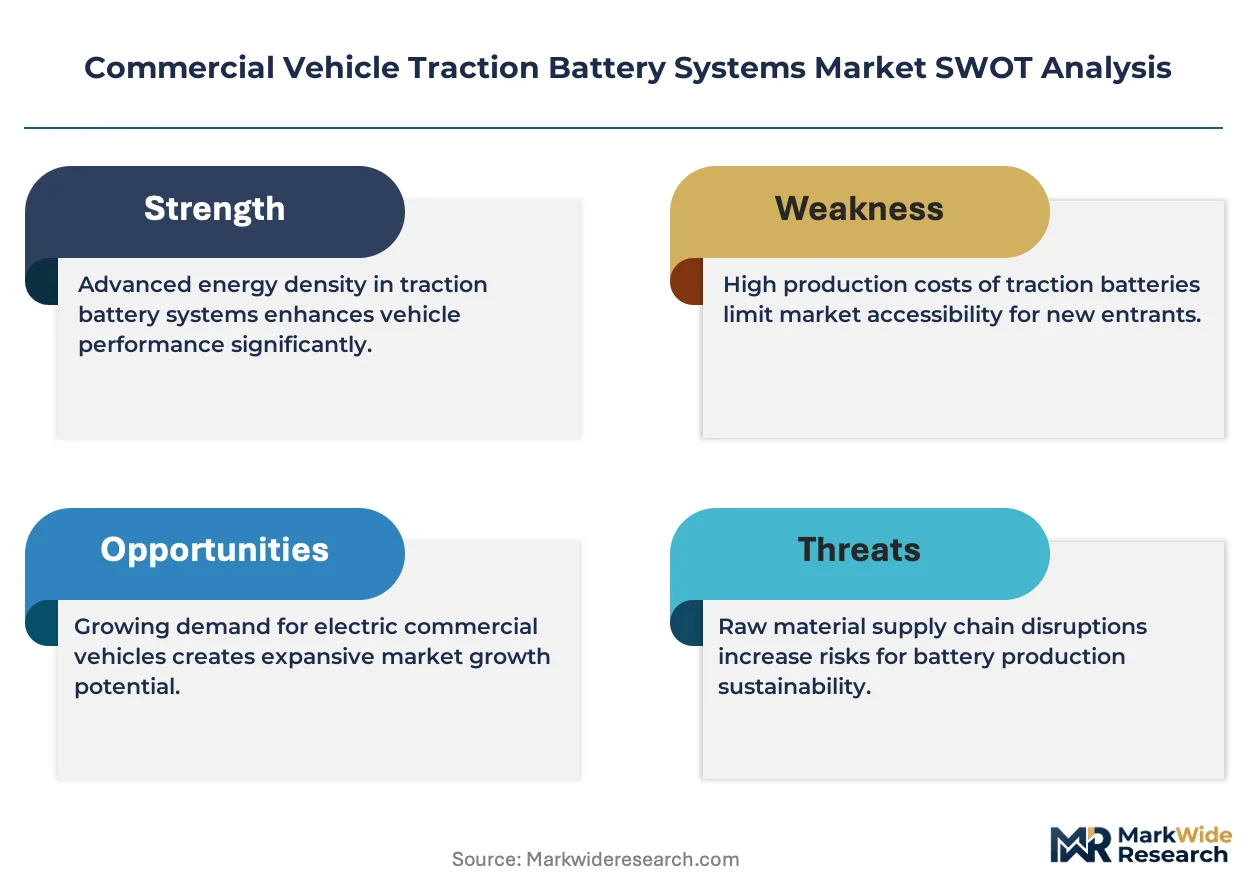
- EU CO2 standards for heavy-duty vehicles:Mandated fleet-average emissions reductions compel OEMs to electrify model lineups and source high-capacity traction systems.
- Logistics sector consolidation:Large freight operators are deploying centralized charging hubs that favor standardized battery specifications and long-term supply agreements.
- Cell-to-pack architectures:Elimination of module housings reduces system mass and assembly cost, accelerating adoption in weight-sensitive delivery applications.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress pack assembler margins and destabilize long-term contract pricing.
- Cathode precursor concentration:Refining capacity clustering in specific geographies creates supply vulnerability for non-integrated manufacturers.
- Energy density ceiling:Current lithium-ion chemistries face theoretical limits that constrain range extension for long-haul trucking without pack mass penalties.
Strategic Opportunities
- India's FAME subsidy scheme:Purchase incentives for electric buses and commercial vehicles open procurement windows for qualified battery suppliers.
- Battery-as-a-service models:Decoupling asset ownership from vehicle purchase lowers fleet operator entry barriers and generates recurring revenue streams.
- Solid-state convergence with silicon anodes:Next-generation cell architectures promise simultaneous gains in energy density and fast-charge capability.
Industry Challenges
- Thermal runaway testing protocols:Extended GB standard certification timelines delay product launches for China-bound commercial platforms.
- Pack integration with legacy vehicle architectures:Retrofit compatibility requirements fragment engineering resources and extend development cycles.
- High-voltage technician scarcity:Qualified service personnel shortages constrain after-sales network expansion and depot maintenance capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Traction Battery Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State, Sodium-Ion Application: Delivery Trucks, City Buses, Long-Haul Trucks, Construction Vehicles, Fleet Vehicles End User: Logistics Companies, Public Transit Operators, Construction Firms, Freight Carriers, Vehicle Leasing Deployment: Onboard Battery Packs, Stationary Energy Storage, Battery Swapping Stations, Portable Chargers, Fast Charging Stations |
| Companies Covered | LG Energy Solution, BYD, Panasonic, Samsung SDI, CATL, SK On, Farasis Energy, Sunwoda Electronic, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Traction Battery Systems Market Trends and Innovations
Cell chemistry evolution and pack architecture simplification are compressing cost structures while regulatory mandates accelerate fleet electrification timelines.
Lithium iron phosphate chemistry is displacing nickel-cobalt-manganese alternatives in urban delivery and bus applications where cycle life and thermal stability outweigh energy density requirements. Municipal transit authorities and last-mile operators are specifying LFP-dominant packs to reduce thermal management complexity and extend operational lifespan. This chemistry shift is displacing high-nickel cathode demand in the sub-300 km range segment and reallocating cobalt supply toward premium passenger vehicle markets.
China's MIIT-administered GB 38031 battery safety standards mandate nail penetration and overcharge testing that exceed UN 38.3 requirements. Domestic OEMs must source from certified cell suppliers, creating qualification barriers for non-Chinese manufacturers. European and North American suppliers are responding by establishing local testing facilities and joint ventures with domestic partners to access commercial vehicle production quotas.
Fleet operators are unbundling battery ownership from vehicle acquisition through leasing structures that transfer residual value risk to suppliers. Logistics companies in Germany and the United States are piloting pay-per-kilometer contracts that align battery replacement cycles with actual utilization patterns. This model is most visible in refrigerated transport where duty-cycle predictability enables accurate degradation forecasting and guaranteed uptime clauses.
Commercial Vehicle Traction Battery Systems Market Segmentation
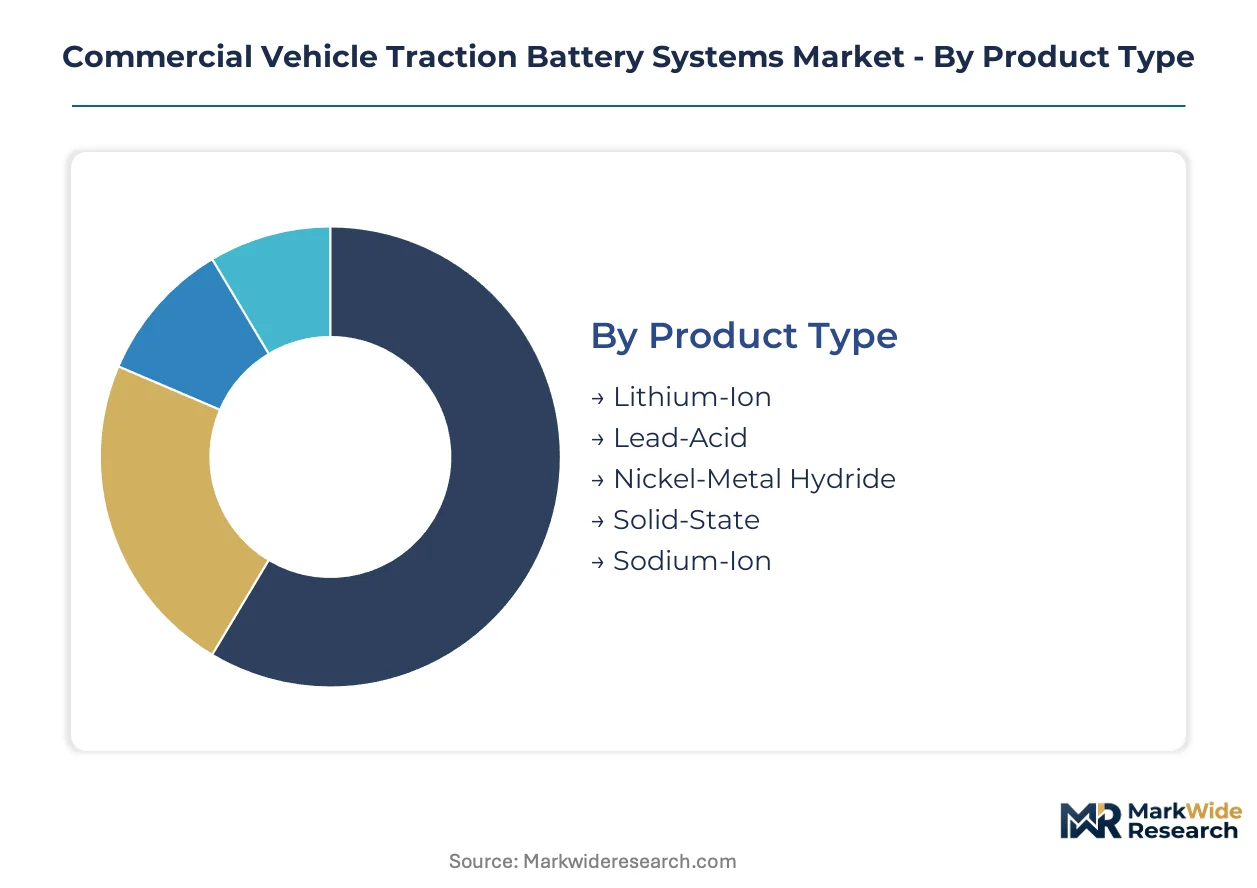
Segmentation in commercial vehicle traction battery systems reveals how chemistry selection, duty-cycle demands, and ownership models reshape procurement patterns. Fleet operators prioritize standardized specifications that align charging infrastructure with vehicle utilization profiles.
Product Type:
Lithium iron phosphate chemistry faces substitution pressure from sodium-ion alternatives in cost-sensitive urban delivery applications where energy density requirements remain modest.
- Lithium-Ion:Dominant cell chemistry configured in series-parallel arrays exceeding 400V nominal, with nickel-cobalt-manganese formulations serving long-haul routes and lithium iron phosphate variants anchoring city bus and last-mile delivery contracts in China and Germany.
- Solid-State:Next-generation electrochemical architecture employing ceramic or sulfide electrolytes eliminates flammable liquid components, attracting development capital from European OEMs targeting extended-range heavy-duty platforms where safety certification and energy density convergence justify premium positioning.
- Lead-Acid:Mature flooded and absorbed glass mat configurations retain niche presence in auxiliary power and starter applications for retrofit commercial fleets.
- Nickel-Metal Hydride:Legacy hybrid-electric chemistry persists in select transit bus retrofits where thermal management infrastructure constraints favor proven reliability profiles.
- Sodium-Ion:Emerging cell technology leveraging abundant raw materials targets sub-300 km range segments with reduced lithium dependency, piloting with Chinese logistics operators seeking supply chain decoupling.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Application:
Cost tier stratification separates premium long-haul specifications from standardized urban duty-cycle configurations where pack interchangeability drives depot efficiency.
- Fleet Vehicles:Centralized procurement of standardized pack architectures by logistics operators enables volume pricing leverage and simplified charging infrastructure deployment across multi-depot networks in the United States and Germany.
- City Buses:High-cycle-duty applications with predictable route profiles favor lithium iron phosphate chemistries and battery-as-a-service ownership models, with municipal transit authorities in China specifying GB 38031-certified systems.
- Delivery Trucks:Last-mile commercial vehicles with sub-200 km daily range requirements prioritize pack mass reduction and fast-charge capability over maximum energy density.
- Long-Haul Trucks:Extended-range freight applications face energy density constraints that delay full electrification, with pilot programs testing megawatt-hour scale packs and opportunity charging corridors.
- Construction Vehicles:Intermittent high-power demand cycles and harsh operating environments drive ruggedized thermal management requirements and modular pack architectures for equipment replacement flexibility.
City buses command the densest installation base; fleet vehicles are expanding most quickly through logistics sector consolidation.
End User:
Customer type differentiation separates asset owners seeking total-cost-of-ownership reduction from leasing intermediaries absorbing residual value risk and technology obsolescence exposure.
- Logistics Companies:Parcel and freight operators including DHL and UPS deployment programs specify standardized pack geometries to enable cross-fleet charging interoperability and centralized maintenance protocols.
- Public Transit Operators:Municipal and regional transport authorities procure through tender processes that prioritize cycle life warranties and local content requirements, particularly in China where MIIT quotas shape supplier qualification.
- Freight Carriers:Long-haul trucking fleets face payload sensitivity that constrains pack mass, delaying adoption pending solid-state or silicon-anode density improvements.
- Construction Firms:Equipment rental and operator companies favor modular battery configurations compatible with mixed-fleet electrification strategies and site-based charging infrastructure.
- Vehicle Leasing:Financial intermediaries pilot battery-as-a-service structures that decouple powertrain assets from vehicle ownership, transferring degradation risk to suppliers and aligning replacement cycles with utilization patterns.
Logistics companies anchor current procurement volume; vehicle leasing climbs the fastest as ownership models fragment.
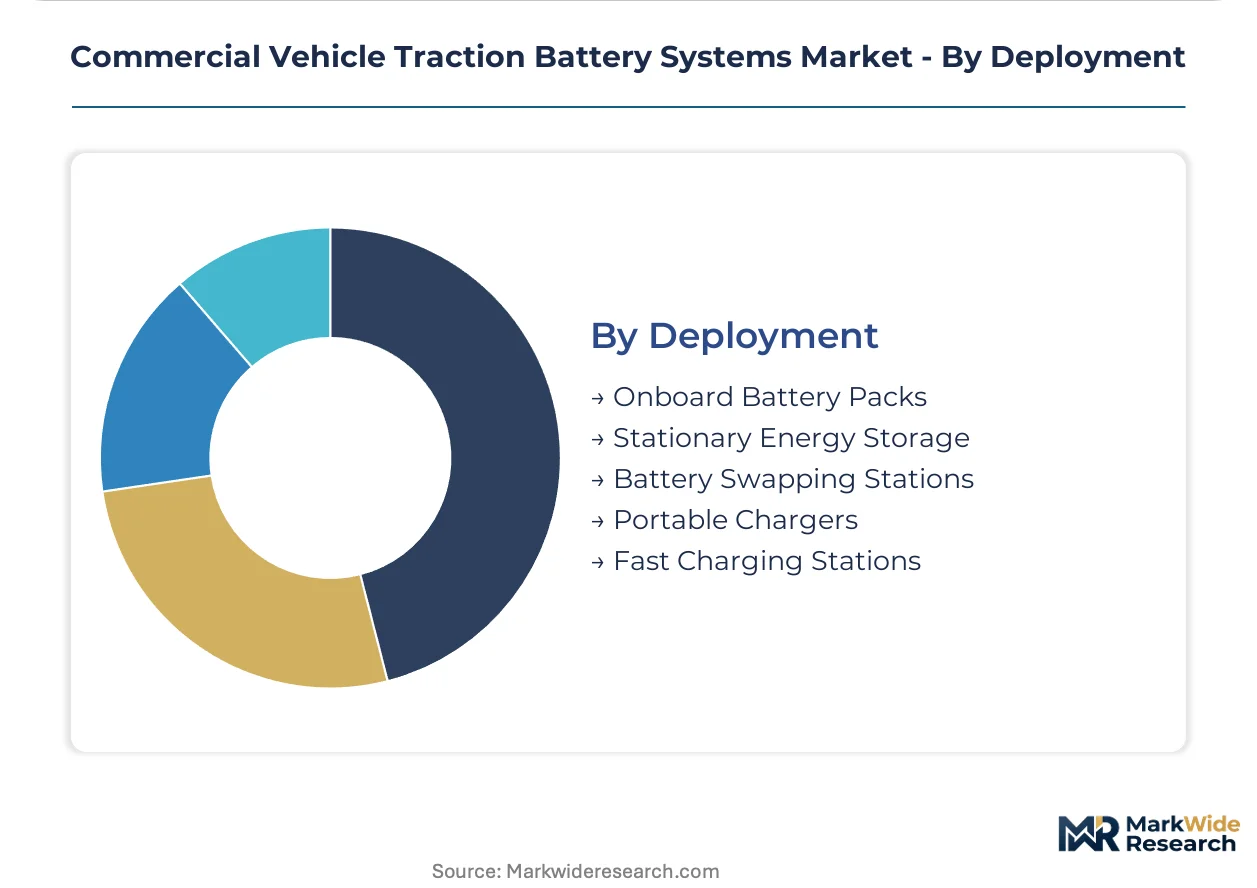
Deployment:
Supply concentration in cell manufacturing versus pack integration creates margin divergence between upstream chemistry control and downstream system assembly competencies.
- Onboard Battery Packs:Integrated vehicle-mounted energy storage systems with cell-to-pack architectures eliminating module housings, dominating OEM factory installations and retrofit programs.
- Battery Swapping Stations:Automated exchange infrastructure deployed by NIO and CATL in China enables commercial vehicle continuous operation with depleted pack replacement within minutes, particularly viable for taxi and delivery fleets with standardized geometries.
- Fast Charging Stations:Megawatt-scale depot infrastructure with liquid-cooled connectors supports opportunity charging for regional haul applications, with utilities in Germany and California managing grid impact through managed charging software.
- Stationary Energy Storage:Second-life commercial vehicle battery repurposing for grid stabilization and renewable integration extends asset value extraction.
- Portable Chargers:Mobile DC fast-charging units serve construction sites and remote logistics hubs lacking permanent infrastructure.
Onboard packs retain volume leadership; battery swapping stations gain share fastest in China-dominated deployment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Chinese cell manufacturers leveraging captive refining capacity, while European pack assemblers absorb margin compression from raw material volatility and qualification delays.
China
MIIT-administered GB 38031 certification requirements and NEV production quotas shape supplier qualification for domestic commercial vehicle platforms. The MIIT enforces battery safety standards that exceed UN 38.3 testing protocols, creating entry barriers for non-certified manufacturers. Shenzhen and Ningbo anchor cell-to-pack manufacturing clusters where CATL and BYD deploy integrated production lines for heavy-duty contracts.
Germany
Freight operators including DHL and DB Schenker consolidate procurement around standardized pack geometries for cross-fleet charging interoperability. The EU's CO2 standards for heavy-duty vehicles mandate fleet-average emissions reductions that compel OEM electrification timelines. Stuttgart and Munich host OEM engineering centers where European long-haul programs test high-nickel chemistry integration.
United States
Logistics sector consolidation drives centralized charging hub deployment favoring standardized battery specifications and long-term supply agreements. The EPA's Clean Trucks Plan mandates fleet-average emissions reductions extending pressure to North American manufacturers. California's Advanced Clean Trucks regulation accelerates procurement in the Los Angeles and San Francisco logistics corridors.
India
FAME subsidy schemes for electric buses and commercial vehicles open procurement windows for qualified battery suppliers facing cost-sensitive operator requirements. The CEA administers grid integration standards for megawatt-scale depot charging infrastructure. Tamil Nadu and Gujarat host emerging pack assembly operations serving municipal transit tenders with local content requirements.
South Korea
Battery suppliers compete on high-nickel chemistry leadership for European OEM programs seeking energy density advantages in extended-range applications. The MFDS oversees industrial safety standards while METI-aligned technology roadmaps guide R&D investment. Seoul and Ulsan concentrate cell manufacturing capacity serving export markets with certified thermal management systems.
Commercial Vehicle Traction Battery Systems Market Competitive Landscape
Concentration sits with integrated cell manufacturers controlling upstream cathode refining and module-less pack architectures. The vendor base stratifies between chemistry-integrated giants and downstream pack assemblers dependent on external cell supply. Three archetypes dominate: vertically integrated Asian cell producers, European system integrators, and Chinese specialists in cost-optimized LFP configurations. Competitive moves center on captive material sourcing and joint venture structures for regional market access.
Among the integrated chemistry leaders, CATL, BYD, and Samsung SDI occupy positions reflecting distinct strategic emphases. CATL exemplifies the captive refining archetype with cell-to-pack architectures targeting heavy-duty volume contracts. BYD represents vertical control through in-house semiconductor and battery production, anchoring city bus electrification. Samsung SDI sits within the high-nickel specialization tier, extending reach into European long-haul OEM programs demanding premium energy density specifications.
| Leading Market Players |
|---|
| LG Energy Solution |
| BYD |
| Panasonic |
| Samsung SDI |
| CATL |
| SK On |
| Farasis Energy |
| Sunwoda Electronic |
| EVE Energy |
| Others |
Pricing and Supply Chain Analysis
Sodium-ion chemistry substitution for lithium iron phosphate in sub-300 km delivery applications is redrawing raw material procurement maps while compressing pack-level pricing benchmarks across Chinese logistics networks. This chemistry pivot simultaneously loosens lithium carbonate dependency and shifts cathode precursor sourcing toward abundant sodium carbonate supply chains concentrated in Chile and the United States.
Pricing Analysis
The customization-premium spread between configured-to-order megawatt-hour packs for long-haul OEM programs and standardized LFP configurations for city bus fleets spans roughly three-to-one pricing multiples. Price differentiation separates GB 38031-certified systems commanding qualification premiums from uncertified alternatives facing market access barriers. Cost compression in standard-tier packs is intensifying because CATL and BYD are deploying captive cathode refining at scale. Municipal transit authorities exhibit highest price sensitivity due to tender-based procurement with fixed budget envelopes, while European long-haul OEMs absorb premium positioning for high-nickel energy density specifications.
Supply Chain Analysis
Cathode precursor refining capacity clustering in Indonesia and the Democratic Republic of Congo creates single-source vulnerability for non-integrated pack assemblers dependent on nickel and cobalt sulfate feedstocks. The commercial vehicle traction battery supply chain draws from lithium spodumene concentrates in Australia, graphite anodes from China, and electrolyte salts manufactured in South Korea and Japan. Distribution runs through OEM-direct contracts for factory-installed packs and tier-one system integrators serving retrofit markets. Tariff exposure on Chinese cell imports into the European Union and United States is forcing qualification investments in regional pack assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Logistics sector consolidation around DHL, UPS, and DB Schenker procurement consortiums is concentrating buyer power and forcing standardized pack geometry requirements that reshape supplier competitive dynamics.
For Market Incumbents: Compound captive refining advantages by locking long-term offtake agreements with Indonesian nickel and Chilean lithium operations before sodium-ion chemistry erodes lithium demand premiums. Defend position against emerging sodium-ion specialists by accelerating GB 38031 certification investments for next-generation solid-state platforms. Prioritize backward integration into cathode active material production to preserve margin structure against raw material volatility. For New Entrants and Emerging Players: Battery-as-a-service financing gaps in refrigerated transport and construction equipment leasing create white-space opportunities where incumbents under-serve asset-light fleet operators. Target India's FAME-subsidized municipal bus tenders with sodium-ion pilot programs leveraging local content requirements and supply chain decoupling narratives. Pursue joint venture structures with established cell manufacturers to bypass GB 38031 qualification timelines and access China-bound commercial vehicle production quotas. For Investors and Strategic Acquirers: The market sits at a chemistry-transition phase that favors upstream material control over downstream pack assembly scale. Long-term viability over the next decade rests on securing positions in cathode precursor refining and solid-state electrolyte development rather than commodity pack integration. Acquisition targets should display captive mining offtake or ceramic electrolyte IP portfolios. Monitor sodium-ion pilot deployment metrics with Chinese logistics operators as the critical inflection signal for lithium demand displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Deployment | Elimination of module housings reduces system mass and assembly cost for weight-sensitive delivery applications. |
| GB 38031 Certification Investment | MIIT-administered safety standards create qualification barriers that filter non-certified manufacturers from China-bound contracts. |
| Cathode Precursor Backward Integration | Captive refining capacity in Indonesia and Chile insulates margins from nickel and lithium carbonate spot price volatility. |
| Battery-as-a-Service Model Launch | Pay-per-kilometer contracts align replacement cycles with utilization patterns and transfer residual value risk to suppliers. |
| Solid-State Electrolyte R&D Partnership | Ceramic and sulfide electrolyte development attracts European OEM capital targeting extended-range heavy-duty platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, OEM platform engineers, cell manufacturing executives, and thermal management specialists; and secondary validation through MIIT GB standard filings, EPA Clean Trucks Plan regulatory dockets, EU heavy-duty CO2 compliance databases, and customs trade records for lithium carbonate and cathode precursor flows. Bottom-up cell shipment estimates by chemistry and application were triangulated against top-down OEM electrification timeline disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions including cell chemistry, vehicle application duty cycle, ownership model structure, and regional regulatory cluster. CAGRs were derived from installed base growth rates, replacement cycle assumptions, and chemistry substitution curves. Key inputs included fleet operator electrification capex plans, charging infrastructure deployment pipelines, and solid-state technology readiness assessments.
Underlying assumptions cover lithium carbonate price stabilization, GB 38031 certification timeline continuity, and EU CO2 standard enforcement rigor, with deviation risk concentrated in sodium-ion chemistry scale-up velocity and trade policy shifts affecting Chinese cell import tariffs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Scooter Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Electric Vehicle Power Control Unit Market